
 Vasculitis Market | 2026-2036
Vasculitis Market Size, Share, and Industry Trends Forecast 2026-2036
Vasculitis Market Outlook
Biologics-grade manufacturing standards are redrawing competitive boundaries in autoimmune therapeutics. F. Hoffmann-La Roche Ltd anchors its position through monoclonal antibody production scale and rare-disease commercial infrastructure. Bristol-Myers Squibb Company differentiates via immunology R&D intensity and established relationships with rheumatology centers. AbbVie Inc. leverages its immunology franchise to extend pipeline assets into anti-neutrophil cytoplasmic antibody-associated indications.
Vasculitis comprises a heterogeneous group of disorders characterized by inflammatory destruction of blood vessel walls, with classification depending on vessel size and histopathologic patterns such as leukocytoclastic infiltration or granulomatous inflammation. These conditions demand immunomodulatory intervention to prevent end-organ ischemia, hemorrhage, and irreversible tissue necrosis. Among product types, biologics command the fastest expansion as targeted B-cell and interleukin-6 pathway inhibitors displace chronic corticosteroid dependence. The treatment approach dimension shows combination therapy capturing dominant clinical share, though monotherapy biologics gain ground where precision diagnostics enable patient stratification.
The FDA accelerates rare disease biologic reviews through breakthrough therapy and orphan drug designations, while the EMA's centralized procedure shapes parallel European access timelines. Japan's PMDA maintains distinct immunogenicity testing requirements that influence regional development programs. Stakeholders must monitor how evolving biomarker-defined patient subsets reshape trial design and payer evidence requirements for conditional reimbursement.
Market Dynamics
The transition from chronic corticosteroid dependence to biologic-targeted therapy is restructuring prescribing patterns and reimbursement negotiations across autoimmune vasculitis care pathways.
Growth Catalysts
- Orphan drug incentives:The FDA's breakthrough therapy designation compresses development timelines for rare disease biologics, accelerating patient access to B-cell and interleukin-6 pathway inhibitors.
- Hospital infusion center expansion:Tertiary referral networks in the United States are scaling biologic administration infrastructure, creating dedicated autoimmune therapy units with specialized nursing protocols.
- Precision diagnostics:ANCA testing and histopathologic stratification tools enable patient subset identification, supporting targeted therapy selection and payer justification for biologic coverage.
Market Restraints
- Biologics manufacturing concentration:Contract development and manufacturing organizations in Switzerland and Ireland control critical monoclonal antibody production capacity, creating supply vulnerability for emerging entrants.
- Reimbursement heterogeneity:Germany's G-BA assessment procedures impose divergent evidence requirements versus French HAS evaluations, fragmenting commercialization economics across European markets.
- Corticosteroid substitution persistence:Generic prednisone and methylprednisolone remain first-line in resource-constrained settings, limiting biologic penetration where diagnostic infrastructure is underdeveloped.
Strategic Opportunities
- Japan's immunogenicity pathway:PMDA's distinct testing requirements for anti-drug antibody monitoring create first-mover advantage for sponsors with established Japanese regulatory relationships.
- Subcutaneous formulation development:Self-administration platforms are converging with wearable injection devices, potentially shifting administration from hospital-based infusion to home care settings.
- Real-world evidence mandates:EMA's post-authorization study requirements for conditional approvals create structured entry points for registry-based comparative effectiveness research.
Industry Challenges
- Rheumatology-immunology talent scarcity:Fellowship-trained vasculitis specialists concentrate in academic medical centers, limiting site availability for multi-center trials and commercial education.
- Legacy EHR integration:Biologic therapy monitoring requires interoperable adverse event reporting across hospital systems with fragmented data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vasculitis Market |
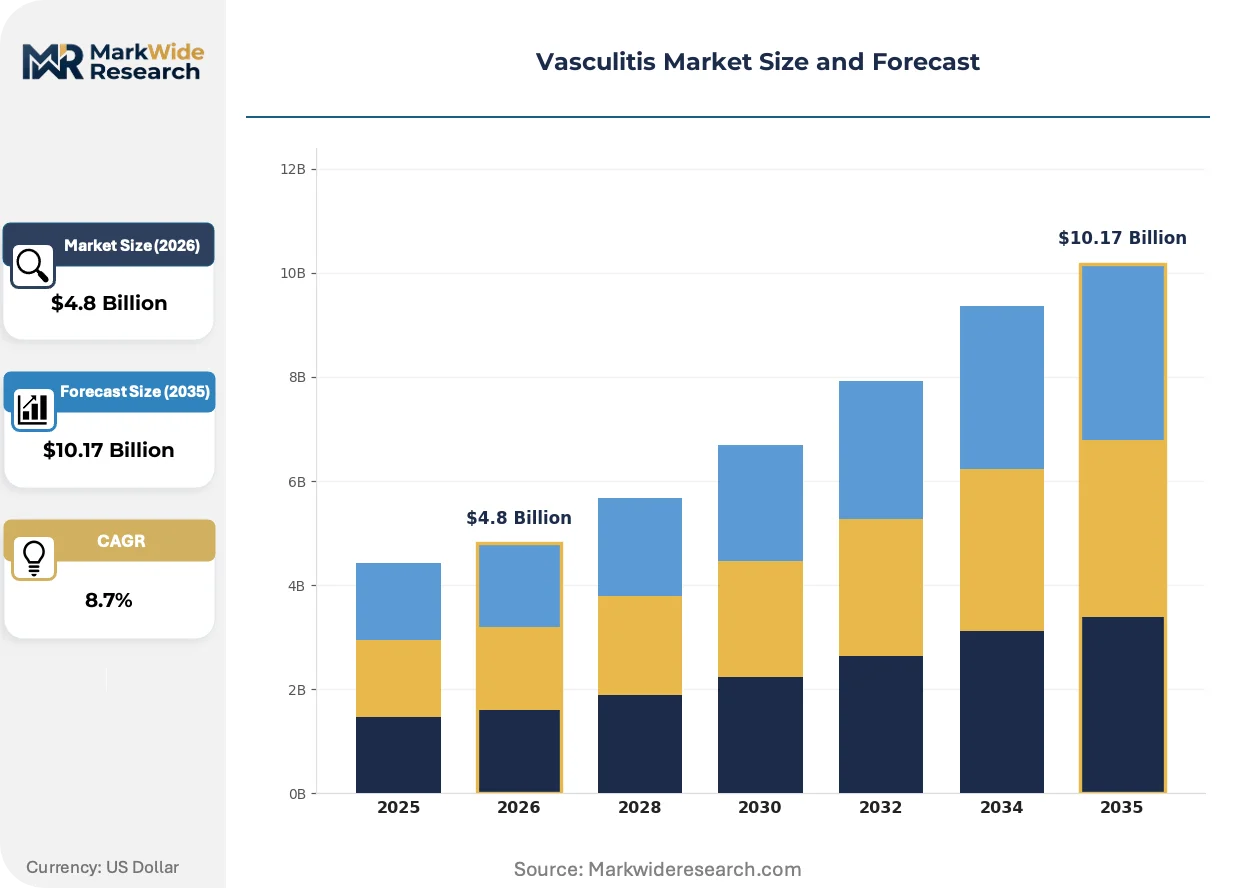
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Plasma Exchange End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Indication: Granulomatosis with Polyangiitis, Takayasu Arteritis, Polyarteritis Nodosa, Eosinophilic Granulomatosis Treatment Approach: Biological Therapy, Combination Therapy, Monotherapy, Supportive Care |
| Companies Covered | F. Hoffmann-La Roche Ltd, GSK, Pfizer Inc., Novartis AG, Bristol-Myers Squibb Company, AbbVie Inc., Amgen Inc., AstraZeneca plc, Amneal Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vasculitis Market Strategic Shifts
Biomarker-defined patient stratification is collapsing the traditional one-size-fits-all treatment paradigm, forcing adaptation across clinical trial design, regulatory submission strategies, and payer contracting approaches.
Companion diagnostic development is fragmenting the vasculitis therapeutic landscape into addressable molecular subtypes. Pharmaceutical sponsors now co-develop ANCA specificity assays alongside biologic candidates, enabling enrichment strategies in phase II trials. This convergence of diagnostic and therapeutic development is compressing the addressable patient pool per indication while improving response rates and payer value demonstration.
REACH authorization procedures for novel biologic substances are tightening environmental risk assessment requirements for monoclonal antibody manufacturing effluent. European contract manufacturers must now document biodegradation profiles and aquatic toxicity data prior to commercial scale-up. Small and mid-size biotech sponsors without established ECHA compliance infrastructure are outsourcing environmental dossier preparation to specialized regulatory consultancies.
Hospital procurement committees are consolidating biologic purchasing through centralized pharmacy and therapeutics boards, displacing individual prescriber autonomy in product selection. Account managers now engage pharmacy directors and value analysis committees rather than rheumatology department chairs. This concentration is most pronounced in United States integrated delivery networks, where formulary placement decisions increasingly hinge on total cost of care models and risk-sharing arrangements.
Vasculitis Market Segmentation
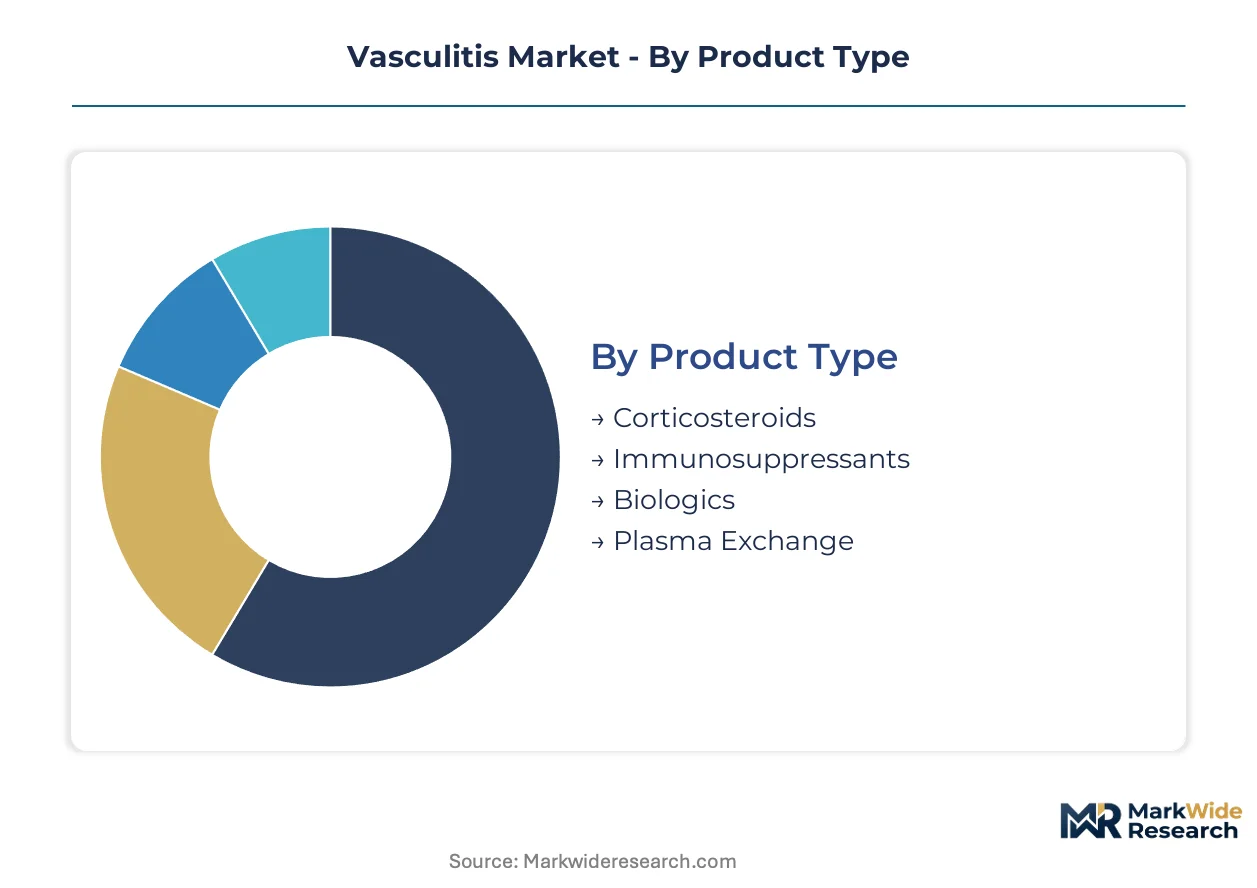
Vasculitis therapeutics fragment across multiple dimensions that reshape channel economics and patient access pathways. Treatment modality, care setting, and disease subtype each impose distinct manufacturing, distribution, and reimbursement requirements on market participants.
Product Type:
Hospital infusion centers and specialty pharmacies split procurement volumes differently across these therapeutic classes, with biologics concentrating in tertiary referral networks while corticosteroids flow through broad wholesale channels.
- Biologics:Monoclonal antibodies targeting B-cell and interleukin-6 pathways require cold-chain distribution and specialized nursing administration. United States academic medical centers capture the dominant share of rituximab and tocilizumab infusions, driven by FDA breakthrough therapy designations that accelerate hospital formulary adoption.
- Corticosteroids:Generic prednisone and methylprednisolone remain the volume foundation of first-line induction therapy. These agents distribute through standard pharmaceutical wholesale networks into community hospitals and outpatient clinics where cost constraints limit biologic penetration.
- Immunosuppressants:Cyclophosphamide and azathioprine bridge acute induction and maintenance phases, flowing through both hospital oncology pharmacies and retail specialty distributors.
- Plasma Exchange:Apheresis services concentrate in regional reference laboratories and major medical centers with dedicated extracorporeal therapy units.
By volume, corticosteroids lead. By growth pace, biologics are expanding most quickly.
End User:
Site-of-care economics and reimbursement intensity stratify demand concentration across these settings, with higher-complexity biologic administration concentrating where payer contracts and specialist density align.
- Hospitals:Tertiary centers with dedicated rheumatology-immunology divisions capture complex vasculitis cases requiring infusion suite monitoring and multidisciplinary coordination. These institutions negotiate directly with manufacturers for biologic purchasing contracts.
- Clinics:Community rheumatology practices and outpatient infusion centers handle stable maintenance patients and corticosteroid tapers, operating on distinct reimbursement schedules from hospital outpatient departments.
- Homecare:Subcutaneous biologic formulations and oral immunosuppressant maintenance shift into home settings where nursing support and remote monitoring infrastructure determine feasibility.
- Long-term Care Facilities:Skilled nursing facilities manage elderly vasculitis patients with comorbid limitations, though biologic administration remains rare due to staffing and liability constraints.
Hospital systems command the revenue concentration. Homecare channels show the steepest expansion trajectory as self-administration platforms mature.
Indication:
Disease prevalence and severity gradients reshape addressable patient pools, with ANCA-associated subtypes driving biologic trial enrollment and commercial investment.
- Granulomatosis with Polyangiitis:The most common ANCA-associated small-vessel vasculitis subtype, characterized by necrotizing granulomatous inflammation of the upper and lower respiratory tract plus glomerulonephritis. United States tertiary centers generate concentrated demand for B-cell depleting therapy.
- Takayasu Arteritis:Large-vessel inflammation affecting the aorta and major branches, predominantly in younger female patients. Japanese and Korean academic hospitals maintain specialized vascular surgery-rheumatology collaboration models for this indication.
- Polyarteritis Nodosa:Medium-vessel necrotizing vasculitis with hepatitis B association in specific geographic clusters, requiring antiviral-immunosuppressant combination protocols.
- Eosinophilic Granulomatosis:Asthma-driven small-vessel disease with eosinophilic tissue infiltration, representing a target population for anti-interleukin-5 pathway expansion from severe asthma indications.
Granulomatosis with Polyangiitis dominates current biologic prescribing. Eosinophilic Granulomatosis is gaining share fastest as asthma-biologic cross-pollination accelerates.
Treatment Approach:
Prescribing patterns shift between these modalities based on disease severity stratification, biomarker availability, and payer prior authorization requirements.
- Combination Therapy:Corticosteroid plus immunosuppressant or biologic regimens remain standard for induction of remission in severe organ-threatening presentations. United States integrated delivery networks negotiate bundled payment arrangements for these complex protocols.
- Biological Therapy:Targeted B-cell and cytokine pathway inhibitors displace chronic corticosteroid exposure where ANCA specificity and disease activity indices support precision selection.
- Monotherapy:Single-agent biologic maintenance after induction response reduces cumulative immunosuppression burden, contingent on biomarker-defined relapse risk stratification.
- Supportive Care:Anticoagulation, antihypertensive management, and infection prophylaxis accompany all active immunomodulatory approaches.
Combination Therapy retains the patient volume lead. Biological Therapy is climbing the fastest as diagnostic precision improves and corticosteroid-sparing mandates strengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in biologics and immunosuppressants shape regional market balances, with specialized manufacturing concentrated in established pharmaceutical clusters and demand gravitating toward tertiary care networks in high-income economies.
United States
Tertiary referral networks in Boston, New York, and the Research Triangle drive concentrated demand for rituximab and tocilizumab regimens. FDA breakthrough therapy designations compress commercialization timelines for rare disease biologics. The Mayo Clinic Rochester and Cleveland Clinic anchor specialized vasculitis centers with dedicated infusion infrastructure.
Germany
Academic medical centers in Berlin and Munich maintain high diagnostic throughput for ANCA-associated subtypes. G-BA assessment procedures impose stringent evidence requirements for biologic reimbursement, fragmenting access compared to neighboring markets. The country's contract manufacturing base supplies critical monoclonal antibody capacity to European sponsors.
Japan
PMDA immunogenicity testing requirements create distinct regulatory pathways for anti-drug antibody monitoring. Tokyo and Osaka academic hospitals specialize in Takayasu arteritis management through vascular surgery-rheumatology collaboration. Domestic biologic development programs prioritize subcutaneous formulation platforms for home administration.
Switzerland
Basel and Zurich host concentrated biologics manufacturing infrastructure serving global supply chains. Swissmedic maintains streamlined rare disease authorization procedures that attract sponsor headquarters relocations. The country's CDMO sector controls critical fill-finish capacity for monoclonal antibody therapies.
United Kingdom
London and Manchester tertiary centers generate demand for precision diagnostics supporting biologic patient stratification. NICE technology appraisals determine conditional reimbursement for corticosteroid-sparing therapies. The country's research hospitals participate in multinational vasculitis registries generating real-world evidence.
Vasculitis Market Competitive Environment
Listed pharmaceutical leaders compete with private specialists across manufacturing scale and rare-disease commercial infrastructure. The market structure concentrates around integrated biologics manufacturers with established immunology franchises. Three archetypes dominate: diversified biopharma conglomerates with monoclonal antibody platforms, mid-cap immunology specialists with rheumatology center relationships, and emerging biotechs with subcutaneous formulation pipelines. Competitive moves center on regulatory exclusivity extensions through orphan drug designations and backward integration into biologics manufacturing capacity.
Within the diversified biopharma tier, F. Hoffmann-La Roche Ltd and Novartis AG exemplify scale-driven positioning anchored by monoclonal antibody production infrastructure. Bristol-Myers Squibb Company occupies a specialist position representing immunology R&D intensity and established rheumatology center networks. AbbVie Inc. sits within the immunology franchise extension archetype, leveraging existing assets across anti-neutrophil cytoplasmic antibody-associated indications.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| GSK |
| Pfizer Inc. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Amgen Inc. |
| AstraZeneca plc |
| Amneal Pharmaceuticals, Inc. |
| Others |
Value Chain & Pricing Dynamics
Biologic substitution for chronic corticosteroid regimens is redrawing procurement geography and reimbursement economics across autoimmune vasculitis care pathways. This therapeutic transition concentrates purchasing power within United States hospital pharmacy and therapeutics boards while fragmenting price negotiation leverage across European national health technology assessment bodies.
Pricing Analysis
Hospital pharmacy and therapeutics boards anchor pricing power in this market through consolidated biologic purchasing contracts. Three-tier pricing structure across originator biologics, biosimilars, and generic corticosteroids stratifies by regulatory exclusivity status and manufacturing complexity. Cost compression in the biosimilar tier is intensifying as FDA interchangeable designations expand, though originator brands retain formulary preference where hospital infusion center relationships embed switching costs. Community rheumatology clinics exhibit highest price sensitivity due to thin reimbursement margins, while academic medical centers leverage patient volume for risk-sharing arrangements.
Supply Chain Analysis
Just-in-time inventory management dominates biologic distribution given cold-chain requirements and limited shelf stability, though strategic stockpiling of corticosteroid APIs persists among generic manufacturers. Monoclonal antibody production concentrates in Switzerland, Ireland, and the United States, with fill-finish capacity anchored in Basel and Zurich manufacturing clusters. Supply chain risk hinges on single-source vulnerability for B-cell depleting therapies where CDMO qualification timelines extend regulatory submission windows. Distribution runs through specialty pharmacy networks for hospital outpatient departments and direct-to-site cold chain logistics for academic infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation for rare disease biologics has compressed development timelines below traditional autoimmune benchmarks, creating a high-growth disruption window for participants with established regulatory infrastructure.
For Market Incumbents: Consolidate manufacturing scale advantages through captive fill-finish capacity additions in Switzerland and Ireland, insulating against CDMO queue congestion that threatens launch timing for pipeline assets. Deepen hospital pharmacy relationships through real-world evidence generation partnerships that support formulary defense against biosimilar entrants. For New Entrants and Emerging Players: FDA orphan drug fast-track pathways offer accelerated review timelines for ANCA-associated subtypes where diagnostic infrastructure enables enriched trial design. Target eosinophilic granulomatosis as the most penetrable indication given asthma-biologic prescriber familiarity and existing interleukin-5 pathway infrastructure. Pursue subcutaneous formulation development as the primary go-to-market angle, shifting administration from hospital infusion to home care settings where nursing support requirements lower competitive barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap immunology specialists possessing rheumatology center relationships but lacking biologics manufacturing scale. Long-term viability over the five-to-ten year horizon rests on backward integration into monoclonal antibody production capacity. Watch PMDA immunogenicity guidance evolution as the signal indicating whether Japanese regulatory relationships will confer sustainable competitive moats or become commoditized through harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA breakthrough therapy status compresses commercialization timelines for rare disease biologics. |
| Subcutaneous Formulation Development | Self-administration platforms shift site-of-care economics from hospital infusion to home settings. |
| Real-World Evidence Generation | EMA post-authorization study requirements create structured entry points for registry-based research. |
| CDMO Backward Integration | In-house monoclonal antibody production reduces supply vulnerability for launch-critical biologics. |
| Companion Diagnostic Co-Development | ANCA specificity assays enable patient enrichment strategies in phase II trials. |
Study Parameters
Desk research of FDA breakthrough therapy designations, EMA centralized procedure filings, and ClinicalTrials.gov protocols preceded structured interviews with drug development executives, regulatory affairs leads, hospital pharmacy directors, and payer access specialists. Secondary validation drew from formulary databases, SEC 10-K immunology franchise disclosures, and G-BA assessment documentation. Bottom-up patient-flow modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Variance decomposition across the projection horizon isolates contribution from biologic penetration rates, corticosteroid-sparing protocol adoption, and regional reimbursement policy shifts. Segmentation dimensions span treatment modality, care setting, disease subtype, and administration route. CAGRs derive from log-linear trend fitting with regulatory event adjustments. Forecast inputs incorporate ANCA testing volume trajectories and hospital infusion center capacity expansion plans.
Decision-makers should treat outputs as directional under stable FDA accelerated approval policy and continued orphan drug incentive continuity; material deviation in breakthrough therapy designation criteria or G-BA evidence requirements would warrant model refresh. Practitioners should keep alternative scenarios live as PMDA immunogenicity guidance and EMA environmental risk assessment procedures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Global Statin Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Stable Angina Management Market