
 Restrictive Cardiomyopathy Treatment Market | 2026-2036
Restrictive Cardiomyopathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Restrictive Cardiomyopathy Treatment Market Analytics
Specialized orphan-drug designation tiers is bifurcating competitive positioning in restrictive cardiomyopathy therapeutics. Pfizer Inc. leverages its established cardiovascular portfolio to sustain clinical trial momentum across multiple mechanism classes. Novartis AG anchors its presence through deep expertise in heart failure pathways and regenerative medicine platforms. AstraZeneca plc differentiates via targeted biologics development and strategic positioning within rare disease ecosystems.
Restrictive cardiomyopathy treatment encompasses pharmacological interventions, implantable devices, surgical procedures, and diagnostic modalities designed to address myocardial stiffness and impaired ventricular filling without chamber dilation. Therapeutic approaches target diastolic dysfunction through calcium channel modulation, neurohormonal blockade, and mechanical circulatory support, with endomyocardial biopsy serving as a definitive diagnostic standard. Medications occupy the largest current revenue pool given chronic administration requirements, while implantable devices capture expanding share as leadless pacing and advanced hemodynamic monitoring technologies mature. Hospitals remain the dominant end-user channel due to procedural complexity, though outpatient clinics are gaining traction for stable patient monitoring and medication management.
The FDA's orphan drug incentives and breakthrough therapy designations directly shape development economics and commercial prioritization for developers targeting this indication. EMA's parallel scientific advice pathways and Japan's PMDA sakigake designation system create comparable acceleration mechanisms across major regulated markets. Stakeholders must monitor evolving payer evidence requirements for gene and cell therapies, as reimbursement uncertainty for one-time interventions will determine capital allocation across the development pipeline.
Market Dynamics
The FDA's accelerated approval pathways for orphan cardiovascular indications are compressing development timelines and redirecting capital toward mechanism-diverse therapeutic pipelines in restrictive cardiomyopathy. Hospital-based cardiac care units in the United States, Germany, and Japan are expanding procurement of advanced hemodynamic monitoring and leadless pacing systems.
Growth Catalysts
- Orphan drug incentives:The FDA's orphan drug designation and breakthrough therapy pathways reduce regulatory burden and extend market exclusivity, attracting venture funding toward novel mechanism classes.
- Specialized center clustering:Concentrated demand in Cleveland Clinic, Heidelberg University Hospital, and Tokyo Medical University Hospital creates referral economies that sustain high-complexity procedure volumes.
- Leadless pacing maturation:Transcatheter delivery systems eliminate lead-related complications, expanding implantable device candidacy to patients previously excluded from conventional pacemaker therapy.
Market Restraints
- Reimbursement uncertainty for gene therapies:One-time curative interventions face payer resistance due to budget-impact modeling that conflicts with traditional chronic medication paradigms.
- Diagnostic complexity:Endomyocardial biopsy requirements and advanced cardiac MRI interpretation shortages create bottlenecks at non-specialized institutions, delaying treatment initiation.
- Supply concentration in contrast media:Reliance on iodinated contrast for hemodynamic assessment exposes catheterization labs to periodic shortage events and price volatility.
Strategic Opportunities
- Outpatient clinic expansion:Stable patient monitoring and oral medication management are migrating to ambulatory settings, creating channel diversification beyond hospital-based care.
- Japan's PMDA sakigake designation:Priority review pathways for regenerative medicine products accelerate commercial timelines for cell therapy developers targeting diastolic dysfunction.
- Biomarker-guided patient stratification:Integration of circulating cardiac troponin and natriuretic peptide panels with imaging data enables precision enrollment in mechanism-specific trials.
Industry Challenges
- Advanced heart failure specialist scarcity:Restrictive cardiomyopathy expertise concentrates at tertiary centers, limiting patient access in community hospital systems and extending wait times for definitive diagnosis.
- Legacy EHR integration friction:Hemodynamic monitoring data streams require custom interface development with existing electronic health record architectures, complicating device procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restrictive Cardiomyopathy Treatment Market |
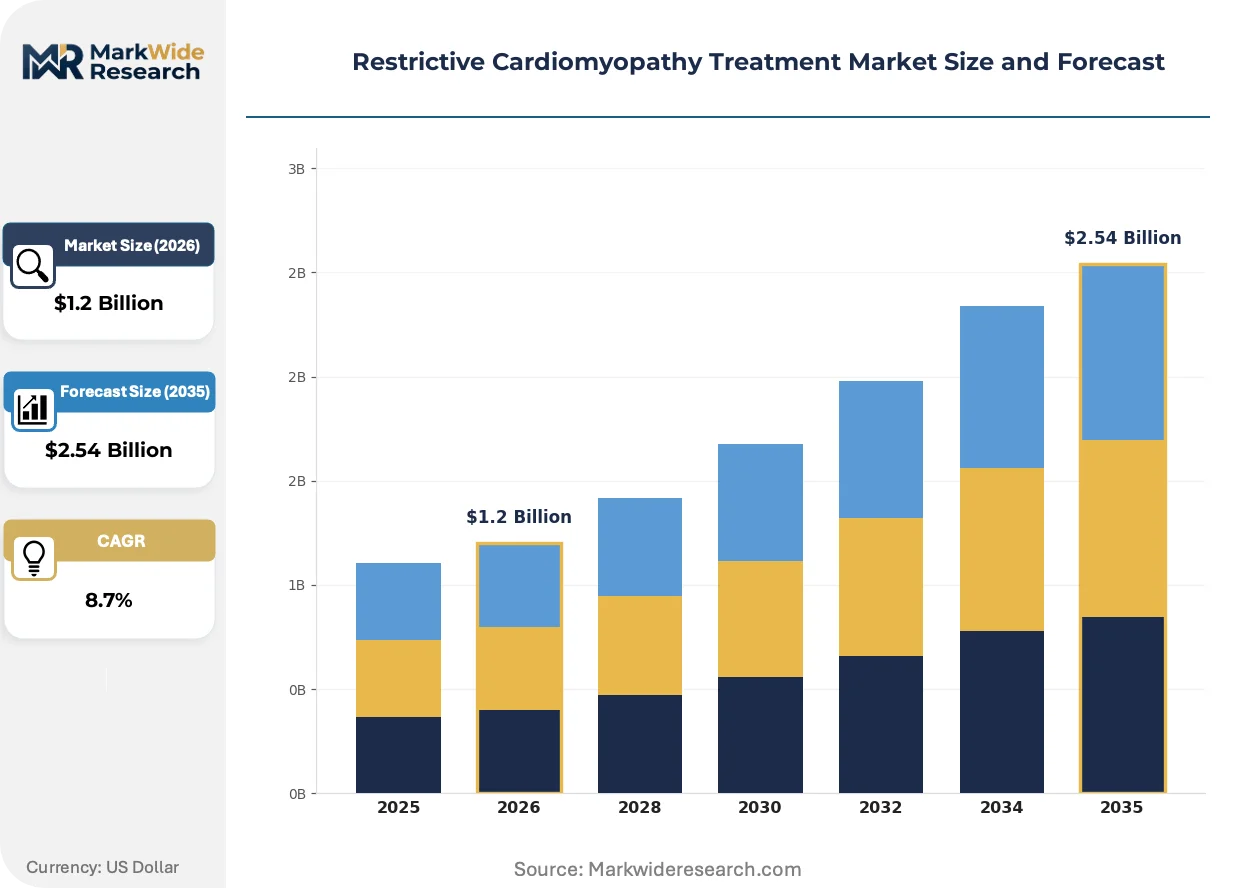
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Devices, Surgery, Diagnostic Tools Delivery Mode: Oral, Intravenous, Inhalation, Implantable End User: Hospitals, Outpatient Clinics, Home Care, Rehabilitation Centers Application: Management, Diagnosis, Monitoring, Treatment |
| Companies Covered | Pfizer Inc., Novartis AG, AstraZeneca plc, Sanofi, Merck & Co. Inc., Johnson & Johnson, Bristol-Myers Squibb, GlaxoSmithKline plc, Vericel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restrictive Cardiomyopathy Treatment Market Evolving Landscape
Mechanical circulatory support technologies are converging with implantable diagnostics to create closed-loop therapeutic systems that respond to real-time hemodynamic deterioration. These integrated platforms promise to reduce acute decompensation events that currently drive hospitalization burden.
Implantable pulmonary artery pressure sensors are supplanting intermittent catheterization for hemodynamic surveillance in advanced heart failure. Specialized cardiomyopathy centers in the United States and Germany are adopting these devices at accelerating pace for restrictive physiology patients. The technology is compressing the diagnostic-therapeutic loop from days to minutes, enabling preemptive medication titration before clinical decompensation.
The EMA's parallel scientific advice pathways are synchronizing development strategies across European member states, reducing redundant regulatory submissions for orphan cardiovascular indications. This framework compresses time-to-market for therapies securing EMA rapporteur engagement early in Phase II. Developers targeting restrictive cardiomyopathy are prioritizing parallel FDA-EMA consultation to align pivotal trial designs across both jurisdictions.
Hospital procurement committees are unbundling device acquisition from long-term service contracts, shifting vendor relationships toward component-level competition. This purchasing pattern disrupts traditional single-source dependencies and pressures manufacturers to demonstrate discrete value for monitoring hardware, implantable leads, and data analytics platforms separately. The United States exhibits the most pronounced unbundling behavior, with integrated delivery networks leading contract restructuring.
Restrictive Cardiomyopathy Treatment Market Segmentation
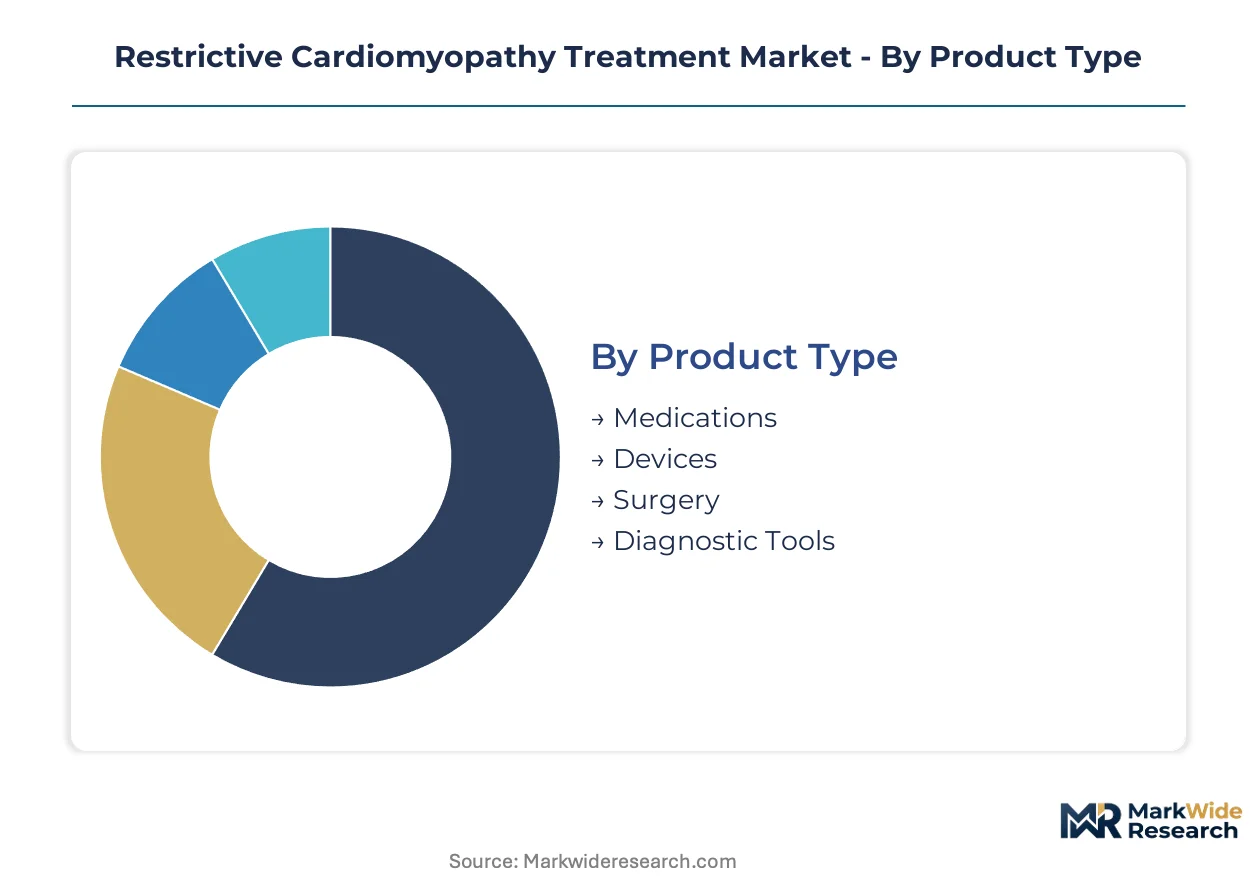
Segmentation in restrictive cardiomyopathy therapeutics reveals divergent regulatory pathways and procurement economics across intervention types. Treatment complexity and reimbursement granularity vary sharply between chronic pharmacological management and acute procedural interventions.
Product Type:
FDA orphan drug designation tiers and EMA parallel scientific advice pathways create divergent development economics across product categories in this market.
- Medications:Chronic oral and intravenous pharmaceutical regimens targeting diastolic dysfunction through calcium channel modulation and neurohormonal blockade. Demand concentrates in hospital-based cardiac care units in the United States and Germany, where Cleveland Clinic and Heidelberg University Hospital sustain high-volume prescription throughput for stable patients.
- Devices:Implantable hemodynamic monitors, leadless pacemakers, and pulmonary artery pressure sensors enabling real-time therapeutic adjustment. Japan's PMDA sakigake designation accelerates commercial timelines for regenerative medicine-integrated device platforms targeting diastolic dysfunction.
- Surgery:Endomyocardial biopsy procedures and mechanical circulatory support implantation requiring specialized surgical infrastructure.
- Diagnostic Tools:Advanced cardiac MRI protocols and catheterization laboratory equipment for definitive restrictive physiology confirmation.
Medications handle the majority of throughput; Devices are expanding most quickly on share as leadless pacing and hemodynamic monitoring technologies mature.
Delivery Mode:
Cost tier differentiation separates acute intervention economics from chronic maintenance paradigms across delivery modalities.
- Oral:First-line calcium channel blockers and neurohormonal antagonists for stable outpatient management. Outpatient clinics in the United States are gaining traction for oral medication titration and stable patient monitoring, reducing hospital-based care burden.
- Intravenous:Acute decompensation interventions and inpatient loading doses requiring infusion infrastructure.
- Inhalation:Pulmonary hypertension-targeted therapies addressing right heart failure secondary to restrictive physiology.
- Implantable:Transcatheter delivery systems for leadless pacing and pressure monitoring eliminating lead-related complications.
Oral administration handles the majority of throughput; Implantable delivery is climbing the fastest as catheterization lab capabilities expand.
End User:
Customer type fragmentation reflects the concentration of specialized expertise at tertiary centers versus ambulatory migration for stable disease management.
- Hospitals:Tertiary cardiac centers performing endomyocardial biopsy, device implantation, and acute decompensation management. Tokyo Medical University Hospital and Cleveland Clinic anchor referral economies that sustain high-complexity procedure volumes.
- Outpatient Clinics:Ambulatory settings managing stable medication regimens and non-invasive monitoring. Clinic-based care is migrating from hospital systems in Germany and the United States as remote hemodynamic monitoring matures.
- Home Care:Remote patient monitoring and caregiver-administered oral therapies for advanced disease palliation.
- Rehabilitation Centers:Post-acute functional recovery programs following device implantation or surgical intervention.
Hospitals handle the majority of throughput; Outpatient Clinics are gaining share fastest as monitoring technologies enable ambulatory migration.
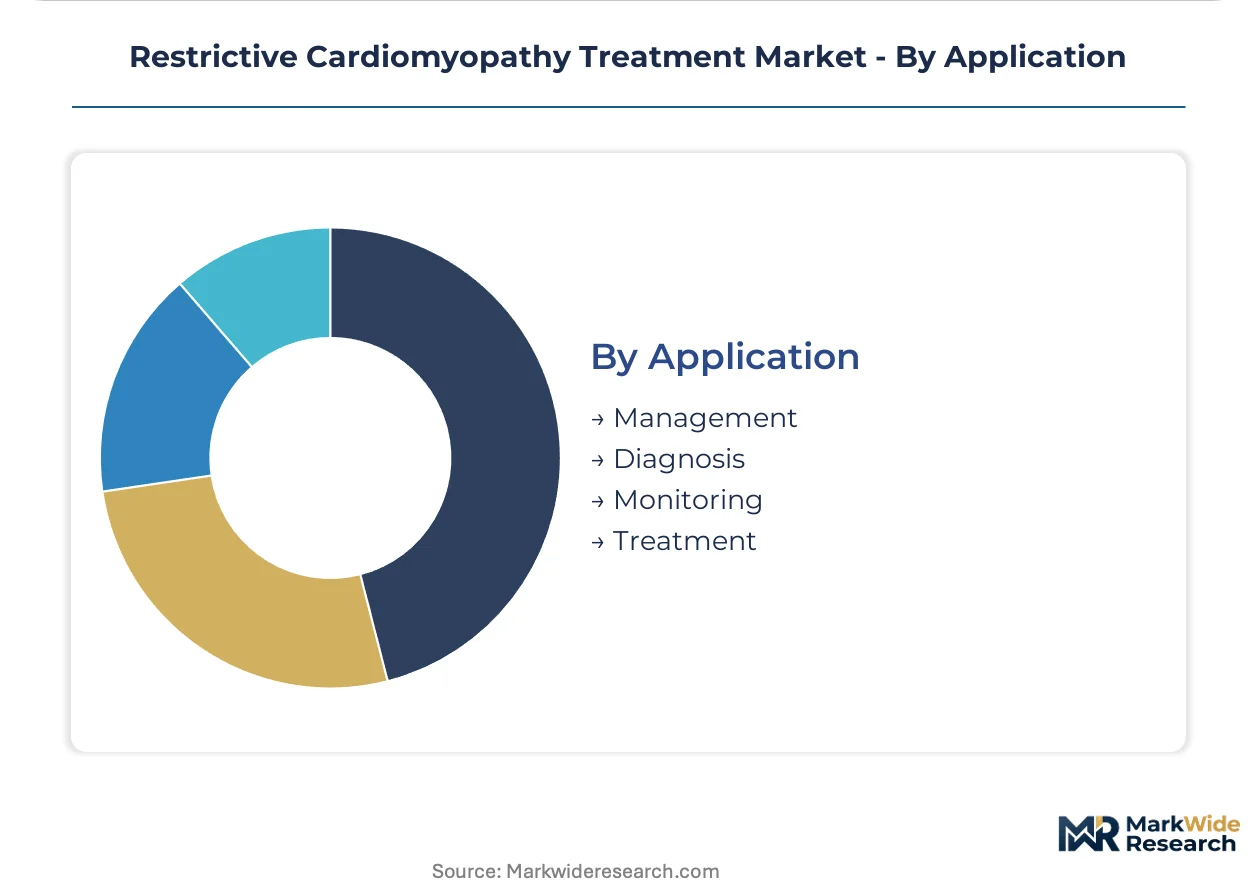
Application:
Maturity gradients separate established diagnostic standards from emerging closed-loop therapeutic platforms across application categories.
- Management:Chronic disease stabilization through medication optimization and lifestyle intervention protocols.
- Diagnosis:Endomyocardial biopsy as definitive standard, supplemented by advanced cardiac MRI and biomarker panels. Diagnostic complexity creates bottlenecks at non-specialized institutions, delaying treatment initiation.
- Monitoring:Implantable pulmonary artery pressure sensors supplanting intermittent catheterization. Heidelberg University Hospital and specialized United States centers are adopting these devices at accelerating pace for restrictive physiology surveillance.
- Treatment:Acute and chronic therapeutic interventions spanning pharmacological, device-based, and surgical modalities.
Management handles the majority of throughput; Monitoring is expanding most quickly as real-time hemodynamic surveillance compresses the diagnostic-therapeutic loop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States imports specialized contrast media and catheterization lab consumables while exporting advanced hemodynamic monitoring devices and leadless pacing systems to European and Asian markets. Germany and Japan maintain near-balanced trade in diagnostic equipment but rely on US-sourced biologics for orphan cardiovascular indications.
United States
Cleveland Clinic and Mayo Clinic anchor referral economies that concentrate endomyocardial biopsy volumes and device implantation procedures. FDA orphan drug designation and breakthrough therapy pathways compress development timelines for mechanism-diverse therapeutic pipelines. Transcatheter delivery system manufacturing clusters in Minnesota and Massachusetts supply leadless pacing technologies to domestic and export markets.
Germany
Heidelberg University Hospital and Charité Berlin sustain high-complexity procedure volumes for restrictive physiology diagnosis and management. EMA parallel scientific advice pathways synchronize development strategies across European member states, reducing redundant regulatory submissions. Baden-Württemberg hosts concentrated manufacturing of advanced cardiac MRI protocols and catheterization laboratory equipment serving continental European demand.
Japan
Tokyo Medical University Hospital and Osaka University Hospital cluster specialized cardiomyopathy expertise that drives procurement of regenerative medicine-integrated platforms. PMDA sakigake designation accelerates commercial timelines for cell therapy developers targeting diastolic dysfunction. Kanto and Kansai regions concentrate domestic manufacturing of implantable pulmonary artery pressure sensors for regional and select export markets.
Switzerland
Swissmedic's streamlined authorization procedures for orphan indications attract cardiovascular biotech development and clinical trial placement. Basel and Zurich host specialized cardiac centers that participate in multinational pivotal studies for restrictive cardiomyopathy therapeutics. The country's precision manufacturing base supplies high-grade catheter components and implantable device subassemblies to German and US assemblers.
United Kingdom
NHS specialized commissioning for rare cardiovascular diseases concentrates diagnostic and therapeutic expertise at Royal Brompton Hospital and Papworth Hospital. MHRA reliance on EMA scientific opinions streamlines market access for therapies securing European approval. London and Cambridge research clusters contribute biomarker-guided patient stratification methodologies to multinational clinical development programs.
Restrictive Cardiomyopathy Treatment Market Competitive Landscape
Listed leaders compete with private specialists across regulatory engagement intensity and portfolio breadth in restrictive cardiomyopathy therapeutics. The market structure consolidates around multinational pharmaceutical conglomerates with established cardiovascular divisions, while emerging cell therapy developers occupy niche mechanism-class positions. Strategic archetypes include orphan-drug portfolio builders, heart failure pathway integrators, and regenerative medicine platform specialists. Dominant competitive moves encompass M&A targeting gene and cell therapy assets, and strategic partnerships bridging diagnostic and therapeutic capabilities.
Within the multinational pharmaceutical tier, Pfizer Inc. and Novartis AG exemplify archetypes of cardiovascular portfolio breadth and heart failure pathway depth respectively. AstraZeneca plc occupies a position emphasizing targeted biologics development within rare disease ecosystems. These three listed entities anchor competitive dynamics through clinical trial momentum across multiple mechanism classes and established relationships with specialized cardiomyopathy centers in the United States, Germany, and Japan.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| AstraZeneca plc |
| Sanofi |
| Merck & Co. Inc. |
| Johnson & Johnson |
| Bristol-Myers Squibb |
| GlaxoSmithKline plc |
| Vericel Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at specialized cardiac device foundries in Minnesota and Massachusetts shapes both supply concentration and price floors for leadless pacing systems. High-mix, low-volume production requirements for orphan cardiovascular indications sustain premium pricing tiers that resist commoditization pressure.
Pricing Analysis
Hospital procurement committees anchor contract negotiations through unbundled purchasing frameworks that separate device hardware from long-term service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough therapy designation status and accompanying exclusivity periods. Cost compression in the standard tier is intensifying because integrated delivery networks consolidate purchasing volume across multi-hospital systems. Community hospital systems exhibit highest price sensitivity due to constrained capital budgets, while specialized cardiomyopathy centers at Cleveland Clinic and Heidelberg University Hospital prioritize clinical performance metrics over unit cost.
Supply Chain Analysis
Strategic stockpiling of iodinated contrast media dominates inventory strategy given periodic shortage events that disrupt catheterization lab scheduling. Manufacturing concentration in the United States, Germany, and Japan draws from specialized polymer foundries for implantable device housings and precision-machined catheter components. Supply chain vulnerability rests on single-source dependencies for high-purity iodinated contrast agents used in hemodynamic assessment. Distribution runs through GPO-negotiated contracts with integrated delivery networks dominating downstream channel structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Restrictive cardiomyopathy therapeutics exhibit cyclical recovery characteristics driven by FDA orphan drug designation waves that periodically refresh development pipelines and reorder competitive positioning.
For Market Incumbents: Fortify market position through backward integration into precision catheter component manufacturing to reduce exposure to Swiss and German subassembly suppliers. Secure exclusive long-term service contracts with Cleveland Clinic, Heidelberg University Hospital, and Tokyo Medical University Hospital to lock in referral economies before leadless pacing technologies commoditize. Prioritize R&D investment in closed-loop therapeutic systems that integrate hemodynamic monitoring with automated medication titration.
For New Entrants and Emerging Players: Post-implantation remote monitoring services represent a service-layer gap where incumbents under-serve stable outpatient populations. Target ambulatory clinic expansion in Germany and the United States where monitoring technologies enable patient migration from hospital-based care. Pursue white-space positioning through biomarker-guided patient stratification platforms that bridge diagnostic and therapeutic capabilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device manufacturers with implanted sensor platforms requiring ongoing data analytics subscriptions. Long-term viability favors acquisition targets possessing regenerative medicine platforms with PMDA sakigake designation progress and established relationships with specialized cardiomyopathy centers. Watch for inflection when orphan drug exclusivity cliffs for first-generation calcium channel modulators trigger portfolio restructuring among multinational pharmaceutical conglomerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for novel mechanism classes. |
| Hospital System Partnership | Exclusive contracts with Cleveland Clinic anchor referral economies for high-complexity procedures. |
| Pipeline Diversification | Cell therapy platforms targeting diastolic dysfunction reduce dependence on chronic medication paradigms. |
| Manufacturing Scale-Up | Transcatheter delivery system production expansion in Minnesota serves domestic and export demand. |
| Reimbursement Strategy | Outpatient clinic channel development captures ambulatory migration for stable patient monitoring. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down epidemiological triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across regulatory approval probability scenarios and reimbursement assumption variations over the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and application category alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves calibrated to historical orphan cardiovascular indication launch patterns and specialist center capacity expansion trajectories.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA frameworks; material policy shifts would require re-modeling. Revision becomes warranted when gene therapy reimbursement thresholds cross institutional adoption tipping points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
US Statin Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Genetic Cardiomyopathies Market