
 Paroxysmal Supraventricular Tachycardia (PSVT) Market | 2026-2036
Paroxysmal Supraventricular Tachycardia (PSVT) Market Size, Share, and Industry Trends Forecast 2026-2036
Paroxysmal Supraventricular Tachycardia (PSVT) Market Analytics
Ambulatory surgical centers is reorganizing treatment delivery for PSVT interventions, pulling procedures away from traditional inpatient settings. Milestone Pharmaceuticals leverages its etripamil program to target self-administered nasal therapy for acute PSVT episodes. Medtronic anchors the ablation device segment through its cryoablation and radiofrequency catheter portfolios. Abbott competes across diagnostic and therapeutic endpoints with integrated electrophysiology mapping systems.
Paroxysmal supraventricular tachycardia comprises a group of cardiac arrhythmias originating above the ventricles, characterized by sudden onset of rapid heart rates exceeding 150 beats per minute with abrupt termination, typically involving re-entrant circuits within the atrioventricular node or accessory pathways. Catheters and ablation devices constitute the procedural backbone, with radiofrequency ablation generating durable pulmonary vein isolation outcomes that reduce recurrent tachycardia burden. Monitoring systems and diagnostic equipment represent adjacent revenue pools where margin accrues to platforms enabling real-time intracardiac signal acquisition. Hospitals retain the highest procedure volume, though ambulatory surgical centers capture faster volume growth as payors favor same-day discharge economics.
FDA premarket notification pathways and CMS national coverage determinations shape market access timelines for novel PSVT therapies, while the EU Medical Device Regulation imposes clinical evidence requirements on ablation catheter manufacturers seeking CE marking. The EU AI Act introduces conformity obligations for machine learning-enabled arrhythmia detection algorithms integrated into monitoring systems. Stakeholders must track how real-world evidence mandates from FDA and post-market surveillance requirements from EMA reshape clinical trial investments and commercial launch sequencing.
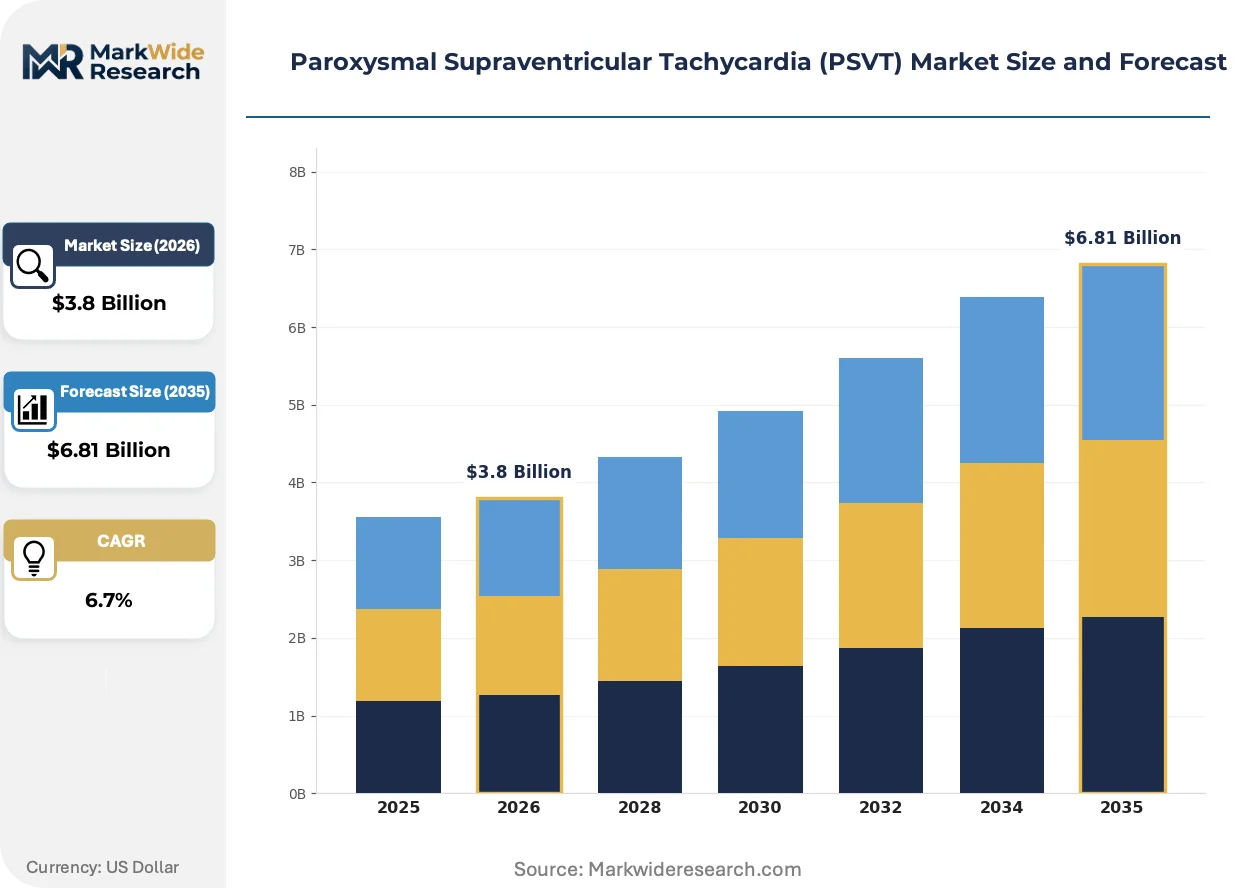
Market Dynamics
Catheter ablation is displacing pharmacological management as first-line intervention for PSVT, driven by CMS reimbursement parity between inpatient and ambulatory settings that accelerates procedural migration toward lower-cost care venues.
Growth Catalysts
- FDA breakthrough pathway:Expedited review timelines for novel ablation catheters compress commercialization cycles, enabling faster patient access to next-generation devices.
- Electrophysiology lab expansion:Hospital systems in Germany and Japan are adding dedicated EP suites, creating procedural capacity that absorbs rising referral volumes.
- Cryoablation precision gains:Improved lesion controllability reduces atrio-esophageal fistula risk, expanding treatable patient populations previously excluded from thermal ablation.
Market Restraints
- Reimbursement compression:CMS physician fee schedule adjustments constrain per-procedure margins for catheter ablation in outpatient settings.
- EP workforce scarcity:Fellowship-trained electrophysiologists concentrate in urban academic centers, creating access deserts in secondary markets.
- Device durability limitations:Radiofrequency catheter electrode degradation necessitates frequent replacement, elevating per-case supply costs.
Strategic Opportunities
- Self-administered acute therapy:Intranasal formulations for patient-managed PSVT termination address emergency department avoidance incentives.
- Ambulatory surgical center penetration:Same-day discharge protocols in United States markets capture payor preference for lower site-of-service costs.
- AI-enabled arrhythmia detection:Machine learning algorithms integrated into consumer wearables create referral pipelines for confirmatory electrophysiology studies.
Industry Challenges
- Credentialing bottlenecks:Proctoring requirements for new ablation technologies delay operator certification and revenue recognition.
- Real-world evidence mandates:FDA post-market surveillance obligations for ablation catheters necessitate costly longitudinal registry participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paroxysmal Supraventricular Tachycardia (PSVT) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Ablation Devices, Monitoring Systems, Diagnostic Equipment End User: Hospitals, Clinics, Ambulatory Surgical Centers, Cardiology Practices Technology: Radiofrequency Ablation, Cryoablation, Electrical Cardioversion, Device Implantation Therapy Area: Arrhythmias, Cardiovascular Disorders, Heart Health, Emergency Medicine |
| Companies Covered | AstraZeneca, Sanofi, Milestone Pharmaceuticals, Medtronic, Johnson & Johnson, Acutus Medical, Bayer, Abbott, Ji Xing Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paroxysmal Supraventricular Tachycardia (PSVT) Market Evolving Landscape
Pulsed field ablation and machine learning diagnostics are restructuring competitive advantage in PSVT intervention, compressing procedure times while expanding treatable anatomy.
Pulsed field ablation technology delivers irreversible electroporation with cardiac tissue selectivity that spares esophageal and phrenic nerve structures. Academic medical centers in Germany and Japan are adopting this modality for complex atrial substrate cases. The technology is decomposing the traditional thermal ablation market by eliminating pulmonary vein isolation redo procedures.
The EU Medical Device Regulation imposes clinical evidence requirements on ablation catheter manufacturers seeking CE marking, extending pre-market timelines by 12-18 months. Manufacturers are restructuring quality management systems to accommodate notified body capacity constraints. High-risk device classifications in Europe are forcing portfolio prioritization toward systems with strongest existing clinical datasets.
Integrated electrophysiology mapping platforms now bundle diagnostic and therapeutic functions into single-procedure workflows. Hospital procurement committees are consolidating vendor relationships around full-stack solutions rather than point-product acquisitions. This consolidation pressure concentrates in United States integrated delivery networks seeking standardization across multi-site electrophysiology programs.
Paroxysmal Supraventricular Tachycardia (PSVT) Market Segmentation
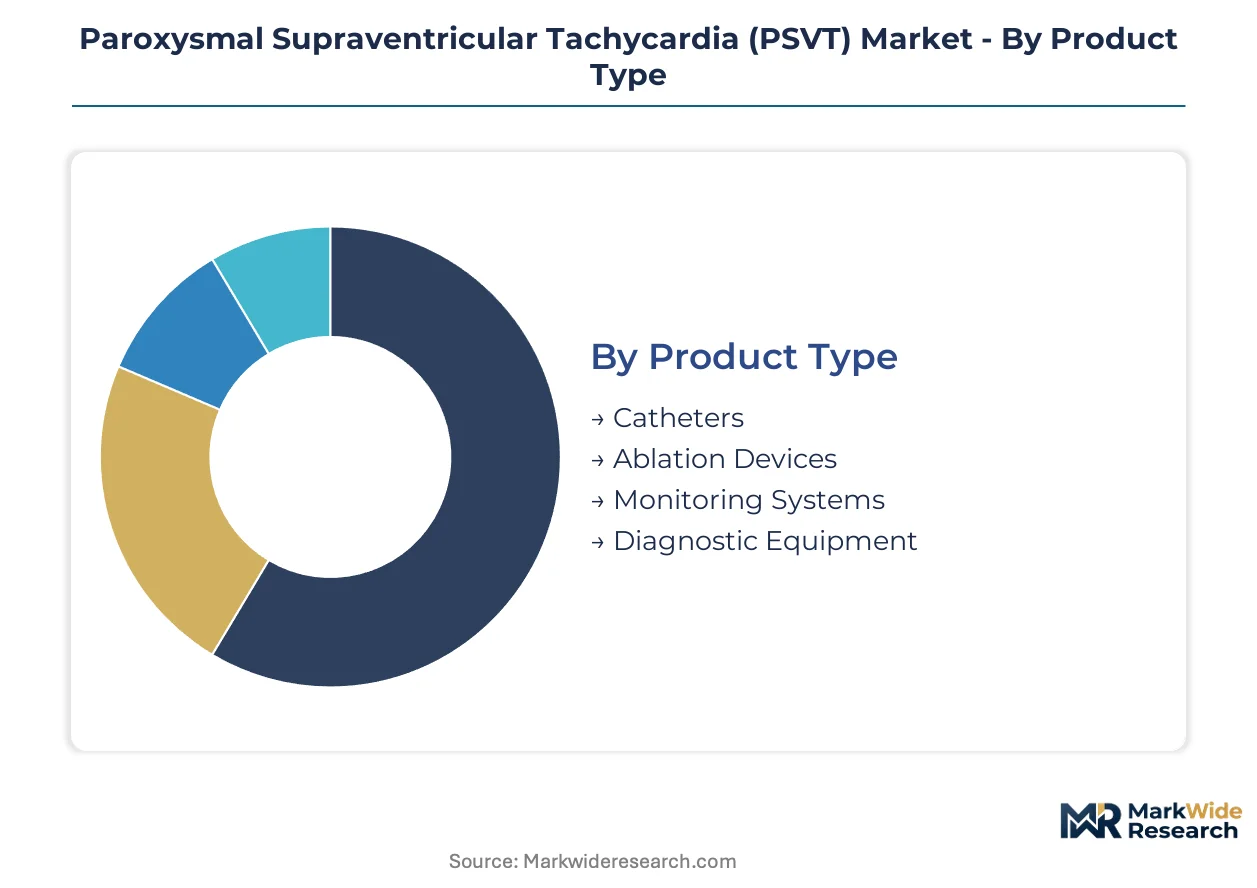
PSVT market segmentation reveals distinct procurement patterns across product categories, with reimbursement pathways and site-of-service economics driving divergent growth trajectories. Understanding these segment boundaries enables targeted positioning for catheter manufacturers, monitoring device developers, and acute therapy innovators competing for electrophysiology budget allocation.
Product Type:
Catheters and ablation devices concentrate manufacturing in Germany and Japan, while monitoring systems show stronger domestic assembly presence in the United States.
- Catheters:Steerable electrode assemblies deliver radiofrequency energy or cryothermal cooling to cardiac tissue via transseptal access. Demand clusters in United States academic medical centers where complex accessory pathway cases require high-density mapping catheter configurations.
- Ablation Devices:Generator systems power thermal and pulsed field modalities with integrated irrigation pumps and temperature feedback loops. German hospital systems are expanding cryoablation console installations to support outpatient procedure migration.
- Monitoring Systems:Holter patches and implantable loop recorders capture arrhythmia episodes for diagnostic confirmation.
- Diagnostic Equipment:Electrophysiology workstations integrate signal processing with three-dimensional cardiac mapping.
Catheters hold the largest share; momentum sits with ablation devices.
End User:
Procurement authority varies sharply across settings, with integrated delivery networks consolidating hospital purchasing while ambulatory centers negotiate device-only contracts.
- Hospitals:Inpatient electrophysiology labs handle complex redo ablations and complication management requiring surgical backup. United States tertiary centers retain high-acuity case volume despite outpatient migration pressure.
- Clinics:Community cardiology offices perform diagnostic workup and patient selection for referral. Japanese clinic networks are expanding Holter monitoring capacity to reduce hospital referral bottlenecks.
- Ambulatory Surgical Centers:Same-day discharge protocols attract uncomplicated pulmonary vein isolation cases.
- Cardiology Practices:Private group practices integrate diagnostic and therapeutic services under single ownership.
Hospitals retain procedural dominance; ambulatory surgical centers are gaining share fastest.
Technology:
Technology selection tracks operator training background and capital equipment amortization schedules, with cryoablation adoption concentrated in newer EP labs.
- Radiofrequency Ablation:Thermal lesion formation via resistive heating remains the reference standard for AV nodal reentrant tachycardia. German electrophysiologists maintain high radiofrequency utilization rates given established reimbursement codes and durable long-term outcomes data.
- Cryoablation:Nitrous oxide-mediated tissue freezing enables reversible testing before permanent lesion creation. United States pediatric EP centers favor cryoablation for AV node proximity cases where thermal injury risks conduction block.
- Electrical Cardioversion:Synchronized shock delivery terminates acute PSVT episodes in emergency settings.
- Device Implantation:Pacemaker and defibrillator placement addresses concomitant bradyarrhythmia or sudden death risk.
Radiofrequency ablation commands installed base leadership; cryoablation shows steepest expansion trajectory.
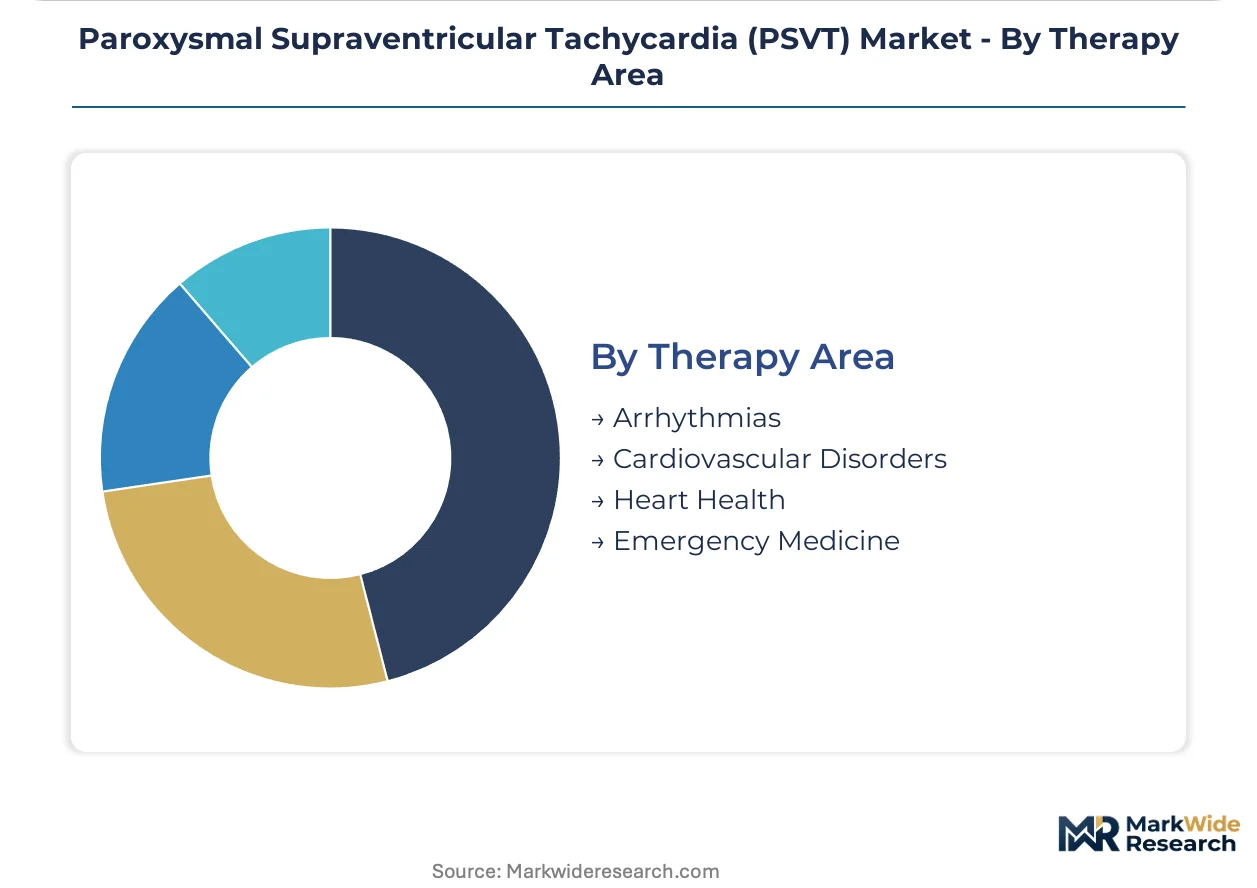
Therapy Area:
Regulatory classification and clinical trial endpoints diverge across therapy areas, with arrhythmia indications commanding premium pricing versus broader cardiovascular labels.
- Arrhythmias:Dedicated PSVT and atrial fibrillation ablation procedures generate procedure-specific reimbursement. Japanese national health insurance maintains distinct fee schedules for supraventricular versus ventricular arrhythmia interventions.
- Cardiovascular Disorders:Structural heart programs bundle arrhythmia treatment with valve or coronary interventions. United States integrated delivery networks capture episode-of-care savings through cardiovascular service line consolidation.
- Heart Health:Preventive screening and risk stratification programs incorporate ambulatory rhythm monitoring.
- Emergency Medicine:Acute episode termination with pharmacological or electrical intervention.
Arrhythmias represents the largest addressable segment; emergency medicine applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiology lab density concentrates PSVT procedure demand in health systems with established cardiac arrhythmia referral networks. Reimbursement parity between inpatient and outpatient settings accelerates site-of-service migration in markets with mature ambulatory surgery infrastructure.
United States
Integrated delivery networks in Texas and Florida are consolidating electrophysiology service lines under single vendor contracts. FDA breakthrough device designations for next-generation ablation catheters compress pre-market timelines for manufacturers targeting outpatient migration. The Cleveland Clinic and Mayo Clinic anchor complex redo ablation referral patterns from secondary markets.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are adding dedicated EP suites to absorb rising supraventricular tachycardia case volumes. EU Medical Device Regulation clinical evidence requirements extend CE marking timelines for ablation catheter manufacturers. The Heidelberg and Hamburg university hospital clusters pioneer pulsed field ablation adoption for complex atrial substrate cases.
Japan
Metropolitan Tokyo and Osaka electrophysiology centers handle concentrated PSVT procedure volumes under national health insurance fee schedules. PMDA consultation pathways for innovative medical devices accelerate market access for novel ablation technologies. The Juntendo and Keio university hospital networks drive cryoablation utilization in pediatric AV node proximity cases.
United Kingdom
NHS England integrated care systems in London and the Midlands are standardizing electrophysiology pathways across tertiary referral networks. NICE technology appraisals shape catheter ablation reimbursement thresholds for paroxysmal supraventricular tachycardia indications. The Royal Brompton and Harefield NHS Foundation Trust anchors national complex ablation case concentration.
China
Provincial hospital systems in Shanghai and Beijing are expanding electrophysiology lab capacity to address underserved arrhythmia patient populations. NMPA innovative medical device review pathways accelerate registration timelines for imported ablation systems. The Fuwai Hospital and Zhongshan Hospital clusters drive domestic catheter manufacturing partnerships.
Paroxysmal Supraventricular Tachycardia (PSVT) Market Competitive Landscape
Player mix skews toward diversified cardiovascular conglomerates with integrated electrophysiology portfolios. Market structure concentrates around manufacturers with full-stack mapping and ablation system offerings. Three archetypes dominate: diversified medtech conglomerates with cardiac rhythm management divisions, pure-play electrophysiology device specialists, and pharmaceutical developers targeting acute episode termination. Competitive dynamics center on strategic partnerships for integrated workflow solutions and geographic expansion through distributor relationships in emerging markets.
Among diversified cardiovascular conglomerates, Medtronic, Abbott, and Johnson & Johnson occupy positions spanning diagnostic mapping through therapeutic ablation. Medtronic represents the cryoablation and radiofrequency catheter archetype with generator system integration. Abbott exemplifies the integrated electrophysiology mapping platform approach bundling diagnostic and therapeutic functions. Johnson & Johnson sits within the structural heart and electrophysiology convergence tier leveraging cardiac surgery relationships. Milestone Pharmaceuticals anchors the self-administered acute therapy developer archetype targeting emergency department avoidance incentives.
| Leading Market Players |
|---|
| AstraZeneca |
| Sanofi |
| Milestone Pharmaceuticals |
| Medtronic |
| Johnson & Johnson |
| Acutus Medical |
| Bayer |
| Abbott |
| Ji Xing Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for ablation catheter electrode assemblies concentrate pricing power with German and Japanese component foundries, while inventory carrying costs for cryoablation console systems force capital equipment vendors toward consignment models that compress working capital margins.
Pricing Analysis
Next-generation pulsed field ablation systems command 40-60% premiums over radiofrequency platforms, while prior-generation thermal catheters face commoditization in high-volume outpatient contracts. Per-procedure transactional pricing dominates, with differentiation driven by FDA breakthrough designation tier and bundled mapping software licenses. Pricing pressure stems from CMS physician fee schedule compression in ambulatory settings. Integrated delivery networks exhibit lowest price sensitivity; standalone cardiology practices face acute budget constraints.
Supply Chain Analysis
Port congestion on transpacific lanes from Shanghai to Long Beach elevates inbound logistics costs for nitrous oxide cryoablation canisters and iridium electrode materials. Manufacturing concentrates in Germany, Japan, and the United States. Component dependencies include platinum-iridium alloys, medical-grade nitrous oxide, and high-density polyethylene catheter sheaths. Single-source vulnerability sits with Japanese suppliers of specialized electrode alloys. Distribution runs through hospital procurement committees and GPO contracts in the United States, direct hospital sales in Germany, and distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter ablation incumbents must defend against pharmacological substitution, particularly intranasal self-administered therapies that threaten emergency department referral volumes and procedural economics.
For Market Incumbents: Shield procedural volume by deepening electrophysiologist training partnerships in secondary markets where workforce scarcity limits competitive entry. Secure GPO contract exclusivity for integrated mapping-ablation platforms before ambulatory surgical center purchasing committees consolidate vendor relationships. Invest in pulsed field ablation R&D to maintain technology leadership against thermal modality commoditization. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable regulatory pathway for novel ablation modalities seeking accelerated commercial access. Target German university hospital clusters where pulsed field ablation adoption creates reference center demand for next-generation catheter designs. Pursue white-label manufacturing partnerships with established generator system vendors to bypass capital equipment distribution barriers. For Investors and Strategic Acquirers: Long-term, this sits as a procedure-migration play because ambulatory surgical center volume capture will determine competitive positioning across the next decade. Acquisition targets should display integrated electrophysiology platform capabilities rather than point-product specialization. Monitor CMS national coverage determination timelines for outpatient ablation as the critical inflection signal for valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses commercialization cycles for novel ablation catheters targeting outpatient migration. |
| Hospital System Partnership | Exclusive vendor contracts with Cleveland Clinic and Mayo Clinic anchor complex redo ablation referral networks. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend pre-market timelines and force portfolio prioritization toward established datasets. |
| Software Companion Development | AI-enabled arrhythmia detection algorithms integrated into mapping platforms create referral pipeline capture. |
| Reimbursement Strategy | CMS national coverage determinations for ambulatory ablation accelerate site-of-service economics favoring same-day discharge. |
Research Methodology
A spread of perspectives from electrophysiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying procedural volume and technology adoption trajectories. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and PMDA consultation pathway disclosures. Bottom-up triangulation of catheter shipment volumes and top-down reconciliation against national health insurance fee schedules anchored the analytical framework.
Segmentation dimensions modeled include ablation technology modality, site-of-service setting, and operator training background across the projection horizon. CAGRs were derived from elasticity-adjusted procedural volume projections and equipment replacement cycle analysis. Forecast inputs incorporated electrophysiology lab capacity expansion schedules in Germany and Japan, and CMS reimbursement parity assumptions between inpatient and ambulatory settings.
Decision-makers should treat outputs as directional under base assumptions of sustained reimbursement support for catheter ablation and stable EP workforce training pipeline throughput; material deviation in either factor would warrant model refresh. Specific risks include PMDA regulatory delays for novel modalities and EU notified body capacity constraints extending CE marking timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Atherosclerosis Therapeutics Market