
 Ventricular Tachycardia Market | 2026-2036
Ventricular Tachycardia Market Size, Share, and Industry Trends Forecast 2026-2036
Ventricular Tachycardia Market Intelligence
The distinction between high-margin, technologically advanced ablation systems and lower-cost pharmacological therapies is recalibrating market dynamics. Medtronic plc leverages its extensive portfolio in implantable cardioverter defibrillators (ICDs) to maintain a strong market presence. Boston Scientific Corporation differentiates through its investment in novel catheter-based ablation technologies. Abbott Laboratories competes with its advanced cardiac mapping and diagnostic systems, focusing on improving procedural accuracy and patient outcomes.
Ventricular tachycardia is a life-threatening cardiac arrhythmia characterized by a rapid heart rate, typically over 100 beats per minute, originating from the ventricles. This condition can impair the heart's ability to pump blood effectively, leading to syncope or sudden cardiac arrest. The primary clinical goal is to terminate the arrhythmia and implement strategies to prevent recurrence. Implantable cardioverter defibrillators and catheter ablation devices represent the highest-value product segments. Electrophysiology labs and specialty hospitals are the dominant end-user settings due to the technical requirements of these advanced interventions.
Regulatory oversight from the FDA in the United States and the EMA in Europe mandates stringent premarket approval processes for new devices and drugs. In China, the NMPA sets standards for cardiac rhythm management technologies, influencing market entry for foreign and domestic firms. These regulatory frameworks directly impact product development cycles and market access strategies. A key decision for providers involves balancing investment in capital-intensive ablation systems against the long-term management costs associated with ICDs and pharmacological treatments.
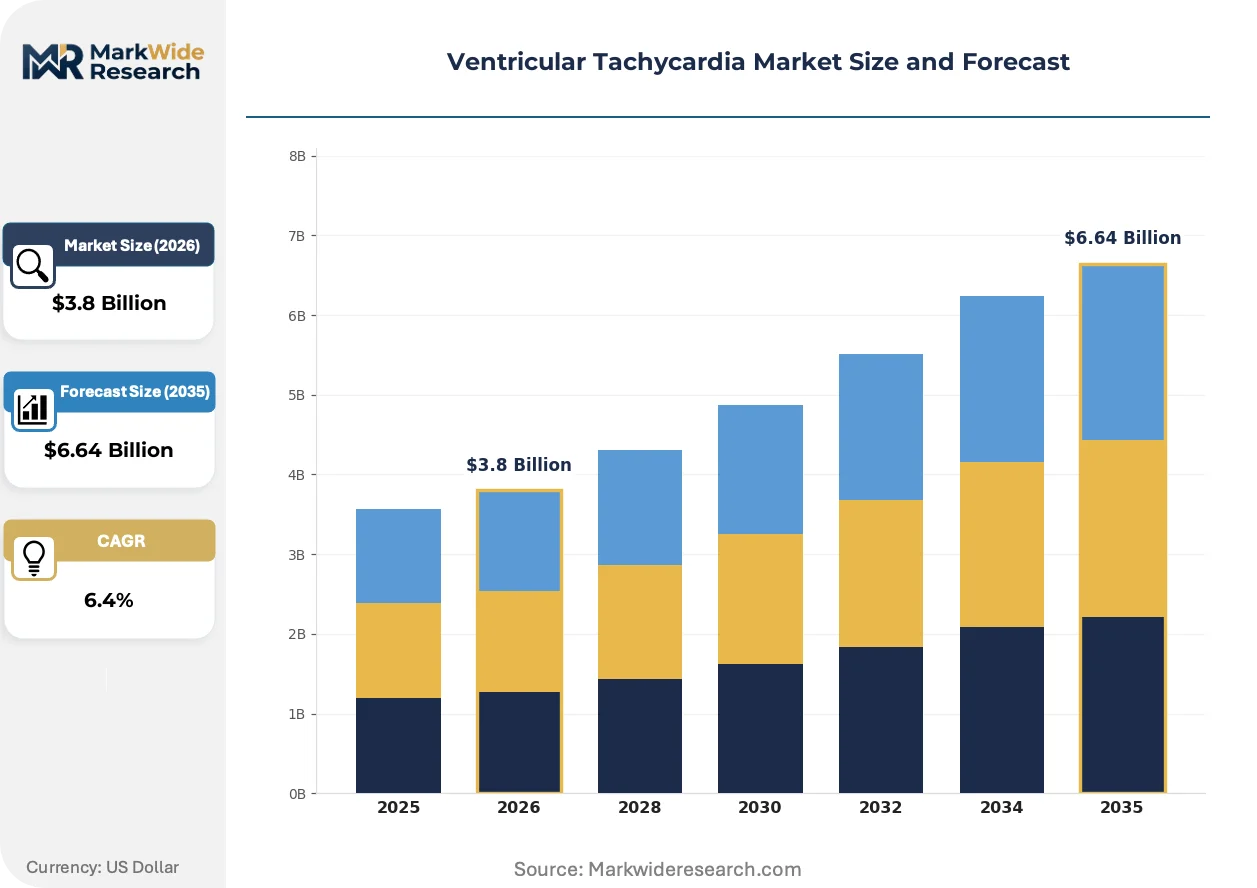
Market Dynamics
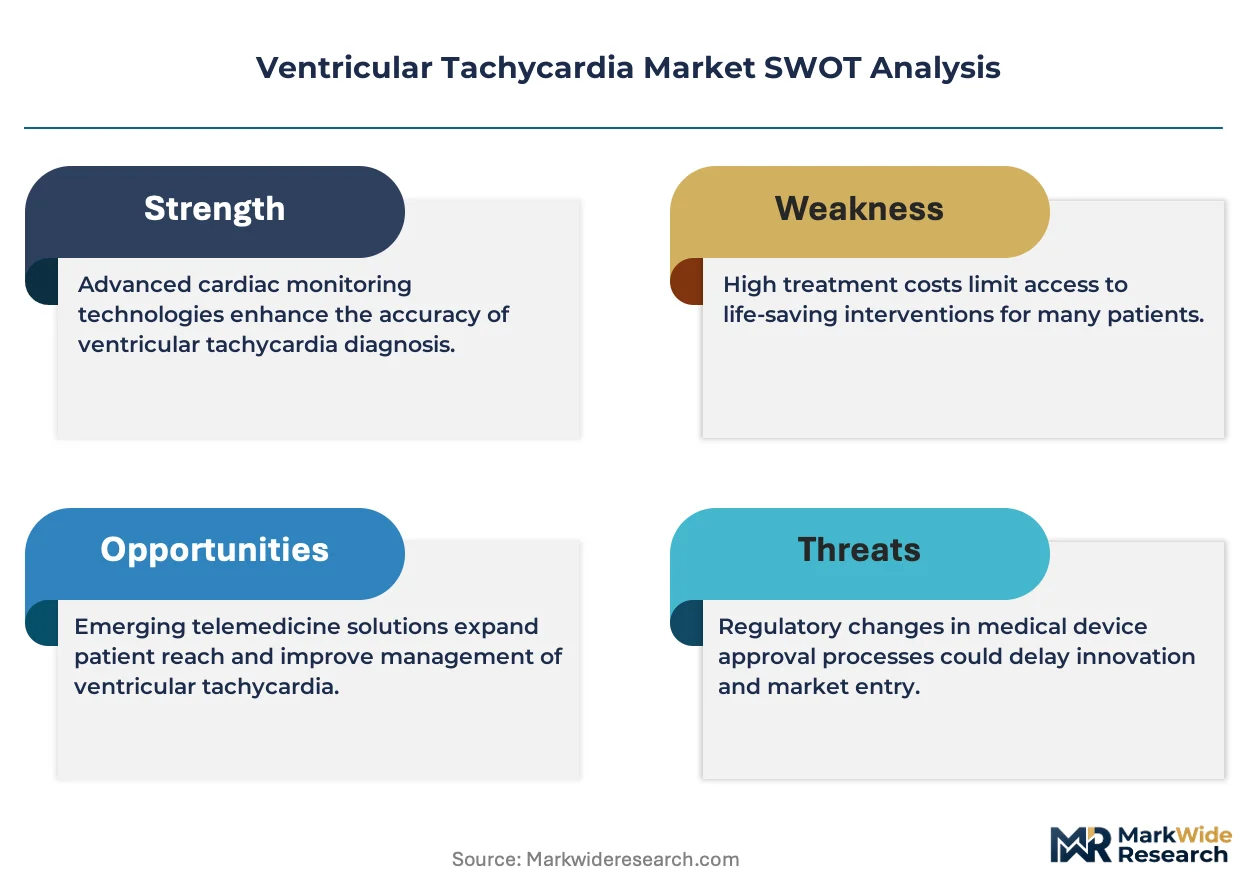
The market's central dynamic is the clinical and economic trade-off between capital-intensive, curative interventional procedures and long-term, palliative management with ICDs and pharmaceuticals. This balance dictates investment priorities for providers and shapes technology development for manufacturers.
Growth Catalysts
- Advanced Cardiac Mapping:The evolution of high-density, 3D cardiac mapping systems improves the precision and success rates of catheter ablation procedures, encouraging adoption in specialized electrophysiology labs for treating complex arrhythmias.
- Aging Demographics:A growing global elderly population, particularly in developed nations, leads to a higher prevalence of structural heart disease and associated ventricular arrhythmias, directly expanding the addressable patient base.
- Favorable Reimbursement:Established reimbursement frameworks for ICD implantation and catheter ablation in countries like the United States and Germany provide financial incentives for hospitals to invest in and perform these high-value procedures.
Market Restraints
- High Capital Investment:The substantial upfront cost of catheter ablation systems, including 3D mapping consoles and related disposables, acts as a significant financial barrier for smaller hospitals and healthcare systems in emerging markets.
- Procedural Complexity and Risk:Catheter ablation for ventricular tachycardia is a technically demanding procedure with inherent risks, including cardiac perforation, limiting its application to highly skilled electrophysiologists in specialized centers.
- Stringent Regulatory Hurdles:Rigorous premarket approval pathways enforced by the FDA and the EMA for new Class III cardiac devices result in extended and expensive product development timelines, slowing innovation.
Strategic Opportunities
- Emerging Market Penetration:Expanding access to advanced arrhythmia treatments in large, underserved markets like China and India represents a major growth vector as their healthcare infrastructure and disposable income levels increase.
- AI Integration in Diagnostics:Incorporating artificial intelligence and machine learning algorithms into diagnostic and mapping systems to automatically identify arrhythmia origins offers a path to reduce procedure times and improve outcomes.
- Subcutaneous ICDs:The development and promotion of subcutaneous implantable cardioverter-defibrillators (S-ICDs) provide an alternative for patients without the need for pacing, opening a new patient segment concerned with transvenous lead complications.
Industry Challenges
- Electrophysiologist Shortage:A global scarcity of trained electrophysiologists and skilled lab staff capable of performing complex ablation procedures creates a critical bottleneck, limiting the capacity to meet patient demand.
- System Interoperability:Achieving seamless data integration between competing cardiac mapping systems, ablation generators, and a hospital's electronic health record (EHR) systems remains a persistent operational hurdle for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventricular Tachycardia Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiarrhythmic Drugs, Implantable Cardioverter Defibrillators, Catheters, External Defibrillators, Ablation Devices Therapy Area: Ischemic Heart Disease, Cardiomyopathy, Congenital Heart Defects, Myocarditis, Valvular Disease End User: Cardiology Clinics, Electrophysiology Labs, Specialty Hospitals, Ambulatory Surgical Centers, Diagnostic Centers Delivery Mode: Invasive Catheter-Based, Pharmacological, Device-Based Therapy, Surgical Intervention, Remote Monitoring |
| Companies Covered | Johnson & Johnson, Asahi Kasei Corporation, Medtronic plc, EBR Systems, Inc., LivaNova plc, Boston Scientific Corporation, BIOTRONIK SE & Co. KG, Siemens Healthineers AG, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventricular Tachycardia Market Strategic Shifts & Innovations
A fundamental shift toward procedural precision is defining the market, driven by innovations that enhance diagnostic accuracy and therapeutic efficacy. This evolution prioritizes data-driven interventions over generalized treatment protocols, aiming for improved long-term patient outcomes and reduced recurrence rates.
Advanced software algorithms are being integrated directly into 3D cardiac mapping platforms to analyze complex electrogram signals. Electrophysiology labs in major academic hospitals are the primary adopters of these sophisticated tools. This technology is automating the identification of critical arrhythmia circuits, thereby reducing reliance on operator interpretation and potentially shortening complex procedure times.
The European Union's Medical Device Regulation (MDR) has significantly elevated the bar for clinical evidence and post-market surveillance. This regulation compels manufacturers of high-risk devices like ICDs and ablation catheters to conduct more extensive clinical investigations. Consequently, the cardiac rhythm management device segment faces increased compliance costs and longer pathways to secure and maintain CE marking for market access in Europe.
Hospital purchasing behavior is moving away from one-time capital equipment sales toward comprehensive, multi-year managed service contracts. This trend disrupts the traditional transactional model for ablation systems, replacing it with partnerships that bundle equipment, software updates, maintenance, and clinical support. This model is gaining traction in large US and German hospital networks seeking predictable operational expenditures and access to the latest technology.
Ventricular Tachycardia Market Segmentation
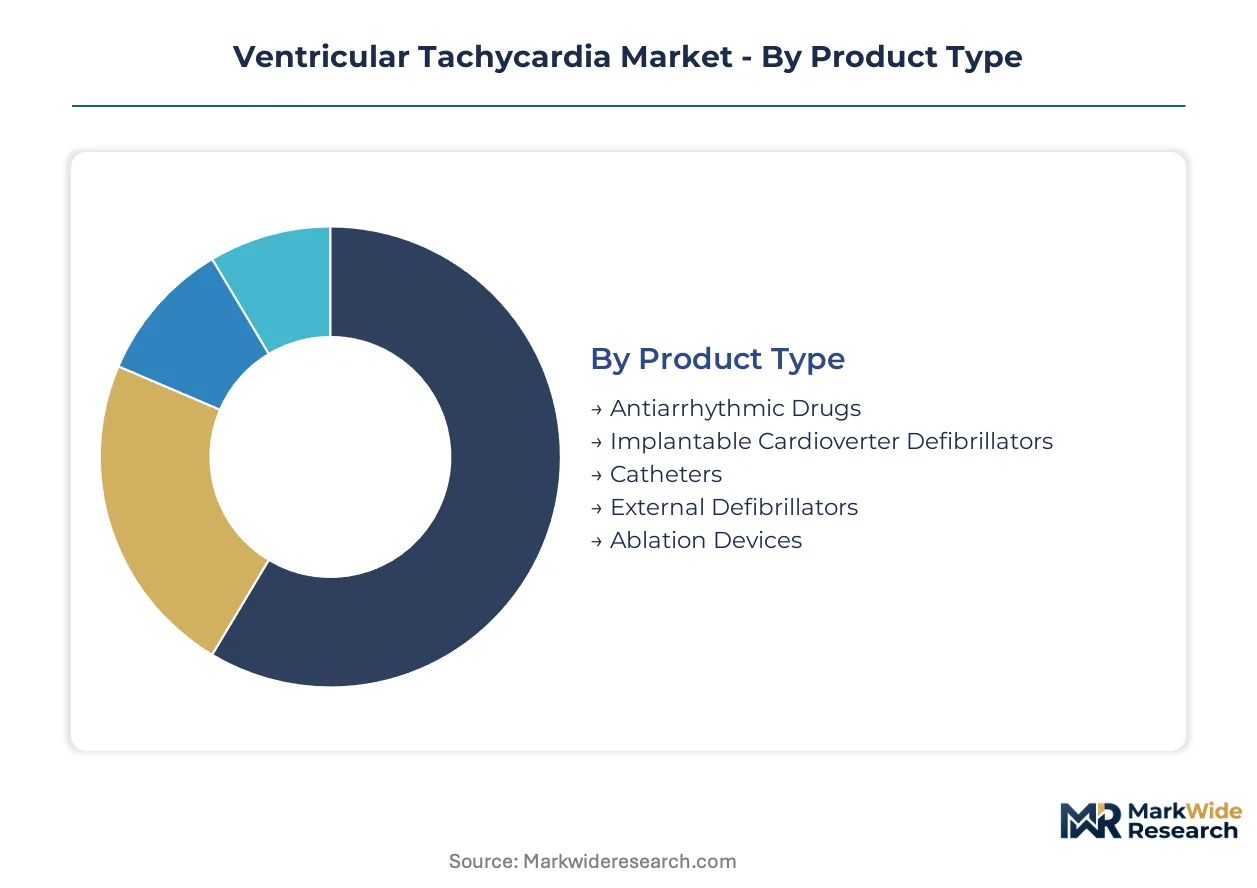
The Ventricular Tachycardia market's segmentation reflects the diverse approaches to managing complex cardiac arrhythmias, influencing procurement decisions and technology development. Understanding these distinct segments helps manufacturers tailor solutions and healthcare providers optimize treatment protocols for patient-specific needs. Each segment addresses specific clinical requirements and operational capabilities.
Product Type:
The selection of product types is primarily driven by the clinical urgency and long-term management strategy for ventricular tachycardia patients.
- Implantable Cardioverter Defibrillators:These devices continuously monitor heart rhythm and deliver electrical shocks to correct life-threatening arrhythmias, preventing sudden cardiac death. Demand concentrates in the United States, supported by established reimbursement pathways for long-term cardiac rhythm management.
- Ablation Devices:Catheter-based systems designed to precisely target and destroy cardiac tissue causing arrhythmias, offering a potentially curative intervention. Adoption is increasing in Germany, driven by advancements in 3D cardiac mapping systems that enhance procedural efficacy.
- Antiarrhythmic Drugs:Pharmacological agents used to suppress or prevent abnormal heart rhythms, serving as a first-line or adjunctive therapy.
- Catheters:Specialized tubes used in electrophysiology procedures for diagnostic mapping and delivering energy during ablation.
- External Defibrillators:Devices used for immediate resuscitation in out-of-hospital or emergency settings to deliver a high-energy electrical shock.
Volume sits with Antiarrhythmic Drugs; growth tilts toward Ablation Devices.
Therapy Area:
The scope of application for ventricular tachycardia treatments varies significantly across different underlying cardiac conditions.
- Ischemic Heart Disease:This condition, caused by reduced blood flow to the heart, is a major contributor to ventricular arrhythmias, necessitating interventions to stabilize heart function. This patient group represents a large addressable market in developed nations due to aging demographics.
- Cardiomyopathy:A disease of the heart muscle that makes it harder for the heart to pump blood, often leading to ventricular tachycardia. Treatment for this condition requires specialized diagnostic and interventional tools.
- Congenital Heart Defects:Structural problems with the heart present at birth, which can predispose individuals to complex arrhythmias later in life.
- Myocarditis:Inflammation of the heart muscle, typically caused by viral infections, which can trigger ventricular tachycardia.
- Valvular Disease:Conditions affecting the heart valves that can lead to structural changes and electrical instability, increasing arrhythmia risk.
The largest patient population is observed in Ischemic Heart Disease, while Cardiomyopathy shows the most dynamic expansion.
End User:
Operational capabilities and the level of specialized expertise dictate where advanced ventricular tachycardia treatments are performed.
- Electrophysiology Labs:Highly specialized facilities equipped with advanced imaging, mapping, and ablation systems for complex arrhythmia interventions. These labs in major academic hospitals in the United States are primary adopters of new technologies.
- Specialty Hospitals:Institutions focusing on specific medical conditions, including cardiovascular diseases, providing comprehensive care for ventricular tachycardia patients. These hospitals in Germany are investing in capital-intensive ablation systems.
- Cardiology Clinics:Outpatient settings primarily focused on diagnosis, medical management, and follow-up care for cardiac conditions.
- Ambulatory Surgical Centers:Facilities performing same-day surgical procedures, which may include less complex device implantations or diagnostic procedures.
- Diagnostic Centers:Facilities dedicated to identifying medical conditions through various tests, including electrocardiograms and electrophysiology studies.
Specialized interventions are predominantly performed in Electrophysiology Labs, with increasing demand observed in Specialty Hospitals.
Delivery Mode:
The invasiveness and long-term nature of treatment define the different delivery modes for managing ventricular tachycardia.
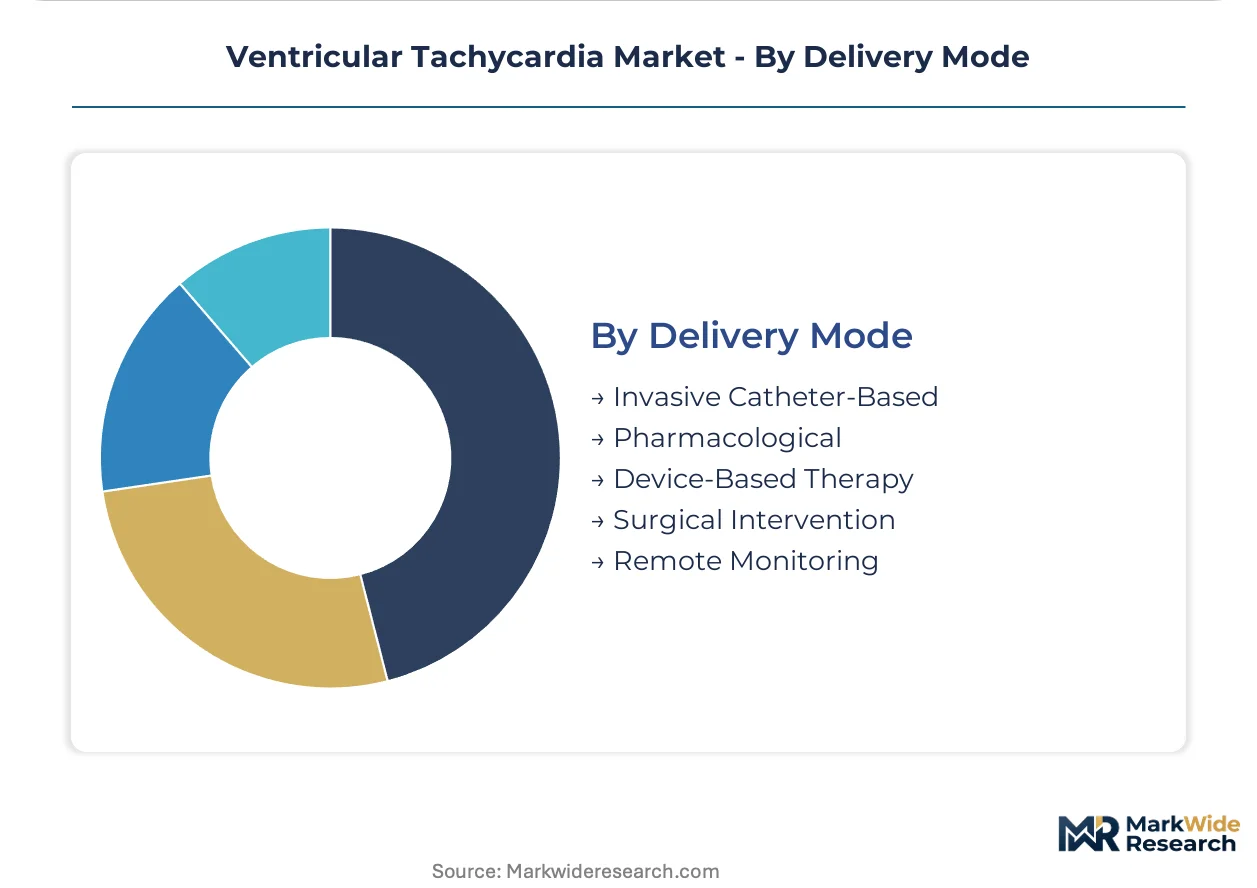
- Invasive Catheter-Based:Procedures involving the insertion of catheters into the heart to diagnose and ablate arrhythmia-causing tissues. This mode offers a curative approach, particularly for complex arrhythmias.
- Device-Based Therapy:Implantation of devices like ICDs that provide continuous monitoring and automatic intervention for life-threatening arrhythmias. This represents a high-value product segment, particularly in developed markets.
- Pharmacological:Administration of antiarrhythmic drugs to control heart rhythm, offering a less invasive management option.
- Surgical Intervention:Open-heart procedures performed to address underlying structural heart issues contributing to ventricular tachycardia, often reserved for complex cases.
- Remote Monitoring:Systems that allow healthcare providers to track patient cardiac rhythm and device performance from a distance, enhancing patient safety and follow-up care.
The most frequent approach is Pharmacological, though Invasive Catheter-Based is gaining considerable traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City's dense medical infrastructure and advanced research institutions drive a significant portion of ventricular tachycardia market innovation. This urban hub, alongside other major global cities, fosters the development and adoption of cutting-edge cardiac rhythm management technologies. Specialized electrophysiology labs within these metropolitan areas lead in complex arrhythmia interventions.
United States
Demand for implantable cardioverter defibrillators and catheter ablation systems is high, supported by a large aging population and advanced healthcare infrastructure. The FDA's stringent premarket approval process ensures device safety and efficacy for cardiac rhythm management technologies. Boston's biotech corridor concentrates research and development efforts for novel arrhythmia treatments and diagnostic tools.
Germany
Investments in capital-intensive ablation systems are substantial, driven by a focus on curative interventional procedures. European Medical Device Regulation (MDR) compliance shapes product development cycles for devices seeking market access within the EU. Munich's medical technology cluster actively develops sophisticated 3D cardiac mapping systems.
China
Expanding access to advanced arrhythmia treatments is a major growth vector, fueled by increasing healthcare infrastructure and disposable income. The NMPA sets standards for cardiac rhythm management technologies, influencing market entry for foreign and domestic firms. Shanghai's medical device manufacturing centers are increasing local production capabilities for electrophysiology equipment.
India
Healthcare infrastructure improvements and a rising middle class are contributing to a growing addressable patient base for ventricular tachycardia treatments. The CDSCO regulates medical devices, impacting market penetration for advanced cardiac rhythm management solutions. Bengaluru's emerging medical technology sector focuses on developing cost-effective diagnostic and therapeutic devices.
Japan
An aging demographic significantly contributes to the prevalence of structural heart disease and associated arrhythmias. PMDA regulations guide the approval and market entry of new cardiac devices, ensuring high safety and quality standards. Tokyo's leading hospitals and research institutions are at the forefront of adopting advanced cardiac mapping technologies.
Ventricular Tachycardia Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the ventricular tachycardia market. The market exhibits a tiered structure, with established medical device giants alongside specialized innovators. Strategic archetypes include integrated device manufacturers, focused ablation technology providers, and diagnostic system developers. Dominant competitive moves involve strategic partnerships for technology co-development and portfolio diversification across cardiac rhythm management solutions.
Within the integrated device manufacturer archetype, Medtronic plc and Boston Scientific Corporation exemplify firms with extensive portfolios spanning implantable devices and catheter-based therapies. Medtronic plc, a global medical technology company, leverages its strong presence in implantable cardioverter defibrillators to maintain market share. Boston Scientific Corporation, a US-based firm, differentiates through its investment in novel catheter-based ablation technologies, targeting improved procedural efficacy. Abbott Laboratories, also a US-based corporation, occupies a position focused on advanced cardiac mapping and diagnostic systems, emphasizing procedural accuracy and patient outcomes.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Asahi Kasei Corporation |
| Medtronic plc |
| EBR Systems, Inc. |
| LivaNova plc |
| Boston Scientific Corporation |
| BIOTRONIK SE & Co. KG |
| Siemens Healthineers AG |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Medical-grade material costs, particularly for platinum-iridium alloys used in catheter electrodes, cascade through the Ventricular Tachycardia market. This cost structure influences the final pricing tiers for advanced ablation systems and implantable devices, impacting procurement decisions for healthcare providers globally.
Pricing Analysis
Value-based pricing, tied to improved patient outcomes and reduced recurrence rates, underpins the Ventricular Tachycardia market. The dominant pricing structure blends transactional per-unit sales for disposables with comprehensive multi-year managed service contracts for capital equipment. Price differentiation stems from technological sophistication and regulatory approval tiers like FDA clearance. Pricing softness reflects intense competition from pharmacological alternatives. Electrophysiology labs in academic hospitals demonstrate lower price sensitivity compared to smaller specialty hospitals.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers in regions like the United States and Germany, supplying critical microprocessors and sensors for cardiac devices. The supply chain draws from medical-grade plastics and advanced electronic circuits. Logistics chokepoints represent a structural risk, particularly for time-sensitive, sterile components. Distribution runs through direct sales forces to major hospital networks and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ventricular Tachycardia market operates as a cost-of-compliance story, where the European Union's Medical Device Regulation (MDR) creates a significant barrier-to-entry moat for compliant device manufacturers.
For Market Incumbents: Deploy strategic partnerships for technology co-development to counter the threat from specialized software innovators. Incumbents should diversify portfolios across implantable devices and advanced ablation systems, leveraging existing reimbursement pathways. Investing in AI integration within current mapping systems enhances procedural efficacy, protecting market share against emerging, asset-light diagnostic firms.
For New Entrants and Emerging Players: AI-powered diagnostic and mapping software offers a technology-first wedge, targeting underserved markets like India and China. New entrants should focus on cost-effective, high-precision tools for less complex arrhythmia cases. A go-to-market angle emphasizing automated arrhythmia identification and reduced procedure times can attract early adopters in developing electrophysiology centers.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking specialized software firms and innovative S-ICD developers for long-term growth. Investment over the next five to ten years should target companies with strong intellectual property in AI-driven cardiac mapping. A key signal to watch is successful clinical trial data for novel non-invasive arrhythmia detection technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Secures market access for novel devices in the critical United States market. |
| Hospital System Partnership | Ensures consistent adoption of advanced ablation technologies across major networks. |
| Software Companion Development | Enhances device functionality and improves procedural accuracy for electrophysiologists. |
| Reimbursement Strategy | Optimizes financial incentives for hospitals to adopt new high-value interventions. |
| CE Marking Pathway | Facilitates market entry and sustained sales for devices within the European Union. |
Research Approach
Multi-period observation of device adoption rates and procedural volumes anchored the trend analysis, supplemented by interviews with electrophysiologists, hospital procurement managers, and device R&D leads. Secondary validation drew from FDA filings, EMA submissions, company annual reports, and clinical trial registries. Bottom-up data collection was triangulated with top-down market sizing for robust estimates.
An input-output matrix structured the quantitative analytical framework across the analysis window. Segmentation dimensions modeled included product type, therapy area, end user, delivery mode, and regional adoption patterns. Compound Annual Growth Rates were derived from historical trajectory analysis and projected market drivers. Key inputs included aging population demographics and global healthcare expenditure trends.
Several conditions sit outside the modeled scope, including specific macroeconomic shocks or unforeseen technological breakthroughs. Forecasts reflect assumptions regarding regulatory stability and clinical practice evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
US Statin Market