
 Antihypertensive Market | 2026-2036
Antihypertensive Market Size, Share, and Industry Trends Forecast 2026-2036
Antihypertensive Market Intelligence
Generic drug manufacturing in India is pivoting towards producing complex combination therapies and extended-release formulations, creating new competitive pressures. This shift challenges established portfolios from major pharmaceutical firms like AstraZeneca Plc, which sustains its market position through a strong R&D pipeline in cardiovascular disease. Pfizer Inc. leverages its extensive global distribution network for its established brands, while Novartis AG specializes in innovative treatments, including novel antihypertensive agents.
Antihypertensive drugs are a class of pharmaceuticals designed to lower and control high blood pressure. These medications function through various mechanisms, such as ACE Inhibitors that block the angiotensin-converting enzyme to relax blood vessels. Therapeutic approaches for primary hypertension heavily rely on established drug classes like Calcium Channel Blockers and Beta Blockers. Meanwhile, injectable solutions and transdermal patches represent niche delivery modes, often reserved for specific patient populations in specialty hospitals.
Market access is governed by stringent clinical trial and approval protocols set by bodies like the US FDA and the European Medicines Agency (EMA). In Asia, regulators such as China's NMPA and Japan's PMDA enforce specific guidelines for drug registration and pharmacovigilance. Manufacturers must navigate these diverse regulatory landscapes while balancing investment in next-generation therapies against the lifecycle management of existing blockbuster drugs.
Market Dynamics
The antihypertensive market is shaped by the structural tension between the high-value, patent-protected portfolios of established pharmaceutical firms and the escalating competitive pressure from Indian manufacturers specializing in complex generic formulations and combination therapies.
Growth Catalysts
- Accelerated Approval Pathways:The US FDA's framework for accelerated approval of novel combination therapies is lowering barriers to entry for new formulations, stimulating innovation in fixed-dose combinations that improve patient adherence.
- Aging Demographics:The large and rapidly aging population in China is a significant driver, as the prevalence of primary hypertension and associated chronic conditions increases, requiring long-term pharmacological management.
- Formulation Technology:Advances in drug delivery, specifically the development of extended-release formulations, are creating value by improving therapeutic outcomes and reducing dosing frequency for patients in geriatric care settings.
Market Restraints
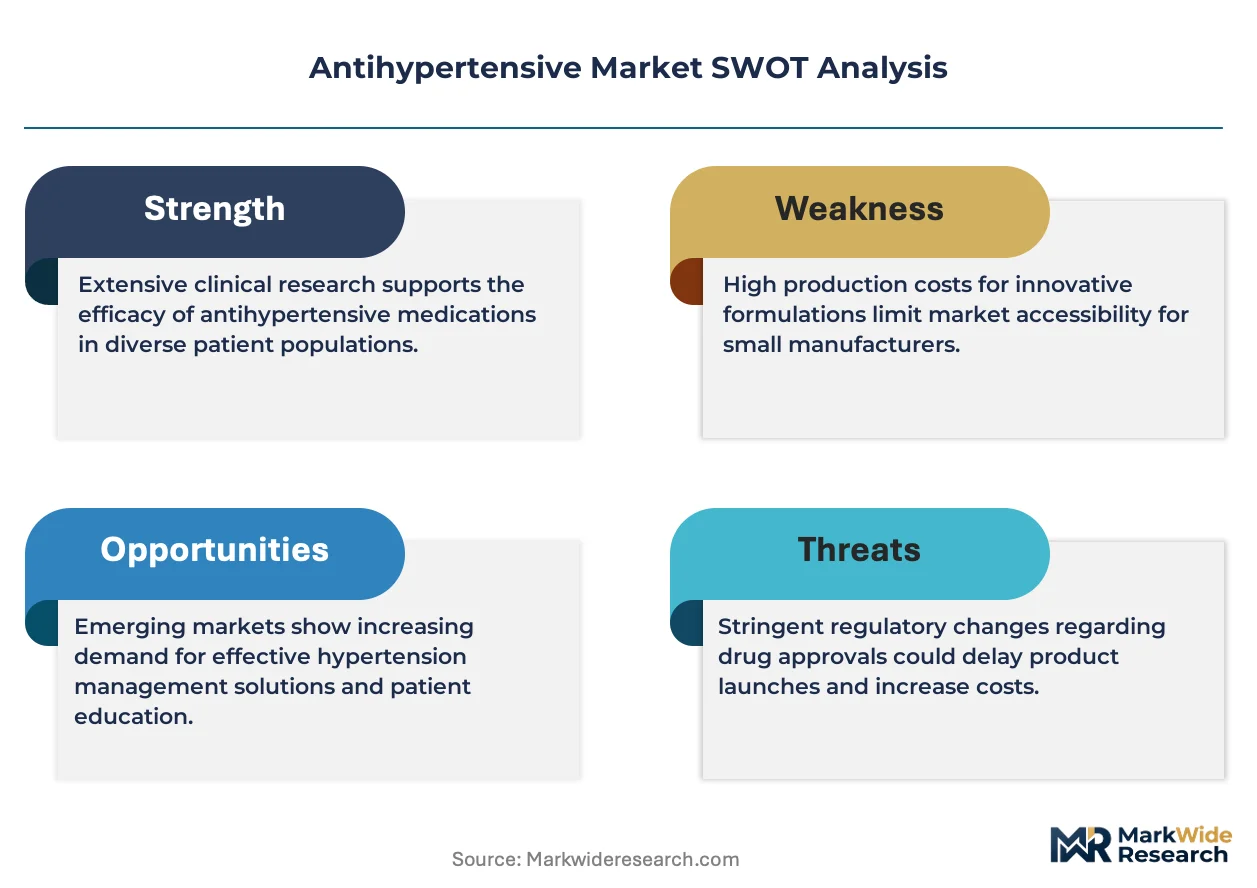
- Stringent Regulatory Hurdles:The rigorous and lengthy clinical trial and approval protocols mandated by regulatory bodies like the European Medicines Agency (EMA) and US FDA impose significant time and cost burdens on drug development.
- Patent Cliff Erosion:The expiration of patents on major blockbuster antihypertensive drugs triggers rapid market share loss and severe price declines as generic manufacturers introduce chemically equivalent alternatives.
- API Supply Concentration:A high degree of dependency on a limited number of active pharmaceutical ingredient (API) suppliers, particularly for older drug classes, creates potential for supply chain disruptions and price volatility.
Strategic Opportunities
- Digital Health Integration:The convergence of antihypertensive agents with digital health platforms, such as smart inhalers or connected blood pressure monitors, offers a pathway to create value-added services around remote monitoring and adherence support.
- Novel Delivery Systems:There is a distinct opportunity in developing alternative delivery mechanisms like transdermal patches, which can cater to specific patient populations such as those with dysphagia or in critical care.
- Untreated Population Access:Expanding market access in underpenetrated regions of Southeast Asia and Africa, where hypertension prevalence is high but access to effective and affordable treatment remains limited, represents a long-term growth vector.
Industry Challenges
- Regulatory Divergence:Manufacturers face significant operational complexity in navigating the disparate drug registration and pharmacovigilance requirements of national regulators, including China's NMPA, Japan's PMDA, and the US FDA.
- Lifecycle Management Pressure:Companies must balance the substantial investment required for R&D in next-generation therapies against the need to defend the intellectual property and market position of existing blockbuster drugs.
- Manufacturing Scale-Up:The transition towards producing complex combination therapies and modified-release formulations demands higher capital investment in specialized manufacturing technology and quality control systems compared to standard generics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antihypertensive Market |
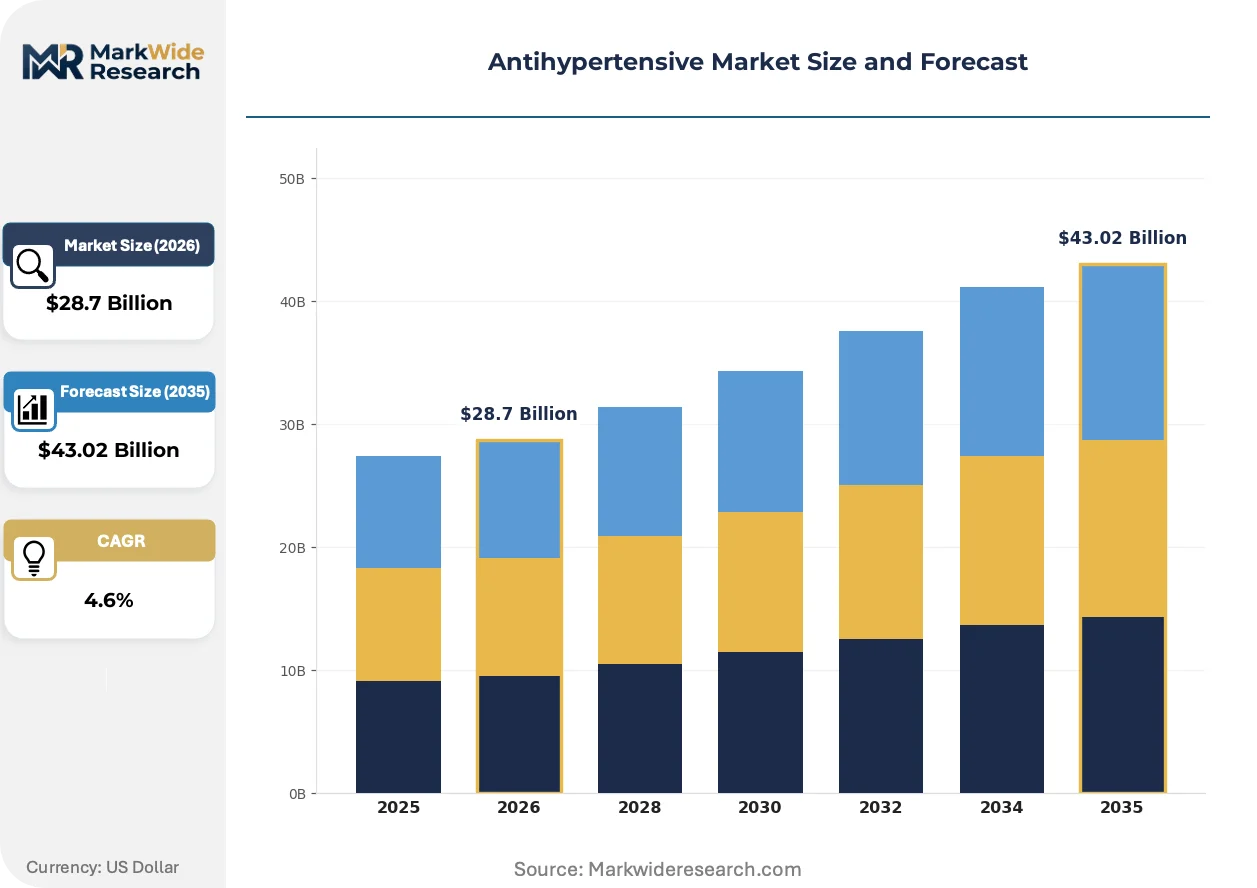
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta Blockers, Calcium Channel Blockers, ACE Inhibitors, Diuretics, Angiotensin II Receptor Blockers Application: Primary Hypertension, Secondary Hypertension, Pulmonary Hypertension, Gestational Hypertension, Renovascular Hypertension End User: Cardiology Clinics, Geriatric Care, Specialty Hospitals, Research Institutes, Community Health Centers Delivery Mode: Oral Tablets, Injectable Solutions, Transdermal Patches, Extended Release Capsules, Sublingual Films |
| Companies Covered | AstraZeneca Plc, Sanofi SA, Pfizer Inc., Bayer AG, Boehringer Ingelheim GmbH, Novartis AG, Merck & Co., Inc., Daiichi Sankyo Company, Limited, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antihypertensive Market Strategic Shifts & Innovations
The market is experiencing a definitive pivot from a reliance on single-agent monotherapy towards more sophisticated treatment strategies. This evolution prioritizes improved patient outcomes through combination drugs, novel delivery methods, and evidence-based prescribing practices.
Combination therapies, which co-formulate multiple drug classes like ACE Inhibitors and Beta Blockers into a single dosage form, enhance both efficacy and patient compliance. These single-pill combinations are being adopted rapidly in geriatric care and for patients with difficult-to-control hypertension. The approach is expanding into the primary treatment paradigm, challenging the traditional stepped-care model that begins with monotherapy.
The European Medicines Agency (EMA) is increasingly emphasizing the use of real-world evidence (RWE) for post-marketing surveillance and label expansions of cardiovascular drugs. This regulatory focus compels manufacturers to collect and analyze data from everyday clinical practice, supplementing traditional clinical trial results. Established drug classes with extensive long-term safety data are well-positioned, while novel agents face a higher burden to prove their value in diverse, real-world patient populations.
A notable shift in purchasing behavior is the move from simple volume-based procurement to value-based agreements, especially within large, integrated healthcare systems. This change disrupts the conventional fee-for-service sales channel, where prescribing decisions were less directly tied to long-term health outcomes. This trend is most pronounced in the United States and parts of Western Europe, where payers are beginning to link reimbursement to demonstrated blood pressure control.
Antihypertensive Market Segmentation
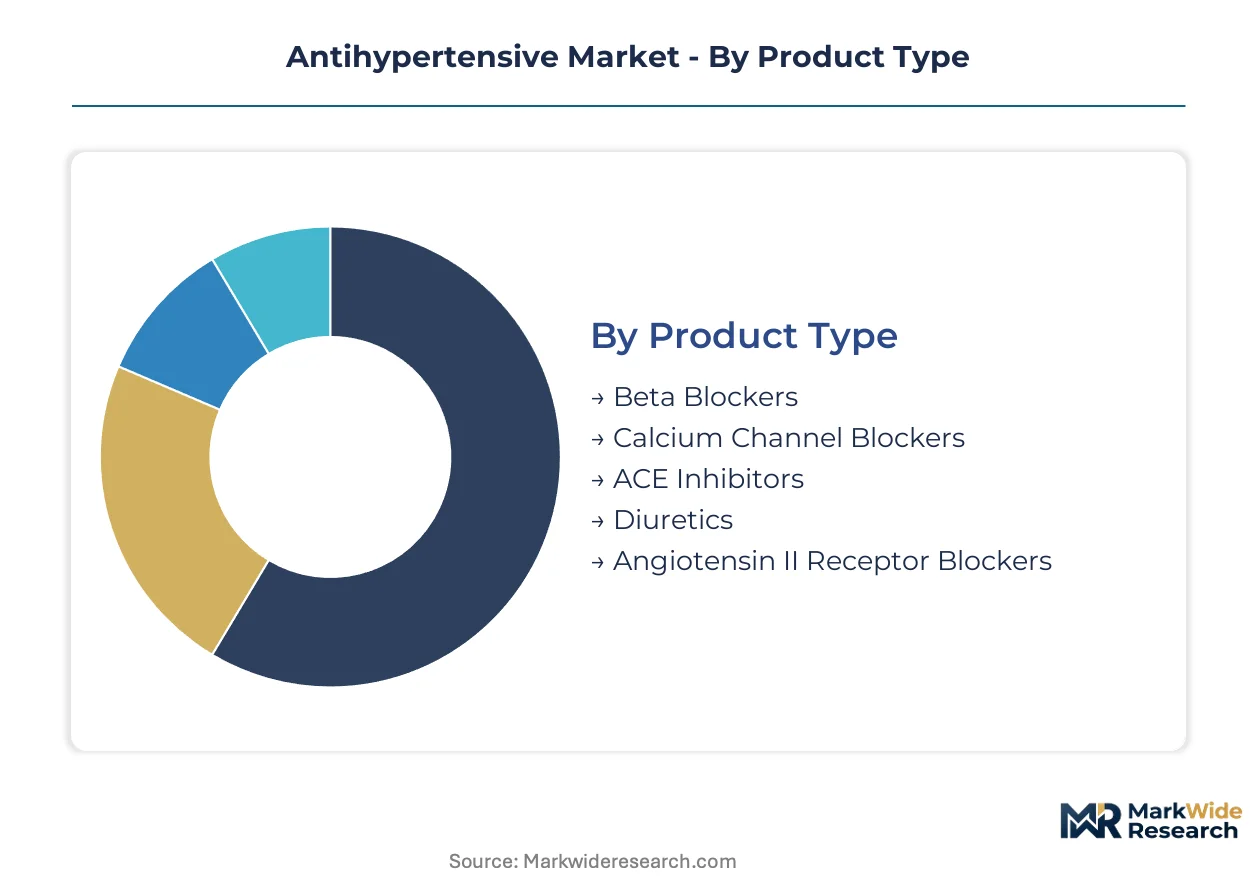
The Antihypertensive Market exhibits diverse patient needs and therapeutic approaches, necessitating a granular segmentation to understand demand patterns and innovation trajectories. Analyzing the market across product types, applications, end users, and delivery modes provides crucial insights into how pharmaceutical firms tailor their offerings. This segmentation highlights the specific patient populations and clinical settings driving growth within the broader antihypertensive landscape.
Product Type:
The spectrum of antihypertensive drug classes ranges from long-established, widely prescribed agents to more targeted, newer formulations, reflecting varying levels of therapeutic customization. Each class operates through distinct pharmacological mechanisms to achieve blood pressure control, addressing different patient profiles and comorbidities.
- ACE Inhibitors:These agents block the angiotensin-converting enzyme, leading to vasodilation and reduced blood volume. Demand concentrates in primary care settings across the United States and Europe, driven by their efficacy and established safety profiles in managing essential hypertension.
- Angiotensin II Receptor Blockers:These medications selectively block the AT1 receptor, offering an alternative for patients intolerant to ACE Inhibitors due to cough. Their market presence is strong in China and Japan, where patient adherence benefits from once-daily dosing.
- Beta Blockers:These drugs reduce heart rate and cardiac output, primarily used for hypertension with co-occurring conditions like angina or anxiety. Their use is widespread in European cardiology clinics.
- Calcium Channel Blockers:These agents relax blood vessels by blocking calcium entry into smooth muscle cells, effective for isolated systolic hypertension. India and Southeast Asia show significant demand for these cost-effective options.
- Diuretics:These medications increase sodium and water excretion, reducing blood volume and blood pressure. They remain a foundational therapy, particularly in community health centers.
Most installed capacity flows through ACE Inhibitors. Expansion is steepest in Angiotensin II Receptor Blockers.
Application:
The volume of treated patients varies significantly across different forms of hypertension, influencing drug development and market access strategies. Specific patient populations with distinct physiological origins for their high blood pressure require tailored diagnostic and therapeutic pathways.
- Primary Hypertension:This category encompasses essential hypertension, representing the vast majority of cases without an identifiable underlying cause. Demand for primary hypertension treatments is dominant globally, especially in aging populations in China.
- Pulmonary Hypertension:This severe condition involves high blood pressure in the arteries leading to the lungs, requiring specialized and often complex therapeutic regimens. Specialty hospitals in Germany and the US are key centers for its management.
- Secondary Hypertension:This form of high blood pressure results from an identifiable underlying condition, such as kidney disease or endocrine disorders. Diagnosis and treatment often occur in specialized clinics.
- Gestational Hypertension:This condition develops during pregnancy, posing risks to both mother and fetus, and requires careful management with specific drug choices. Obstetric units manage these cases.
- Renovascular Hypertension:Caused by narrowing of the arteries to the kidneys, this type often necessitates interventional procedures alongside medication. Nephrology clinics address these complex cases.
Primary Hypertension accounts for the largest patient volume. Pulmonary Hypertension demonstrates the highest per-patient expenditure.
End User:
Different healthcare settings cater to distinct patient cohorts and treatment complexities, influencing procurement patterns and the types of antihypertensive agents prescribed. Each end-user segment has unique requirements for drug formulation, administration, and patient education.
- Geriatric Care:This segment serves the elderly population, where polypharmacy and comorbidities are common, driving demand for simplified dosing regimens and combination therapies. Facilities in Japan and Italy prioritize ease of administration for their aging residents.
- Cardiology Clinics:These specialized outpatient centers manage complex cardiovascular conditions, including resistant hypertension, often prescribing advanced or combination therapies. Urban centers in the United States and France see high patient volumes.
- Specialty Hospitals:These institutions focus on specific medical conditions, often managing severe or rare forms of hypertension requiring intensive care or advanced diagnostics. Hospitals in the UK and Canada utilize a broad range of agents.
- Research Institutes:These entities conduct clinical trials and develop novel antihypertensive agents, influencing future treatment paradigms. Academic centers in Switzerland and the Netherlands are prominent in this area.
- Community Health Centers:These facilities provide accessible primary care services, focusing on prevention and management of common conditions in local populations. Rural areas in India and Brazil rely heavily on these centers.
Cardiology Clinics represent a significant prescribing volume. Geriatric Care facilities show the fastest adoption of fixed-dose combination products.
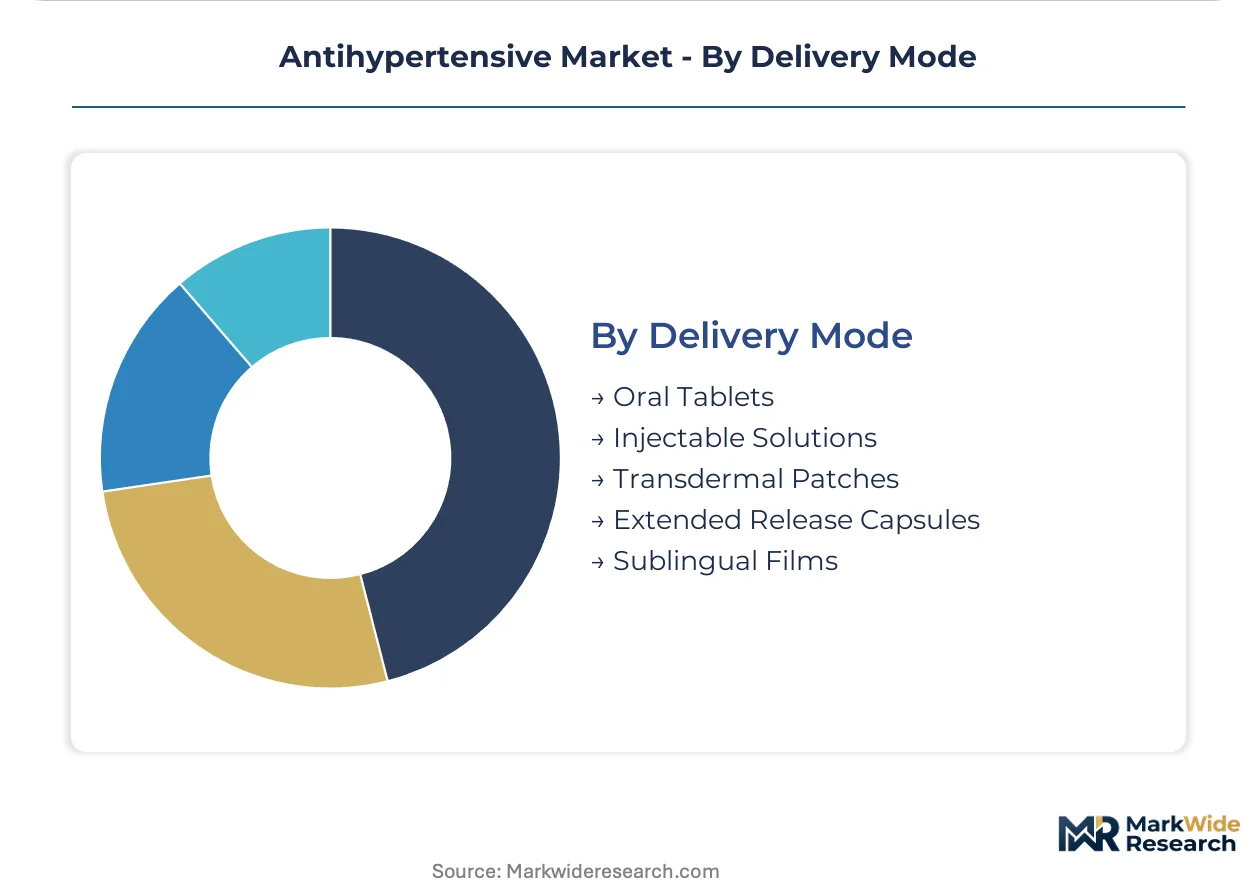
Delivery Mode:
The method of drug administration directly impacts patient adherence, therapeutic efficacy, and suitability for specific clinical scenarios. Innovations in drug delivery aim to improve patient experience and clinical outcomes, particularly for chronic conditions.
- Oral Tablets:These represent the most common and convenient form of administration for long-term management of hypertension. Global demand for oral tablets remains consistently high due to their ease of use and cost-effectiveness.
- Extended Release Capsules:These formulations release the active pharmaceutical ingredient over an extended period, reducing dosing frequency and improving patient compliance. Geriatric care settings in Germany and Canada favor these for improved adherence.
- Injectable Solutions:Reserved for acute hypertensive crises or specific inpatient settings, these provide rapid onset of action. Specialty hospitals utilize injectables for critical care patients.
- Transdermal Patches:These offer continuous drug delivery through the skin, beneficial for patients with dysphagia or poor gastrointestinal absorption. Niche patient populations in the US and Australia use these.
- Sublingual Films:These rapidly dissolving films allow for quick absorption through the oral mucosa, suitable for rapid action or patients with swallowing difficulties. Emergency care units might employ sublingual films.
Oral Tablets dominate the market by volume. Extended Release Capsules demonstrate the highest growth potential for patient adherence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global antihypertensive market exhibits a structural regulatory arbitrage, where the cost of compliance and market access pathways influence manufacturing and distribution strategies across different continents. This dynamic incentivizes pharmaceutical firms to balance stringent approval processes in developed economies against the need for affordable access in high-demand emerging markets. Such a landscape shapes investment in novel therapies and generic formulations.
United States
Demand for novel combination therapies is high, driven by an aging population and complex chronic disease management. The US FDA's accelerated approval pathways facilitate market entry for innovative antihypertensive agents. Research and development clusters in Boston and San Francisco continue to drive pharmaceutical innovation.
China
A large and rapidly aging population fuels significant demand for primary hypertension treatments and long-term pharmacological management. China's NMPA has streamlined drug registration for essential medicines, increasing accessibility. Major pharmaceutical manufacturing hubs in the Yangtze River Delta are expanding capacity for complex generics.
Germany
European cardiology clinics in Germany show widespread use of Beta Blockers and advanced therapies for co-occurring conditions. The EMA's emphasis on real-world evidence influences post-marketing surveillance and label expansions for cardiovascular drugs. Pharmaceutical research in cities like Berlin and Munich focuses on innovative treatments and clinical trials.
India
Generic drug manufacturing in India is pivoting towards complex combination therapies, creating competitive pressures for established firms. The PLI scheme supports domestic production of active pharmaceutical ingredients, reducing supply chain dependency. Community health centers in rural areas rely heavily on affordable, accessible medications.
Japan
Patient adherence benefits from once-daily dosing of Angiotensin II Receptor Blockers, making them strong in the Japanese market. Japan's PMDA enforces specific guidelines for drug registration and pharmacovigilance, ensuring product safety and efficacy. Geriatric care facilities in Tokyo and Osaka prioritize ease of administration for their aging residents.
Antihypertensive Market Key Industry Players
United States producers anchor one tier; Indian specialists hold another, creating a tiered competitive structure within the antihypertensive market. This landscape features established pharmaceutical firms with extensive R&D pipelines alongside generic manufacturers focusing on cost-effective alternatives. Archetypes include innovation-driven majors, generic-focused specialists, and niche players in novel delivery systems. Portfolio diversification and strategic partnerships are dominant competitive moves for market participants.
Within the innovation-driven major archetype, AstraZeneca Plc and Novartis AG exemplify substantial investment in next-generation therapies, maintaining their market positions through strong R&D pipelines and specialized innovative treatments. Pfizer Inc. occupies a position among global pharmaceutical firms, leveraging its extensive distribution network for established brands across diverse therapeutic areas. These companies collectively anchor the premium segment of the market, focusing on lifecycle management of existing blockbuster drugs while navigating stringent regulatory landscapes.
| Leading Market Players |
|---|
| AstraZeneca Plc |
| Sanofi SA |
| Pfizer Inc. |
| Bayer AG |
| Boehringer Ingelheim GmbH |
| Novartis AG |
| Merck & Co., Inc. |
| Daiichi Sankyo Company, Limited |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
The Active Pharmaceutical Ingredient (API) price index, influenced by manufacturing costs in China and India, cascades through the antihypertensive market, shaping the pricing tiers for both innovative and generic drug formulations. This dynamic creates a structural tension, where cost efficiencies in raw material sourcing directly impact final drug pricing across different geographies.
Pricing Analysis
Distributor margins significantly influence the final cost of antihypertensive drugs, particularly for established generic formulations in emerging markets. Value-based agreements are gaining traction in developed economies, linking reimbursement to demonstrated patient outcomes rather than volume alone. Price differentiation stems from brand premium for novel agents and the regulatory approval status by bodies like the US FDA. Pricing softness runs through generic segments due to intense competition from Indian manufacturers. Community health centers in India and Brazil exhibit the highest price sensitivity, prioritizing cost-effective therapeutic options.
Supply Chain Analysis
Skilled workforce availability in pharmaceutical manufacturing hubs across India and China underpins the global supply chain for antihypertensive agents. Geographic supply concentration is pronounced in India for generic active pharmaceutical ingredients and in China for various chemical intermediates. The market relies heavily on a consistent supply of specific APIs, creating a single-source vulnerability for older drug classes. Regulatory restrictions, such as export controls during health crises, represent a structural risk to global distribution. Downstream distribution runs through extensive global networks for major pharmaceutical firms and localized channels for generic specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, where lower manufacturing costs in India for complex generics contrast sharply with the high R&D and stringent approval costs in the United States.
For Market Incumbents:
Hedge against patent cliff erosion by accelerating investment in novel combination therapies and advanced delivery systems. Defend market share through robust lifecycle management of existing blockbuster drugs, emphasizing real-world evidence for label expansions with the European Medicines Agency (EMA). Leverage extensive global distribution networks to maintain brand presence and counter generic competitive pressures. Strategic partnerships with digital health platforms can create value-added services around remote patient monitoring.
For New Entrants and Emerging Players:
Contract research organizations (CROs) can partner with new entrants to navigate complex regulatory pathways, particularly for fixed-dose combinations. Target underpenetrated regions of Southeast Asia and Africa, where significant untreated populations exist and demand for affordable, effective treatments is high. Focus on niche delivery mechanisms like transdermal patches or sublingual films to cater to specific patient populations such as those with dysphagia. A go-to-market angle emphasizing improved patient adherence through simplified dosing regimens offers a strong value proposition.
For Investors and Strategic Acquirers:
Asymmetric upside sits with firms specializing in next-generation therapies or innovative drug delivery technologies. The long-term viability of the antihypertensive market is secured by aging global demographics and the chronic nature of hypertension. Target acquisition candidates include companies with strong R&D pipelines in cardiovascular disease or those developing advanced formulation technologies for extended-release products. The signal to watch is the adoption rate of value-based procurement models by large integrated healthcare systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate Novel Combination Therapy Development | Enhances patient adherence and therapeutic efficacy, addressing complex chronic disease management. |
| Expand Digital Health Integration | Creates value-added services for remote monitoring and improves patient engagement. |
| Invest in Advanced API Manufacturing | Reduces supply chain dependency and mitigates price volatility for critical raw materials. |
| Target Untreated Populations in Emerging Markets | Unlocks significant long-term growth by addressing unmet medical needs in high-prevalence regions. |
| Strengthen Regulatory Affairs Capabilities | Navigates diverse global approval protocols, facilitating market access for new formulations. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, extensive secondary research, and proprietary database analytics — were reconciled to construct a robust market view. This approach involved engaging pharmaceutical R&D executives, regulatory affairs specialists, hospital formulary managers, and procurement leads across key geographies. Secondary data sources included US FDA filings, European Medicines Agency (EMA) submissions, China's NMPA guidelines, and specialized industry association reports, ensuring comprehensive market intelligence. Bottom-up and top-down triangulation validated market size and growth projections.
Historical market performance was cross-referenced with expert panel input to develop the forecast framework across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, delivery mode, and regional regulatory clusters. Compound annual growth rates were derived from a weighted average of historical trends and projected market dynamics, factoring in demographic shifts, particularly aging populations, and anticipated regulatory approval rates for novel therapies. This ensured a balanced perspective on future market trajectory.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to major patent expirations, unforeseen regulatory changes, and significant supply chain disruptions. Forecasts reflect assumptions documented through stakeholder consultations and secondary data analysis. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Vasculitis Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Angina Market