
 Life Support Systems Market | 2026-2036
Life Support Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Life Support Systems Market Foresight
Market Context
Critical care nursing shortages and biomedical engineering talent gaps are rotating hospital procurement priorities toward systems with lower training burdens and automated safety protocols. Philips leverages its integrated monitoring-to-ventilation ecosystem to sustain installed-base loyalty across tertiary care networks. Drägerwerk AG & Co. KGaA anchors its position through German-engineered anesthesia and ventilation platforms that dominate European hospital standards. Hamilton Medical specializes in adaptive ventilation algorithms that differentiate its ICU ventilators in high-acuity settings.
Technical Definition and Segment Structure
Life support systems encompass electromechanical devices that substitute or supplement failing organ functions, with ventilators delivering precise tidal volumes at 2-80 mL/kg and ECMO circuits maintaining blood flow rates of 50-150 mL/kg/min through membrane oxygenators. These systems serve primarily to sustain patients through reversible organ failure, surgical intervention, or bridge-to-transplant periods in intensive care and operating room environments. Mechanical ventilation technology leads product type revenue due to pandemic-era fleet expansions and recurring consumables demand, while extracorporeal membrane oxygenation is the fastest-growing technology segment as cardiac and respiratory failure protocols widen eligibility. Hospitals capture the dominant end user share through centralized capital budgets, though home healthcare providers are gaining traction for long-term ventilator weaning and nocturnal respiratory support programs.
Regulatory Framework and Outlook
FDA premarket notification requirements under 21 CFR 870 for cardiovascular devices and EPA energy efficiency standards for hospital equipment shape product development timelines and compliance costs for manufacturers. EMA Medical Device Regulation (MDR) and ISO 80601-2-80 ventilation-specific safety standards are forcing design modifications and clinical evidence packages that extend European market entry cycles. Stakeholders must monitor evolving software-as-a-medical-device classifications for AI-driven ventilator adjustments and remote monitoring platforms that blur traditional hardware regulatory boundaries.
Market Dynamics
Intensive care infrastructure expansion is colliding with biomedical engineering talent scarcity, forcing hospital procurement committees toward automated ventilation platforms and remote monitoring architectures that reduce bedside specialist dependency.
Growth Catalysts
- ICU capacity mandates:National health ministries in Germany, China, and the United States are mandating per-capita ventilator stockpiles and ECMO circuit reserves following pandemic-era shortages.
- ISO 80601-2-80 harmonization:Ventilation-specific safety standards are converging across FDA and EMA jurisdictions, streamlining multinational product registrations for manufacturers with compliant platforms.
- Aging demographics:Cardiac and respiratory failure incidence in populations over 65 is expanding the addressable patient base for mechanical circulatory support in tertiary hospitals.
Market Restraints
- Membrane oxygenator supply concentration:ECMO circuit production depends on specialized hollow-fiber membrane suppliers concentrated in Japan and Germany, creating single-source vulnerability.
- EMA MDR clinical evidence requirements:Extended post-market surveillance obligations and notified body capacity constraints are stretching European market entry timelines to 18-24 months.
- Biocompatibility testing costs:ISO 10993 cytotoxicity and hemolysis validation for blood-contacting surfaces adds substantial fixed cost per product iteration.
Strategic Opportunities
- Home-based ventilator weaning:Long-term acute care hospitals and durable medical equipment providers are building respiratory therapy programs for post-ICU patients, opening ambulatory revenue streams.
- AI-driven closed-loop ventilation:Machine learning algorithms that auto-adjust pressure support and PEEP settings are converging with cloud telemetry to enable predictive weaning protocols.
- Indian hospital infrastructure:Government-funded critical care expansion under the Ayushman Bharat scheme is creating procurement windows for mid-acuity ventilation platforms in tier-2 cities.
Industry Challenges
- Perfusionist and ECMO specialist shortages:Extracorporeal circuit management requires certified clinicians whose training pipelines operate at 30-40% of replacement rates needed for projected demand.
- Legacy device interoperability:Hospital IT networks must integrate new ventilator data streams with existing EMR architectures, forcing middleware development and cybersecurity validation.
Report Scope
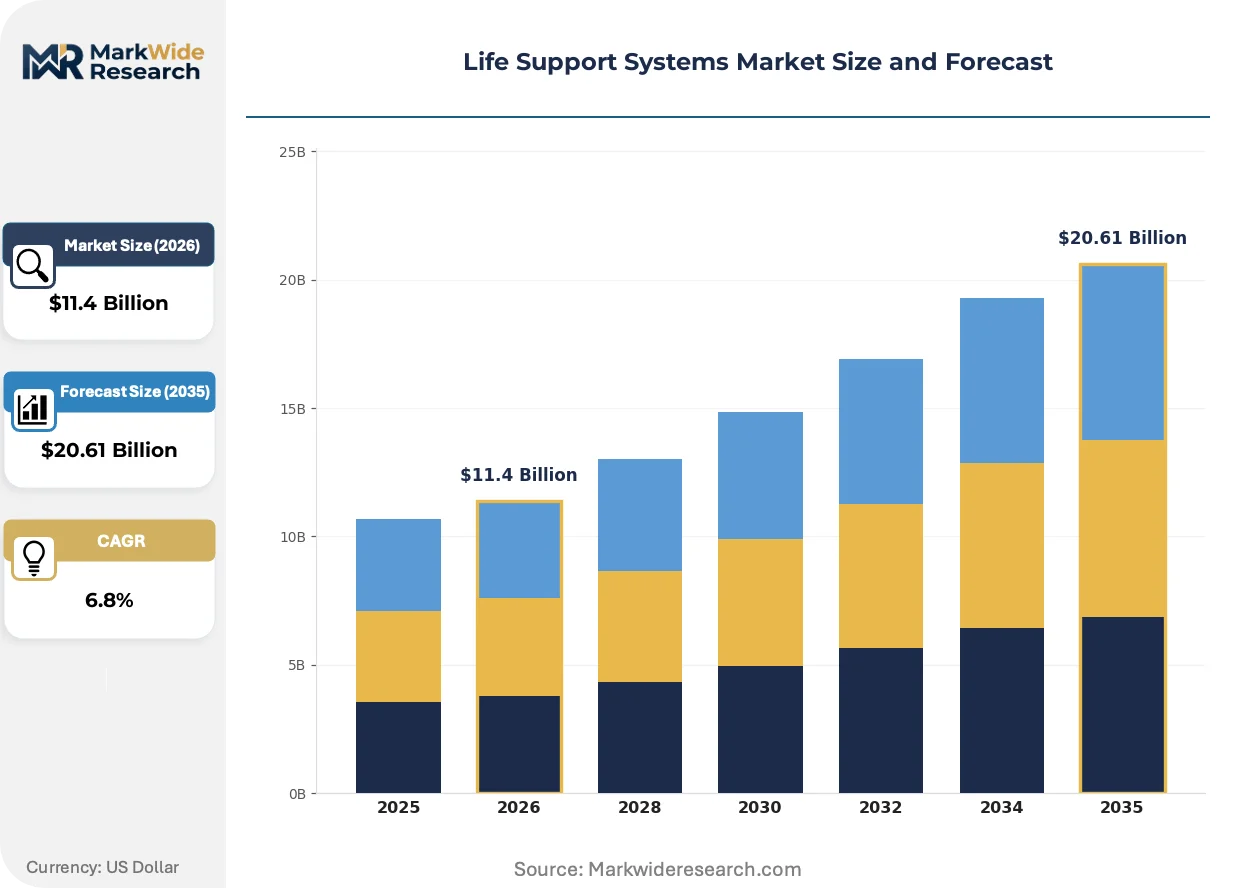
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Support Systems Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Infusion Pumps, Heart-Lung Machines, Dialysis Machines Technology: Mechanical Ventilation, Extracorporeal Membrane Oxygenation, Continuous Renal Replacement Therapy, Advanced Monitoring Systems End User: Hospitals, Rehabilitation Centers, Emergency Medical Services, Home Healthcare Providers Delivery Mode: In-Hospital, Outpatient Services, Telehealth Platforms, Emergency Response Units |
| Companies Covered | Philips, GE Healthcare, Medtronic, Drägerwerk AG & Co. KGaA, Getinge AB, Hamilton Medical, Baxter, ZOLL Medical, ResMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Support Systems Market Shifts & Advancements
Software-defined functionality is displacing hardware-differentiated competition across ventilation and circulatory support platforms, compressing product development cycles and reshaping service revenue models.
Adaptive ventilation algorithms that synchronize breath delivery with patient effort are fragmenting the traditional volume-control versus pressure-control product taxonomy. High-acuity ICUs in the United States and Germany are adopting these platforms at replacement-cycle pace. This technology is fragmenting vendor lock-in by enabling plug-and-play compatibility with third-party monitoring ecosystems.
EMA Medical Device Regulation Article 10 clinical evaluation requirements are forcing manufacturers to generate real-world evidence through post-market clinical follow-up studies. Design dossier preparation costs have risen substantially for cardiovascular device classifications. ECMO systems and high-frequency ventilators face the most stringent scrutiny, with several manufacturers withdrawing legacy products rather than re-certifying.
Hospital procurement committees are consolidating vendor relationships through integrated monitoring-to-ventilation contracts that bundle hardware, consumables, and remote technical support. Group purchasing organizations are displacing individual hospital negotiations in the United States, while centralized procurement in China's provincial health commissions is compressing price points for domestic and multinational suppliers alike. This consolidation is most visible in tertiary hospital networks across Guangdong, Jiangsu, and Shandong provinces.
Life Support Systems Market Segmentation
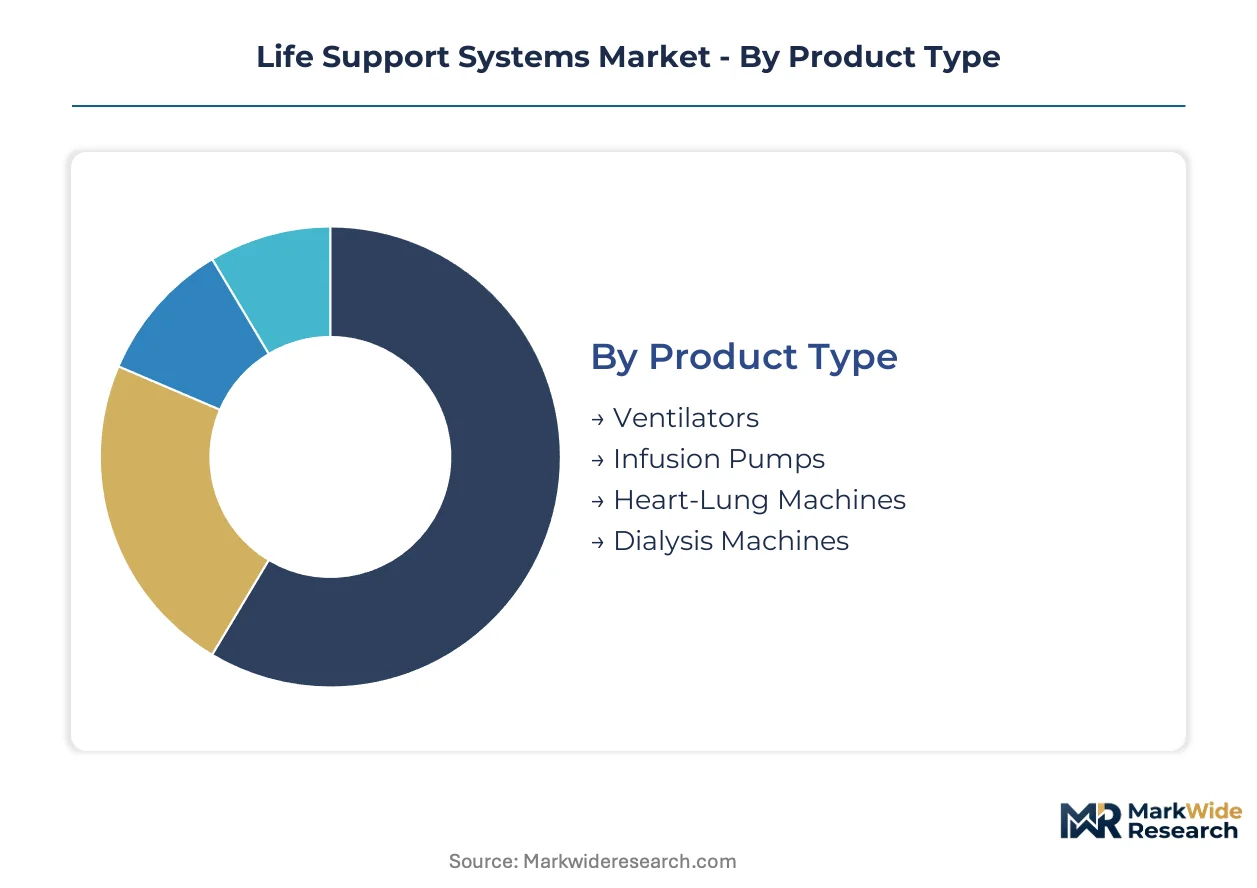
Life support systems traverse sharply divergent procurement channels depending on acuity level and reimbursement structure. High-acuity equipment flows through centralized hospital capital budgets, while chronic support devices increasingly reach patients via durable medical equipment distributors and telehealth-integrated home care networks.
Product Type:
Ventilators dominate hospital procurement volumes through group purchasing organization contracts, whereas dialysis machines generate recurring consumables revenue through outpatient service networks.
- Ventilators:Electromechanical systems delivering precise tidal volumes from 2-80 mL/kg with pressure-controlled, volume-controlled, and adaptive modes. Demand concentrates in tertiary ICU networks across the United States, Germany, and China where pandemic-era stockpile mandates have institutionalized replacement cycles. Automated weaning protocols and remote telemetry integration are shifting procurement criteria toward software-defined platforms.
- Dialysis Machines:Hemodialysis and peritoneal systems performing solute clearance and fluid removal through semipermeable membranes. Home dialysis programs in the United States and Japan are expanding ambulatory placements, though in-center hemodialysis retains dominant reimbursement economics.
- Infusion Pumps:Programmable volumetric and syringe pumps for precise medication delivery in critical care settings. Smart pump interoperability with EMR systems is becoming a non-negotiable procurement specification.
- Heart-Lung Machines:Cardiopulmonary bypass systems maintaining systemic perfusion during open-heart surgery. Cardiac surgery volume concentration in metropolitan medical centers limits addressable site count.
By volume, ventilators lead. By growth pace, dialysis machines for home settings are climbing fastest.
Technology:
Cost tier stratification separates capital-intensive ECMO platforms from consumables-heavy renal replacement modalities, with mechanical ventilation occupying the mid-tier hardware-plus-consumables hybrid position.
- Mechanical Ventilation:Positive-pressure systems with microprocessor-controlled breath delivery, spanning invasive and non-invasive interfaces. High-acuity ICUs in Germany and the United States are replacing legacy volume-control platforms with adaptive algorithms that synchronize with patient effort.
- Extracorporeal Membrane Oxygenation:Circuit-based cardiac and respiratory support maintaining blood flow rates of 50-150 mL/kg/min through membrane oxygenators. Cardiac and respiratory failure protocol expansions in Chinese tertiary hospitals are accelerating centrifugal pump and oxygenator demand.
- Continuous Renal Replacement Therapy:Slow, continuous blood purification for hemodynamically unstable patients in ICU settings. CRRT adoption tracks sepsis and acute kidney injury incidence in aging populations.
- Advanced Monitoring Systems:Integrated platforms combining hemodynamic, respiratory, and neurological parameter tracking with predictive analytics. Cloud telemetry and AI-driven alarm management are differentiating next-generation offerings.
Mechanical ventilation retains the largest installed base. ECMO technology is gaining share fastest among high-acuity modalities.
End User:
Customer type determines service intensity and contract structure, with hospitals demanding 24/7 biomedical engineering support while home healthcare providers prioritize patient training and remote monitoring capabilities.
- Hospitals:Tertiary medical centers, community hospitals, and long-term acute care facilities with centralized capital equipment budgets. Chinese provincial health commissions and United States group purchasing organizations are consolidating vendor relationships through bundled monitoring-to-ventilation contracts.
- Home Healthcare Providers:Durable medical equipment suppliers and respiratory therapy services managing long-term ventilator weaning and nocturnal support. Reimbursement expansion for home-based chronic respiratory failure is opening ambulatory revenue streams.
- Rehabilitation Centers:Post-acute facilities focusing on ventilator weaning and functional recovery. These sites favor mid-acuity platforms with lower training burdens.
- Emergency Medical Services:Pre-hospital transport ventilators and portable circulatory support for inter-facility transfers. Ruggedization and battery autonomy drive procurement specifications.
Hospitals account for dominant equipment volume. Home healthcare providers are expanding most quickly as reimbursement shifts toward ambulatory settings.
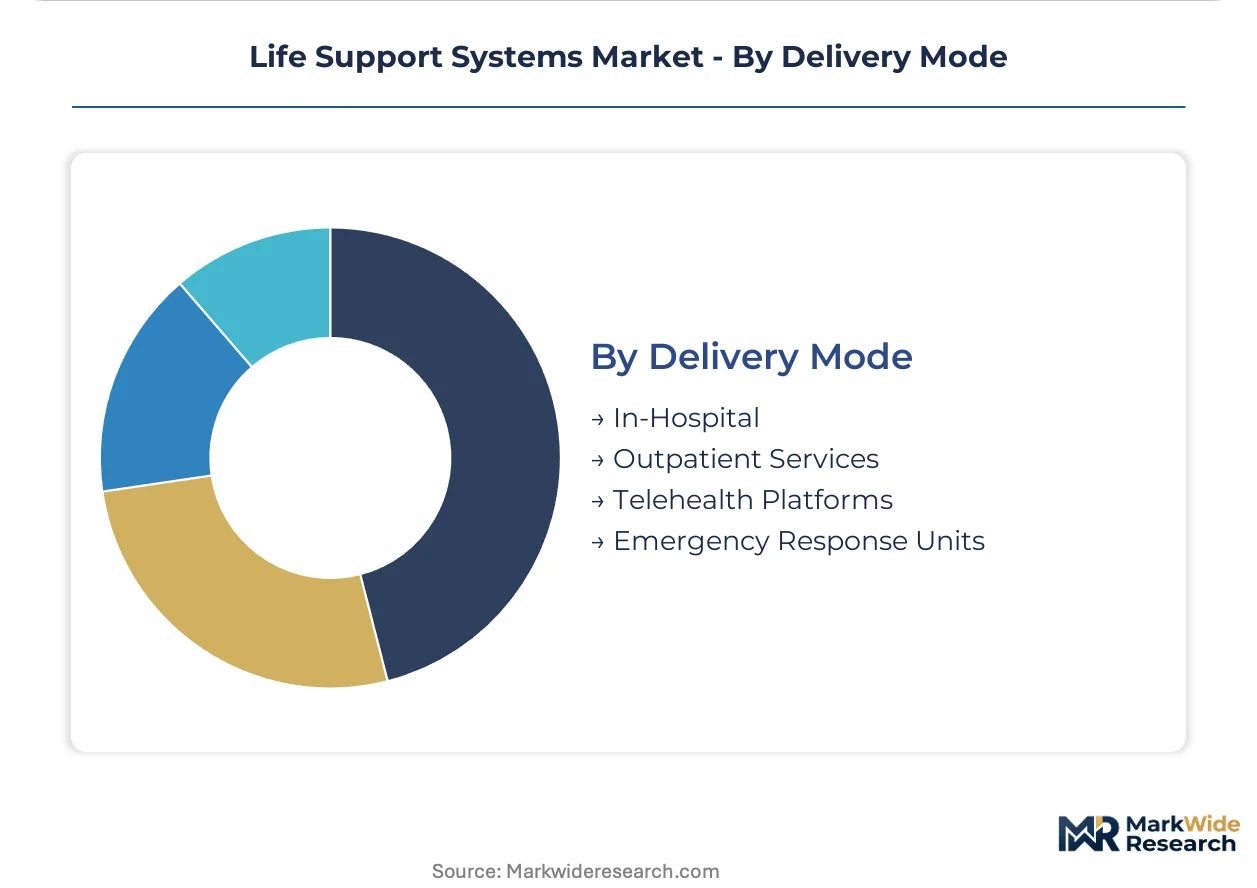
Delivery Mode:
Application context shapes regulatory pathway and service model, with in-hospital deployments facing FDA 510(k) or EMA MDR premarket scrutiny while telehealth platforms navigate emerging software-as-a-medical-device classifications.
- In-Hospital:Operating room, ICU, and emergency department deployments with continuous biomedical engineering coverage. German-engineered anesthesia and ventilation platforms dominate European hospital standards through integrated safety protocols.
- Telehealth Platforms:Remote monitoring architectures enabling predictive weaning protocols and specialist consultation across distributed sites. FDA and EMA software-as-a-medical-device frameworks are clarifying regulatory boundaries for cloud-connected ventilator adjustments.
- Outpatient Services:Dialysis centers, infusion clinics, and sleep disorder facilities with scheduled technical support. These sites prioritize equipment reliability over cutting-edge feature sets.
- Emergency Response Units:Mobile intensive care units and air ambulance services requiring ruggedized, battery-powered systems. Weight and footprint constraints limit platform selection.
In-hospital delivery retains predominant value concentration. Telehealth platforms are expanding most rapidly as health systems address specialist scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German hospitals prioritize integrated anesthesia-to-ventilation ecosystems, while Chinese procurement concentrates on domestic manufacturing scale and provincial stockpile mandates. United States demand flows through group purchasing organizations toward automated platforms with remote telemetry.
United States
Hospital consolidation into mega-systems such as HCA and CommonSpirit Health drives centralized ventilator procurement through group purchasing organizations. FDA 510(k) premarket notification pathways under 21 CFR 870 shape cardiovascular device entry timelines. The Cleveland Clinic and Mayo Clinic networks anchor high-acuity ECMO adoption in the Midwest corridor.
Germany
Tertiary hospital networks in Bavaria and North Rhine-Westphalia maintain per-capita ventilator stockpiles exceeding EU averages. EMA Medical Device Regulation Article 10 clinical evaluation requirements extend market entry cycles for new cardiovascular platforms. Drägerwerk AG & Co. KGaA anchors German-engineered anesthesia and ventilation dominance through integrated safety protocols.
China
Provincial health commissions in Guangdong, Jiangsu, and Shandong centralize procurement for mid-acuity ventilation platforms under pandemic-era ICU capacity mandates. NMPA medical device registration pathways prioritize domestic manufacturing capacity expansion. Beijing-Tianjin-Hebei hospital clusters drive centrifugal pump and membrane oxygenator demand for cardiac failure protocols.
Japan
Aging demographics above 65 expand chronic respiratory failure incidence and home ventilator weaning programs. PMDA pharmaceutical and medical device agency standards enforce rigorous biocompatibility validation for blood-contacting surfaces. Tokyo-Osaka metropolitan hospital networks concentrate high-frequency ventilator and CRRT platform adoption.
India
Government-funded critical care expansion under the Ayushman Bharat scheme opens procurement windows for mid-acuity ventilation in tier-2 cities. CDSCO medical device registration requirements are harmonizing with ISO 80601-2-80 ventilation safety standards. Maharashtra and Karnataka hospital networks lead private-sector ICU infrastructure investment.
Life Support Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in life support systems. Philips and GE Healthcare occupy the integrated tier through monitoring-to-ventilation ecosystems that lock in tertiary hospital networks. Specialists such as Hamilton Medical and ZOLL Medical differentiate through adaptive algorithms and emergency transport platforms. Competitive moves concentrate on strategic partnerships for AI-driven closed-loop ventilation and backward integration into membrane oxygenator supply.
Within the integrated systems tier, Philips and GE Healthcare exemplify platform consolidation through bundled hardware-consumables-service contracts. Drägerwerk AG & Co. KGaA anchors German-engineered anesthesia and ventilation standards across European hospital procurement. Hamilton Medical occupies the adaptive ventilation specialist position with algorithmic platforms that synchronize breath delivery with patient effort.
| Leading Market Players |
|---|
| Philips |
| GE Healthcare |
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| Getinge AB |
| Hamilton Medical |
| Baxter |
| ZOLL Medical |
| ResMed |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for membrane oxygenators and centrifugal pumps lock in supply access for ECMO manufacturers while anchoring price visibility across multi-year hospital procurement cycles in Germany, China, and the United States.
Pricing Analysis
Contract-based long-term offtake dominates high-acuity equipment procurement, with pricing stratifying across FDA-cleared premium tiers, CE-marked standard platforms, and economy-grade systems for emerging markets. Price differentiation rests on ISO 80601-2-80 certification level and bundled remote technical support. Cost compression in mid-acuity ventilation is intensifying because Chinese provincial health commissions centralize purchasing. Home healthcare providers exhibit highest price sensitivity; tertiary ICU networks prioritize algorithmic capability over unit cost.
Supply Chain Analysis
Germany and Japan anchor hollow-fiber membrane oxygenator production, while China scales domestic centrifugal pump manufacturing under NMPA registration pathways. Critical inputs draw from specialized polymer suppliers for biocompatible surfaces, precision-machined pump housings, and medical-grade silicone tubing. Single-source vulnerability concentrates in Japanese membrane suppliers. Distribution runs through group purchasing organizations in the United States and provincial health commissions in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perfusionist and ECMO specialist training pipelines operate at 30-40% of replacement rates, constraining circuit management capacity and amplifying returns for automation-capable platforms.
For Market Incumbents: Secure backward integration into membrane oxygenator supply to mitigate Japanese supplier concentration risk. Lock hospital system partnerships through bundled monitoring-to-ventilation contracts that embed AI-driven weaning protocols, raising switching costs against adaptive algorithm specialists. For New Entrants and Emerging Players: Anchor in Indian tier-2 city hospitals under Ayushman Bharat infrastructure expansion, where mid-acuity ventilation demand outpaces established vendor coverage. Target telehealth-integrated home weaning programs as reimbursement shifts toward ambulatory respiratory support. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined ventilation platforms with FDA 510(k) clearance for AI-driven closed-loop control, positioned for sustained relevance as hardware commoditization accelerates. Watch EMA MDR notified body capacity constraints as inflection signal for European market entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Ventilation | Accelerates market entry for machine learning-driven pressure support algorithms under 21 CFR 870. |
| CE Marking Pathway under EMA MDR | Extends European commercialization timelines but secures Article 10 clinical evaluation compliance. |
| Hospital System Partnership | Locks multi-year consumables revenue through integrated monitoring-to-ventilation contracts. |
| Software Companion Development | Enables predictive weaning protocols that reduce bedside specialist dependency in ICU settings. |
| Reimbursement Strategy for Home Ventilation | Captures ambulatory revenue streams as CMS and provincial programs expand chronic respiratory coverage. |
Research Methodology
Desk research of FDA 510(k) filings, EMA MDR design dossiers, hospital procurement databases, and GPO contract archives preceded structured interviews with ICU clinicians, biomedical engineers, hospital purchasing committee chairs, and perfusionist training program directors. Secondary validation drew from ISO 80601-2-80 technical standards, CMS Medicare reimbursement data, and NMPA registration disclosures. Bottom-up unit economics and top-down market sizing underwent iterative triangulation.
Variance decomposition across product type, technology modality, end-user facility tier, and delivery mode shaped the analytical framework throughout the projection horizon. CAGRs derived from installed-base replacement cycles, pandemic-era stockpile mandate trajectories, and aging-demography-driven acute kidney injury incidence curves. ECMO circuit demand and adaptive ventilation algorithm adoption velocity served as primary forecast inputs.
Material uncertainties — regulatory reclassification of AI-driven ventilator adjustments, notified body capacity bottlenecks under EMA MDR, and membrane oxygenator supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about clinician training pipeline expansion and reimbursement stability for home-based respiratory support. Recalibration cycles align with material shifts in FDA software-as-a-medical-device guidance and provincial procurement centralization in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Global Microtome Market
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Global Surgical Lights Market