
 Heart Block Therapeutics Market | 2026-2036
Heart Block Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Block Therapeutics Market Foresight
Lead-free electrode materials are pivoting pacemaker construction away from traditional platinum-iridium alloys, reducing long-term corrosion risks and lowering raw material volatility. Medtronic leverages vertically integrated manufacturing to control leadless pacemaker supply chains from wafer to finished device. Abbott Laboratories anchors its position through specialized catheter-delivery systems that enable minimally invasive implantation. Boston Scientific Corporation competes on R&D intensity in subcutaneous ICD platforms that eliminate transvenous leads entirely.
Heart block therapeutics encompass devices and pharmacological agents that restore or maintain atrioventricular conduction, with implantable pacemakers delivering electrical impulses at programmable rates between 30 and 180 beats per minute to compensate for failed native conduction. The primary purpose spans acute stabilization in post-myocardial infarction settings through permanent rhythm management in chronic degenerative conduction disease. Implantable pacemakers dominate value generation due to recurring battery replacement cycles and proprietary lead compatibility ecosystems that lock in long-term service revenue. Remote monitoring represents the fastest-expanding technology segment as cellular-enabled home transmission reduces in-person clinic burden while capturing arrhythmia burden data for reimbursement documentation.
The FDA premarket approval process and ISO 14155 clinical investigation standards govern device safety validation, with FDA breakthrough device designation compressing review timelines for novel conduction-system pacing approaches. The European Medical Device Regulation imposes stricter post-market surveillance and unique device identification requirements that elevate compliance costs for multi-jurisdiction manufacturers. Stakeholders must monitor evolving CMS national coverage determinations for conduction system pacing and His-bundle pacing modalities, as reimbursement parity with conventional right ventricular pacing will determine whether specialized catheter investments achieve commercial viability.
Market Dynamics
The transition from transvenous to leadless and conduction-system pacing architectures is compressing service revenue models while elevating upfront device costs, forcing manufacturers to restructure pricing around long-term outcomes rather than replacement cycles.
Growth Catalysts
- Cellular-enabled remote monitoring:Home-based arrhythmia transmission reduces clinic visit burden while generating reimbursable data streams for electrophysiology practices.
- FDA breakthrough device designation:Accelerated review pathways for His-bundle pacing and left bundle branch pacing catheters compress time-to-market for novel conduction-system approaches.
- Aging demographics in developed economies:Expanding Medicare-eligible populations in the United States drive demand for permanent pacemaker implantation in degenerative conduction disease.
Market Restraints
- Platinum-iridium alloy dependency:Traditional electrode materials expose manufacturers to precious metal price volatility and supply concentration in South African and Russian mining operations.
- European Medical Device Regulation compliance costs:Stricter post-market surveillance and unique device identification requirements elevate administrative burdens for multi-jurisdiction manufacturers.
- Lead extraction complexity:Transvenous lead removal procedures carry procedural mortality risks that deter upgrade decisions and extend legacy device lifecycles.
Strategic Opportunities
- Conduction-system pacing reimbursement parity:CMS national coverage determination expansion for His-bundle pacing would validate specialized catheter investments.
- Subcutaneous ICD-leadless pacemaker convergence:Device miniaturization enables combined rhythm management platforms without transvenous hardware.
- India's underserved electrophysiology infrastructure:Underpenetrated cardiac catheterization laboratory networks create first-mover positioning for training-intensive conduction-system techniques.
Industry Challenges
- Electrophysiologist training pipeline constraints:Conduction-system pacing requires specialized anatomical expertise that outpaces fellowship program expansion.
- Legacy device ecosystem lock-in:Proprietary lead compatibility standards complicate patient migration to alternative manufacturer platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Block Therapeutics Market |
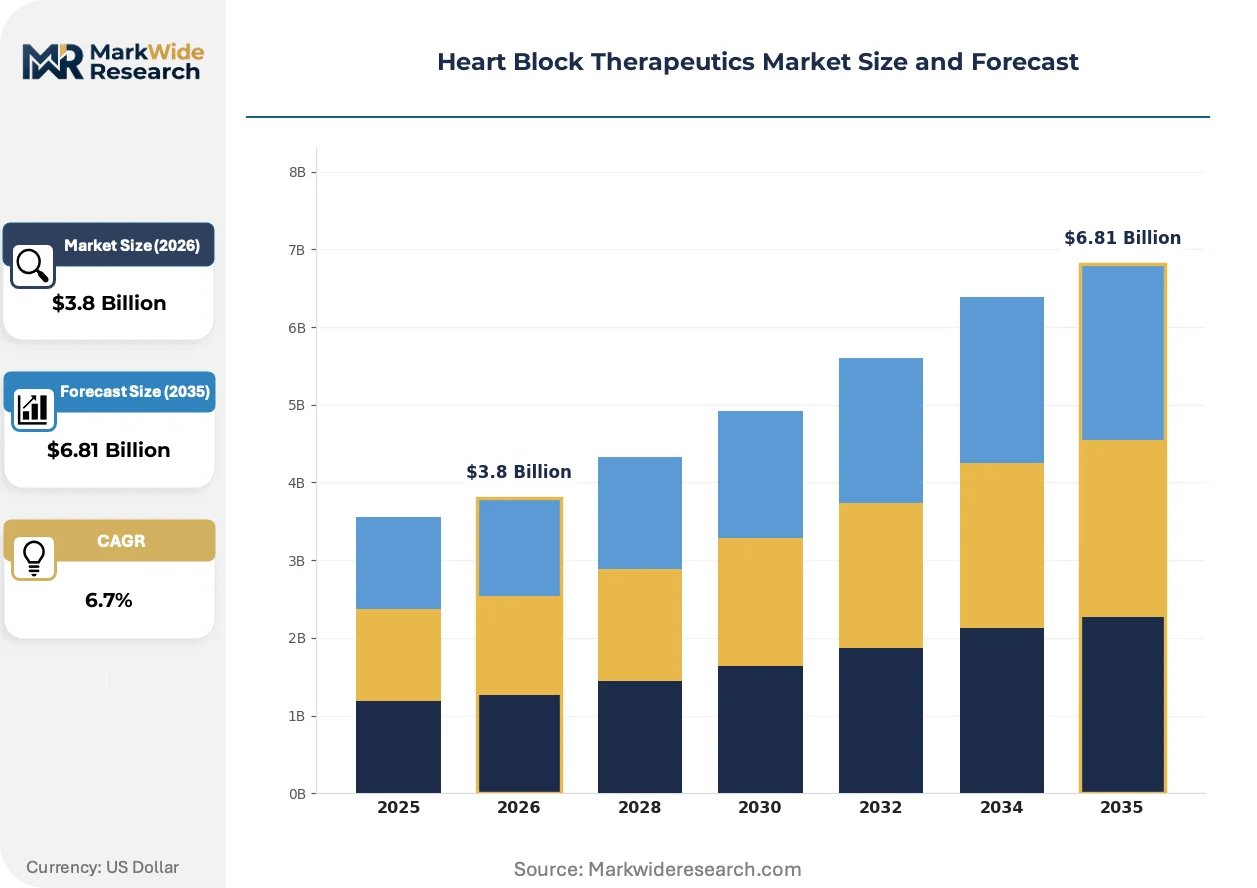
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Pacemakers, External Pacemakers, Medications, Therapies Technology: Biochemical Therapy, Electrical Stimulation, Telemedicine, Remote Monitoring Application: Cardiology Clinics, Hospitals, Home Care, Rehabilitation Centers Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, BIOTRONIK SE & Co. KG, Koninklijke Philips N.V., LivaNova PLC, MicroPort Scientific Corporation, Lepu Medical Technology, St. Jude Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Block Therapeutics Market Shifts & Advancements
Digital health integration and physiological pacing modalities are restructuring how cardiac rhythm management delivers value, shifting emphasis from hardware longevity to real-time clinical decision support and conduction-preserving therapies.
Leadless pacemaker technology is overtaking transvenous systems in selected patient populations. Cardiology clinics in the United States are expanding implant volumes for single-chamber leadless devices in patients with vascular access limitations or prior lead complications. This transition compresses long-term service revenue streams while elevating upfront device procurement costs.
The European Medical Device Regulation imposes enhanced post-market clinical follow-up requirements on cardiac implantable electronic devices. Manufacturers must now sustain systematic literature reviews and periodic safety update reports across entire product lifecycles. Small and mid-cap device developers face disproportionate compliance resource demands relative to revenue scale.
After-sales service unbundling is fragmenting traditional device-commercialization models. Hospital purchasing committees now separately negotiate remote monitoring subscriptions, technical support, and capital equipment financing. This shift is most pronounced in United States integrated delivery networks where procurement centralization has compressed vendor margin structures.
Heart Block Therapeutics Market Segmentation
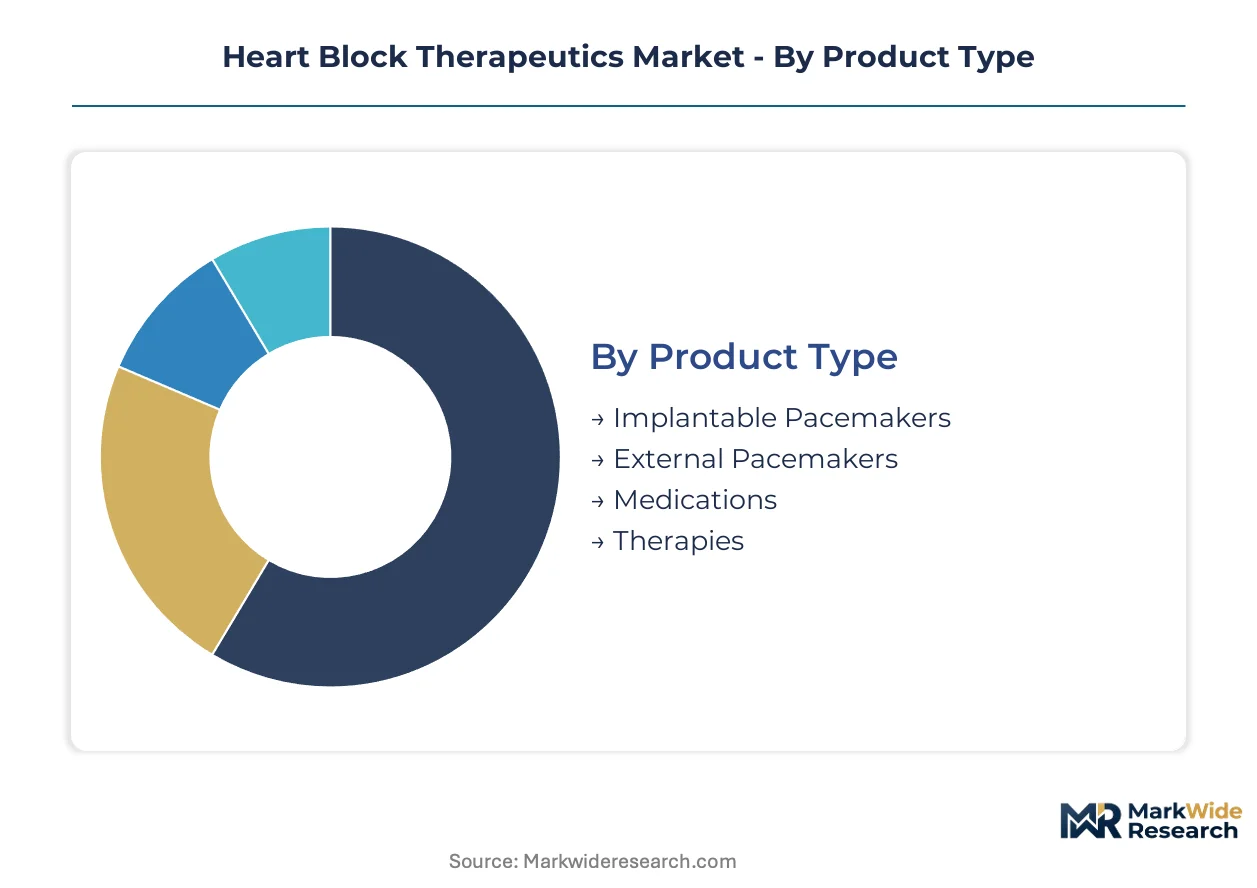
Heart block therapeutics segment along device-versus-pharmaceutical boundaries, with procurement committees weighing upfront capital expenditure against recurring service revenue and long-term outcomes liability. Each segmentation dimension reflects distinct stakeholder influence patterns across electrophysiology practices, hospital systems, and home-based care models.
Product Type:
Procurement committees prioritize total cost of ownership, balancing device longevity against replacement cycle revenue and complication risk exposure.
- Implantable Pacemakers:Battery-powered pulse generators with programmable rate response deliver electrical stimulation between 30 and 180 beats per minute through transvenous or leadless configurations. United States electrophysiology practices concentrate demand here, driven by Medicare reimbursement parity for minimally invasive implantation and remote monitoring integration.
- External Pacemakers:Temporary transcutaneous or transvenous systems provide acute rate support during post-myocardial infarction stabilization or perioperative bridging. Hospital emergency departments and cardiac catheterization laboratories in Germany and Japan anchor procurement volumes, constrained by short-term utilization economics and infection risk protocols.
- Medications:Chronotropic agents including atropine and isoproterenol address reversible conduction deficits without device implantation.
- Therapies:Catheter ablation and conduction-system pacing approaches target specific anatomical substrates in specialized referral centers.
Volume sits with implantable pacemakers; growth tilts toward leadless configurations that eliminate transvenous hardware complications.
Technology:
Reimbursement documentation requirements and clinical workflow integration determine technology adoption sequencing across practice settings.
- Biochemical Therapy:Pharmacological modulation of autonomic tone and calcium channel function addresses transient conduction disturbances without procedural intervention. Cardiology clinics in India and Brazil leverage these approaches where catheterization laboratory infrastructure remains underdeveloped.
- Electrical Stimulation:Programmable pulse delivery through endocardial, epicardial, or leadless electrodes dominates permanent rhythm management. United States integrated delivery networks and German university hospitals drive specification requirements, influenced by FDA breakthrough device pathways and European MDR compliance timelines.
- Telemedicine:Virtual consultation platforms enable remote electrophysiology specialist access for implant candidacy assessment and follow-up triage.
- Remote Monitoring:Cellular-enabled home transmission systems capture arrhythmia burden and device diagnostic data for reimbursement documentation.
Electrical stimulation captures the dominant revenue share; remote monitoring is expanding most quickly as CMS reimbursement validates transmission-based care models.
Application:
Site-of-care economics and procedural complexity dictate where specific therapeutic modalities achieve commercial viability.
- Cardiology Clinics:Outpatient electrophysiology practices concentrate leadless pacemaker implantation and conduction-system pacing procedures. United States metropolitan markets and South Korean tertiary centers anchor volume, supported by specialized catheter inventory and physician training density.
- Hospitals:Inpatient cardiac catheterization laboratories and operating rooms handle complex device upgrades, lead extractions, and emergency temporary pacing. German, French, and Japanese hospital systems maintain comprehensive electrophysiology service lines with full procedural capability.
- Home Care:Post-implant remote monitoring and medication adherence programs shift follow-up burden from clinic settings.
- Rehabilitation Centers:Structured cardiac rehabilitation programs incorporate rhythm management optimization for post-implant functional recovery.
Procedure complexity concentrates in hospitals; patient convenience and cost containment are elevating cardiology clinic and home care expansion trajectories.
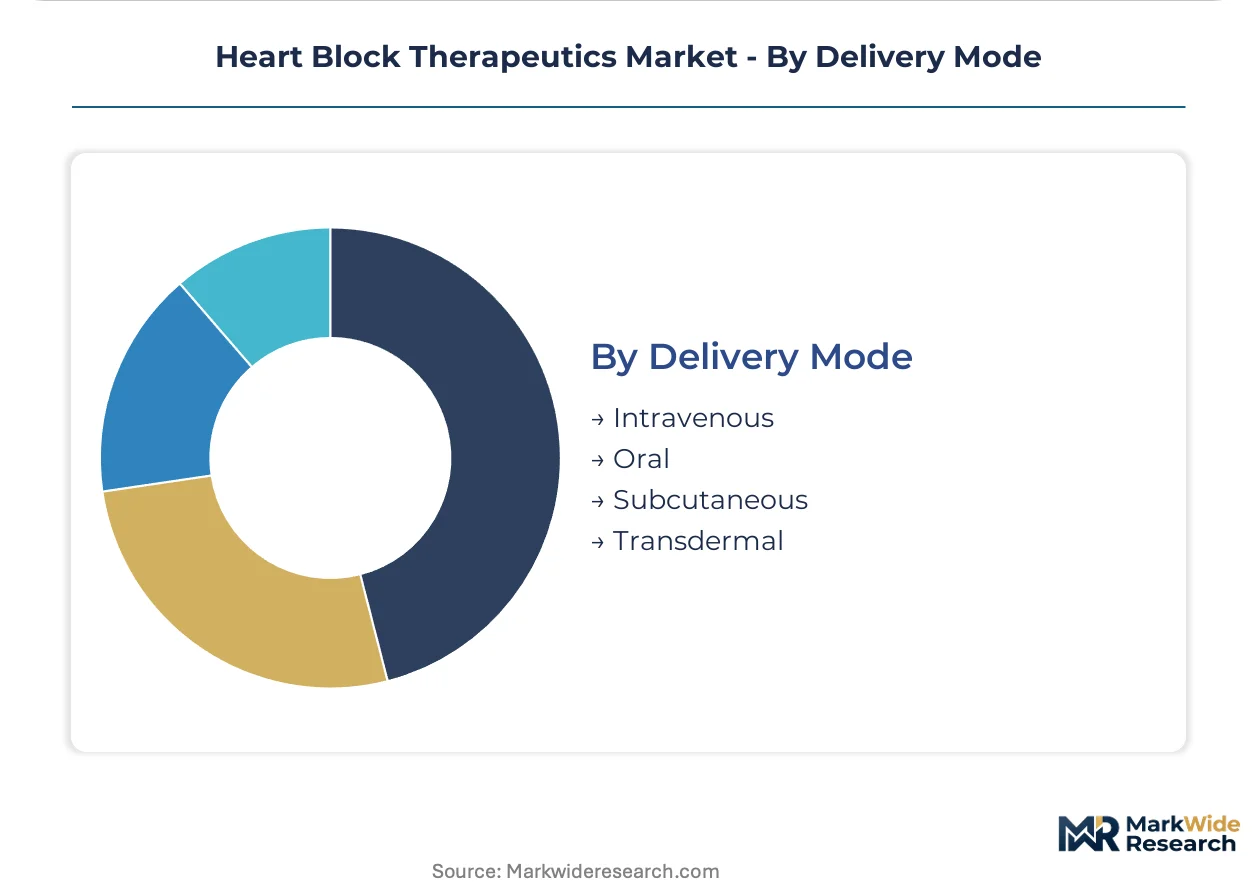
Delivery Mode:
Pharmacokinetic requirements and onset speed determine route selection across acute stabilization and chronic maintenance scenarios.
- Intravenous:Rapid-onset chronotropic support through central or peripheral venous access addresses hemodynamically unstable bradycardia in emergency and perioperative settings. United States emergency departments and Japanese critical care units anchor utilization, constrained by infection risk and vascular access limitations.
- Oral:Sustained-release formulations and chronic antiarrhythmic regimens support outpatient rhythm management without procedural intervention. Indian and Chinese pharmaceutical markets drive volume through cost-sensitive primary care prescribing patterns.
- Subcutaneous:Depot formulations and implantable drug delivery systems bridge acute and chronic therapeutic windows.
- Transdermal:Non-invasive absorption pathways remain experimental for cardiac glycosides and chronotropic agents.
Oral delivery dominates prescription volume; intravenous routes retain priority in acute care settings where hemodynamic stability demands immediate intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States electrophysiology practices generate the dominant share of procedural volume, with Medicare reimbursement policies and integrated delivery network procurement centralization concentrating purchasing power in metropolitan hospital systems.
United States
FDA breakthrough device designation accelerates review timelines for His-bundle pacing catheters, while CMS national coverage determinations shape commercial viability for conduction-system approaches. The Cleveland Clinic and Mayo Clinic anchor specialized training pipelines in Ohio and Minnesota respectively.
Germany
University hospital networks in Berlin and Munich drive adoption of leadless pacemaker systems through comprehensive electrophysiology service lines. The European Medical Device Regulation imposes enhanced post-market surveillance requirements that elevate compliance resource demands for manufacturers operating across German markets.
Japan
Aging demographics and PMDA regulatory frameworks favor minimally invasive rhythm management devices in Tokyo and Osaka metropolitan centers. The Ministry of Economy, Trade and Industry supports domestic medical device innovation through targeted R&D subsidies for next-generation pacing technologies.
India
Underpenetrated cardiac catheterization laboratory infrastructure in Maharashtra and Karnataka creates positioning opportunities for training-intensive conduction-system techniques. The Central Drugs Standard Control Organization governs import licensing and clinical trial approvals for implantable cardiac devices entering Indian markets.
South Korea
Tertiary cardiology centers in Seoul concentrate demand for remote monitoring-enabled devices supported by national health insurance reimbursement. The Ministry of Food and Drug Safety maintains streamlined approval pathways for cardiac implantable electronic devices with established international regulatory clearances.
Heart Block Therapeutics Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers restructure around long-term outcomes rather than replacement cycle revenue. The vendor base concentrates among diversified medical technology conglomerates with vertically integrated manufacturing capabilities and specialized electrophysiology pure-plays with catheter-delivery expertise. Three archetypes define competitive positioning: integrated device manufacturers controlling supply chains from component to finished product, catheter specialists enabling minimally invasive implantation techniques, and platform developers converging subcutaneous ICD and leadless pacemaker architectures. M&A activity and strategic partnerships represent the dominant competitive vectors as firms acquire specialized anatomical pacing capabilities and remote monitoring data infrastructure.
Among diversified medical technology conglomerates, Medtronic exemplifies the integrated manufacturing archetype through captive control of leadless pacemaker supply chains from wafer to finished device. Abbott Laboratories occupies a position within the catheter-specialist tier, with its structural emphasis on delivery systems that enable minimally invasive implantation approaches. Boston Scientific Corporation anchors the platform convergence archetype, representing R&D intensity in subcutaneous ICD systems that eliminate transvenous leads entirely.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| BIOTRONIK SE & Co. KG |
| Koninklijke Philips N.V. |
| LivaNova PLC |
| MicroPort Scientific Corporation |
| Lepu Medical Technology |
| St. Jude Medical |
| Others |
Supply & Pricing Matrix
United States integrated delivery networks and German university hospital systems concentrate procurement power, anchoring contract-based long-term offtake agreements that lock in volume commitments against tiered service bundles. This buyer concentration elevates upfront device costs while compressing margins on replacement cycles and remote monitoring subscriptions.
Pricing Analysis
Volume concentrates in standard-tier transvenous pacemakers with established reimbursement codes; margin accrues to premium leadless configurations and conduction-system pacing catheters with specialized delivery systems. Price differentiation hinges on FDA breakthrough device designation status and proprietary remote monitoring platform integration. Pricing pressure stems from Medicare reimbursement compression for conventional right ventricular pacing as CMS evaluates parity for His-bundle approaches. Hospital purchasing committees exhibit highest price sensitivity on capital equipment, while electrophysiology practices prioritize catheter performance over unit cost.
Supply Chain Analysis
Freight costs for temperature-controlled transport of biocompatible materials and sterile finished devices elevate landed costs for manufacturers distributing across European and Asia-Pacific markets. Component manufacturing concentrates in Ireland, Costa Rica, and Malaysia for final assembly; platinum-iridium electrodes and lithium-iodine battery cells draw from South African mining operations and Japanese chemical processors. Single-source vulnerability in precious metal supply creates exposure to commodity price swings. Distribution runs through specialized cardiac device distributors with field clinical engineering support rather than general medical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrophysiologist training pipeline constraints limit procedural capacity expansion, propping pricing power for manufacturers with established catheter-delivery expertise and remote monitoring infrastructure.
For Market Incumbents: Lock in long-term service revenue through proprietary remote monitoring platform subscriptions that capture arrhythmia burden data for reimbursement documentation. Deepen backward integration into leadless pacemaker battery cell production to insulate margins from lithium-iodine supply volatility. Defend against subcutaneous ICD-leadless pacemaker convergence platforms by accelerating R&D in combined rhythm management architectures. For New Entrants and Emerging Players: Enter via India's underpenetrated cardiac catheterization laboratory networks where training-intensive conduction-system techniques face limited established competition. Target Maharashtra and Karnataka state hospital systems with catheter-delivery system partnerships that address infrastructure gaps. Pursue licensing arrangements with tertiary cardiology centers rather than direct device sales to navigate CDSCO import licensing complexity. For Investors and Strategic Acquirers: The window for entry favors electrophysiology pure-plays with specialized anatomical pacing capabilities and established training relationships. Acquisition targets should demonstrate proprietary catheter-delivery IP and remote monitoring data infrastructure with hospital system integration. Watch CMS national coverage determination timing for His-bundle pacing as the inflection signal validating specialized catheter investments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates review timelines for His-bundle pacing catheters entering United States markets. |
| CE Marking Pathway | Unlocks European Medical Device Regulation compliance for leadless pacemaker commercialization. |
| Hospital System Partnership | Secures preferred vendor status within United States integrated delivery network procurement centralization. |
| Software Companion Development | Enables cellular-enabled remote monitoring data capture for CMS reimbursement documentation. |
| Reimbursement Strategy | Positions conduction-system pacing for Medicare parity with conventional right ventricular approaches. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with electrophysiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. FDA 510(k) premarket notifications, EMA device registration databases, and CMS national coverage determination records supplied validation benchmarks. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation reconciled volume estimates.
Data-stream reconciliation across implant procedure registries, hospital procurement databases, and manufacturer revenue disclosures calibrated segmentation outputs. The analytical framework modeled product type, technology platform, application site-of-care, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from historical implant volume trajectories, reimbursement policy evolution, and electrophysiologist workforce expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA breakthrough designation delays or CMS reimbursement parity reversals. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Stroke Management Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Cardiovascular Enterprise Viewer Market