
 Myocardial Infarction Therapeutics Market | 2026-2036
Myocardial Infarction Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Myocardial Infarction Therapeutics Market Outlook
Hospital procurement of myocardial infarction therapeutics is tilting toward bundled protocols that pair antiplatelet agents with statins and beta-blockers. Pfizer leverages its manufacturing scale to anchor supply contracts across integrated health networks in North America. AstraZeneca competes through specialized cardiovascular portfolios that emphasize dual antiplatelet therapy continuity. Novartis differentiates via gene therapy and regenerative medicine pipelines targeting post-infarction cardiac remodeling.
Myocardial infarction therapeutics encompass pharmacological and interventional modalities designed to restore coronary perfusion, limit myocardial necrosis, and prevent recurrent ischemic events through anticoagulation, plaque stabilization, and revascularization support. These interventions typically deploy within minutes to hours of symptom onset, with intravenous thrombolytics and percutaneous coronary intervention representing time-critical standards of care. Antiplatelet agents and statins command the largest current revenue pools due to chronic post-event prescribing, while gene therapy and stem cell therapy represent the fastest-expanding technology segments as investigators target myocardial regeneration beyond acute stabilization. Oral administration routes dominate maintenance-phase prescribing, though intravenous delivery retains priority in emergency settings where rapid bioavailability determines clinical outcomes.
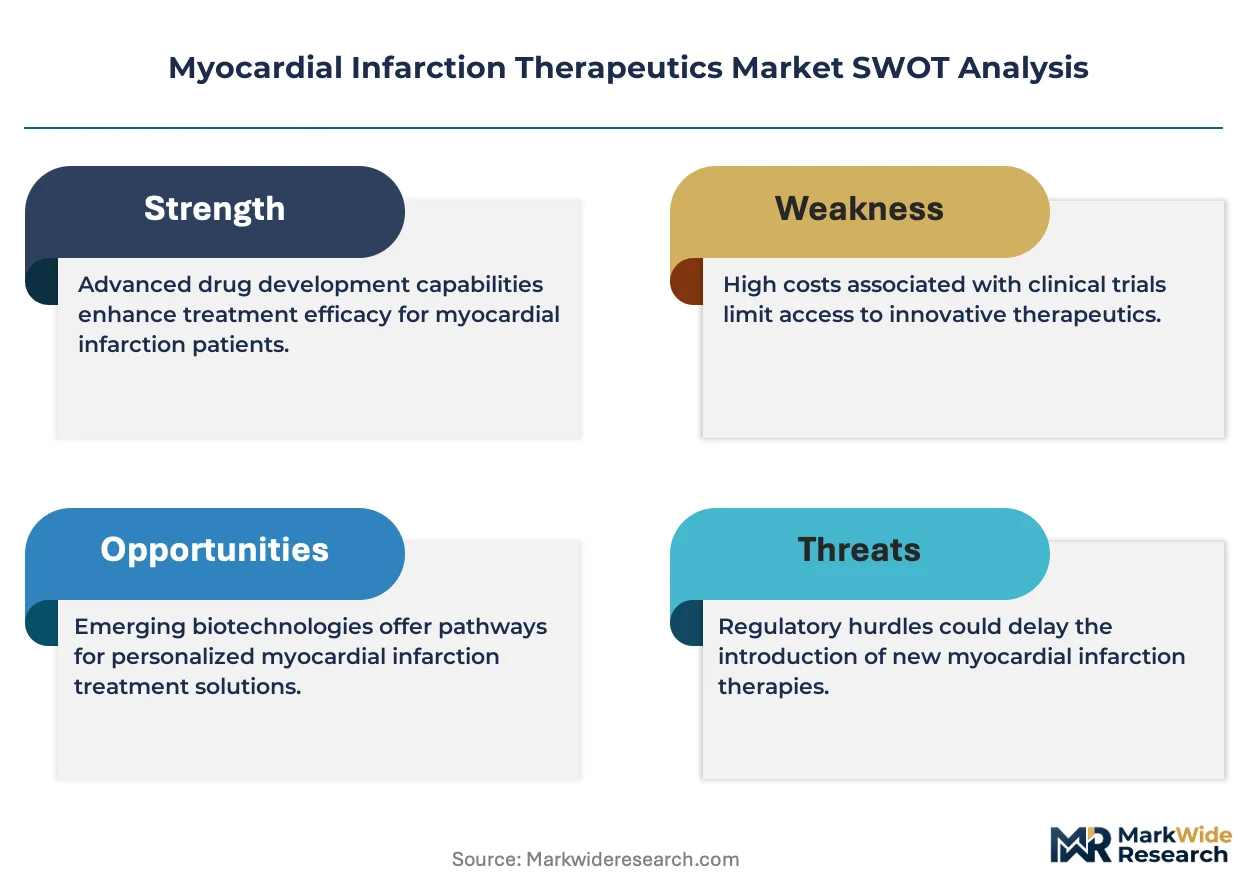
FDA cardiovascular safety mandates and EMA's MDR framework for drug-eluting stents shape product development timelines and market access pathways for device-pharma combination therapies. The EU AI Act and FDA guidance on machine learning in cardiovascular diagnostics are beginning to influence how risk stratification tools integrate with therapeutic decision systems. Stakeholders must monitor how regulatory convergence on real-world evidence requirements affects post-market surveillance obligations and reimbursement negotiations across jurisdictions.
Market Dynamics
Hospital procurement consolidation is forcing therapeutic suppliers to restructure commercial models around bundled protocol contracts rather than discrete product sales. Integrated delivery networks in the United States and Germany now mandate dual antiplatelet therapy continuity guarantees as a condition of formulary inclusion.
Growth Catalysts
- FDA cardiovascular safety guidelines:Updated mandates accelerate combination antiplatelet and statin protocol standardization across acute care settings. Emergency departments embed these regimens into door-to-balloon quality metrics.
- Japan's super-aging demographic:Patients over 75 drive recurrent event prevention prescribing intensity. Interventional cardiology infrastructure expansion in prefectural centers sustains therapeutic volume.
- Gene therapy platforms:Investigational approaches targeting post-infarction cardiac remodeling attract priority funding. Regenerative medicine pipelines address myocardial regeneration beyond acute stabilization.
Market Restraints
- Biologic API cost volatility:Recombinant protein production inputs face supply concentration in Chinese contract manufacturing organizations. Price instability compresses margin structures for advanced therapeutic candidates.
- EMA MDR framework complexity:Drug-eluting stent recertification timelines extend market access windows. Device-pharma combination products face disproportionate regulatory burden versus pure pharmaceutical alternatives.
- Thrombolytic substitution pressure:Primary percutaneous coronary intervention displaces intravenous thrombolytics in urban centers with catheterization laboratory access. Rural and developing markets retain thrombolytic dependence.
Strategic Opportunities
- Stem cell therapy convergence:Mesenchymal stem cell delivery platforms hybridize with interventional cardiology workflows. Academic medical centers in Germany pilot catheter-based myocardial injection protocols.
- EU AI Act diagnostic integration:Machine learning risk stratification tools gain reimbursement traction when bundled with therapeutic decision systems. Payers reward algorithm-guided antiplatelet intensity modulation.
- Direct-to-hospital distribution:Specialty pharmaceutical distributors bypass wholesale intermediaries for emergency cardiovascular products. Cold chain biologics require temperature-controlled last-mile capabilities.
Industry Challenges
- Interventional cardiology workforce scarcity:Fellowship-trained operators concentrate in tertiary centers. Community hospital expansion of PCI programs stalls due to credentialing pipeline constraints.
- Real-world evidence infrastructure:Post-market surveillance obligations under FDA and EMA convergence demand registry participation. Smaller therapeutic developers lack data science capacity for longitudinal outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myocardial Infarction Therapeutics Market |
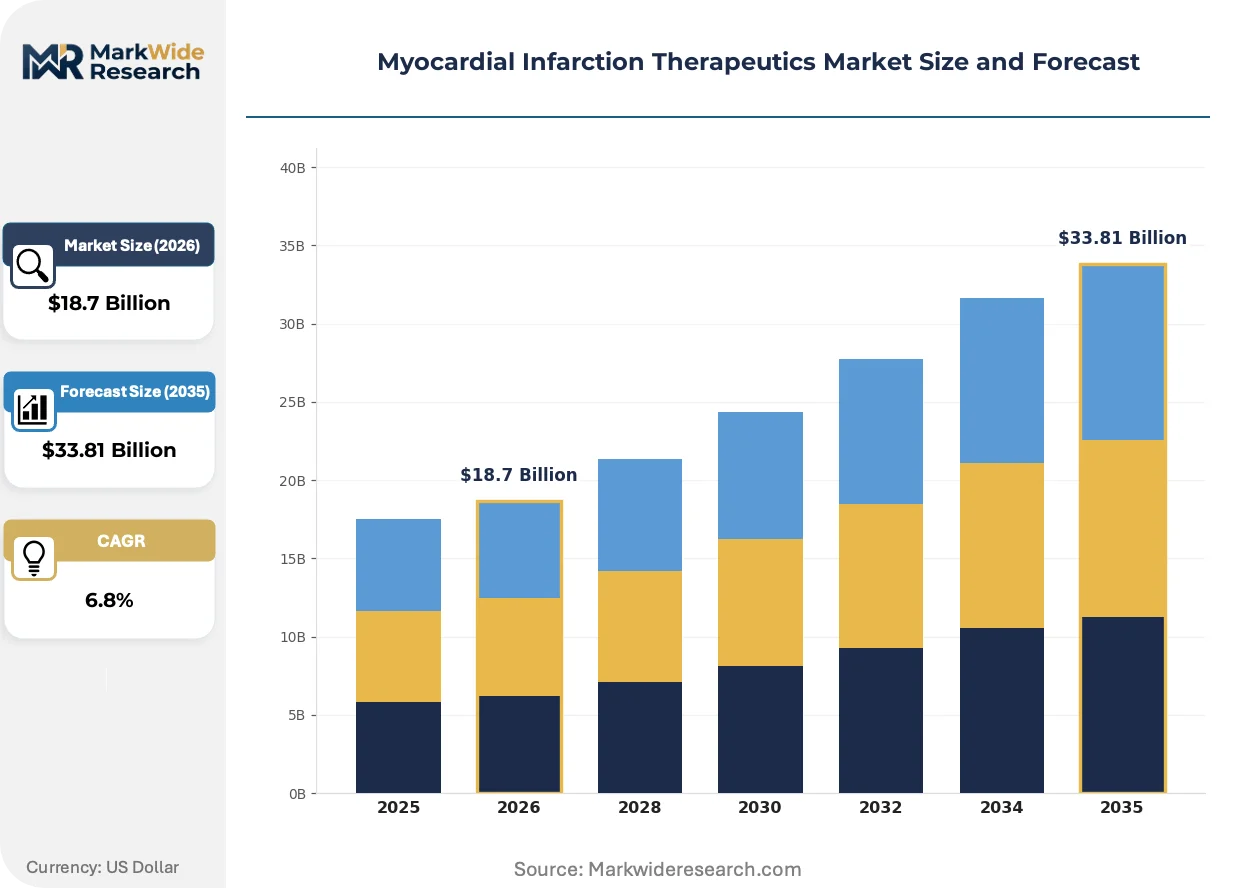
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angiotensin Receptor Blockers, Beta-Blockers, Antiplatelet Agents, Statins Administration Route: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Cardiology Clinics, Rehabilitation Centers, Home Care Technology: Gene Therapy, Stem Cell Therapy, Drug-Eluting Stents, Antibody-Drug Conjugates |
| Companies Covered | Pfizer, AstraZeneca, Novartis, Bristol-Myers Squibb, Amgen, Boehringer Ingelheim, Daiichi Sankyo, Eli Lilly and Company, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myocardial Infarction Therapeutics Market Strategic Shifts
Cardiovascular therapeutic development is hybridizing across pharmaceutical, device, and regenerative modalities. Competitive advantage now depends on protocol integration rather than single-product superiority.
Antiplatelet-statin-beta-blocker triple therapy protocols are hybridizing into fixed-dose combination formulations. Hospital formularies in the United States prioritize adherence-optimized dosing to reduce secondary event readmissions. Cardiovascular service lines embed these combinations into discharge bundle standards, compressing prescribing discretion.
EMA's MDR framework for drug-eluting stents is extending clinical evidence requirements beyond initial approval. Manufacturers must submit annual safety updates and participate in European registries. Japanese PMDA alignment with these standards is forcing Asia-Pacific submission strategy recalibration.
Integrated health networks are consolidating vendor relationships around therapeutic protocol guarantees rather than product-level contracts. Emergency department directors negotiate dual antiplatelet therapy continuity assurances spanning admission through 12-month post-discharge. This concentration is visible in United States accountable care organizations and German sickness fund networks.
Myocardial Infarction Therapeutics Market Segmentation
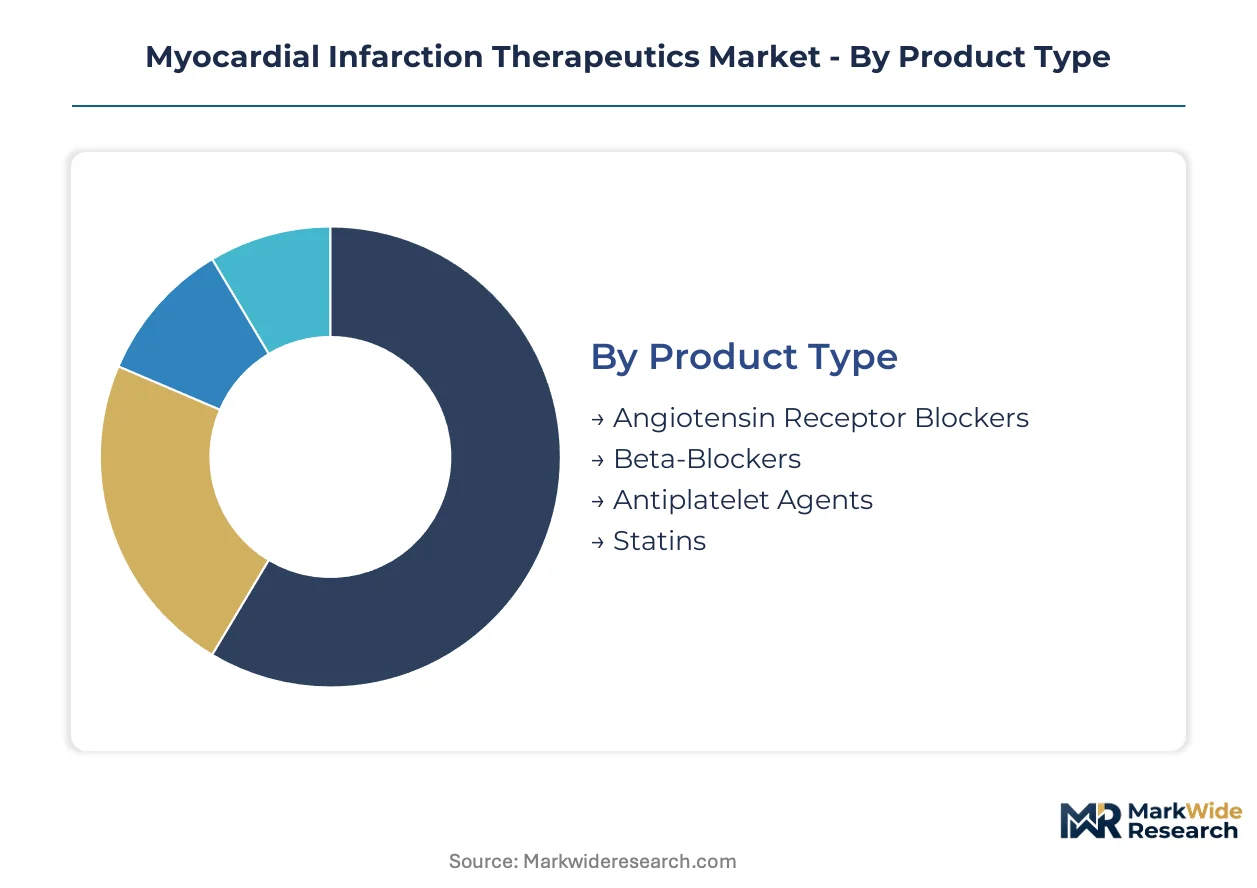
Therapeutic modality selection in myocardial infarction care follows distinct replenishment rhythms. Emergency-phase interventions turn over in hours while maintenance regimens sustain months-long prescribing cycles. Understanding these temporal patterns clarifies inventory positioning and contract negotiation priorities across acute and ambulatory settings.
Product Type:
Cycle times vary dramatically across pharmacological classes, with acute-phase agents requiring hourly restocking versus chronic therapies operating on quarterly procurement schedules.
- Antiplatelet Agents:Dual antiplatelet therapy combining aspirin with P2Y12 inhibitors forms the cornerstone of acute coronary syndrome management. Hospital formularies in the United States and Germany negotiate annual volume guarantees for these agents given their position in door-to-balloon quality metrics. Supply contracts increasingly bundle 12-month post-discharge continuity programs to reduce secondary event readmissions.
- Statins:High-intensity statin protocols initiated within 24 hours of presentation reduce recurrent ischemic events through plaque stabilization. Japanese prefectural centers drive prescribing intensity among patients over 75, where super-aging demographics sustain chronic maintenance demand. Procurement cycles extend to 90-day intervals for these oral agents.
- Beta-Blockers:Cardioselective beta-blockers reduce myocardial oxygen demand during acute phases and prevent remodeling chronically. These agents integrate into fixed-dose combination formulations with antiplatelet agents and statins.
- Angiotensin Receptor Blockers:ARBs target renin-angiotensin system modulation for patients intolerant to ACE inhibitors. These therapies follow quarterly procurement patterns aligned with heart failure comorbidity management.
Antiplatelet agents anchor the volume base while gene therapy platforms gain share at the steepest rate.
Administration Route:
Cost tiers separate emergency delivery requiring specialized infrastructure from maintenance-phase options suitable for outpatient distribution.
- Intravenous:IV thrombolytics and glycoprotein IIb/IIIa inhibitors demand immediate bioavailability in catheterization laboratories. These high-cost emergency formulations require cold chain infrastructure and 24-hour pharmacy availability. Urban centers with PCI capability concentrate procurement, while rural settings retain thrombolytic dependence where laboratory access remains limited.
- Oral:Maintenance-phase antiplatelet agents, statins, and beta-blockers dominate chronic prescribing through oral routes. German sickness fund networks and United States accountable care organizations prioritize adherence-optimized dosing to compress prescribing discretion.
- Subcutaneous:Subcutaneous delivery supports anticoagulation bridging and select biologic agents. This route occupies a mid-tier cost position between emergency IV and maintenance oral options.
- Transdermal:Transdermal patches for nitrate delivery and select cardiovascular agents offer adherence advantages for elderly populations. Prefectural centers in Japan pilot these formulations for super-aging patient cohorts.
Oral administration commands the chronic volume base while intravenous delivery retains the highest per-dose value capture.
End User:
Customer type determines contract structure complexity, with integrated networks demanding protocol guarantees versus individual facility purchasing.
- Hospitals:Acute care facilities anchor therapeutic demand through emergency department presentation and PCI capability. United States integrated delivery networks and German sickness funds mandate dual antiplatelet therapy continuity guarantees as formulary conditions. Bundled protocol contracts now supersede discrete product procurement.
- Cardiology Clinics:Outpatient cardiology practices manage post-infarction risk factor modification and medication titration. These settings concentrate maintenance-phase prescribing for statins and antiplatelet agents.
- Rehabilitation Centers:Cardiac rehabilitation programs coordinate secondary prevention protocols including medication adherence monitoring. These facilities bridge acute hospitalization and long-term primary care management.
- Home Care:Home-based administration supports select anticoagulation regimens and patient self-management of chronic cardiovascular medications. This channel expands with telemedicine integration and remote monitoring capabilities.
Hospitals anchor the acute-phase volume base while home care channels expand most quickly with remote monitoring adoption.
Technology:
Development maturity separates established device-pharma combinations from investigational platforms still navigating regulatory pathways.
- Drug-Eluting Stents:DES technology combines mechanical revascularization with localized antiproliferative drug delivery. EMA's MDR framework extends recertification timelines and registry participation obligations. Japanese PMDA alignment with these standards forces Asia-Pacific submission strategy recalibration.
- Stem Cell Therapy:Mesenchymal stem cell delivery platforms target myocardial regeneration beyond acute stabilization. Academic medical centers in Germany pilot catheter-based myocardial injection protocols. These investigational approaches attract priority funding for post-infarction cardiac remodeling.
- Gene Therapy:Viral vector and gene editing platforms address genetic determinants of cardiovascular risk and regenerative capacity. Novartis differentiates via pipelines targeting post-infarction remodeling through regenerative mechanisms.
- Antibody-Drug Conjugates:ADC technology applies targeted cytotoxic delivery to cardiovascular indications including vascular inflammation modulation. These platforms remain in earlier development phases relative to oncology applications.
Drug-eluting stents anchor the interventional volume base while stem cell therapy climbs the fastest toward commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement protocols in Germany and the United States now mandate dual antiplatelet therapy continuity guarantees as a condition of formulary inclusion, reshaping how therapeutic suppliers structure commercial contracts across integrated delivery networks.
United States
Aging demographics and established interventional cardiology infrastructure sustain therapeutic intensity in acute care settings. FDA cardiovascular safety guidelines accelerate combination antiplatelet and statin protocol standardization across emergency departments. Accountable care organizations in the Northeast and California embed these regimens into door-to-balloon quality metrics and discharge bundle standards.
Germany
Super-aging patient cohorts over 75 drive recurrent event prevention prescribing intensity through statutory sickness fund networks. EMA's MDR framework for drug-eluting stents extends recertification timelines and registry participation obligations. Academic medical centers in Bavaria and Baden-Württemberg pilot catheter-based mesenchymal stem cell injection protocols for post-infarction cardiac remodeling.
Japan
Patients over 75 command a disproportionate share of maintenance-phase statin and antiplatelet prescribing volume. PMDA alignment with EMA MDR standards forces Asia-Pacific submission strategy recalibration for device-pharma combination products. Prefectural centers in Kanto and Kansai regions expand interventional cardiology infrastructure to sustain therapeutic volume outside Tokyo.
United Kingdom
NHS England's cardiovascular disease prevention program targets secondary event reduction through high-intensity statin protocols initiated within 24 hours of acute presentation. NICE technology appraisals shape formulary access for novel antiplatelet agents and regenerative therapies. London and Southeast England concentrate tertiary PCI capability while Midlands and North England retain thrombolytic dependence where catheterization laboratory access remains limited.
China
Rapid urbanization and dietary transition expand the addressable patient population for acute coronary syndrome management. NMPA cardiovascular safety mandates accelerate local clinical trial requirements for imported antiplatelet agents and drug-eluting stents. Yangtze River Delta and Pearl River Delta clusters concentrate domestic manufacturing capacity for generic statins and anticoagulation therapies.
Myocardial Infarction Therapeutics Market Competitive Environment
On the supply side, the industry is consolidating around therapeutic protocol guarantees rather than discrete product sales, with hospital procurement consolidation forcing suppliers to restructure commercial models around bundled contracts. Three strategic archetypes dominate: large-scale pharmaceutical manufacturers anchoring supply contracts across integrated health networks, specialized cardiovascular portfolio companies emphasizing dual antiplatelet therapy continuity, and regenerative medicine developers targeting post-infarction cardiac remodeling. Competitive moves concentrate on M&A for gene therapy platform acquisition and strategic partnerships for real-world evidence generation.
Among established pharmaceutical manufacturers, Pfizer and AstraZeneca occupy positions as anchor suppliers to integrated delivery networks, with Novartis representing the regenerative medicine archetype through gene therapy pipelines. These three companies exemplify the tiering between scale-driven contract manufacturers, specialized cardiovascular portfolio players, and investigational platform developers. Their collective positioning reflects how competitive advantage now depends on protocol integration rather than single-product superiority.
| Leading Market Players |
|---|
| Pfizer |
| AstraZeneca |
| Novartis |
| Bristol-Myers Squibb |
| Amgen |
| Boehringer Ingelheim |
| Daiichi Sankyo |
| Eli Lilly and Company |
| Bayer |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta biologics manufacturing clusters anchor global capacity for recombinant antiplatelet API production, concentrating pricing power among contract manufacturers serving branded and generic formulation houses. Their dominance in fermentation-based inputs shapes downstream cost structures for dual antiplatelet therapy regimens across North American and European hospital networks.
Pricing Analysis
Certification level (FDA-grade versus EMA MDR-compliant versus regional standard) creates the primary spread between emergency-phase IV thrombolytics and maintenance oral agents. Three-tier pricing structure across premium branded, authorized generic, and commodity generic tiers separates hospital formulary anchors from cost-optimized tenders. Cost compression in the generic antiplatelet tier is intensifying because of Indian API supplier consolidation. Community hospital systems exhibit the highest price sensitivity, while integrated delivery networks prioritize protocol guarantees over per-unit cost.
Supply Chain Analysis
Wuxi Biologics and Lonza hold dominant contract-manufacturing capacity for monoclonal antibody components in cardiovascular pipelines. Active pharmaceutical ingredient production concentrates in China, India, and Switzerland, with fill-finish operations anchored in Ireland and Singapore. Supply chains draw from recombinant protein feedstocks, specialized fermentation media, and cold-chain packaging materials. Single-source vulnerability in Chinese heparin precursor supply poses structural risk. Distribution runs through specialty pharmaceutical distributors with temperature-controlled last-mile capabilities direct to hospital pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-discharge medication adherence programs represent the fastest-expanding service-attach layer, converting acute episodic sales into recurring twelve-month continuity contracts that outperform device revenue growth.
For Market Incumbents: Build regulatory data moats through EMA MDR registry participation and FDA real-world evidence infrastructure investments. Anchor hospital formulary position by guaranteeing dual antiplatelet therapy continuity across admission-to-discharge episodes. Deepen backward integration into recombinant API production to defend margin position against Chinese contract manufacturing volatility. For New Entrants and Emerging Players: Establish a beachhead in catheter-based stem cell delivery platforms for post-infarction remodeling, where clinical evidence gaps favor nimble developers. Target German academic medical centers piloting mesenchymal stem cell injection protocols. Pursue strategic partnerships with interventional cardiology device manufacturers for workflow integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among therapeutic suppliers bundling 12-month post-discharge adherence programs with acute-phase product sales. Gene therapy platform developers targeting cardiac regeneration offer the strongest long-term viability profile within the regenerative medicine archetype. Watch for PMDA alignment with EMA MDR standards as the signal indicating accelerated Japan market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Infrastructure Investment | FDA and EMA convergence on post-market surveillance obligations rewards registry participation with accelerated formulary access. |
| Dual Antiplatelet Therapy Continuity Guarantee | United States accountable care organizations and German sickness funds mandate this as a condition of vendor selection. |
| Catheter-Based Stem Cell Delivery Partnership | Academic medical centers in Bavaria and Baden-Württemberg pilot these protocols for post-infarction cardiac remodeling. |
| Direct-to-Hospital Distribution Buildout | Cold chain biologics require temperature-controlled last-mile capabilities bypassing wholesale intermediaries. |
| Gene Therapy Platform Acquisition | Novartis differentiation via regenerative pipelines signals competitive priority for post-infarction remodeling targets. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up therapeutic volume modeling was cross-checked against top-down market sizing through triangulation across these sources.
Forecast inputs considered therapeutic modality, administration route, end-user facility type, and regional regulatory cluster across the analysis window. CAGRs were derived from segment-level volume trajectories weighted by pricing tier and procurement cycle patterns. Modeled assumptions included FDA cardiovascular safety guideline adoption curves, EMA MDR recertification timelines, and Japan super-aging demographic prescribing intensity.
Stress conditions across biologic API cost volatility, interventional cardiology workforce scarcity, and thrombolytic substitution pressure were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of hospital procurement contract announcements, registry enrollment data, and PMDA submission filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Global Statin Market
Cardiovascular
Endothelial Dysfunction Market