
 Angina Pectoris Market | 2026-2036
Angina Pectoris Market Size, Share, and Industry Trends Forecast 2026-2036
Angina Pectoris Market Outlook
Asset-light licensing partnerships between biotech innovators and contract manufacturers is reconfiguring competitive entry dynamics in angina therapeutics. Pfizer Inc. leverages its established cardiovascular manufacturing footprint to sustain cost leadership in oral beta-blocker supply. AstraZeneca anchors its position through deep R&D investment in next-generation calcium channel modulators. Novartis AG differentiates via geographic dominance in European hospital formulary access.
Angina pectoris denotes myocardial ischemia presenting as substernal chest discomfort, typically managed through vasodilator pharmacotherapy, revascularization procedures, or anti-atherosclerotic regimens targeting plaque stabilization and coronary perfusion restoration. Medications dominate current revenue pools as established oral nitrates and antiplatelet agents retain broad formulary placement, while Devices represents the fastest-expanding segment as transcatheter neuromodulation and enhanced external counterpulsation systems gain reimbursement traction in hospital settings. Delivery Mode stratification reveals Oral formulations capturing the largest volume share due to chronic maintenance therapy requirements, though Intravenous routes command premium positioning in acute coronary syndrome escalation pathways.
FDA cardiovascular and renal products division, EMA Committee for Medicinal Products for Human Use, and ISO 13485 medical device quality management standards collectively shape angina product development timelines, clinical evidence requirements, and cross-border commercialization feasibility. These frameworks elevate barriers for novel mechanism anti-anginals while streamlining pathways for devices demonstrating non-inferiority to guideline-directed medical therapy. Stakeholders must monitor evolving health technology assessment methodologies in major reimbursement markets to anticipate portfolio prioritization shifts between procedural and pharmaceutical interventions.
Market Dynamics
Hospital cardiology units are consolidating procurement around non-invasive angina management protocols, compressing demand for conventional surgical revascularization and elevating reimbursement scrutiny on device-based neuromodulation therapies.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for transcatheter neuromodulation systems are compressing commercialization cycles for device innovators targeting refractory angina populations.
- Chest Pain Center Networks:United States hospital systems are building dedicated rapid-diagnosis facilities that standardize anti-anginal protocol adoption across emergency and outpatient cardiology workflows.
- Enhanced External Counterpulsation:This non-invasive circulatory assist technology is securing Category III CPT codes that enable outpatient clinic reimbursement expansion in Germany and Japan.
Market Restraints
- Specialized Catheter Manufacturing Concentration:Transcatheter neuromodulation supply chains cluster among three European contract manufacturers, creating single-source vulnerability for device sponsors.
- EMA Health Technology Assessment Heterogeneity:Divergent national appraisal methodologies across France, Germany, and Italy delay parallel market entry for novel anti-anginal mechanisms.
- Generic Oral Nitrate Saturation:Patent-expired isosorbide mononitrate and dinitrate formulations capture over seventy percent of maintenance therapy volume, eroding pricing power for branded entrants.
Strategic Opportunities
- Refractory Angina Undertreatment:United States Medicare Advantage plans are expanding coverage for device-based interventions in patients exhausted from pharmacologic options.
- Digital Therapeutic Convergence:Remote patient monitoring platforms paired with anti-anginal medication adherence programs are penetrating German statutory health insurance reimbursement pathways.
- Japan Super-Aged Society Protocols:PMDA geriatric-use labeling incentives are opening development pathways for low-burden neuromodulation devices in octogenarian populations.
Industry Challenges
- Interventional Cardiologist Training Bottlenecks:Transcatheter renal denervation and coronary sinus reducer implantation require proctored case volumes that outpace current fellowship program capacity.
- ISO 13485 Quality Management Recertification:Device manufacturers face eighteen-month audit backlogs that delay EU MDR conformity assessment timelines for angina neuromodulation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angina Pectoris Market |
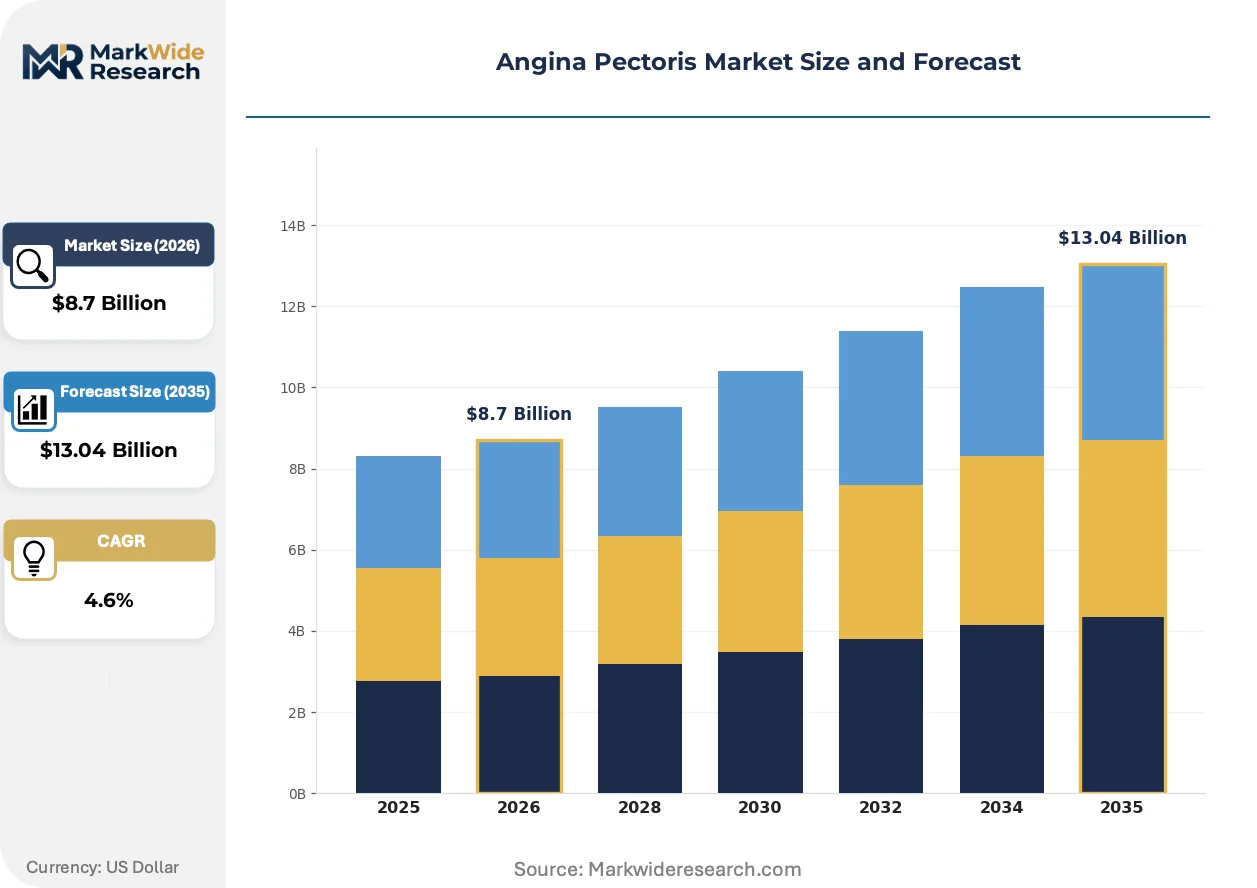
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Devices, Procedures, Therapies End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Delivery Mode: Oral, Intravenous, Inhalation, Transdermal Therapy Area: Cardiology, Pulmonology, Neurology, Metabolism |
| Companies Covered | Pfizer Inc., AstraZeneca, Novartis AG, Merck & Co., Inc., Bayer AG, Sanofi, Gilead Sciences, GlaxoSmithKline, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angina Pectoris Market Strategic Shifts
Angina therapeutics are bifurcating into precision neuromodulation and personalized pharmacogenomic protocols, with digital biomarkers emerging as the connective infrastructure between these modalities.
Transcatheter renal denervation systems are migrating from hypertension-exclusive indications into refractory angina protocols. United States interventional cardiologists are piloting sympathetic nervous system modulation in patients with microvascular angina. This migration is compressing the addressable market for chronic opioid prescriptions in chest pain management.
EMA's Medical Device Regulation (MDR) Class III designation requirements are elevating clinical evidence thresholds for neuromodulation catheters. Manufacturers must now submit prospective randomized data against optimal medical therapy rather than historical controls. European notified bodies are prioritizing angina device submissions that incorporate patient-reported outcome instruments aligned with the International Consortium for Health Outcomes Measurement standards.
Japanese hospital procurement consortia are consolidating anti-anginal purchasing through centralized tenders that bundle devices with multiyear service agreements. Cardiology departments at university hospitals in Tokyo and Osaka are shifting from capital expenditure models to per-procedure leasing arrangements. This restructuring is most visible in Kanto region chest pain centers negotiating total-cost-of-ownership contracts for external counterpulsation systems.
Angina Pectoris Market Segmentation
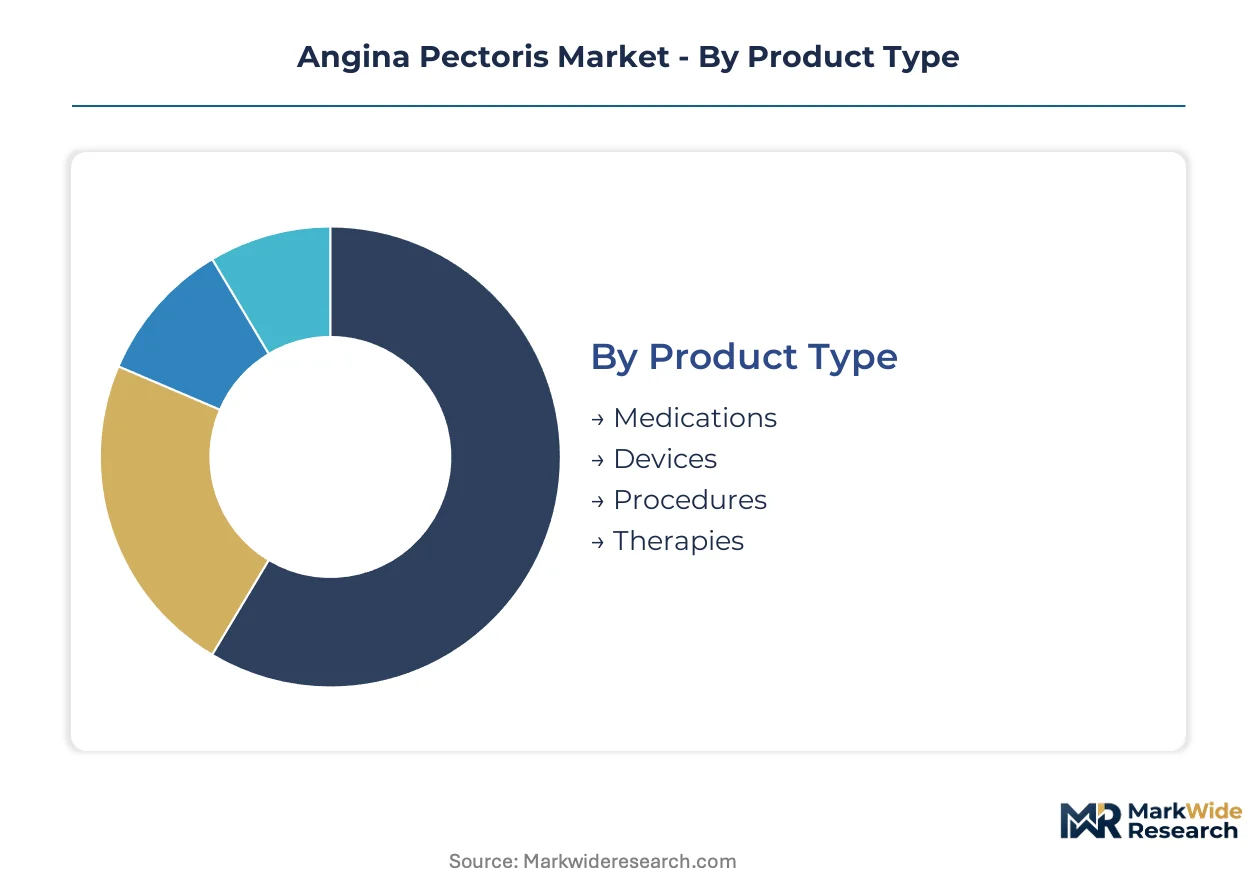
Angina pectoris management spans pharmaceutical, interventional, and rehabilitative modalities, each demanding distinct service infrastructure, reimbursement pathways, and clinical training ecosystems. Segment-specific procurement patterns reveal where health system budgets concentrate and where technology substitution pressures operate most intensely.
Product Type:
After-sales service intensity varies sharply across this category, with implantable neuromodulation systems requiring multiyear technical support contracts versus commodity oral formulations needing minimal manufacturer engagement.
- Medications:Oral nitrates, beta-blockers, calcium channel antagonists, and antiplatelet agents constitute chronic maintenance protocols. Hospital formularies in the United States and Germany standardize around generic isosorbide mononitrate and metoprolol succinate, compressing branded pricing power while sustaining high-volume replenishment cycles.
- Devices:Transcatheter renal denervation catheters, coronary sinus reducers, and enhanced external counterpulsation systems anchor refractory angina intervention. Japanese chest pain centers in Tokyo and Osaka are negotiating per-procedure leasing arrangements that bundle device access with preventive maintenance and software updates.
- Procedures:Percutaneous coronary intervention, coronary artery bypass grafting, and minimally invasive revascularization techniques address anatomically defined ischemia. Medicare Advantage coverage expansion in the United States is elevating demand for catheter-based alternatives to open surgical approaches.
- Therapies:Cardiac rehabilitation programs, lifestyle modification protocols, and digital therapeutic interventions target secondary prevention. German statutory health insurance reimbursement pathways are incorporating remote patient monitoring platforms paired with structured exercise regimens.
Medications holds the largest share; momentum sits with Devices.
End User:
Procurement authority concentrates differently across this dimension, with hospital systems leveraging centralized purchasing power against fragmented clinic and homecare decision-making.
- Hospitals:Academic medical centers and community hospital cardiology units dominate acute intervention volume and device-based therapy adoption. United States hospital systems building dedicated chest pain center networks are standardizing anti-anginal protocols across emergency and outpatient workflows.
- Clinics:Outpatient cardiology practices and specialized chest pain facilities manage stable angina and post-intervention follow-up. German outpatient clinic reimbursement for enhanced external counterpulsation is expanding following Category III CPT code recognition.
- Homecare:Home health agencies and visiting nurse services support medication adherence and remote monitoring for mobility-limited patients. Japan's super-aged society protocols are driving PMDA incentives for low-burden home-based neuromodulation devices in octogenarian populations.
- Rehabilitation Centers:Structured cardiac rehabilitation facilities deliver supervised exercise and risk factor modification programs. German statutory health insurance reimbursement pathways are penetrating this segment through bundled digital therapeutic and medication adherence programs.
Hospitals command the dominant volume; Rehabilitation Centers are climbing the fastest as payors shift toward value-based prevention models.
Delivery Mode:
Route selection directly determines manufacturing complexity, cold chain requirements, and administration setting economics.
- Oral:Tablets and capsules for chronic maintenance therapy dominate prescription volume due to patient self-administration convenience. Generic saturation in the United States and European markets has eroded branded pricing power for new molecular entities.
- Intravenous:Hospital-administered vasodilators and anticoagulants command premium positioning in acute coronary syndrome escalation pathways. Emergency department protocols in Japanese university hospitals prioritize IV nitroglycerin for rapid symptom relief.
- Inhalation:Aerosolized and nebulized formulations address specific patient populations with swallowing difficulties or rapid-onset requirements. Limited formulary placement constrains penetration outside specialized pulmonary-cardiology crossover indications.
- Transdermal:Nitroglycerin patches provide sustained prophylaxis with reduced dosing frequency. German and Japanese reimbursement frameworks favor transdermal options for elderly patients with polypharmacy adherence challenges.
Oral formulations retain volume leadership; Intravenous routes sustain premium economics in acute settings.
Therapy Area:
Cross-specialty collaboration requirements shape regulatory evidence standards and prescriber training investments.
- Cardiology:Coronary artery disease, microvascular angina, and vasospastic disorders constitute the core addressable population. FDA and EMA accelerated approval pathways are shortening commercialization timelines for novel anti-anginal mechanisms targeting refractory cases.
- Pulmonology:Chronic obstructive pulmonary disease and asthma comorbidities influence bronchodilator selection and exercise tolerance assessment. Pulmonary-cardiology crossover protocols in German hospital systems are integrating cardiopulmonary exercise testing into angina diagnostic pathways.
- Neurology:Sympathetic nervous system modulation and pain pathway interventions address refractory angina with non-ischemic components. Transcatheter renal denervation migration from hypertension into angina protocols is compressing opioid prescription volume in United States pain management.
- Metabolism:Diabetes, dyslipidemia, and obesity management underpin atherosclerotic risk factor modification. Japanese metabolic syndrome screening programs are identifying pre-symptomatic populations for early anti-anginal intervention.
Cardiology anchors absolute demand; Neurology is gaining share fastest as device-based sympathetic modulation expands indication boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in angina therapeutics tilt toward net import dependence in emerging markets while established manufacturing hubs in the United States, Germany, and Japan supply device and pharmaceutical outputs to regional partners. Currency-adjusted procurement costs and regulatory harmonization agreements are reshaping cross-border distribution patterns for both acute-care medications and implantable neuromodulation systems.
United States
Medicare Advantage expansion for device-based refractory angina interventions is accelerating hospital procurement of transcatheter neuromodulation systems. FDA Breakthrough Device Designation pathways compress review timelines for sympathetic nervous system modulation technologies. Chest pain center networks in Texas, Florida, and the Northeast Corridor are standardizing anti-anginal protocols across emergency and outpatient cardiology workflows.
Germany
Statutory health insurance reimbursement for enhanced external counterpulsation is penetrating outpatient clinic settings following Category III CPT code recognition. EMA Committee for Medicinal Products for Human Use assessments shape formulary placement timelines for novel anti-anginal mechanisms. Hospital procurement consortia in Bavaria and North Rhine-Westphalia are negotiating total-cost-of-ownership contracts for external counterpulsation systems.
Japan
PMDA geriatric-use labeling incentives are opening development pathways for low-burden neuromodulation devices in octogenarian populations. METI industrial policy supports domestic manufacturing of cardiovascular devices through targeted R&D subsidies. University hospitals in Tokyo and Osaka are shifting from capital expenditure models to per-procedure leasing arrangements for angina management technologies.
United Kingdom
NICE health technology assessments are elevating evidence thresholds for device-based angina interventions relative to optimal medical therapy. MHRA post-Brexit regulatory autonomy is creating divergence from EMA approval timelines for novel anti-anginal submissions. London and Southeast England hospital systems are consolidating procurement through centralized tenders that bundle devices with multiyear service agreements.
India
CDSCO accelerated approval pathways for cardiovascular devices are shortening commercialization timelines for multinational sponsors targeting refractory angina populations. Government hospital procurement through centralized tenders is expanding access to generic oral nitrates and beta-blockers. Cardiology centers in Maharashtra and Karnataka are building capacity for transcatheter intervention procedures through public-private partnership models.
Angina Pectoris Market Competitive Environment
On the supply side, the industry is consolidating around pharmaceutical incumbents with cardiovascular manufacturing footprints and emerging device specialists with neuromodulation expertise. Established oral therapy manufacturers leverage high-volume generic production to defend position against branded entrants, while device innovators concentrate manufacturing among European contract partners to access specialized catheter fabrication capabilities. Two strategic archetypes dominate: integrated pharmaceutical conglomerates with global cardiovascular portfolios, and focused device developers with sympathetic nervous system modulation platforms. Competitive moves center on portfolio diversification into adjacent cardiovascular indications and geographic expansion through hospital system partnership agreements.
Among integrated pharmaceutical conglomerates, Pfizer Inc., AstraZeneca, and Novartis AG occupy positions exemplifying scale-driven cost leadership, deep R&D investment in next-generation calcium channel modulation, and geographic dominance in European hospital formulary access respectively. These entities anchor the maintenance therapy segment through established oral formulation supply chains while monitoring device-based substitution threats in refractory angina populations. Their competitive positioning reflects divergent strategic emphases on manufacturing efficiency, pipeline depth, and regional market penetration rather than uniform global approaches.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AstraZeneca |
| Novartis AG |
| Merck & Co., Inc. |
| Bayer AG |
| Sanofi |
| Gilead Sciences |
| GlaxoSmithKline |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
European catheter fabrication clusters in Ireland and Germany anchor margin capture for transcatheter neuromodulation systems, concentrating pricing power among contract manufacturers serving device innovators targeting refractory angina populations.
Pricing Analysis
Hospital procurement managers anchor pricing negotiations through centralized chest pain center networks. Three-tier pricing structure across premium branded anti-anginals, standard generic nitrates, and economy contract-manufactured APIs stratifies the market. Cost compression in oral maintenance therapy intensifies because generic isosorbide mononitrate saturates United States formularies. Outpatient clinics demonstrate highest price sensitivity; academic medical centers with bundled reimbursement models show lowest.
Supply Chain Analysis
Extended payment terms from German hospital procurement consortia are squeezing working capital for device sponsors. Manufacturing concentrates in Ireland, Germany, and Switzerland for specialized catheter fabrication. Supply chains draw from nitroglycerin precursor chemicals, biocompatible polymers, and precision electronics. Single-source vulnerability clusters among three European contract manufacturers. Distribution runs through hospital GPO contracts and specialized cardiovascular device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-based sympathetic modulation is accelerating through FDA Breakthrough Designation pathways, expanding addressable populations beyond exhausted pharmacologic options.
For Market Incumbents: Build formulary lock-in moats through multiyear hospital system partnerships bundling devices with technical service contracts. Deepen backward integration into catheter fabrication to offset European contract manufacturer concentration risk. Anchor capacity addition in United States manufacturing zones to shorten FDA inspection logistics. Certification investment in ISO 13485 recertification ahead of EU MDR audit backlogs protects market access timelines. For New Entrants and Emerging Players: Establish a beachhead in Japanese octogenarian neuromodulation protocols where PMDA geriatric-use labeling incentives reduce competitive density. Target German outpatient clinic digital therapeutic convergence where statutory health insurance reimbursement pathways are opening for remote monitoring platforms paired with anti-anginal adherence programs. Pursue per-procedure leasing arrangements with university hospitals in Tokyo and Osaka as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital therapeutic and remote monitoring sub-segments as software margins displace hardware-heavy device economics. Long-term viability favors platforms combining pharmacologic and neuromodulation modalities with patient-reported outcome infrastructure. Acquisition target archetype: device developers with sympathetic nervous system modulation platforms and existing CE marking progress. Signal to watch: Category III CPT code expansion for enhanced external counterpulsation in additional geographies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review timelines compress commercialization cycles for transcatheter neuromodulation innovators. |
| Hospital System Partnership | Chest pain center networks in Texas and Florida standardize anti-anginal protocol adoption across workflows. |
| Per-Procedure Leasing Arrangement | Tokyo and Osaka university hospitals shift from capital expenditure to operational budgeting for device access. |
| Digital Therapeutic Convergence | German statutory health insurance incorporates remote monitoring platforms with structured exercise regimens. |
| Backward Integration into Catheter Fabrication | In-house production of specialized components mitigates single-source vulnerability among European contract manufacturers. |
Study Parameters
Operator-level perspectives from interventional cardiologists, hospital procurement managers, formulary directors, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA Committee for Medicinal Products for Human Use assessments, ClinicalTrials.gov registries, and hospital GPO contract databases. Bottom-up patient population modeling and top-down health system expenditure analysis provided triangulation.
Scenario-bracketing framed analytical outputs across the projection horizon. Segmentation dimensions modeled include product type, end user, delivery mode, therapy area, and regional regulatory cluster. CAGRs derived from historical procedure volume trajectories, reimbursement pathway expansion rates, and technology substitution elasticities. Forecast inputs incorporated chest pain center network buildout timelines and PMDA geriatric-use labeling incentive uptake curves.
Stress conditions across FDA review timeline variability, EMA health technology assessment heterogeneity, and generic oral nitrate pricing erosion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sympathetic nervous system modulation clinical evidence standards and catheter manufacturing capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Tachycardia Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Bifurcation Lesions Market