
 Cardiovascular Pledgets Market | 2026-2036
Cardiovascular Pledgets Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Pledgets Market Analytics
Cardiovascular clinics are rotating toward absorbable pledget procurement as cardiac surgery volumes shift from open procedures to minimally invasive interventions. Medtronic leverages its integrated cardiovascular portfolio to sustain hospital system contracts across multiple pledget formats. B. Braun Melsungen AG anchors European surgical supply chains through specialized distribution for cardiac centers. Johnson & Johnson differentiates via its broad suture-pledget bundling strategy that controls operating room procurement workflows.
Cardiovascular pledgets are small, flat reinforcing pads—typically composed of braided polyester, cotton, or polypropylene nonwoven matrices—sutured alongside cardiac or vascular tissue to distribute tension and prevent suture pull-through during valve replacement, aneurysm repair, or septal defect closure. Absorbable pledgets manufactured from biodegradable polymers such as polydioxanone or polyglycolic acid eliminate permanent foreign body retention and reduce long-term infection risk in pediatric and redo cardiac surgery. Polyester pledgets dominate current surgical volume due to decades of hemocompatibility validation and established tensile strength profiles, while biodegradable polymer pledgets represent the fastest-growing material segment as hospitals prioritize reduced foreign material burden and regulatory pathways for absorbable implants mature.
FDA 510(k) clearance requirements and EU MDR Class III device regulations shape cardiovascular pledget design standards, biocompatibility testing protocols, and post-market surveillance obligations for manufacturers seeking transatlantic market access. The country's national pharmaceutical regulator in India and CDSCO enforce incremental quality control mandates that filter substandard imports and elevate domestic production benchmarks. Stakeholders must monitor evolving absorbable polymer degradation data and regulatory harmonization between FDA and EMA to align R&D pipelines with the material transition unfolding across cardiac surgery procurement.
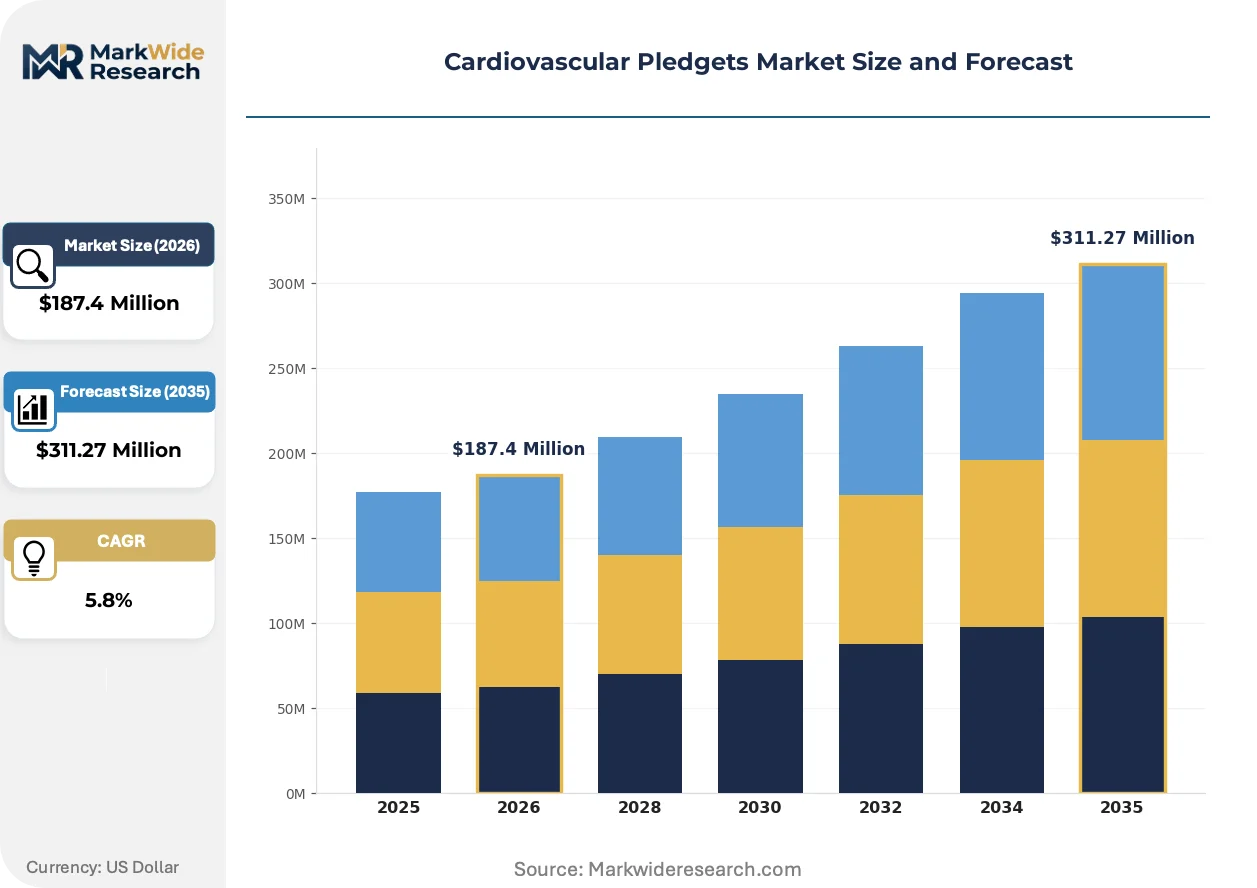
Market Dynamics
Cardiovascular pledget demand is fragmenting across material types as absorbable polymer formulations gain surgical preference against established polyester standards, creating procurement bifurcation in cardiac centers.
Growth Catalysts
- Minimally Invasive Valve Surgery Expansion:Transcatheter and robotic-assisted cardiac procedures require specialized pledget geometries that distribute suture tension through smaller access ports, driving format innovation in tertiary hospital surgical suites.
- FDA 510(k) Pathway Maturation:Streamlined clearance mechanisms for absorbable cardiovascular implants accelerate biodegradable polymer pledget commercialization timelines relative to permanent implant categories.
- Pediatric Cardiac Volume Concentration:Absorbable pledget demand concentrates in pediatric cardiac surgery centers where foreign body elimination reduces long-term infection surveillance burden.
Market Restraints
- EU MDR Class III Compliance Burden:Extended clinical evaluation requirements and notified body capacity constraints delay absorbable pledget market entry for European manufacturers.
- Polymer Raw Material Concentration:Medical-grade polydioxanone and polyglycolic acid supply chains concentrate among specialty chemical producers in Germany and Switzerland, creating input cost volatility.
- Established Polyester Validation Depth:Decades of hemocompatibility data for braided polyester pledgets create clinical inertia against absorbable alternatives despite theoretical advantages.
Strategic Opportunities
- India CDSCO Regulatory Alignment:India's incremental quality control mandates for cardiovascular implants filter substandard imports and elevate domestic production benchmarks for compliant manufacturers.
- Redo Surgery Application Expansion:Absorbable pledget utilization in reoperative cardiac procedures addresses adhesive complications from prior permanent implant retention.
- Suture-Pledget Bundling Integration:Control over combined suture-pledget procurement workflows creates channel leverage through operating room standardization contracts.
Industry Challenges
- Absorbable Degradation Data Generation:Long-term polymer degradation profiles in cardiac tissue environments require extended follow-up studies that compress R&D timelines.
- Biocompatibility Testing Protocol Harmonization:Divergent FDA and EMA testing standards for absorbable cardiovascular materials force redundant validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Pledgets Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Pledgets, Absorbable Pledgets, Non-Absorbable Pledgets, Specialty Pledgets End User: Hospitals, Surgical Centers, Cardiovascular Clinics, Research Institutions Material: Polyester, Cotton, Polypropylene, Biodegradable Polymers Application: Cardiac Surgery, Vascular Surgery, Wound Closure, Tissue Healing |
| Companies Covered | Medtronic, B. Braun Melsungen AG, Medline Industries, Inc., Johnson & Johnson, Teleflex Incorporated, Peters Surgical, Dolphin Sutures, Aesculap, Inc., DeRoyal Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Pledgets Market Evolving Landscape
Material science convergence with regulatory science is redefining cardiovascular pledget competitive positioning, separating manufacturers with integrated absorbable polymer capabilities from legacy polyester-dependent suppliers.
Biodegradable polymer pledget technology is fragmenting established market structures as polydioxanone and polyglycolic acid formulations demonstrate equivalent tensile strength to polyester during the critical 6-8 week cardiac tissue healing window. Academic medical centers in the United States are piloting absorbable formats in pediatric septal defect closures and valve annuloplasties where permanent foreign body elimination aligns with long-term patient surveillance reduction. This material transition is fragmenting procurement categories, forcing hospitals to maintain dual inventory systems and retraining surgical teams on degradation-rate considerations.
EU MDR Class III device regulations are compressing commercialization timelines for novel absorbable pledget entrants through enhanced post-market surveillance obligations and clinical evidence requirements. Manufacturers must now generate real-world performance data across diverse cardiac surgery populations to maintain CE marking validity. European cardiac surgery centers are responding by consolidating supplier relationships toward established players with regulatory infrastructure capacity, reducing vendor fragmentation in high-complexity procedures.
Hospital value analysis committees are unbundling suture-pledget procurement from traditional surgical supply contracts, creating direct manufacturer engagement opportunities outside distributor intermediaries. This channel compression is most visible in United States academic medical centers where cardiac surgery volumes justify dedicated supply chain personnel. Tiered pricing negotiations now separate premium absorbable formats from standard polyester lines through performance-based contracting rather than commodity bundling.
Cardiovascular Pledgets Market Segmentation
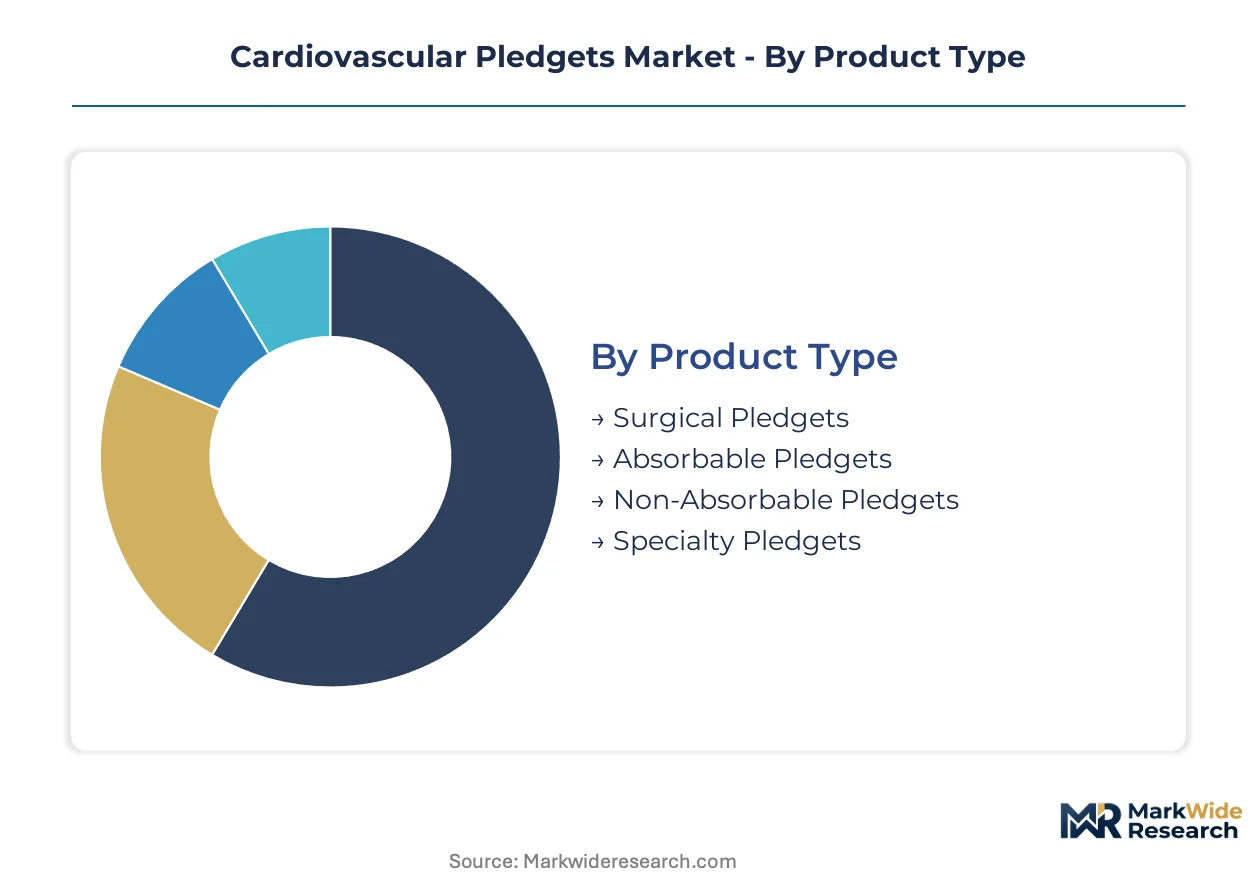
Cardiovascular pledget procurement channels bifurcate between high-volume hospital systems and specialized cardiac centers, with material composition and application specificity driving distinct distribution pathways. Segmentation clarity enables manufacturers to align R&D investment with the surgical workflows and regulatory requirements of each channel.
Product Type:
Channel mix varies sharply across product formats, with surgical pledgets flowing through broadline distributors while absorbable variants require direct manufacturer engagement for clinical training and value analysis committee presentations.
- Surgical Pledgets:Braided polyester or polypropylene pads designed for general cardiac reinforcement procedures. Demand concentrates in United States tertiary hospitals where high-volume valve replacement programs drive standardized procurement contracts.
- Absorbable Pledgets:Biodegradable polymer matrices—polydioxanone or polyglycolic acid—engineered for complete tissue resorption within 6-12 months. Pediatric cardiac centers in Germany and Switzerland prioritize these formats to eliminate long-term foreign body surveillance burden.
- Non-Absorbable Pledgets:Permanent implant-grade polyester configurations for structural cardiac repairs requiring lifelong tensile support. Cardiac surgery departments in India source these through regional distributors serving price-sensitive institutional buyers.
- Specialty Pledgets:Custom-shaped or coated variants for robotic-assisted and transcatheter procedures. Academic medical centers in Boston and Cleveland pilot these through limited distribution agreements with device innovators.
By volume, surgical pledgets lead. By growth pace, absorbable formats are climbing the fastest.
End User:
Customer type determines pricing architecture and contract structure, with hospital systems leveraging scale for bundled suture-pledget agreements while surgical centers prioritize flexibility over volume discounts.
- Hospitals:Integrated health systems with dedicated cardiac surgery departments. United States academic medical centers in New York and California drive premium absorbable pledget adoption through value-based procurement frameworks.
- Surgical Centers:Ambulatory facilities performing elective cardiac and vascular interventions. German outpatient cardiac centers favor standardized polyester formats through group purchasing organizations.
- Cardiovascular Clinics:Specialized practices focusing on diagnostic and interventional cardiology. Mumbai and Delhi clinics increasingly stock absorbable pledgets for pediatric septal defect closures.
- Research Institutions:Academic and clinical trial sites evaluating novel polymer formulations. Swiss university hospitals in Zurich and Geneva anchor biodegradation studies for next-generation pledget materials.
Hospitals capture the largest revenue share. Cardiovascular clinics are expanding most quickly as minimally invasive procedures migrate to outpatient settings.
Material:
Raw material selection governs regulatory pathway complexity and manufacturing scale economics, with established polymers flowing through validated supply chains while biodegradable alternatives require specialized polymerization capabilities.
- Polyester:Braided polyethylene terephthalate fibers with decades of hemocompatibility validation. Dominates procurement in United States cardiac surgery programs where clinical inertia favors proven performance profiles.
- Cotton:Natural fiber pledgets for cost-sensitive applications and specific tissue adhesion requirements. Indian domestic manufacturers supply these to regional hospitals through CDSCO-compliant production facilities.
- Polypropylene:Nonwoven synthetic matrices offering chemical resistance and dimensional stability. German cardiac centers specify these for vascular anastomosis procedures requiring precise suture placement.
- Biodegradable Polymers:Polydioxanone and polyglycolic acid formulations eliminating permanent implant burden. Pediatric cardiac units in Switzerland and the United States drive demand as regulatory pathways for absorbable cardiovascular materials mature.
Polyester commands current volume leadership. Biodegradable polymers hold the steepest expansion trajectory as FDA 510(k) pathways for absorbable implants streamline.
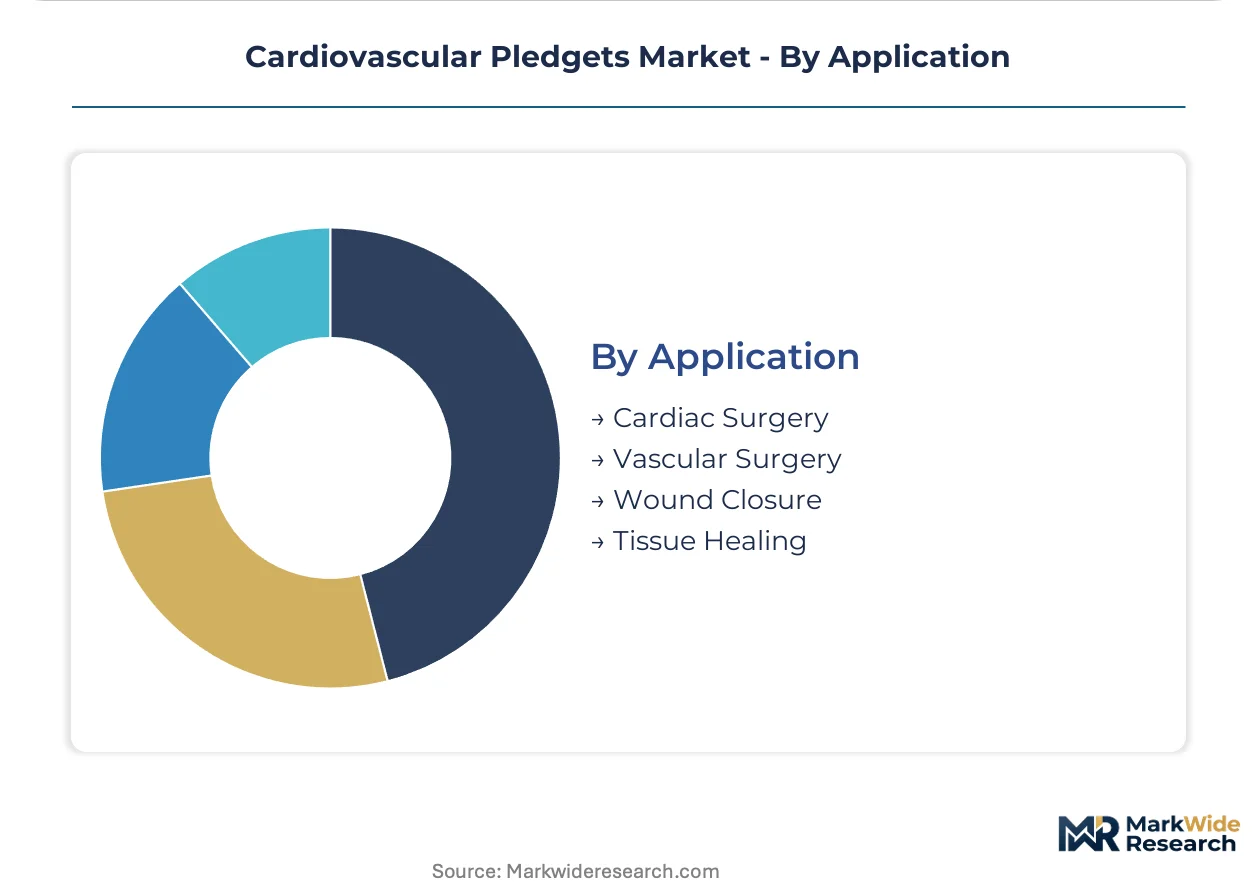
Application:
Procedure-specific requirements fragment the market into distinct technical specifications, with cardiac surgery demanding highest performance tiers while wound closure applications tolerate broader material variability.
- Cardiac Surgery:Valve replacement, annuloplasty, and septal defect closure procedures requiring precise tension distribution. United States academic medical centers specify premium absorbable formats for pediatric interventions.
- Vascular Surgery:Aneurysm repair and bypass grafting applications where suture line reinforcement prevents hemorrhage. German vascular surgery departments favor polyester pledgets for aortic procedures.
- Wound Closure:General surgical applications extending beyond cardiovascular specialties. Indian multispecialty hospitals procure cotton and polypropylene formats through consolidated surgical supply contracts.
- Tissue Healing:Regenerative and reconstructive procedures leveraging pledget-mediated tissue approximation. Research institutions in Switzerland investigate biodegradable polymer integration with cellular scaffolding technologies.
Cardiac surgery generates highest absolute volume. Tissue healing applications are gaining share fastest as regenerative medicine protocols expand pledget utility beyond traditional cardiovascular domains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export absorbable polymer pledgets to United States academic medical centers, establishing the primary transatlantic trade corridor for biodegradable cardiovascular implants.
United States
Pediatric cardiac surgery volumes at Boston Children's Hospital and Cleveland Clinic drive absorbable pledget procurement. FDA 510(k) pathway maturation accelerates biodegradable polymer commercialization timelines. The Texas Medical Center in Houston anchors high-volume valve replacement programs that standardize polyester pledget contracts.
Germany
Specialty chemical producers in Ludwigshafen and Leverkusen supply medical-grade polydioxanone for absorbable pledget matrices. EU MDR Class III regulations compress commercialization timelines through enhanced post-market surveillance. The Berlin-Brandenburg corridor concentrates cardiac surgery research institutions evaluating next-generation biodegradable formulations.
Switzerland
Swiss university hospitals in Zurich and Geneva anchor biodegradation studies for pediatric applications. Swissmedic maintains stringent implantable device standards that filter substandard imports. The Basel pharmaceutical cluster integrates cardiovascular pledget development with broader absorbable polymer R&D pipelines.
India
Domestic cotton pledget production serves cost-sensitive regional hospitals through CDSCO-compliant facilities in Ahmedabad and Mumbai. The country's national pharmaceutical regulator enforces incremental quality control mandates that elevate domestic production benchmarks. Tamil Nadu cardiac centers increasingly source absorbable formats for pediatric septal defect closures.
Cardiovascular Pledgets Market Competitive Landscape
Listed leaders compete with private specialists across regulatory infrastructure capacity, creating tiered market access where public company scale advantages meet private firm agility in absorbable polymer development. The vendor base concentrates around established cardiovascular device conglomerates with integrated suture-pledget bundling capabilities and specialized regional distributors serving price-sensitive institutional buyers. Three archetypes dominate: integrated cardiovascular portfolio holders, European surgical supply chain anchors, and domestic cost-optimized manufacturers. Competitive moves center on suture-pledget procurement workflow control and absorbable polymer regulatory pathway navigation.
Within the integrated portfolio tier, Medtronic and Johnson & Johnson exemplify scale-driven channel leverage through hospital system contracts across multiple pledget formats. B. Braun Melsungen AG occupies a specialist position anchoring European cardiac center supply chains through dedicated distribution infrastructure. These three entities represent the concentration of regulatory science capabilities and value analysis committee engagement capacity that defines competitive positioning in absorbable cardiovascular materials.
| Leading Market Players |
|---|
| Medtronic |
| B. Braun Melsungen AG |
| Medline Industries, Inc. |
| Johnson & Johnson |
| Teleflex Incorporated |
| Peters Surgical |
| Dolphin Sutures |
| Aesculap, Inc. |
| DeRoyal Industries, Inc. |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance tiers and EU MDR Class III certification gates simultaneously filter supplier qualification and stratify price bands across cardiovascular pledget procurement, with absorbable polymer formats commanding premium positioning against commodity polyester lines.
Pricing Analysis
Next-generation absorbable pledgets trade at substantial premiums over established polyester configurations, while prior-generation cotton formats face cost compression in price-sensitive Indian hospital procurement. Three-tier pricing structure across premium absorbable, standard polyester, and economy cotton levels reflects certification depth and hemocompatibility validation burden. Pricing pressure stems from raw material concentration in German and Swiss specialty chemical producers. Pediatric cardiac centers in Boston and Zurich exhibit lowest price sensitivity due to clinical outcome prioritization, while Indian regional hospitals drive hardest bargain negotiations.
Supply Chain Analysis
Inbound logistics costs from Basel and Ludwigshafen chemical clusters to United States academic medical centers have intensified procurement negotiation leverage for domestic distributors. Medical-grade polydioxanone and polyglycolic acid supply concentrates in Germany, Switzerland, and limited United States specialty polymer facilities. Raw material dependencies rest on petroleum-derived monomer feedstocks and precision polymerization equipment. Single-source vulnerability characterizes medical-grade biodegradable polymer supply chains. Distribution runs through dedicated cardiovascular device distributors with hospital system contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
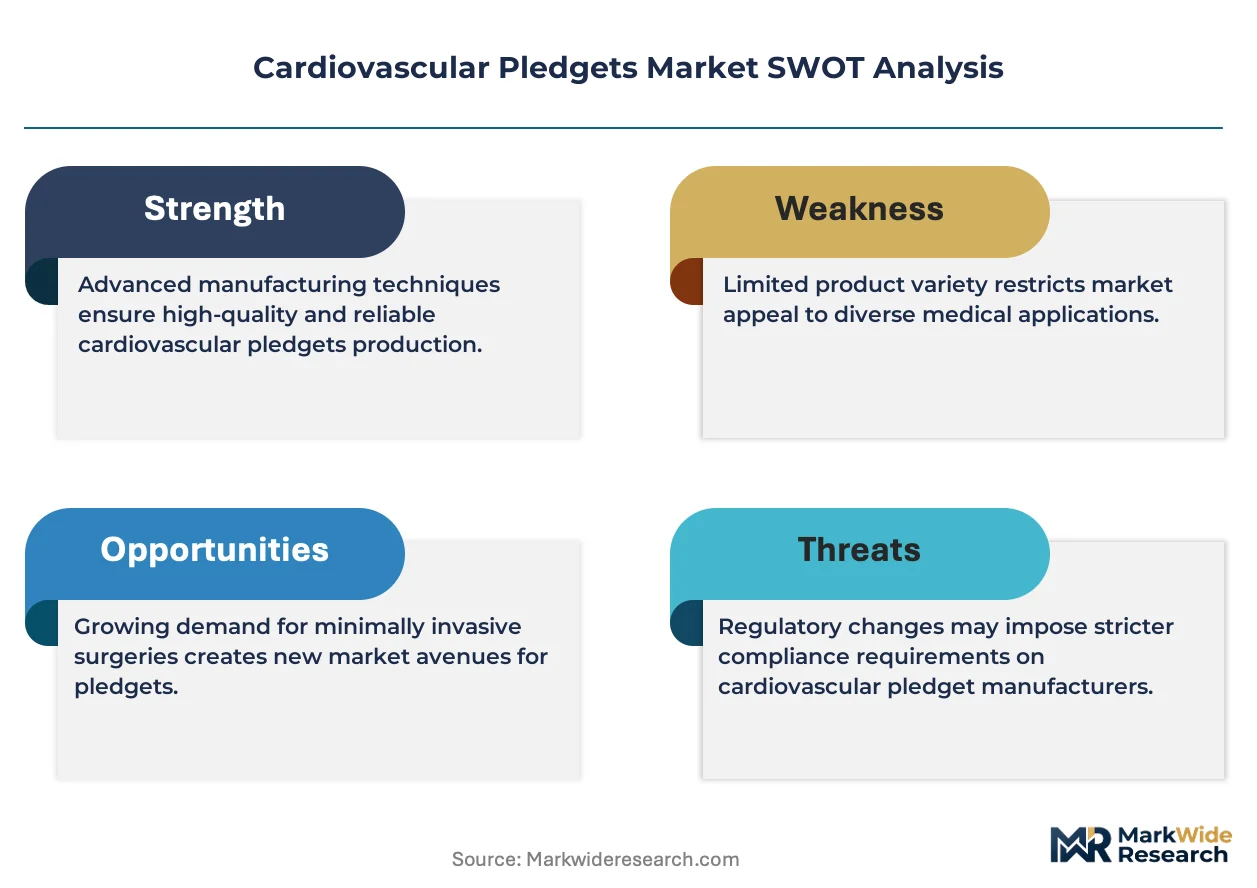
Absorbable polymer pledgets constitute a substitution threat against established polyester incumbents, forcing defensive repositioning across material science capabilities and regulatory pathway navigation.
For Market Incumbents: Fortify polyester supply contracts through backward integration into braided fiber manufacturing and exclusive hospital system partnerships that bundle suture-pledget procurement workflows. Absorbable polymer entrants threaten volume displacement in pediatric segments; counter through accelerated FDA 510(k) submissions for hybrid material formats. For New Entrants and Emerging Players: Differentiate on biodegradable polymer degradation-rate customization for pediatric cardiac applications, where permanent foreign body elimination drives clinical preference. White-space concentration sits in Indian CDSCO-compliant manufacturing for cost-optimized absorbable formats and Swiss university hospital research partnerships for next-generation tissue scaffolding integration. Direct manufacturer engagement with United States academic medical center value analysis committees offers the most penetrable go-to-market channel outside established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across absorbable polymer R&D and regulatory compliance infrastructure, favoring scaled players with existing cardiovascular device portfolios. Long-term viability over the coming decade rests on regulatory science capabilities and hospital system contracting relationships rather than manufacturing scale alone. Acquisition target archetype: specialized biodegradable polymer manufacturers with FDA 510(k) clearances and European notified body relationships. Signal to watch: EU MDR Class III notified body capacity expansion timelines as inflection indicator for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance pathways for absorbable pledgets compress commercialization timelines against permanent implant categories. |
| Hospital System Partnership | Direct engagement with United States academic medical centers secures value analysis committee approval outside distributor intermediaries. |
| Backward Integration into Polymer Production | In-house medical-grade polydioxanone manufacturing reduces German and Swiss specialty chemical supplier dependency. |
| CE Marking Pathway Investment | EU MDR Class III compliance infrastructure builds European cardiac center access against notified body capacity constraints. |
| Software Companion Development | Digital surgical planning tools integrating pledget selection algorithms strengthen operating room workflow control. |
Research Methodology
Operator-level perspectives from cardiac surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers anchored the qualitative base, cross-referenced against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and cardiovascular device SEC disclosures. Bottom-up volume modeling across material types and top-down market sizing triangulated demand estimates.
Sensitivity analysis framed scenario outputs across absorbable polymer adoption trajectories and regulatory pathway maturation speeds. Segmentation dimensions modeled include material composition, product format, end-user facility type, application procedure, and regional regulatory cluster. CAGRs derived from procedure volume projections, material substitution elasticity, and pricing trajectory assumptions. Industry-specific inputs encompassed cardiac surgery volume data from United States academic medical centers and EU MDR implementation timelines.
The analysis sits within stated boundaries; outcomes outside FDA-EU regulatory harmonization progress or absorbable polymer degradation data generation would require recalibration. Forecasts reflect documented assumptions regarding minimally invasive procedure migration and pediatric cardiac surgery volume concentration. Biodegradable polymer supply chain disruption or notified body capacity bottlenecks represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Global Statin Market
Cardiovascular
Tachycardia Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Bifurcation Lesions Market