
 Global Cardiac Resuscitation Device Market | 2026-2036
Global Cardiac Resuscitation Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Resuscitation Device Market Foresight
Public access programs and sports facilities are collapsing the historical hospital-centric purchasing model for cardiac resuscitation equipment. Medtronic plc dominates implantable cardioverter defibrillator manufacturing through captive supply of leads and batteries. ZOLL Medical Corporation competes aggressively in the automated external defibrillator segment with portable units designed for lay rescuers. Koninklijke Philips N.V. leverages its diagnostic imaging heritage to bundle resuscitation devices with patient monitoring ecosystems.
Cardiac resuscitation devices encompass electromechanical systems that restore effective heart rhythm through defibrillation, pacing, or mechanical chest compression, typically operating with biphasic waveforms between 120 and 360 joules and battery autonomy exceeding 200 shocks. Their primary purpose is to interrupt ventricular fibrillation or pulseless ventricular tachycardia and restore perfusing rhythm in out-of-hospital and in-hospital cardiac arrest scenarios. Implantable cardioverter defibrillators anchor the highest margin pool due to recurring replacement cycles and specialized surgical placement requirements. Wireless communication modules within wearable cardioverter defibrillators represent the fastest-growing technology segment as remote patient monitoring reimbursement expands. Emergency medical services applications sustain the largest volume throughput given fleet deployment across ambulance networks.
The FDA's 510(k) pathway governs automated external defibrillator market entry in the United States, while the EU MDR demands clinical performance studies for implantable devices sold across European member states. Japan's PMDA enforces JIS standards for electromagnetic compatibility that constrain design architectures for devices entering that market. Stakeholders must monitor evolving post-market surveillance requirements as regulators tighten traceability for battery and capacitor components across jurisdictions.
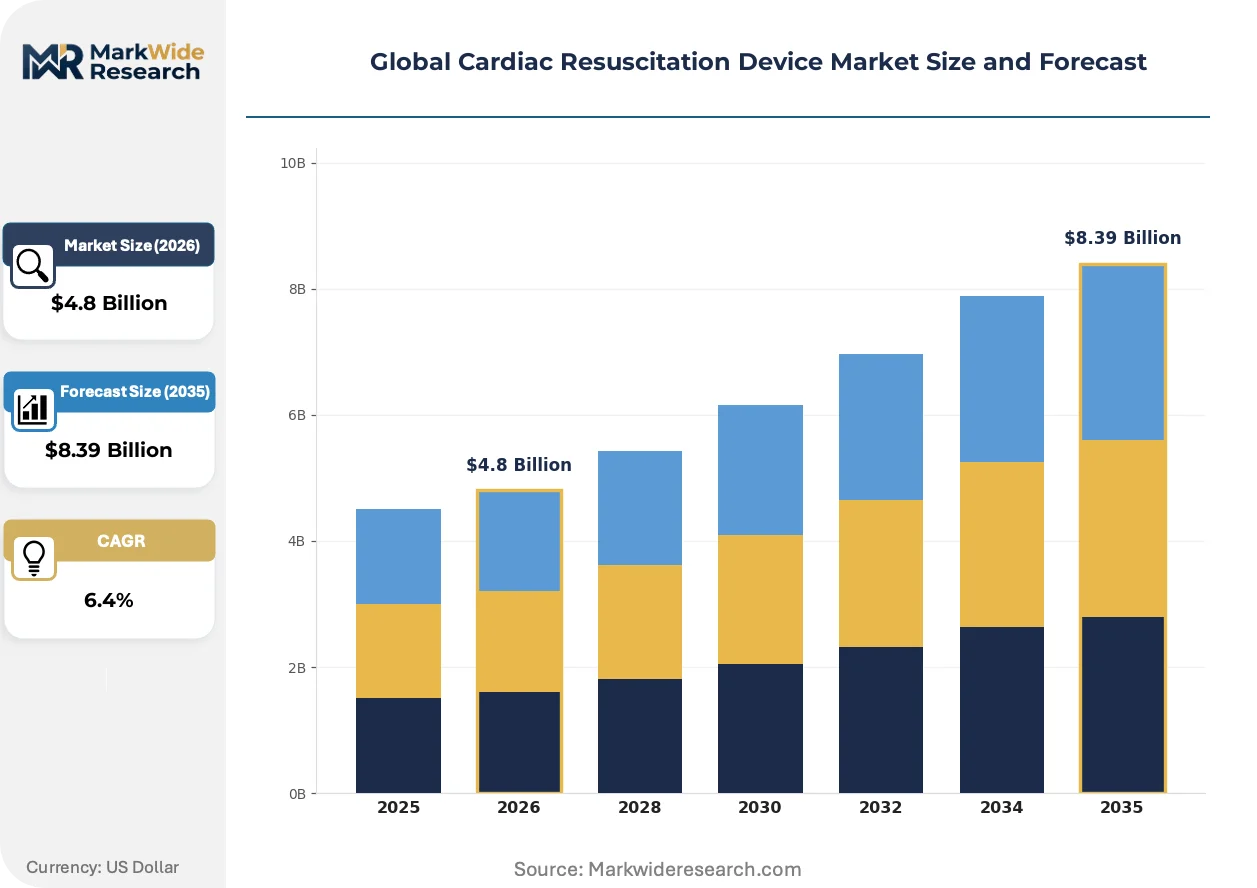
Market Dynamics
Hospital-centric procurement of automated external defibrillators is collapsing as public access programs and sports facilities capture volume, while the EU MDR's stricter clinical evidence requirements compress certification timelines for implantable devices.
Growth Catalysts
- Public Access Defibrillation Mandates:Municipal governments across the United States, Germany, and Japan are legislating AED deployment in transportation hubs and educational institutions.
- Wireless Remote Monitoring:Cellular and Bluetooth modules in wearable cardioverter defibrillators enable continuous patient surveillance and reduce emergency department utilization.
- Aging Demographics:Cardiovascular disease prevalence in populations over sixty-five drives replacement cycles for implantable cardioverter defibrillators in developed economies.
Market Restraints
- Battery Supply Concentration:Lithium manganese dioxide cell production concentrates in East Asian manufacturing clusters, exposing device makers to raw material volatility and logistics disruption.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation demands prospective performance studies for implantable defibrillators, extending time-to-market by eighteen to thirty-six months.
- Technical Limitation of Biphasic Waveforms:Energy delivery optimization for high-impedance patients remains unresolved, constraining efficacy in obese populations.
Strategic Opportunities
- Underpenetrated Rural India:District hospital networks lack automated external defibrillator coverage, creating first-mover advantage for portable units with simplified Hindi-language interfaces.
- Home-Based Cardiac Monitoring:Wearable cardioverter defibrillators with cloud-connected diagnostics address post-myocardial infarction patients discharged to residential settings.
- Japan's PMDA Streamlined Review:The Sakigake designation pathway accelerates approval for devices incorporating novel algorithms, rewarding early regulatory engagement.
Industry Challenges
- Electrophysiologist Training Bottleneck:Complex lead extraction procedures require specialized surgical expertise that residency programs fail to produce at replacement-cycle velocity.
- Post-Market Surveillance Compliance:FDA and EU MDR traceability mandates for battery and capacitor components force manufacturers to reconfigure quality management systems.
- Legacy Device Interoperability:New wireless communication modules must interface with installed patient monitoring ecosystems from competing diagnostic imaging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Resuscitation Device Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated External Defibrillators, Manual Defibrillators, Implantable Cardioverter Defibrillators, Wearable Cardioverter Defibrillators Technology: Electromechanical, Ultrasonic, Optical Sensor, Wireless Communication, Battery Operated, Rechargeable Application: Emergency Medical Services, Cardiac Care Units, Ambulatory Services, Public Access Programs, Sports Facilities End User: Hospitals, Clinics, Paramedic Teams, Rehabilitation Centers, Diagnostic Laboratories |
| Companies Covered | Medtronic plc, Stryker Corporation, ZOLL Medical Corporation, Koninklijke Philips N.V., Physio-Control, Drägerwerk AG & Co. KGaA, Nihon Kohden Corporation, Mindray Medical, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Resuscitation Device Market Shifts & Advancements
Real-time rhythm analysis algorithms and miniaturized capacitor technology are compressing device form factors while expanding deployment settings beyond traditional clinical environments.
Subcutaneous implantable cardioverter defibrillator technology is decomposing the transvenous lead market by eliminating vascular access complications. Electrophysiologists in tertiary centers across the United States and Germany are adopting these systems for patients with compromised venous anatomy. The structural consequence is a bifurcation in surgical training requirements and a compression of lead extraction service revenue.
The EU MDR's post-market clinical follow-up requirements are forcing manufacturers to fund long-term registries for implantable devices. This policy creates sustained data collection obligations that favor large device makers with dedicated epidemiology departments. Implantable cardioverter defibrillator portfolios face the steepest compliance burden as notified bodies scrutinize lead fracture rates and battery longevity claims.
Sports facility managers and corporate wellness directors are consolidating purchasing authority for automated external defibrillators through group procurement organizations. This channel concentration displaces traditional medical equipment distributors and compresses margin structures for manufacturers. The United States exhibits the most pronounced shift, with collegiate athletic conferences and municipal park districts issuing multi-year fleet contracts.
Global Cardiac Resuscitation Device Market Segmentation
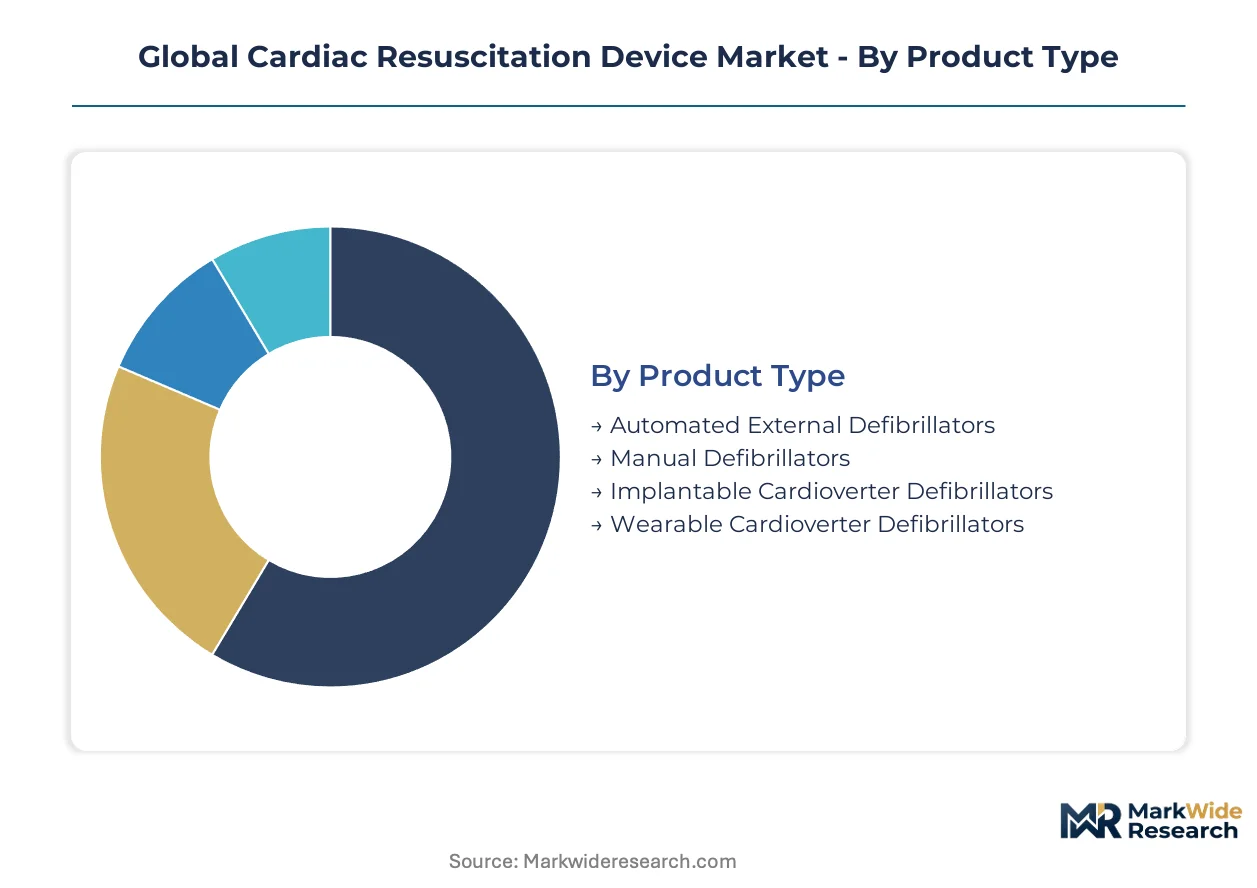
Segmentation in cardiac resuscitation devices reveals divergent margin structures and channel economics across product architectures. Procurement patterns for implantable systems differ fundamentally from public-access automated units, requiring distinct commercial strategies.
Product Type:
Channel mix varies sharply: implantable devices flow through electrophysiology specialists and hospital cardiac catheterization labs, while automated external defibrillators reach end-users through group purchasing organizations and municipal procurement.
- Automated External Defibrillators:Portable biphasic units delivering 120-360 joules with voice-guided operation for lay rescuers. Demand concentrates in United States municipal park districts and German transportation authorities driven by public access legislation mandating deployment in high-traffic venues.
- Implantable Cardioverter Defibrillators:Transvenous and subcutaneous systems with lithium silver vanadium oxide batteries requiring surgical placement. Demand concentrates in Japan's tertiary cardiac centers and United States academic medical centers driven by aging demographics and replacement cycle velocity.
- Manual Defibrillators:Hospital-grade devices with manual energy selection and synchronized cardioversion capability for clinical professionals.
- Wearable Cardioverter Defibrillators:Vest-based systems with wireless telemetry for post-myocardial infarction patients awaiting implantation decisions.
By volume, automated external defibrillators lead. By growth pace, wearable cardioverter defibrillators are expanding most quickly.
Technology:
Cost tier stratification separates premium wireless-enabled systems from basic battery-operated units, with reimbursement codes driving adoption thresholds.
- Wireless Communication:Cellular and Bluetooth modules enabling remote monitoring and cloud-based diagnostic transmission. Demand concentrates in wearable cardioverter defibrillators deployed for home-based cardiac surveillance in United States post-acute care settings.
- Battery Operated:Lithium manganese dioxide primary cells powering automated external defibrillators with 200+ shock autonomy. Demand concentrates in emergency medical services fleets across Germany and Japan driven by field reliability requirements and cold-weather performance specifications.
- Electromechanical:Biphasic waveform generation through capacitor-discharge circuitry with impedance compensation.
- Ultrasonic:Emerging energy delivery mechanisms for specialized cardiac rhythm restoration applications.
- Optical Sensor:Photoplethysmography integration for pulse detection and rhythm confirmation.
- Rechargeable:Lithium-ion secondary cells for wearable systems with daily charging protocols.
By installed base, battery operated systems dominate. By expansion trajectory, wireless communication modules are climbing the fastest.
Application:
Customer type determines specification requirements: emergency medical services demand ruggedized portability while sports facilities prioritize simplified operation protocols.
- Emergency Medical Services:Fleet-deployed manual and automated defibrillators with 12-lead ECG capability and data transmission. Demand concentrates in ambulance networks across the United States and Germany driven by response time metrics and regional cardiac arrest survival initiatives.
- Public Access Programs:Wall-mounted automated external defibrillators with multilingual voice prompts and self-test functionality. Demand concentrates in Japanese railway stations and United States educational institutions driven by legislative mandates and liability risk mitigation.
- Cardiac Care Units:Hospital-based manual defibrillators integrated with patient monitoring ecosystems.
- Ambulatory Services:Transportable units for inter-facility patient transfer with continuous monitoring.
- Sports Facilities:Lightweight automated external defibrillators with pediatric attenuation pads for athletic venue deployment.
By throughput volume, emergency medical services leads. By policy momentum, public access programs are gaining share fastest.
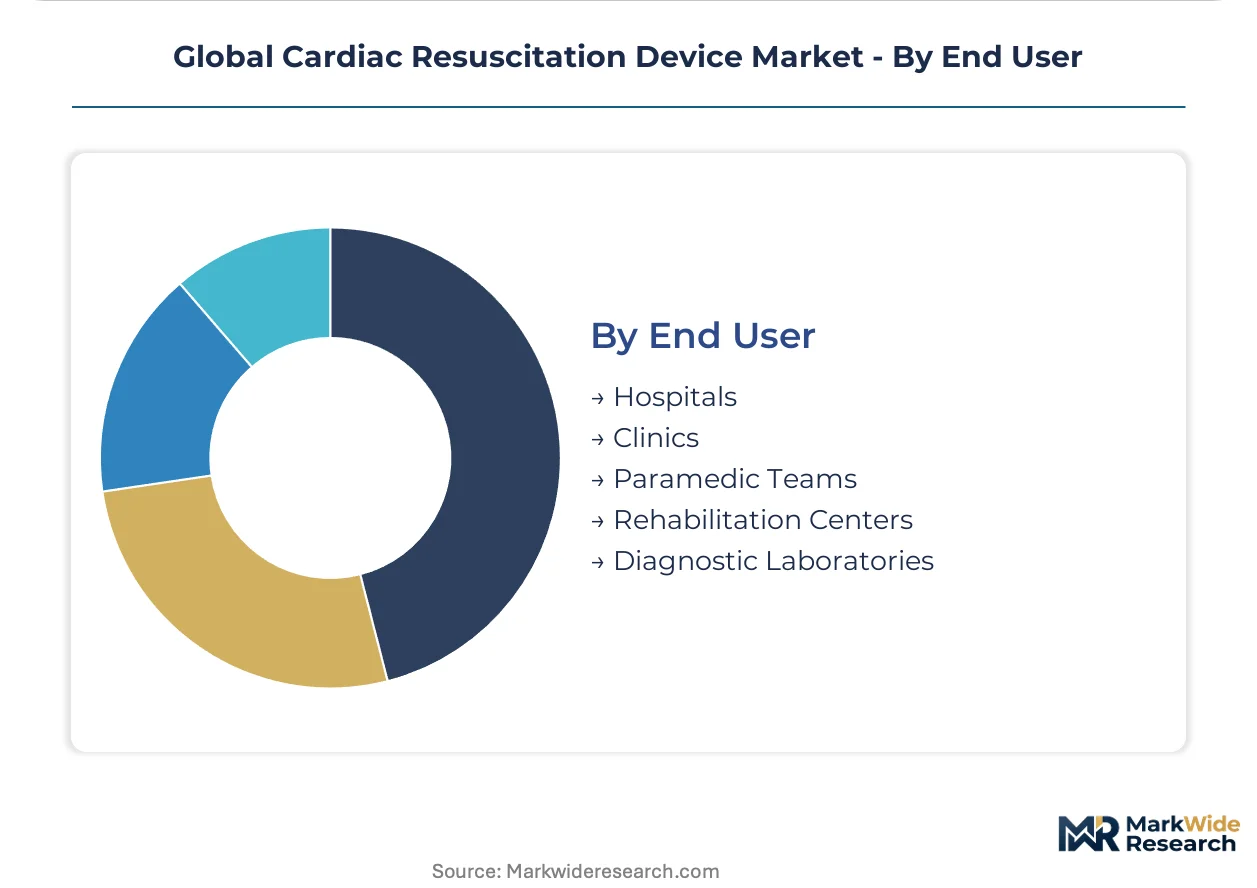
End User:
Supply concentration favors integrated device manufacturers serving hospital systems, while paramedic team procurement fragments across regional distributors.
- Hospitals:Comprehensive defibrillator portfolios spanning manual units, automated external defibrillators for crash carts, and implantable device programs. Demand concentrates in United States integrated delivery networks and German university hospitals driven by capital equipment replacement cycles and electrophysiology service line expansion.
- Paramedic Teams:Field-hardened manual defibrillators with defibrillation-pacing combination capability and vehicle mounting systems. Demand concentrates in municipal fire-rescue departments across Japan and Germany driven by fleet standardization protocols and interoperability requirements with receiving hospital systems.
- Clinics:Automated external defibrillators for primary care and specialty outpatient settings.
- Rehabilitation Centers:Monitoring-integrated systems for post-cardiac event recovery programs.
- Diagnostic Laboratories:Defibrillation backup systems for stress testing and imaging suites.
By procurement value, hospitals lead. By fleet refresh velocity, paramedic teams are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Germany, Japan, and the United States where electrophysiology infrastructure and emergency medical service fleets anchor procurement volume. Device certification timelines diverge sharply across FDA, EU MDR, and PMDA jurisdictions, fragmenting market entry strategies.
United States
Integrated delivery networks in Texas and the Northeast Corridor drive replacement cycles for implantable cardioverter defibrillators. The FDA's 510(k) pathway governs automated external defibrillator market entry, compressing premarket timelines relative to implantable systems. ZOLL Medical Corporation and Physio-Control anchor manufacturing and distribution operations in Massachusetts and Washington state.
Germany
University hospitals in Bavaria and North Rhine-Westphalia concentrate electrophysiology service line expansion. The EU MDR demands prospective clinical performance studies for implantable devices, extending certification by eighteen to thirty-six months. Drägerwerk AG & Co. KGaA maintains production facilities in Lübeck serving EMS fleet procurement across municipal fire-rescue departments.
Japan
Tertiary cardiac centers in Tokyo and Osaka sustain demand for transvenous and subcutaneous implantable systems. PMDA enforces JIS standards for electromagnetic compatibility that constrain design architectures for devices entering the market. Nihon Kohden Corporation anchors domestic manufacturing in Tokyo-to, supplying both hospital and ambulance network procurement.
China
District hospital networks in Shanghai and Guangdong province lack automated external defibrillator coverage, creating deployment gaps for portable units. NMPA regulatory review timelines for Class III medical devices extend market entry for foreign manufacturers. Mindray Medical anchors domestic production in Shenzhen, serving both public hospital procurement and export markets.
Global Cardiac Resuscitation Device Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates controlling captive supply of leads, batteries, and capacitor components. Three to five integrated players dominate implantable device manufacturing while specialized firms compete in automated external defibrillator portability and lay-rescuer interface design. Strategic moves center on M&A for electrophysiology service line integration and vertical control over lithium battery cell supply.
Among diversified conglomerates, Medtronic plc and Stryker Corporation exemplify the integrated archetype through in-house production of critical components and broad hospital system contracting authority. ZOLL Medical Corporation occupies a specialist position in portable automated external defibrillator design, competing on form factor and voice-guided operation protocols for non-clinical deployment settings.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| ZOLL Medical Corporation |
| Koninklijke Philips N.V. |
| Physio-Control |
| Drägerwerk AG & Co. KGaA |
| Nihon Kohden Corporation |
| Mindray Medical |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Capacity utilization at lithium silver vanadium oxide cell facilities in Japan and the United States shapes both component pricing floors and the bargaining position of integrated device manufacturers serving hospital cardiac catheterization labs and emergency medical service fleets.
Pricing Analysis
Volume-discount tiering structures separate automated external defibrillator procurement for municipal fleet deployment from single-unit sales to sports facilities and corporate wellness programs. Pricing stratifies across FDA 510(k) certified premium systems, standard CE-marked units for European public access programs, and economy-tier devices for emerging market district hospitals. Cost compression in the economy tier is intensifying because East Asian manufacturers are flooding portable unit production. Sports facility managers exhibit the highest price sensitivity due to consolidated group purchasing organization leverage, while electrophysiology specialists in tertiary cardiac centers prioritize lead reliability over unit cost.
Supply Chain Analysis
Inbound logistics costs for lithium manganese dioxide cells from East Asian manufacturing clusters have stabilized following port congestion normalization on transpacific trade lanes, though container availability remains volatile for just-in-time battery replenishment. Component sourcing draws from Japan for precision capacitors, South Korea for semiconductor modules, and China for molded device housings. Single-source vulnerability concentrates in transvenous lead fabrication, where Medtronic plc and Boston Scientific Corporation control proprietary conductor alloys. Distribution runs through specialized medical device distributors for implantable systems and direct-to-municipality contracts for automated external defibrillator fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Public access defibrillation mandates across the United States, Germany, and Japan signal early-cycle expansion for automated external defibrillator volume, with wearable cardioverter defibrillator remote monitoring reimbursement creating parallel adoption tailwinds in post-acute care settings.
For Market Incumbents: Fortify captive supply positions in lithium silver vanadium oxide cell procurement through long-term offtake agreements with Japanese chemical producers, and accelerate EU MDR clinical performance study completion to preempt certification timeline compression for implantable cardioverter defibrillator portfolios. Wireless telemetry module commoditization from consumer electronics entrants threatens margin structures in wearable systems. For New Entrants and Emerging Players: Post-myocardial infarction patient monitoring in United States home health settings offers a service-layer gap where incumbents under-serve cloud-connected diagnostic transmission needs. Target rural Indian district hospitals with Hindi-language interface automated external defibrillators, and pursue Japan's Sakigake designation pathway for novel rhythm analysis algorithms to accelerate regulatory market entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrophysiology service line integrators with dedicated lead extraction surgical training infrastructure and hospital system contracting authority. Five-to-ten year viability hinges on subcutaneous implantable cardioverter defibrillator adoption velocity displacing transvenous systems. Monitor FDA post-market surveillance guidance tightening for battery and capacitor component traceability as an inflection indicator for compliance cost escalation favoring scaled manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses premarket timelines for automated external defibrillators against EU MDR implantable device delays. |
| EU MDR Clinical Performance Study Investment | Extends certification timelines eighteen to thirty-six months but creates regulatory moats for compliant implantable portfolios. |
| Hospital System Partnership Consolidation | Locks electrophysiology service line volume through integrated delivery network exclusive contracting in Texas and Northeast Corridor markets. |
| Wireless Telemetry Module Development | Enables remote patient monitoring reimbursement expansion for wearable cardioverter defibrillants in United States post-acute settings. |
| Reimbursement Strategy Formulation | Secures CMS Medicare coverage codes for home-based cardiac surveillance driving wearable device adoption velocity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, and Japanese PMDA Sakigake designation records. Electrophysiologists at United States academic medical centers, German university hospital purchasing committees, and Japanese tertiary cardiac center biomedical engineers provided clinical deployment perspectives. Bottom-up unit shipment estimates from emergency medical service fleet operators and top-down revenue analysis from integrated delivery network capital equipment budgets were cross-validated against GPO contract disclosure databases and CMS Medicare reimbursement fee schedules.
Segmentation dimensions modeled include product architecture spanning implantable, wearable, automated external, and manual defibrillator systems; technology tier separating wireless-enabled from battery-operated units; application context across emergency medical services, public access programs, and cardiac care units; and end-user category distinguishing hospital systems from paramedic teams. CAGRs were derived from replacement cycle velocity analysis for implantable devices and legislative mandate penetration curves for public access deployment. Forecast inputs incorporated aging demographic cardiovascular disease prevalence projections and PMDA electromagnetic compatibility standard evolution timelines.
Forecasts assume regulatory continuity in FDA premarket notification pathways, EU MDR clinical evidence requirements, and Japan PMDA JIS standards; material policy shifts would require re-modeling of certification timeline assumptions and reimbursement code valuations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Global Medical Loupes Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Global Medical Drones Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Face Mask Device Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Band Ligators Market