
 Carotid Artery Stenosis Market | 2026-2036
Carotid Artery Stenosis Market Size, Share, and Industry Trends Forecast 2026-2036
Carotid Artery Stenosis Market Outlook
A shortage of trained vascular surgeons is reorganizing how hospitals deploy carotid stenting programs across developed markets. Abbott Laboratories leverages its endovascular portfolio to sustain presence in embolic protection, while Medtronic anchors its position through integrated stroke-care ecosystems. Silk Road Medical differentiates with transcervical access technology that reduces procedural complexity.
Carotid artery stenosis denotes the pathological narrowing of one or both carotid arteries, typically exceeding 50% luminal diameter reduction, which elevates ischemic stroke risk through plaque embolization or hemodynamic compromise. The condition demands intervention when symptomatic or when asymptomatic stenosis reaches severity thresholds defined by duplex ultrasound velocity criteria and imaging morphology. Stents command the largest revenue share within device type segmentation due to durable patency requirements and premium nitinol alloy specifications. Ambulatory surgical centers represent the fastest-growing end user channel as same-day discharge protocols gain payer acceptance and procedure technique standardization improves. Metal alloys dominate raw material selection for structural integrity under cyclic vascular loading, though bio-absorbable polymers attract R&D investment for future bioresorbable scaffolding concepts.
FDA premarket notification and PMA pathways govern device commercialization in the United States, while EMA medical device regulation and MDR conformity assessment shape European market access requirements. Japan's PMDA enforces stringent clinical evidence standards for stent approval that extend development timelines but reinforce product reliability expectations. Stakeholders must monitor evolving CMS reimbursement determinations for transcarotid artery revascularization against conventional transfemoral approaches.
Market Dynamics
The convergence of transcarotid access techniques with same-day discharge protocols is redistributing procedure volumes away from conventional inpatient settings toward specialized vascular centers. This structural shift compresses revenue per procedure while expanding addressable patient pools.
Growth Catalysts
- Aging demographics in the United States:The 75-plus population cohort drives screening-detected asymptomatic stenosis cases into intervention pathways. CMS reimbursement determinations for transcarotid artery revascularization validate expanded eligibility criteria.
- CE marking under EU MDR:Accelerated conformity assessment timelines for Class III implantable devices reduce market access friction for novel stent designs. European vascular surgery societies publish updated guidelines endorsing minimally invasive alternatives.
- Nitinol alloy specifications:Superelastic nickel-titanium compositions enable thinner stent struts without sacrificing radial force. Material science advances from aerospace applications transfer into vascular scaffolding requirements.
Market Restraints
- Platinum-iridium marker band costs:Precious metal price volatility in radiopaque element sourcing squeezes gross margins on embolic protection devices. Suppliers pass through indexed pricing clauses with 90-day lag structures.
- Japanese PMDA clinical evidence standards:Extended development timelines for stent approval reinforce product reliability expectations but delay revenue recognition. Domestic manufacturers capture interim market share.
- Stroke prevention pharmacotherapy:Dual antiplatelet regimens and statin intensity protocols reduce progression to intervention thresholds in managed populations. Payers incentivize medical management through quality metrics.
Strategic Opportunities
- Bio-absorbable polymer scaffolding:Magnesium alloy and polylactic acid constructs eliminate permanent metal retention. Early feasibility studies in Germany and South Korea demonstrate 24-month resorption timelines.
- Ambulatory surgical center accreditation:Medicare's site-of-service payment differentials reward same-day discharge protocols. Vascular surgery groups consolidate procedures into physician-owned facilities.
- Integrated stroke-care ecosystems:Telestroke networks connect community hospitals with academic intervention centers. Hub-and-spoke configurations expand geographic coverage without capital-intensive expansion.
Industry Challenges
- Vascular surgeon training pipeline:Fellowship positions fail to match retirement-driven attrition. Hospital systems deploy physician assistants and nurse practitioners to extend procedural capacity.
- EMR integration complexity:Duplex ultrasound velocity criteria require structured reporting modules. Vendor-agnostic interoperability standards remain immature across imaging platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carotid Artery Stenosis Market |
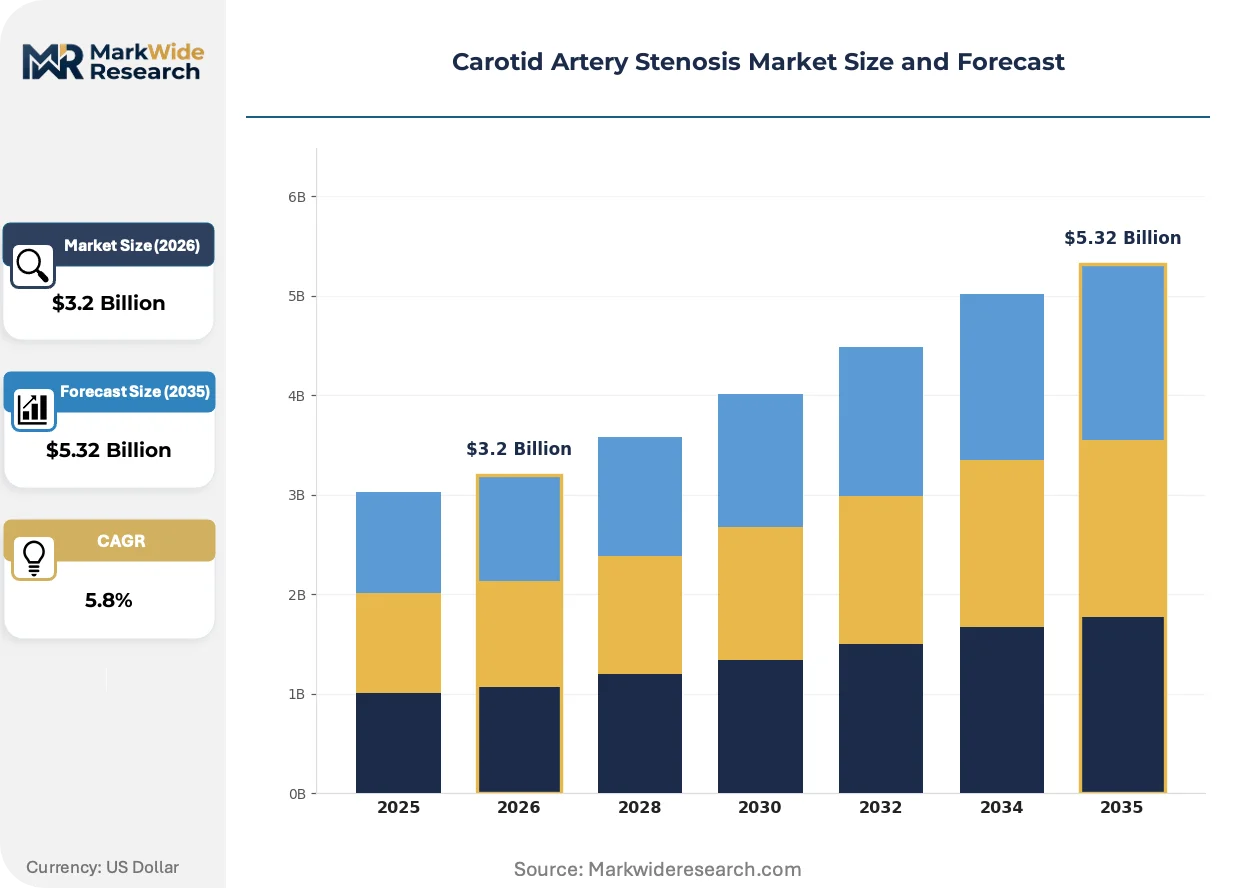
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Stents, Angioplasty Balloons, Guidewires, Surgical Clamps End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Procedure Type: Endovascular Surgery, Bypass Surgery, Stenting, Angioplasty Raw Material: Plastic, Metal Alloys, Bio-absorbable Polymers, Coatings |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic, Cordis, Silk Road Medical, Terumo Europe, Balton, InspireMD, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carotid Artery Stenosis Market Strategic Shifts
Device miniaturization and procedural simplification are compressing the skill threshold required for carotid intervention. These developments expand the addressable operator pool while intensifying competition among access technique platforms.
Transcervical flow reversal systems are decomposing the traditional transfemoral stenting workflow by eliminating aortic arch navigation. Community hospitals with limited endovascular experience adopt these platforms to retain stroke-referral revenue locally. The technology is decomposing the historical concentration of complex cases within academic medical centers.
FDA premarket approval pathway modifications for breakthrough device designation compress review timelines for embolic protection innovations. The agency's priority review vouchers for stroke indications accelerate commercialization schedules. Device manufacturers respond by front-loading clinical trial investment to capture designation eligibility.
Buyer concentration among integrated delivery networks restructures procurement authority away from individual physicians. IDN value analysis committees standardize device selection across multiple hospital sites. This concentration is most visible in the United States, where health system consolidation has reduced independent community hospital purchasing autonomy.
Carotid Artery Stenosis Market Segmentation
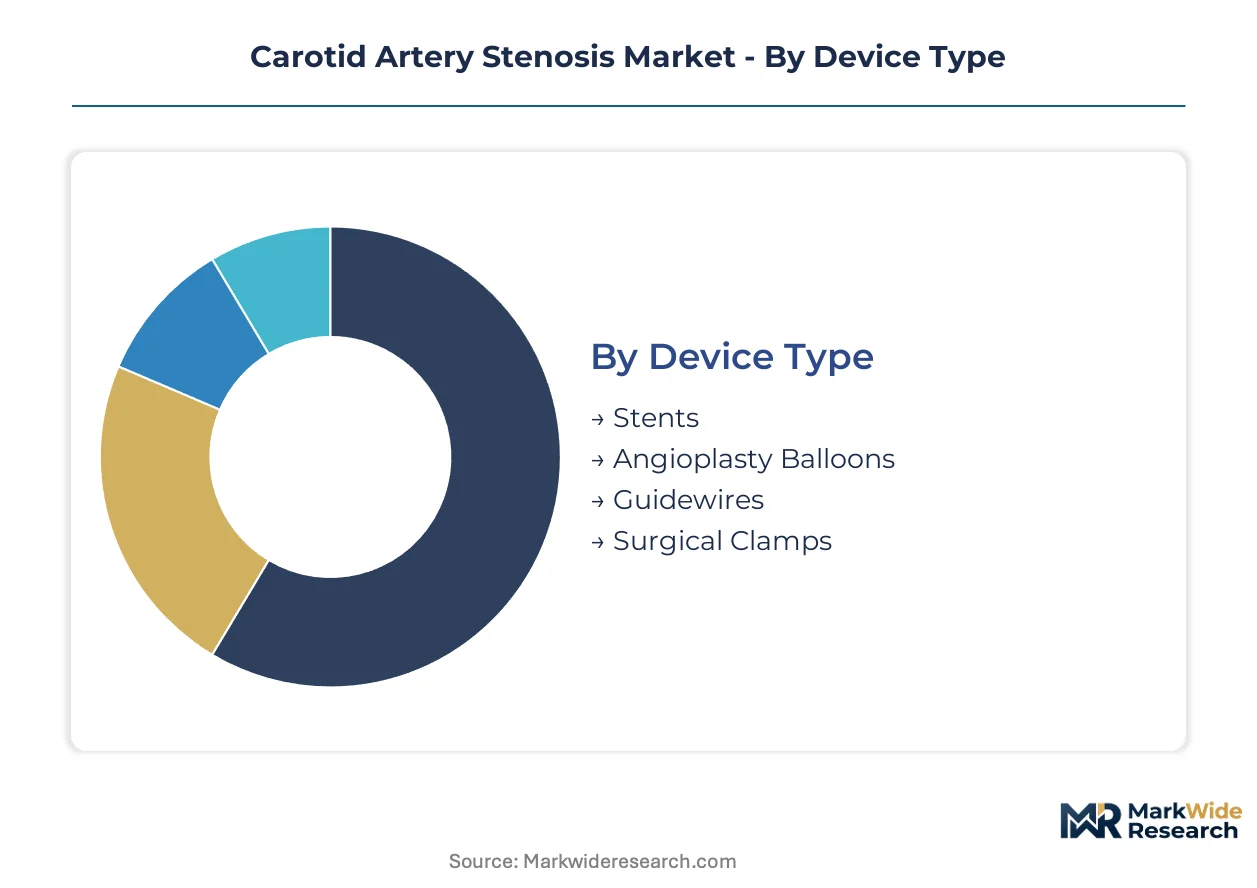
Carotid artery stenosis interventions fragment across device technologies, care settings, and procedural approaches that compete for clinical preference and reimbursement allocation. Understanding segment substitution dynamics reveals where manufacturers must defend installed base versus capture emerging volume.
Device Type:
Angioplasty balloons face the most acute substitution pressure as drug-coated alternatives and cutting-edge platforms displace conventional models in high-volume accounts.
- Stents:Nitinol self-expanding scaffolds with closed-cell geometry dominate the structural intervention segment. Demand concentrates in United States hospital systems where durable patency requirements and premium alloy specifications justify higher acquisition costs against balloon-only approaches.
- Angioplasty Balloons:Semi-compliant and non-compliant inflation platforms pre-dilate stenotic lesions prior to stent deployment. United States ambulatory surgical centers are absorbing volume fastest as same-day discharge protocols reduce per-procedure overhead.
- Guidewires:Hydrophilic-coated and stiff-shaft configurations enable arch navigation and lesion crossing.
- Surgical Clamps:Cross-clamp designs for open endarterectomy retain relevance in specific anatomical presentations.
Stents retain volume leadership; angioplasty balloons hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive inpatient infrastructure from lean outpatient models competing on throughput efficiency.
- Hospitals:Academic medical centers and community hospitals maintain comprehensive stroke-care ecosystems with 24-hour intervention capability. United States integrated delivery networks are consolidating purchasing authority across multiple hospital sites, compressing vendor margins through standardized contracting.
- Ambulatory Surgical Centers:Physician-owned facilities exploit Medicare site-of-service payment differentials to capture profitable elective cases. United States vascular surgery groups are migrating low-complexity procedures to accredited outpatient settings fastest.
- Clinics:Office-based diagnostic and referral functions support pre-procedural screening workflows.
- Research Institutions:Clinical trial sites generate evidence for regulatory submissions and guideline updates.
Hospitals command the revenue base; ambulatory surgical centers are climbing the fastest.
Procedure Type:
Application-specific technique selection reflects operator training distribution and anatomical complexity stratification across patient populations.
- Stenting:Transfemoral and transcervical access approaches deploy metallic scaffolds with embolic protection. United States community hospitals with limited endovascular experience are adopting transcervical flow reversal systems to retain stroke-referral revenue locally.
- Angioplasty:Balloon-only dilation without permanent implantation serves specific high-surgical-risk patients. United States payer quality metrics increasingly scrutinize appropriateness, constraining volume expansion.
- Endovascular Surgery:Minimally invasive catheter-based interventions span the full lesion treatment spectrum.
- Bypass Surgery:Extracranial-intracranial revascularization remains reserved for failed endovascular candidates.
Stenting dominates procedure counts; angioplasty is gaining share fastest among non-implant alternatives.
Raw Material:
Supply concentration in aerospace-derived alloy processing creates procurement leverage for manufacturers with backward-integrated sourcing.
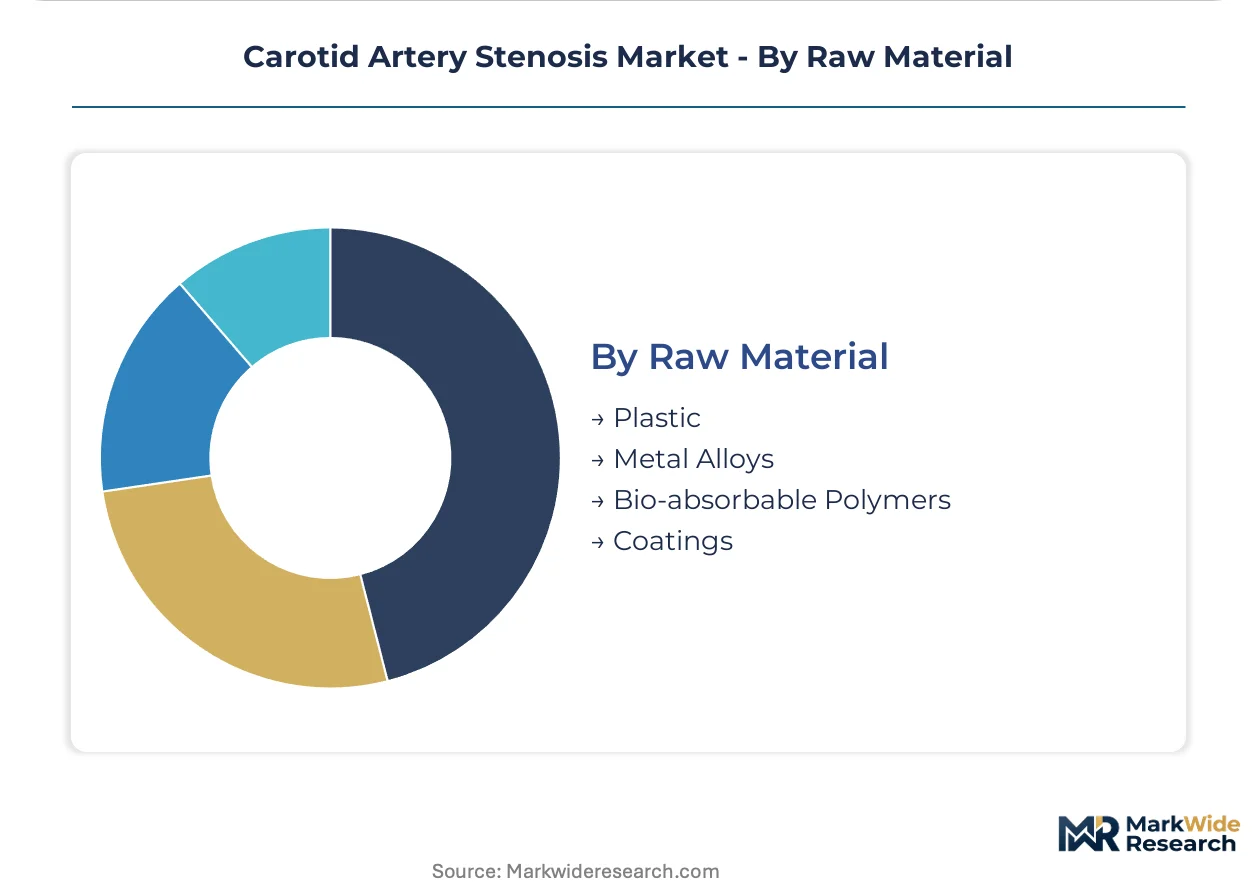
- Metal Alloys:Nickel-titanium superelastic compositions enable thinner stent struts without radial force compromise. Nitinol specification demand concentrates in United States and European manufacturing facilities with vacuum melting and drawing capabilities.
- Bio-absorbable Polymers:Magnesium alloy and polylactic acid constructs eliminate permanent metal retention. Early feasibility studies in Germany and South Korea are validating 24-month resorption timelines for future commercialization.
- Plastic:Engineering polymers serve catheter shafts and delivery system components.
- Coatings:Drug-eluting and passive surface treatments modify thrombogenicity and healing response.
Metal alloys anchor current production; bio-absorbable polymers represent the steepest R&D investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German reimbursement rates by margins that sustain premium nitinol alloy specifications, while Japanese clinical evidence requirements compress manufacturer margins through extended development timelines.
United States
The 75-plus population cohort drives screening-detected asymptomatic stenosis into intervention pathways. CMS reimbursement determinations for transcarotid artery revascularization validate expanded eligibility criteria. Hospital systems in the Southeast and Midwest are consolidating purchasing authority across integrated delivery networks.
Germany
CE marking under EU MDR accelerates conformity assessment timelines for Class III implantable devices. The country's national pharmaceutical regulator enforces stringent post-market surveillance requirements. Early feasibility studies for bio-absorbable polymer scaffolding concentrate in Munich and Heidelberg research clusters.
Japan
Aging demographics comparable to the United States generate substantial screening volumes for asymptomatic cases. PMDA clinical evidence standards extend stent approval timelines but reinforce product reliability expectations. Tokyo and Osaka academic medical centers anchor domestic clinical trial infrastructure.
United Kingdom
NHS England quality metrics incentivize same-day discharge protocols for eligible patients. The national pharmaceutical regulator aligns with EMA medical device regulation for streamlined market access. London and Manchester vascular centers pioneer ambulatory surgical center accreditation pathways.
South Korea
Magnesium alloy resorption studies attract R&D investment from domestic materials science institutes. The national pharmaceutical regulator maintains alignment with international standards while enforcing local clinical trial requirements. Seoul-based manufacturers capture regional supply chain advantages for nitinol processing.
Carotid Artery Stenosis Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated stroke-care ecosystems commanding premium positioning against specialized access-technology developers. The market structure consolidates around three tiers: diversified medical technology conglomerates with endovascular portfolios, mid-cap specialists focused on transcervical platforms, and regional manufacturers serving price-sensitive procurement channels. Dominant competitive moves include strategic partnerships between device manufacturers and telestroke network operators, plus backward integration into nitinol alloy supply by scale players.
Among diversified medical technology conglomerates, Abbott Laboratories and Medtronic occupy positions that exemplify integrated portfolio approaches, while Silk Road Medical represents the specialized access-technology archetype with transcervical platform concentration. These three companies anchor the competitive structure without exhausting the vendor landscape, as regional manufacturers in Europe and Asia-Pacific maintain viable positions in embolic protection and guidewire segments through cost-optimized production.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic |
| Cordis |
| Silk Road Medical |
| Terumo Europe |
| Balton |
| InspireMD |
| MicroPort Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates at vacuum-melting facilities in the United States and Germany determine nitinol alloy availability floors, concentrating supply leverage among aerospace-integrated processors who simultaneously serve vascular scaffolding and turbine blade markets. This dual-use demand pattern establishes price floors that resist commoditization despite ballooning angioplasty volumes in outpatient settings.
Pricing Analysis
The customization-premium spread between patient-specific stent configurations and standard nitinol scaffolds widens as integrated delivery networks consolidate procurement authority. Per-unit transactional pricing dominates device categories, with differentiation driven by FDA breakthrough designation tier and platinum-iridium radiopacity grade. Cost compression in embolic protection devices intensifies as precious metal price volatility squeezes gross margins. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare site-of-service differentials, while academic medical centers absorb premium specifications for complex anatomical cases.
Supply Chain Analysis
Strategic stockpiling of nickel-titanium feedstock prevails among scale manufacturers hedging against aerospace demand surges, contrasting with just-in-time catheter component sourcing from Mexican and Costa Rican maquiladora operations. Nitinol alloy supply concentrates in the United States, Germany, and Japan where vacuum arc remelting capabilities reside. Platinum-iridium marker bands and superelastic wire draw from South African and Russian precious metal channels. Single-source vulnerability in aerospace-qualified melting capacity threatens supply continuity. Distribution runs through integrated delivery network value analysis committees rather than individual physician preference.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as aging demographics in the United States drive screening-detected asymptomatic cases into intervention pathways, creating procedure volume elasticity that outpaces surgeon training pipeline constraints.
For Market Incumbents: Consolidate backward integration into nitinol vacuum-melting capacity to secure feedstock priority against aerospace demand competition. Deepen hospital system partnerships through telestroke network integration, defending installed base against transcervical access platform substitution. Prioritize FDA breakthrough device designation front-loading to accelerate review timelines for embolic protection innovations.
For New Entrants and Emerging Players: FDA pre-submission pathway acceleration offers fastest regulatory validation for novel bio-absorbable polymer scaffolds. Target ambulatory surgical center accreditation as the most penetrable channel, exploiting Medicare site-of-service payment differentials that physician-owned facilities exploit. Pursue GPO contract participation as primary go-to-market mechanism bypassing IDN value analysis committee gatekeeping.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized access-technology developers with transcervical platform concentration over diversified conglomerates with endovascular portfolio breadth. Long-term viability over the next decade hinges on reimbursement strategy execution for same-day discharge protocols. Monitor CMS national coverage determinations for transcarotid artery revascularization as primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compressed review timelines accelerate commercialization for embolic protection innovations ahead of PMA pathways. |
| CE Marking Pathway under EU MDR | Accelerated conformity assessment reduces market access friction for Class III implantable stent designs. |
| Hospital System Partnership | Telestroke network integration expands geographic coverage without capital-intensive academic medical center expansion. |
| Backward Integration into Nitinol Supply | Captive vacuum-melting capacity secures aerospace-grade alloy priority against turbine blade demand competition. |
| Reimbursement Strategy | CMS national coverage determination advocacy determines transcarotid eligibility expansion against conventional transfemoral approaches. |
Study Parameters
A standing panel of vascular surgeons, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FDA PMA filings, CMS Medicare claims data, hospital procurement databases, and European vascular surgery society guideline updates. Bottom-up procedure volume modeling and top-down device revenue estimates were triangulated to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including device type, end user channel, procedure approach, and raw material specification, with geographic regulatory clusters overlaying demand patterns. CAGRs were derived from procedure volume elasticity tied to demographic screening penetration and reimbursement expansion trajectories. Nitinol alloy pricing indices and PMDA approval timeline distributions served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable CMS reimbursement determinations and continued FDA breakthrough pathway availability; material deviation in either would warrant model refresh. Forecasts reflect these base assumptions alongside continued vascular surgeon training pipeline constraints and precious metal price volatility patterns. Revision becomes warranted when transcarotid procedure volume crosses thresholds that trigger payer utilization management intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Ischemia Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
US Statin Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Tachycardia Market