
 Middle East and Africa Acute Coronary Syndrome Market | 2026-2036
Middle East and Africa Acute Coronary Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Acute Coronary Syndrome Market Foresight
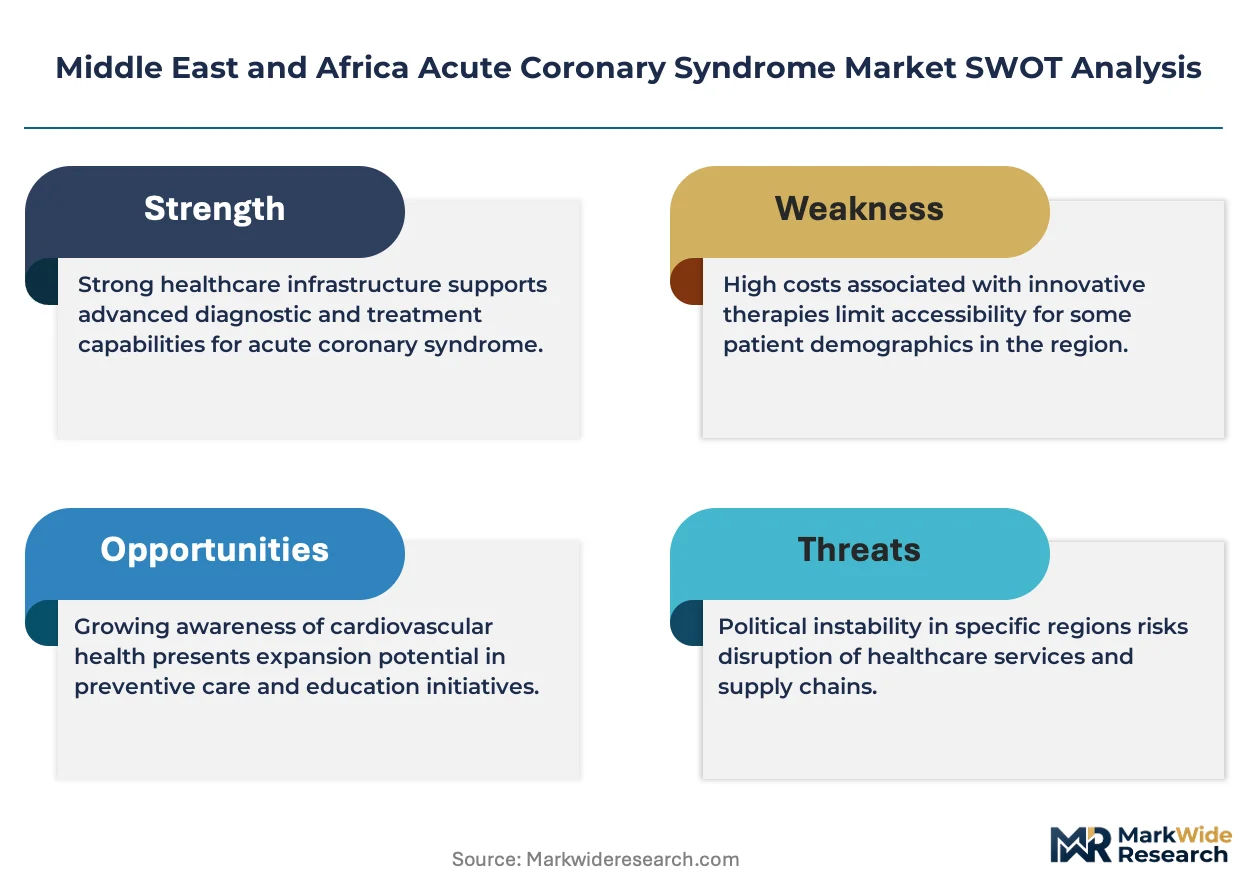
Bioresorbable scaffold technology is reshaping coronary intervention protocols across the Middle East and Africa, shifting procedural preferences toward devices that restore vessel function without permanent metallic implants. AstraZeneca leverages its antiplatelet portfolio to anchor market presence in Gulf Cooperation Council states where dual antithrombotic therapy protocols are expanding. Pfizer Inc. competes through lipid-lowering agent distribution networks that penetrate both South African private chains and Nigerian public procurement channels. Daiichi Sankyo Company Ltd. differentiates its position via oral anticoagulant access programs targeting Egyptian and Moroccan cardiology centers.
Acute coronary syndrome encompasses a spectrum of clinical conditions including unstable angina and myocardial infarction arising from abrupt coronary artery plaque disruption, typically managed through antiplatelet inhibition, revascularization, or surgical bypass with stent deployment requiring precise strut thickness below 100 micrometers and controlled drug elution kinetics. Drug-eluting stents command the dominant product position due to superior restenosis outcomes, while bare metal stents retain cost-driven demand in price-sensitive North African public health systems. Coronary angioplasty leads treatment method adoption as catheterization laboratory capacity expands across Gulf states, though medical management maintains substantial volume in regions where interventional infrastructure remains underdeveloped.
Saudi Arabia's SFDA and South Africa's SAHPRA enforce divergent stent approval timelines that fragment product launch synchronization across the region, while Egypt's drug authority applies localized bioequivalence standards for generic antiplatelet agents that shape manufacturer market entry sequencing. The EU MDR's extraterritorial influence on CE-marked device exports further complicates regulatory navigation for Middle Eastern importers sourcing from European manufacturing facilities. Stakeholders must monitor how national health insurance expansion in the UAE and Qatar alters reimbursement thresholds for premium drug-eluting platforms versus standard bare metal alternatives.
Market Dynamics
Bioresorbable scaffold technology is compressing the addressable market for permanent metallic implants across Middle Eastern catheterization laboratories, forcing incumbent stent manufacturers to reposition around transient vascular support solutions.
Growth Catalysts
- SFDA Streamlined Pathways:Saudi Arabia's medical device regulator has accelerated coronary stent and antithrombotic therapy registrations, reducing time-to-market for interventional cardiology products.
- Catheterization Laboratory Expansion:Egypt's public and private hospital networks are building dedicated cardiac catheterization units, creating procedural capacity for percutaneous coronary intervention volumes.
- Dual Antithrombotic Protocol Adoption:Gulf Cooperation Council cardiology centers are expanding combination antiplatelet-anticoagulant regimens, driving pharmaceutical demand for integrated therapy management.
Market Restraints
- Input Cost Volatility:Cobalt-chromium alloy prices for stent strut manufacturing fluctuate with mining output from South African platinum-group metal operations.
- Regulatory Fragmentation:Divergent approval timelines between Saudi Arabia's SFDA and South Africa's SAHPRA prevent synchronized product launches across the region.
- Technical Limitation:Bioresorbable scaffolds exhibit higher acute recoil rates than metallic platforms in calcified lesions, restricting their deployment in complex coronary anatomies.
Strategic Opportunities
- Underpenetrated Moroccan Market:Morocco's public cardiology infrastructure remains below regional density benchmarks, presenting first-mover advantages for interventional device distributors.
- Regulatory Tailwind:Egypt's drug authority applies localized bioequivalence standards for generic antiplatelet agents, enabling faster market entry for cost-competitive manufacturers.
- Technology Convergence:Integration of intravascular imaging with robotic-assisted catheter navigation is creating premium procedure bundles for Gulf state private hospital networks.
Industry Challenges
- Interventional Cardiologist Shortage:Sub-Saharan African markets face critical deficits in fellowship-trained operators capable of complex percutaneous coronary intervention procedures.
- EU MDR Extraterritorial Compliance:Middle Eastern importers sourcing CE-marked devices from European facilities must navigate updated conformity assessment requirements affecting supply continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Acute Coronary Syndrome Market |
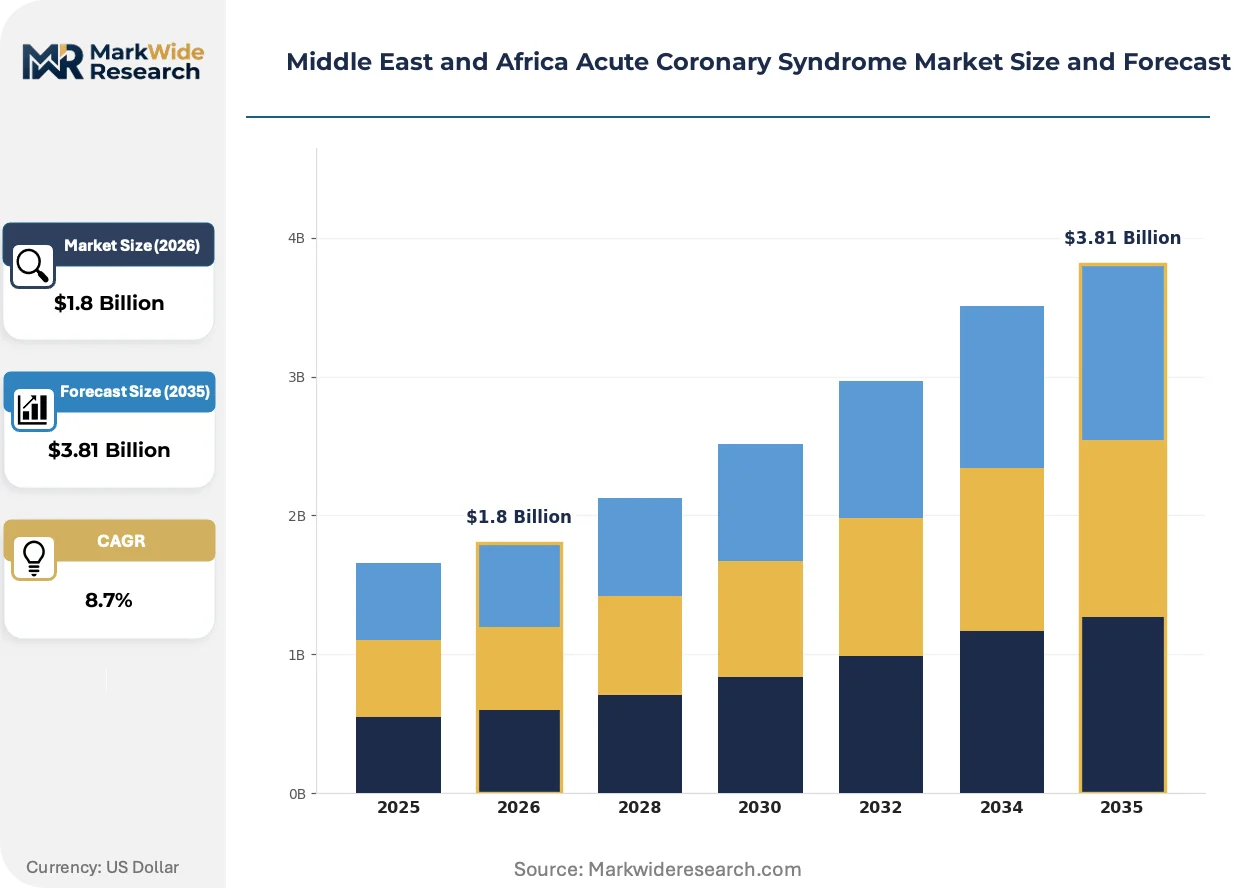
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug-Eluting Stents, Bare Metal Stents, Antiplatelet Agents, Beta-Blockers Treatment Method: Coronary Angioplasty, Coronary Bypass Surgery, Medical Management, Physiotherapy End User: Hospitals, Specialty Clinics, Home Healthcare, Cardiology Centers Distribution Channel: Direct Sales, Online Pharmacy, Retail Pharmacy, Wholesalers |
| Companies Covered | AstraZeneca, Sanofi, Merck & Co., Pfizer Inc., Johnson & Johnson, Boehringer Ingelheim, Bristol Myers Squibb, Daiichi Sankyo Company Ltd., Novartis AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Acute Coronary Syndrome Market Shifts & Advancements
Coronary intervention protocols across the Middle East and Africa are pivoting toward vessel restoration without permanent implant retention, compressing the traditional metallic stent value chain while elevating imaging and pharmaceutical adjuncts.
Intravascular optical coherence tomography is digitizing lesion characterization workflows in Saudi Arabian and Emirati catheterization laboratories. Interventional cardiologists at tertiary centers in Riyadh and Dubai are adopting high-resolution plaque imaging to guide bioresorbable scaffold sizing and deployment. This technology is digitizing the pre-procedural planning phase, reducing fluoroscopy exposure and contrast volume while enabling personalized revascularization strategies.
South Africa's SAHPRA has tightened post-market surveillance requirements for drug-eluting stents, mandating extended safety reporting from private hospital networks. The regulation compresses product lifecycle management for manufacturers serving the Southern African Customs Union. Cardiovascular device distributors are restructuring quality assurance departments to manage real-world evidence collection across Johannesburg and Cape Town metropolitan hospital clusters.
Private hospital procurement in the UAE and Qatar is consolidating antiplatelet therapy purchasing through centralized pharmacy committees. This buyer concentration is displacing traditional physician-directed prescribing for post-acute coronary syndrome maintenance regimens. The shift is most visible in Abu Dhabi's Cleveland Clinic and Doha's Hamad Medical City networks, where formulary standardization now precedes individual clinician preference.
Middle East and Africa Acute Coronary Syndrome Market Segmentation
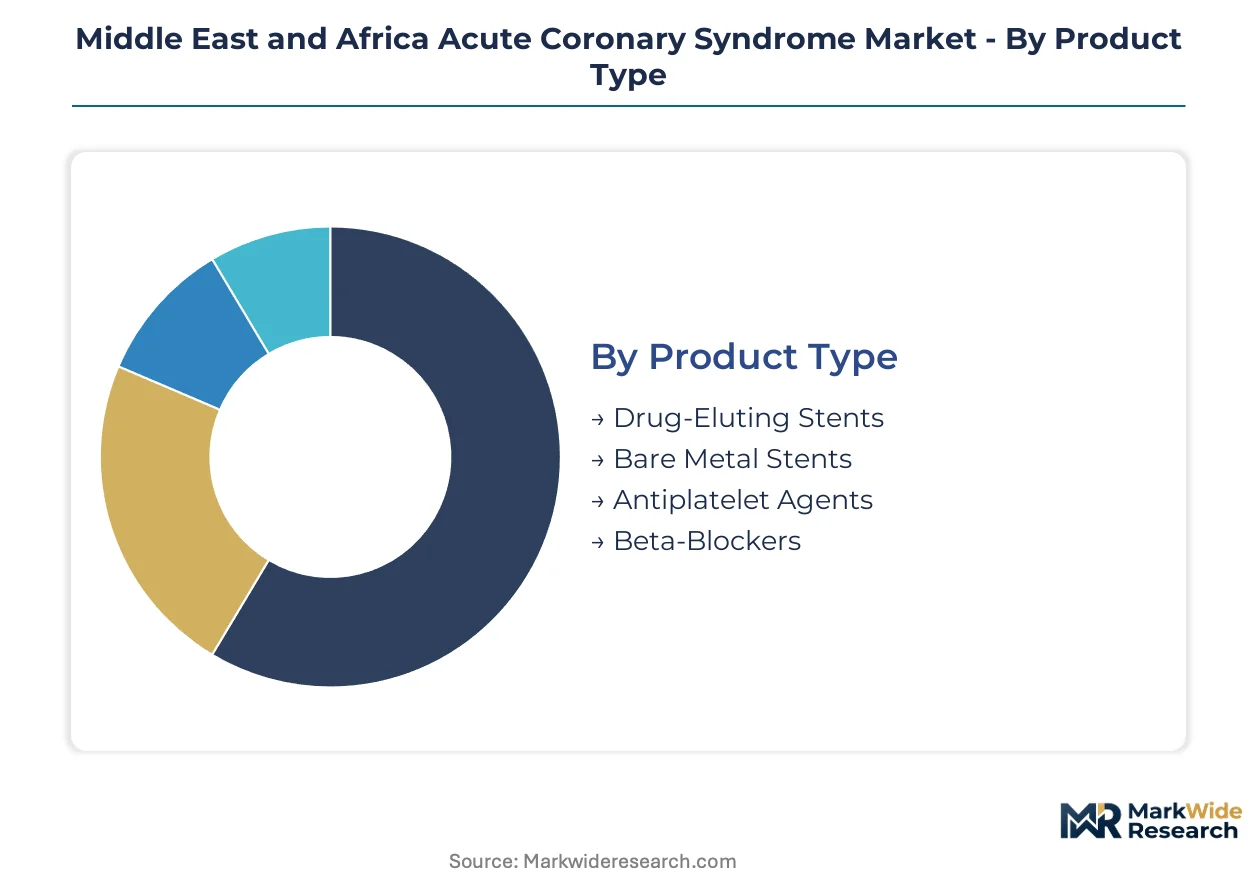
Acute coronary syndrome intervention across the Middle East and Africa fragments across device, pharmaceutical, and service modalities that compete for capital allocation within constrained health budgets. Treatment decisions pivot on catheterization laboratory availability, reimbursement tier, and lesion complexity rather than clinical preference alone.
Product Type:
Use-case spectrum spans permanent implantation for revascularization through pharmaceutical maintenance for non-interventional candidates.
- Drug-Eluting Stents:Polymer-coated metallic platforms elute antiproliferative agents to suppress neointimal hyperplasia. Demand concentrates in Saudi Arabian and Emirati tertiary centers where SFDA registration pathways favor premium platforms with extended safety data.
- Antiplatelet Agents:Oral P2Y12 inhibitors and aspirin combinations form the pharmacological backbone of dual antithrombotic protocols. Egyptian and Moroccan cardiology centers drive volume through post-percutaneous coronary intervention maintenance regimens.
- Bare Metal Stents:Uncoated cobalt-chromium platforms retain position in North African public procurement where acquisition cost dominates selection criteria.
- Beta-Blockers:Cardioselective agents manage post-infarction remodeling and secondary prevention in South African private hospital networks.
Established volume favors Drug-Eluting Stents; emerging adoption favors Antiplatelet Agents.
Treatment Method:
Procedural intensity correlates directly with catheterization laboratory density across Gulf Cooperation Council states versus Sub-Saharan African markets.
- Coronary Angioplasty:Percutaneous transluminal intervention with balloon dilation and stent deployment. Egypt's expanding catheterization infrastructure and Dubai's robotic-assisted platforms concentrate procedural growth.
- Medical Management:Pharmacological stabilization without mechanical revascularization. Nigerian public hospitals and Kenyan county referral centers rely on anticoagulant and antiplatelet protocols where interventional capacity remains undeveloped.
- Coronary Bypass Surgery:Open-chest grafting for multivessel disease retains indication in diabetic patients with complex anatomy at South African academic medical centers.
- Physiotherapy:Cardiac rehabilitation programs support functional recovery post-acute event, gaining traction in Qatar's integrated care networks.
Coronary Angioplasty claims the steepest expansion trajectory; Medical Management retains the largest untreated addressable base.
End User:
Facility type determines device sophistication, pharmaceutical formulary breadth, and follow-up protocol intensity.
- Cardiology Centers:Dedicated interventional suites with on-site hemodynamic monitoring. Saudi Arabia's Ministry of Health expansion targets 50+ standalone catheterization units by decade-end.
- Hospitals:General acute care facilities with cardiac units but variable interventional capability. South Africa's private hospital networks—Netcare, Mediclinic, Life Healthcare—consolidate high-volume elective procedures.
- Specialty Clinics:Outpatient-focused practices managing stable post-acute patients on maintenance antiplatelet regimens.
- Home Healthcare:Post-discharge monitoring and medication adherence programs emerging in UAE's health insurance-mandated chronic disease management frameworks.
Cardiology Centers attract capital investment fastest; Hospitals retain the dominant procedure share.
Distribution Channel:
Channel selection reflects product regulatory classification, cold-chain requirements, and procurement centralization trends.
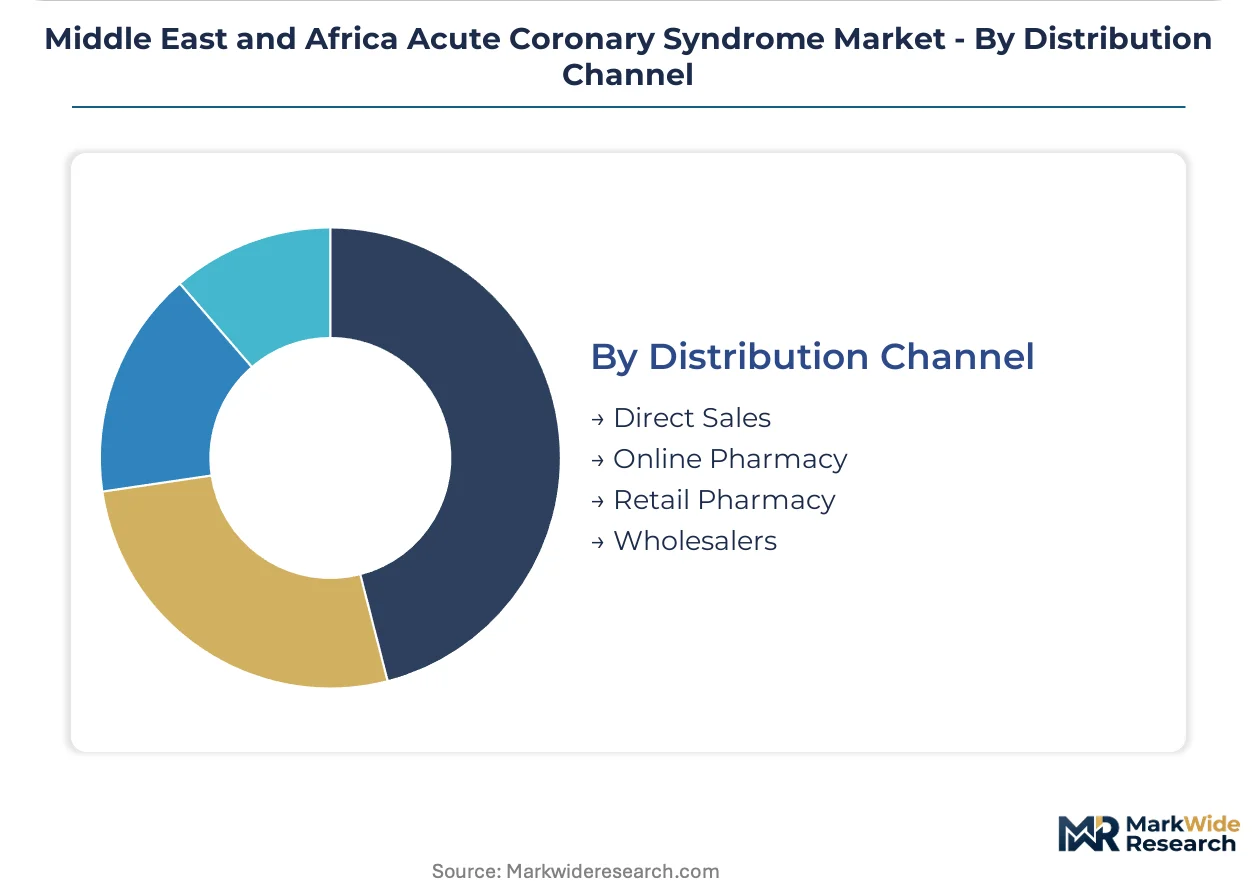
- Direct Sales:Manufacturer-to-hospital contracting for stents and capital equipment. Abu Dhabi's Cleveland Clinic and Doha's Hamad Medical City negotiate enterprise-wide device agreements.
- Retail Pharmacy:Community dispensing for maintenance antiplatelet and lipid-lowering therapies. Egypt's chain pharmacy expansion—Seif, El Ezaby—extends post-discharge medication access.
- Wholesalers:Regional distributors manage inventory and customs clearance for multinational device manufacturers entering Moroccan and Algerian markets.
- Online Pharmacy:Digital platforms for chronic medication refills, constrained by controlled-substance regulations across Gulf states.
Direct Sales commands premium device volume; Retail Pharmacy dominates pharmaceutical maintenance dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss stent manufacturers export drug-eluting platforms through Dubai's Jebel Ali Free Zone into Saudi Arabian and Egyptian hospital procurement channels. This trade corridor funnels European CE-marked devices into Gulf Cooperation Council catheterization laboratories while South African distributors manage parallel imports for the Southern African Customs Union.
Saudi Arabia
Riyadh's King Faisal Specialist Hospital performs complex percutaneous coronary intervention procedures that drive demand for premium drug-eluting platforms. The SFDA operates streamlined medical device registration pathways that accelerate coronary stent and antithrombotic therapy approvals. Eastern Province cities including Dammam and Khobar are expanding standalone cardiology centers with dedicated hemodynamic monitoring suites.
United Arab Emirates
Dubai's robotic-assisted catheter navigation platforms attract medical tourism from North African and South Asian patient populations seeking advanced revascularization. MOHAP enforces post-market surveillance requirements that align with EU MDR standards for imported CE-marked devices. Abu Dhabi's Cleveland Clinic network consolidates enterprise-wide device agreements through centralized pharmacy committees.
South Africa
Johannesburg's private hospital networks—Netcare, Mediclinic, Life Healthcare—consolidate high-volume elective procedures requiring cobalt-chromium alloy stents. SAHPRA mandates extended safety reporting from metropolitan hospital clusters that compresses product lifecycle management. Cape Town's academic medical centers retain coronary bypass surgery indications for diabetic patients with complex multivessel anatomy.
Egypt
Cairo's expanding catheterization laboratory infrastructure creates procedural capacity for percutaneous coronary intervention volumes previously managed through medical management alone. The national drug authority applies localized bioequivalence standards for generic antiplatelet agents that enable faster market entry for cost-competitive manufacturers. Alexandria's public hospital networks are building dedicated cardiac catheterization units with Egyptian Ministry of Health capital allocation.
Morocco
Casablanca's public cardiology infrastructure remains below regional density benchmarks for interventional device penetration. The national pharmaceutical regulator maintains import licensing requirements for coronary stents that favor established European suppliers. Rabat's university hospital clusters are developing fellowship training programs to address critical deficits in intervention-trained operators.
Middle East and Africa Acute Coronary Syndrome Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent regulatory timelines that fragment product launch synchronization. The vendor base organizes around pharmaceutical manufacturers with antiplatelet portfolios and device manufacturers with stent platforms. Three archetypes dominate: integrated cardiovascular therapy managers, interventional device specialists, and generic pharmaceutical cost competitors. Competitive moves concentrate on regulatory pathway optimization and catheterization laboratory partnership networks.
Within the integrated therapy tier, AstraZeneca and Pfizer Inc. occupy positions anchored by antiplatelet and lipid-lowering distribution networks. Daiichi Sankyo Company Ltd. exemplifies the oral anticoagulant specialist archetype targeting North African cardiology centers. These three companies represent distinct strategic postures—pharmaceutical breadth, metabolic management, and anticoagulant access programs—without vertical integration into device manufacturing.
| Leading Market Players |
|---|
| AstraZeneca |
| Sanofi |
| Merck & Co. |
| Pfizer Inc. |
| Johnson & Johnson |
| Boehringer Ingelheim |
| Bristol Myers Squibb |
| Daiichi Sankyo Company Ltd. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Jebel Ali Free Zone's concentration of European device re-export capacity concentrates pricing leverage for coronary stent distributors serving Saudi Arabian and Egyptian hospital procurement channels. Cobalt-chromium alloy sourcing from South African platinum-group metal operations feeds into strut manufacturing costs that propagate through Gulf Cooperation Council catheterization laboratory supply agreements.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation govern raw material pass-through for cobalt-chromium stent platforms. Price differentiation rests on CE-marking tier and catheterization laboratory volume scale, with premium drug-eluting platforms commanding formulary preference in Emirati private networks while bare metal alternatives face intensifying cost compression in North African public tenders. Egyptian hospital procurement committees exhibit highest price sensitivity; Saudi tertiary centers show lowest.
Supply Chain Analysis
EU MDR extraterritorial controls restrict CE-marked device flows to Middle Eastern importers lacking updated conformity documentation. Manufacturing concentrates in Germany, Switzerland, and Ireland for drug-eluting platforms; South Korean and Japanese suppliers anchor antiplatelet pharmaceutical APIs. Single-source vulnerability runs through Dubai's Jebel Ali consolidation point for regional redistribution. Distribution feeds from manufacturer direct sales teams into hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioresorbable scaffold disruption is compressing metallic stent margins across Middle Eastern catheterization laboratories, with SFDA pathway acceleration creating first-mover windows for transient vascular support technologies.
For Market Incumbents: Build regulatory moat through accelerated SFDA and SAHPRA dual-track submissions for bioresorbable platforms ahead of metallic stent commoditization. Deepen catheterization laboratory partnership networks in Egypt's expanding public infrastructure to lock in procedural volume. Defend against generic antiplatelet erosion by anchoring dual antithrombotic protocols in Gulf Cooperation Council formularies.
For New Entrants and Emerging Players: Build out Moroccan distribution infrastructure before European competitors establish catheterization laboratory relationships. Target Algeria's underpenetrated public cardiology centers through wholesaler partnerships that navigate import licensing complexity. Pursue Egyptian generic antiplatelet market entry via localized bioequivalence pathways that bypass originator data requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors device-pharmaceutical convergence plays over pure hardware manufacturers. Five-to-ten year viability hinges on bioresorbable scaffold adoption curves displacing permanent metallic implants. Signal to watch: intravascular imaging integration with robotic-assisted platforms in Dubai and Riyadh tertiary centers indicating premium procedure bundle maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Dual-Track Registration | Accelerates bioresorbable scaffold approval timelines ahead of metallic stent commoditization. |
| Egyptian Catheterization Laboratory Partnership | Locks in procedural volume through Ministry of Health capital allocation expansion. |
| Intravascular Imaging Integration | Creates premium procedure bundles with robotic-assisted platforms at Dubai tertiary centers. |
| Generic Antiplatelet Bioequivalence Pathway | Enables cost-competitive Egyptian market entry via localized regulatory standards. |
| Moroccan Wholesaler Network Development | Establishes distribution presence before European competitors consolidate channel control. |
Research Methodology
Operator-level perspectives from interventional cardiologists, hospital procurement managers, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary fieldwork combined with secondary validation against SFDA registration databases, SAHPRA post-market surveillance filings, Egyptian drug authority bioequivalence standards, and EU MDR conformity assessment documentation. Bottom-up procedure volume estimates triangulated against top-down health expenditure flows across Gulf Cooperation Council national insurance schemes.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across product type, treatment method, end user facility, and distribution channel dimensions. CAGRs derived from fitted growth curves applied to catheterization laboratory capacity expansion timelines and pharmaceutical formulary adoption rates. Forecast inputs incorporated SFDA pathway velocity, cobalt-chromium alloy price index trajectories, and dual antithrombotic protocol penetration by cardiology center tier.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bioresorbable scaffold specialists or Gulf state health insurance expansion would shift outcomes. Material shifts in EU MDR implementation rigor or South African platinum-group metal supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Ischemia Market
Cardiovascular
Stroke Management Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Pulmonary Valve Replacement Market