
 Geopolymer Market | 2026-2036
Geopolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Geopolymer Market Intelligence
Market Context
The geopolymer supply channel is fragmenting as specialty chemical distributors, direct-to-contractor platforms, and integrated concrete producers compete for specification authority. Betolar PLC leverages its Nordic technology base to anchor low-carbon binder formulations for European infrastructure clients. Wagners Holding Company Limited dominates Australian project pipelines through captive supply of fly-ash-derived geopolymer concrete. Imerys Group sustains raw material security via vertical control over metakaolin deposits in France and Ukraine.
Technical Definition and Segment Structure
Geopolymers are inorganic alumino-silicate materials synthesized through alkaline activation of industrial byproducts or natural pozzolans, typically achieving compressive strengths of 20–80 MPa within 24 hours under ambient or thermal curing regimes. Their primary commercial purpose centers on replacing Ordinary Portland Cement in structural concrete, precast elements, and waste encapsulation matrices where carbon footprint reduction carries specification weight. Low-calcium geopolymer formulations occupy the dominant share of current production volume due to superior thermal stability and chemical resistance in nuclear waste immobilization applications. High-calcium variants represent the fastest-expanding technology segment, driven by compatibility with existing concrete batching infrastructure and accelerated setting profiles demanded by construction contractors. Marine infrastructure applications concentrate margin pools where sulfate resistance and chloride impermeability justify premium positioning against conventional cement systems.
Regulatory Frame and Outlook
The EU Green Deal's carbon border adjustments and the EPA's emerging standards for embodied carbon in federal construction projects are reshaping specification criteria for structural materials across public procurement channels. REACH compliance for alkaline activators and GB standards in China for geopolymer-based building products create divergent compliance pathways that segment market access by geography. Stakeholders must monitor regulatory momentum in carbon accounting methodologies, as evolving lifecycle assessment protocols will determine whether geopolymer binders qualify for green procurement preferences in infrastructure tenders.
Market Dynamics
Alkaline activation chemistry is displacing conventional clinker production as the dominant pathway for structural binder manufacturing, with regulatory carbon accounting now determining specification authority across public infrastructure procurement channels.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Public construction tenders in Germany, France, and the Netherlands now require lifecycle assessment documentation that favors low-carbon binders in bridge and tunnel applications.
- Fly ash valorization economics:Power utilities in coal-dependent regions face landfill restrictions that transform combustion residues from liability to revenue-generating feedstock for geopolymer synthesis.
- Nuclear waste immobilization demand:Radioactive waste management agencies specify low-calcium geopolymer matrices for cesium and strontium encapsulation due to superior thermal stability versus borosilicate glass.
Market Restraints
- Sodium silicate supply concentration:Alkaline activator production clusters in China and Germany, creating input cost volatility when energy prices spike or export controls activate.
- Metakaolin deposit geography:Premium calcined clay reserves concentrate in France, Ukraine, and Brazil, limiting formulation flexibility for producers distant from these extraction points.
- Ordinary Portland Cement substitution resistance:Established concrete batching infrastructure, contractor familiarity, and performance guarantee frameworks slow specification switching in private commercial construction.
Strategic Opportunities
- India infrastructure buildout:National highway and railway expansion programs under the Ministry of Road Transport and Highways create specification windows for domestic fly-ash-based geopolymer in precast elements.
- Marine infrastructure sulfate resistance:Port authorities in Australia and the Netherlands specify geopolymer for seawall and dock construction where chloride impermeability commands premium positioning.
- Carbon border adjustment arbitrage:EU importers of embodied-carbon-intensive construction materials face tariff exposure that domestic geopolymer production avoids, incentivizing localized manufacturing investment.
Industry Challenges
- Alkaline activator handling protocols:Site crews require specialized training for sodium hydroxide and potassium silicate safety management, extending project mobilization timelines and insurance liability exposure.
- Performance certification latency:National building codes in most jurisdictions lack prescriptive provisions for geopolymer concrete, forcing case-by-case engineering approval that compresses project schedules.
- Curing regime standardization:Ambient versus thermal curing protocols vary by formulation and climate, complicating quality assurance and creating batch-to-batch performance inconsistency risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geopolymer Market |
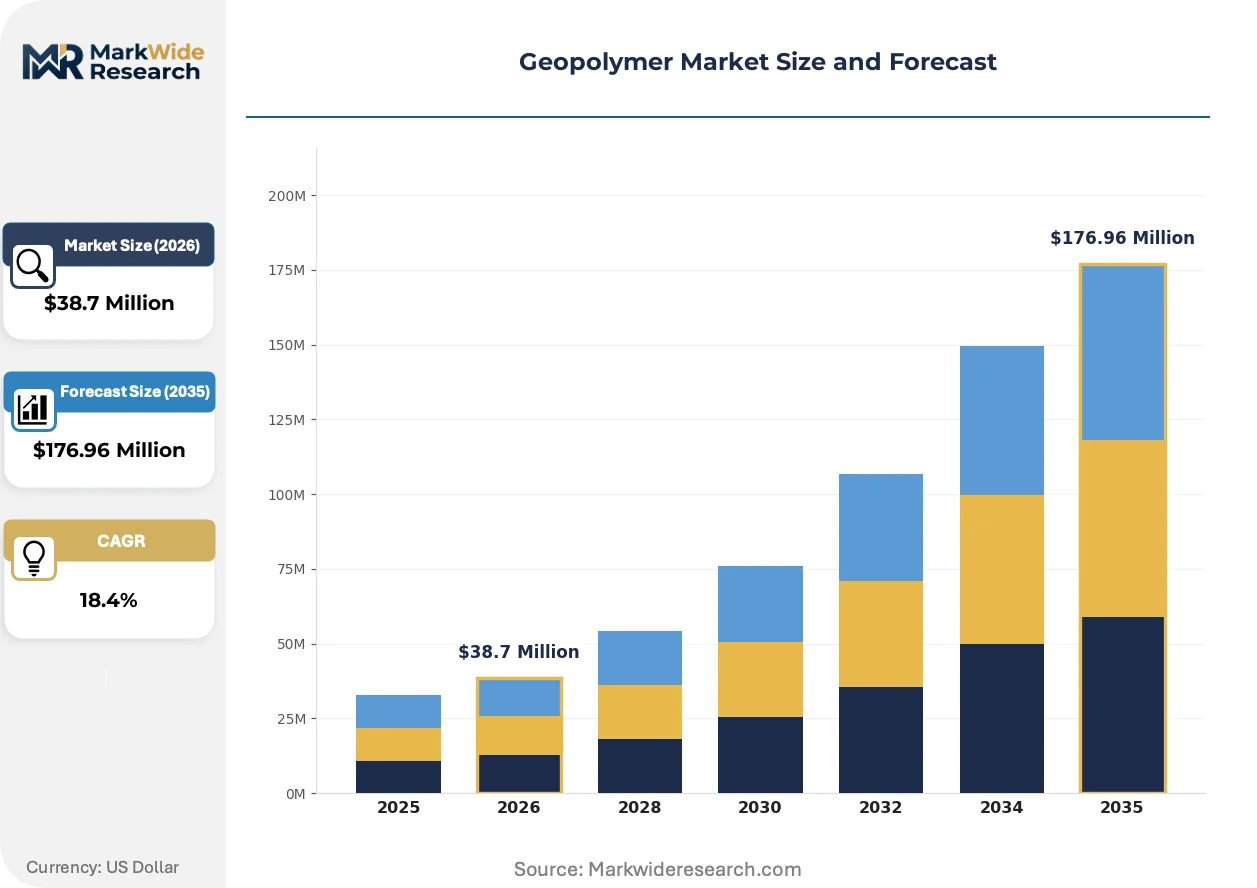
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $176.96 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binder, Foam, Paste, Mortar, Concrete Technology: Low-Calcium Geopolymers, High-Calcium Geopolymers, Ambient Cure, Heat Cure, One-Part Formulations Application: Construction Materials, Fire Resistance, Waste Immobilization, Marine Infrastructure, Repair & Restoration End User: Construction Companies, Chemical Processing Plants, Marine Engineers, Environmental Agencies, Restoration Contractors |
| Companies Covered | Schlumberger Limited, Banah UK Ltd, Wagners Holding Company Limited, Betolar PLC, Imerys Group, Zeobond Pty Ltd, PCI Augsburg GmbH, Geopolymer International Inc., CEMEX SAB de CV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geopolymer Market Strategic Shifts & Innovations
Formulation science is converging with carbon accounting methodologies to redefine competitive advantage in structural materials procurement, with specification authority shifting from commodity distributors to technology-integrated concrete producers.
High-calcium geopolymer chemistry is hybridizing with existing ready-mix concrete infrastructure, enabling adoption without batching plant retrofit. Construction contractors in Australia and the Netherlands specify these formulations for accelerated setting profiles that compress construction schedules. The technology is hybridizing performance characteristics—combining Portland-compatible workability with geopolymer durability metrics—to bridge adoption gaps in conventional building sectors.
REACH compliance pathways for alkaline activators are tightening classification requirements for sodium silicate solutions above specific concentration thresholds. German and French chemical distributors face re-registration costs that favor integrated producers with in-house activator synthesis capability. Precast concrete manufacturers in Northern Europe respond by consolidating supply relationships with technology licensors who guarantee regulatory documentation packages.
Engineering-procurement-construction firms now require embodied carbon declarations as standard bid submission elements, unbundling material sourcing from construction contracting. Infrastructure agencies in California, New South Wales, and the Netherlands mandate third-party-verified Environmental Product Declarations that disadvantage imported conventional cement. This specification shift concentrates contract awards with domestic producers capable of localized lifecycle data generation and rapid certification turnaround.
Geopolymer Market Segmentation
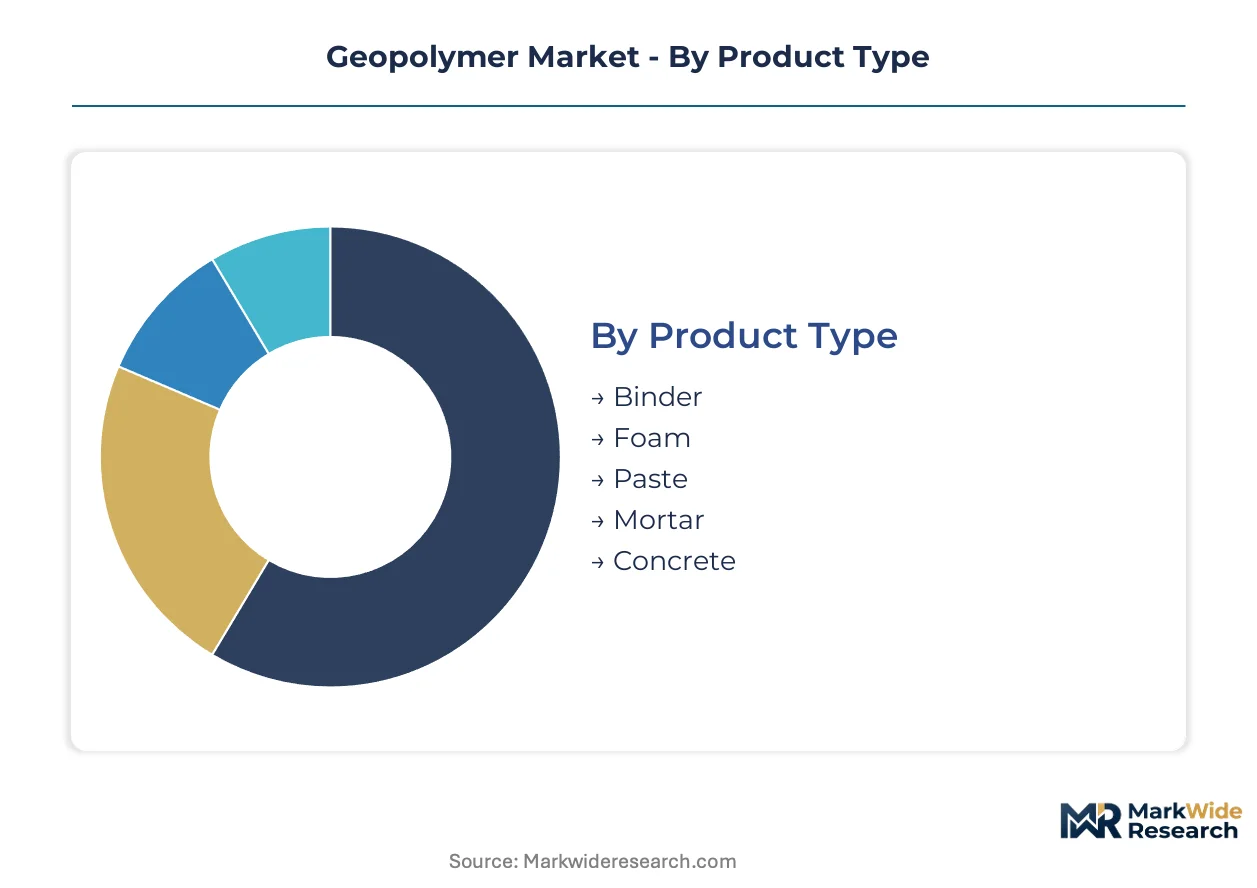
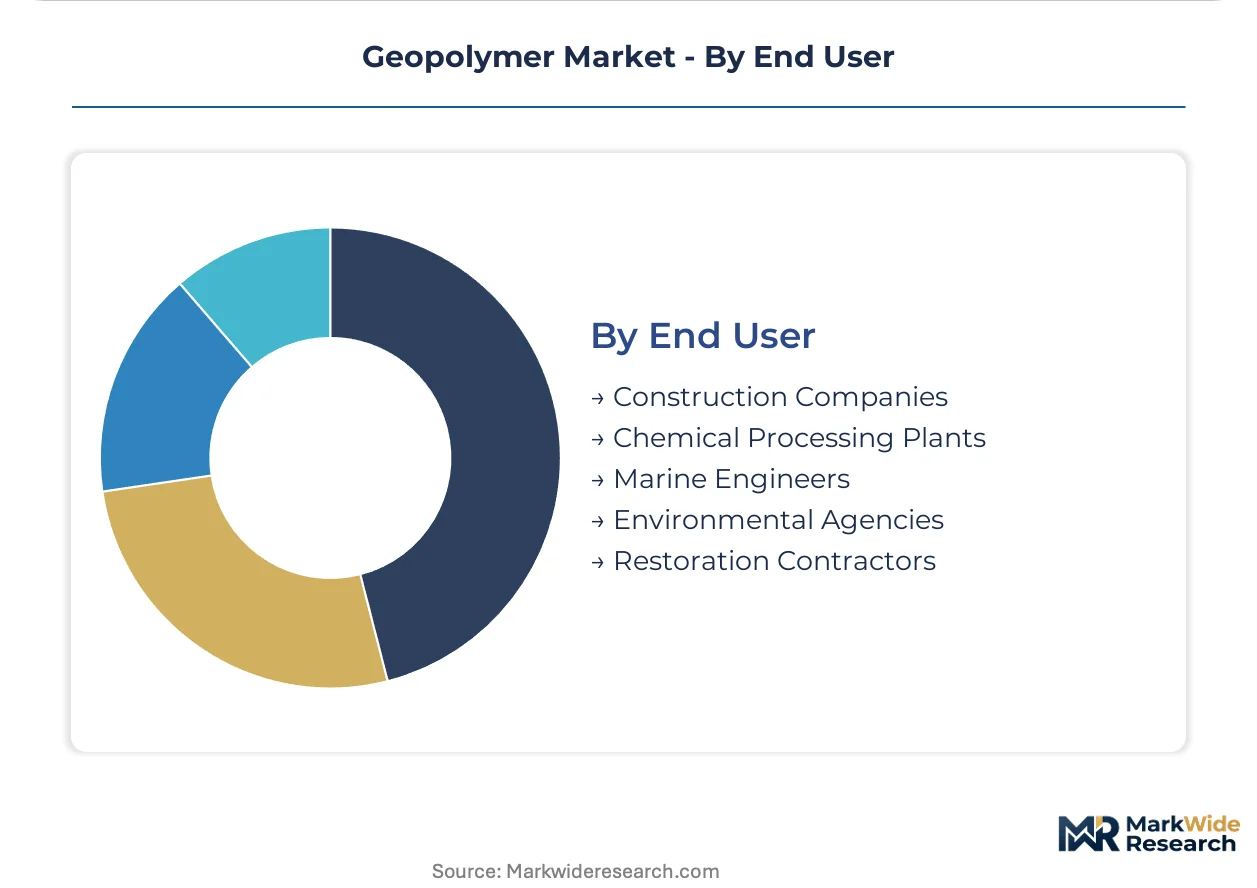
Geopolymer specification authority fragments across product chemistry, curing protocols, and end-use performance requirements. Contractors, waste management agencies, and marine engineers each demand tailored formulations with distinct technical service intensity.
Product Type:
After-sales service intensity varies sharply across product forms, with fluid systems requiring batching plant integration support while pre-formulated binders demand minimal field technical assistance.
- Concrete:Ready-mix and precast applications dominate commercial volume. Wagners Holding Company Limited anchors Australian infrastructure specifications through captive supply of fly-ash-derived geopolymer concrete for structural elements. Contractors prioritize this segment for compressive strength parity with Portland cement systems.
- Binder:Alkaline-activated powder concentrates enable on-site formulation flexibility. Betolar PLC licenses Nordic low-carbon binder technology to European precast manufacturers seeking REACH-compliant activator integration. Demand concentrates where transport economics favor localized mixing versus bulk liquid delivery.
- Foam:Lightweight thermal insulation matrices serve fire-resistant cladding applications.
- Paste:High-viscosity formulations anchor waste encapsulation and repair grouting.
- Mortar:Masonry bonding systems target restoration contractors requiring compatible rheology with historic substrates.
Concrete holds the largest share; momentum sits with binder formulations climbing the fastest as distributed manufacturing reduces logistics costs.
Technology:
Cost tier stratification separates premium heat-cure systems for precast factories from economy-grade ambient-cure formulations suited to remote construction sites lacking thermal infrastructure.
- High-Calcium Geopolymers:Portland-compatible chemistry accelerates setting profiles for contractor schedule compression. Australian and Dutch construction firms specify these formulations to avoid batching plant retrofit investments. The technology bridges adoption gaps through workability familiar to conventional concrete crews.
- One-Part Formulations:Pre-blended powder systems eliminate on-site activator handling hazards. Imerys Group leverages vertical control over French metakaolin deposits to supply packaged formulations for remote marine infrastructure projects. Safety liability reduction drives specification switching in insurance-sensitive contracts.
- Low-Calcium Geopolymers:Superior thermal stability serves nuclear waste immobilization specifications.
- Ambient Cure:Room-temperature hardening suits field-cast applications lacking thermal infrastructure.
- Heat Cure:Elevated-temperature processing accelerates strength development in factory-controlled environments.
High-calcium variants command the dominant production position; one-part formulations are expanding most quickly as safety regulations tighten.
Application:
Volume concentration tracks public infrastructure procurement cycles, with marine and waste applications commanding premium margins through specialized performance certification requirements.
- Construction Materials:Structural concrete, precast elements, and masonry systems absorb the majority of production volume. EU Green Deal embodied carbon mandates in Germany, France, and the Netherlands reshape tender evaluation criteria for bridge and tunnel applications. National highway agencies specify Environmental Product Declarations as mandatory bid elements.
- Waste Immobilization:Low-calcium matrices encapsulate radioactive cesium and strontium with thermal stability exceeding borosilicate glass. Nuclear waste management agencies in multiple geographies specify geopolymer for long-term repository storage. Regulatory acceptance protocols drive extended qualification timelines.
- Marine Infrastructure:Seawalls, docks, and coastal protection structures leverage sulfate resistance and chloride impermeability.
- Fire Resistance:Refractory linings and passive fire protection systems exploit thermal stability.
- Repair & Restoration:Compatible substrate bonding targets historic masonry conservation.
Construction materials anchor volume leadership; waste immobilization represents the steepest expansion trajectory as nuclear decommissioning accelerates.
End User:
Customer type determines procurement channel structure, with environmental agencies mandating extended qualification protocols while construction companies prioritize rapid certification turnaround.
- Construction Companies:Residential and commercial building contractors drive specification adoption through embodied carbon reduction commitments. Engineering-procurement-construction firms now unbundle material sourcing from construction contracting based on third-party-verified lifecycle data. California and New South Wales infrastructure agencies mandate localized Environmental Product Declaration generation.
- Marine Engineers:Port authorities in Australia and the Netherlands specify geopolymer for seawall construction where chloride impermeability justifies premium positioning. Sulfate resistance performance guarantees command specification authority against conventional cement systems.
- Environmental Agencies:Radioactive waste regulators impose stringent matrix qualification protocols.
- Chemical Processing Plants:Acid-resistant containment structures exploit chemical stability.
- Restoration Contractors:Historic substrate compatibility drives niche specification demand.
Construction companies dominate procurement volume; marine engineers are gaining share fastest as coastal infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Australia exceeds that in India by a substantial margin, reflecting divergent regulatory maturity and infrastructure procurement sophistication. Fly-ash valorization economics concentrate manufacturing advantage in coal-dependent regions. Specification authority flows to producers capable of localized Environmental Product Declaration generation.
Australia
Port authorities in Queensland and New South Wales specify geopolymer concrete for seawall construction where chloride impermeability commands premium positioning against conventional cement. The country's building code amendment process incorporates embodied carbon metrics for federal infrastructure tenders. Wagners Holding Company Limited anchors project pipelines through captive supply of fly-ash-derived formulations for structural elements in Brisbane and Sydney metro corridors.
Germany
Federal Ministry for Housing, Urban Development and Building mandates lifecycle assessment documentation for bridge and tunnel applications under national climate protection frameworks. REACH compliance pathways for alkaline activators tighten classification requirements that favor integrated producers with in-house synthesis capability. Precast manufacturers in North Rhine-Westphalia consolidate supply relationships with technology licensors who guarantee regulatory documentation packages.
India
National highway expansion under the Ministry of Road Transport and Highways creates specification windows for domestic fly-ash-based geopolymer in precast elements. The Bureau of Indian Standards develops geopolymer-based building product codes that diverge from European compliance pathways. Manufacturing clusters in Gujarat and Maharashtra leverage captive thermal power plant residues to undercut imported binder costs.
Netherlands
Rijkswaterstaat infrastructure tenders now require third-party-verified Environmental Product Declarations that disadvantage imported conventional cement. The EU Green Deal's carbon border adjustments reshape specification criteria for structural materials across public procurement channels. Rotterdam port authorities specify geopolymer for dock construction where sulfate resistance justifies premium positioning against Portland systems.
United States
California Department of Transportation mandates embodied carbon declarations as standard bid submission elements for state-funded construction. The EPA's emerging standards for embodied carbon in federal projects accelerate specification switching in public infrastructure. Engineering-procurement-construction firms in the Pacific Northwest unbundle material sourcing from construction contracting based on localized lifecycle data generation.
Geopolymer Market Key Industry Players
Technology-integrated concrete producers and specialty chemical distributors split the market along specification authority lines. The supply channel fragments as direct-to-contractor platforms compete with established distributor networks for project influence. Three archetypes dominate: captive infrastructure suppliers with vertical raw material control, technology licensors with regulatory documentation capabilities, and diversified construction material conglomerates with batching plant networks. Competitive moves center on capacity expansion in fly-ash-proximate regions and strategic partnerships with engineering-procurement-construction firms for specification embedding.
Among technology licensors, Betolar PLC exemplifies the Nordic low-carbon binder formulation archetype, while Imerys Group occupies a position representing vertical control over metakaolin deposit security. Wagners Holding Company Limited anchors the captive infrastructure supplier archetype through Australian project pipeline dominance. These three entities illustrate how geographic raw material access and regulatory documentation capability determine competitive positioning across distinct procurement channels.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Banah UK Ltd |
| Wagners Holding Company Limited |
| Betolar PLC |
| Imerys Group |
| Zeobond Pty Ltd |
| PCI Augsburg GmbH |
| Geopolymer International Inc. |
| CEMEX SAB de CV |
| Others |
Cost & Logistics Intelligence
Undercapacity in European alkaline activator synthesis is tightening supplier discipline and compressing margin flexibility for geopolymer concrete producers dependent on imported sodium silicate. German and French chemical distributors leverage this tightness to extract premium terms from precast manufacturers lacking in-house activator production.
Pricing Analysis
Configured-to-order binder formulations command spreads of 15–25% above standard-grade concrete pricing due to activator customization and thermal curing infrastructure requirements. Three-tier pricing structure across premium, standard, and economy levels separates nuclear-grade low-calcium matrices from construction-grade high-calcium variants and bulk fly-ash blends. Cost compression in standard-grade formulations is intensifying because Chinese sodium silicate export quotas restrict input availability. Precast manufacturers exhibit the highest price sensitivity due to thin margins on volume highway contracts, while nuclear waste agencies accept premium positioning for qualification-assured encapsulation matrices.
Supply Chain Analysis
Export-control regimes on concentrated alkaline solutions above specific concentration thresholds restrict cross-border flows of sodium silicate from Chinese and German production hubs. Supply concentrates in Australia, India, and the Netherlands for finished geopolymer concrete, while feedstock extraction draws from French and Ukrainian metakaolin deposits and Australian fly-ash streams. Single-source vulnerability in premium calcined clay reserves limits formulation flexibility for producers distant from European extraction points. Distribution runs through direct-to-contractor platforms competing with established specialty chemical distributor networks for project specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified alkaline activator synthesis capability remains scarce relative to formulation demand, creating acquisition premiums for producers with in-house REACH-compliant production. This gap separates technology-integrated concrete producers from commodity distributors losing specification authority.
For Market Incumbents: Pre-empt activist chemistry substitution by securing captive fly-ash supply agreements with coal-dependent utilities facing landfill restrictions. Add ambient-cure capacity in Gujarat and Queensland to defend against emerging local producers exploiting feedstock proximity. Regulatory documentation capabilities anchor retention of European infrastructure tenders against technology licensors. For New Entrants and Emerging Players: Pursue white-space positioning in Indian national highway precast elements where Bureau of Indian Standards code development creates temporary specification windows. Marine infrastructure in Australian port authorities offers the most penetrable premium segment due to chloride impermeability requirements unmet by conventional cement. License Nordic binder technology to accelerate regulatory approval timelines. For Investors and Strategic Acquirers: Capital is best deployed toward vertically controlled producers with upstream metakaolin deposit access and downstream batching plant networks. Long-term viability hinges on carbon border adjustment arbitrage as EU tariff exposure intensifies for imported conventional cement. Watch for EPA embodied carbon standard finalization as inflection indicator for US public procurement switching.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkaline Activator Synthesis | REACH compliance costs favor in-house sodium silicate production over distributor reliance in Germany and France. |
| Long-term Fly-Ash Supply Agreement | Coal utility landfill restrictions transform combustion residues into captive feedstock for Australian and Indian producers. |
| Environmental Product Declaration Certification | Third-party verification anchors specification authority for Rijkswaterstaat and California Department of Transportation tenders. |
| Joint Venture with Marine Engineering Firm | Port authority relationships in Rotterdam and Queensland accelerate seawall and dock construction specification embedding. |
| Technology Licensing to Precast Manufacturer | Nordic low-carbon binder formulations transfer regulatory documentation packages to European infrastructure clients. |
Research Approach
Initial hypotheses were tested against primary input from geopolymer plant managers, concrete procurement leads at engineering-procurement-construction firms, alkaline activator distribution channel partners, and nuclear waste management technical directors and refined through secondary validation against EU Green Deal implementation documents, EPA emerging standard notices, Bureau of Indian Standards draft codes, and customs trade data on metakaolin and fly-ash flows. Bottom-up project pipeline analysis triangulated with top-down carbon accounting policy impact assessment.
Demand-supply balance modeling across product chemistry, curing protocol, and end-use performance dimensions structured volume projections throughout the forecast period. CAGRs derived from segmented adoption curves weighted by regulatory enforcement timelines and infrastructure procurement cycles. Nuclear decommissioning schedules and coal plant retirement trajectories informed waste immobilization and feedstock availability assumptions.
Sensitivities concentrate around REACH re-registration outcomes for alkaline activators and carbon border adjustment implementation timing. Forecasts reflect documented assumptions on specification switching rates in public infrastructure channels. Material shifts in EU Green Deal embodied carbon mandate enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
PEKK Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Ionomer Resins Market