
 Polypropylene Filler Sheet Market | 2026-2036
Polypropylene Filler Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Filler Sheet Market Analytics
The gap between commodity-grade and performance-engineered polypropylene filler formulations is narrowing as twin-screw compounding and mineral reinforcement technologies mature. Inteplast Group leverages its North American extrusion footprint to sustain supply continuity for automotive tier suppliers. Primex Plastics Corporation differentiates through customized color-matched sheet production for point-of-purchase display applications. Polyreflex Hi-Tech Co., Ltd anchors its position in Asia-Pacific through integrated PP resin-to-sheet manufacturing.
Polypropylene filler sheet consists of polypropylene resin compounded with mineral fillers such as talc, calcium carbonate, or glass fiber, extruded into flat panels with densities typically ranging from 0.6 to 1.2 g/cm³ depending on loading ratios; the material serves primarily as a lightweight, rigid substrate for structural and protective applications across industrial and consumer sectors. Standard sheet dominates volume throughput in packaging dunnage and temporary surface protection, while reinforced sheet commands premium positioning in automotive load floors and construction formwork where flexural modulus requirements exceed 2,500 MPa. Laminated sheet variants are gaining traction in consumer goods displays as brand owners specify UV-stable, printable surfaces for retail environments.
US EPA guidelines on recycled content thresholds and California's rigid plastic packaging regulations are reshaping formulation strategies for suppliers targeting North American OEMs. China's SAMR enforces GB standards for plastic product labeling and restricted substance limits that directly affect import eligibility and domestic production compliance. REACH registration requirements in Europe constrain the use of certain mineral filler surface treatments, pushing compounders toward silane-coupling alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks across these jurisdictions to anticipate compliance-driven material substitutions before they disrupt established supply arrangements.
Market Dynamics
Twin-screw compounding advances and China's tightening GB standards for recycled content are compressing the performance gap between commodity and engineered grades, forcing compounders to recalibrate formulation investments across automotive and construction supply chains.
Growth Catalysts
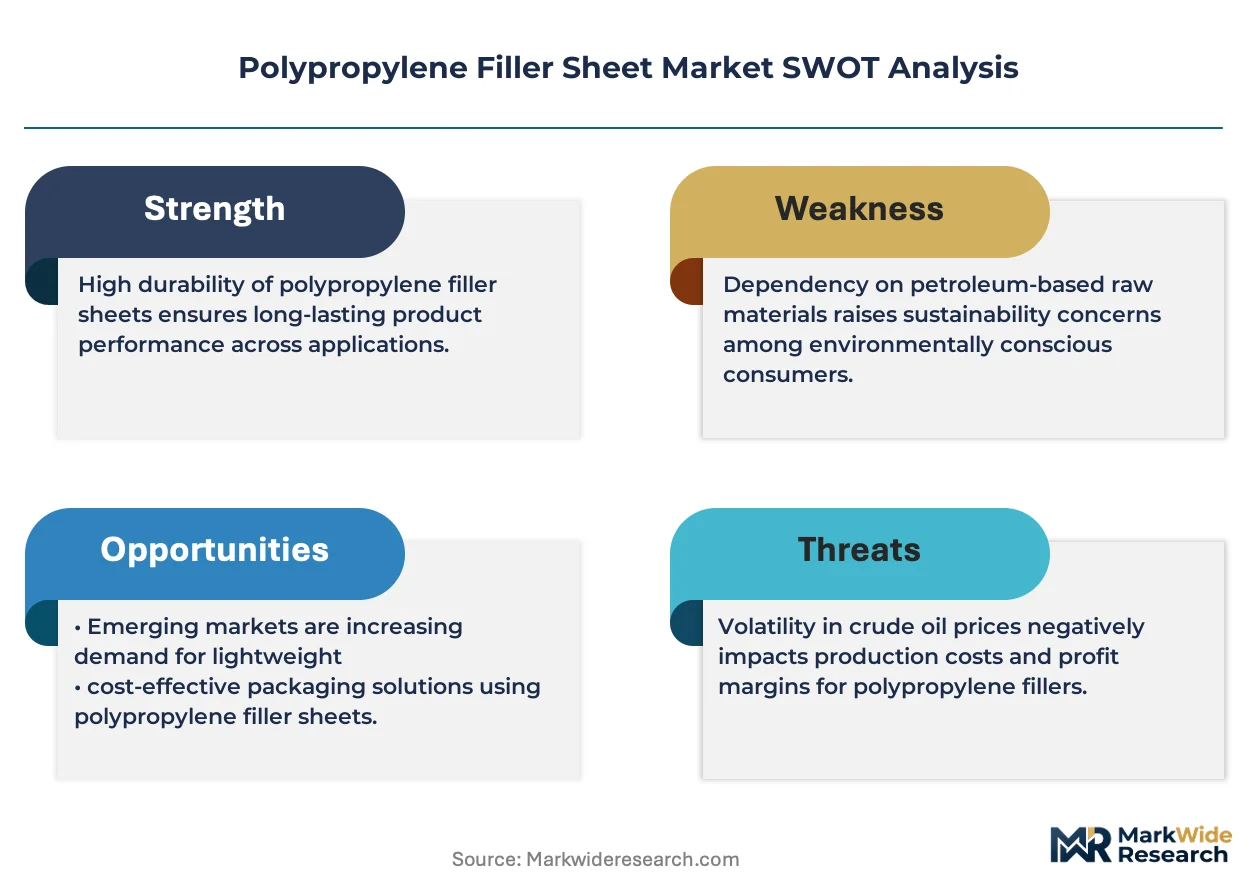
- Automotive lightweighting mandates:OEMs in Germany, Japan, and the United States specify mineral-reinforced polypropylene filler sheet for interior paneling and load floors to meet fleet efficiency targets.
- REACH registration pressure:ECHA constraints on certain mineral filler surface treatments accelerate silane-coupling agent adoption, opening premium positioning for compliant European compounders.
- Guangdong manufacturing concentration:Integrated PP resin-to-sheet operations in this province reduce logistics costs for export-oriented packaging and display manufacturers.
Market Restraints
- Calcium carbonate price volatility:Energy-intensive mineral processing exposes compounders to electricity cost swings in China and Southeast Asia.
- East Asian supply concentration:Overreliance on Zhejiang and Guangdong extrusion capacity creates vulnerability to regional power rationing or port congestion.
- Glass fiber substitution ceiling:Flexural modulus requirements above 3,500 MPa push automotive engineers toward long-fiber thermoplastic composites.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic compounding investments targeting automotive tier suppliers can capture import substitution incentives.
- UV-stable laminated sheet for retail displays:Brand owners in North American and European consumer goods sectors specify printable, weather-resistant surfaces for outdoor point-of-purchase installations.
- California rigid plastic packaging regulations:Recycled content thresholds create compliant formulation demand from suppliers serving West Coast OEMs.
Industry Challenges
- Twin-screw compounding expertise scarcity:Mineral dispersion optimization and L/D ratio calibration require specialized process engineers concentrated at European and Japanese equipment suppliers.
- Extended producer responsibility compliance timelines:Evolving frameworks in the European Union, individual US states, and Chinese provinces demand parallel tracking systems for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Filler Sheet Market |
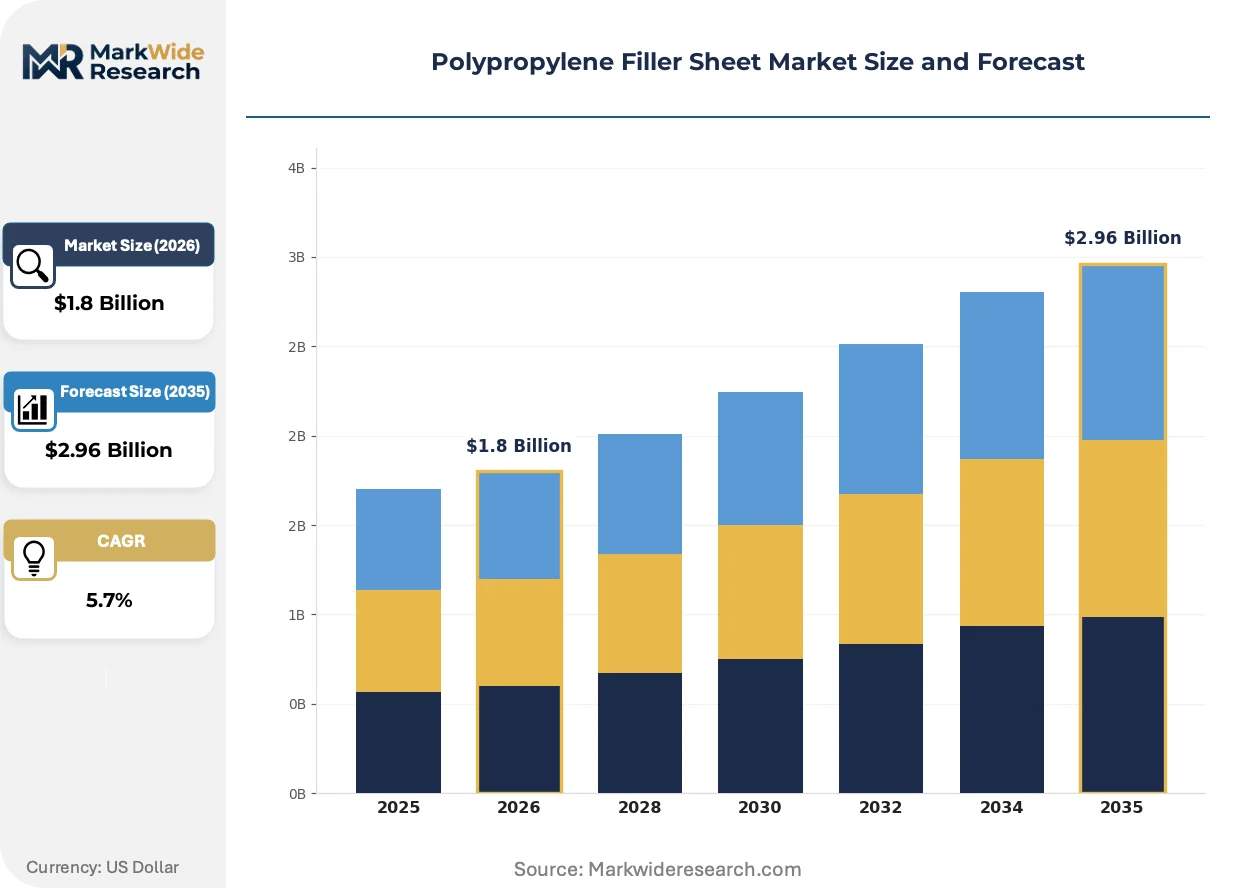
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Sheet, Custom Sheet, Reinforced Sheet, Laminated Sheet Application: Automotive, Packaging, Construction, Consumer Goods End User: Manufacturers, Retailers, Distributors, Exporters Thickness: Thin Sheet, Medium Sheet, Thick Sheet, Ultra-Thin Sheet |
| Companies Covered | Inteplast Group, Primex Plastics Corporation, Corplex, Polyreflex Hi-Tech Co., Ltd, Corex Plastics (Australia) Pty. Ltd., Aerolam Group, Nilkamal Bubble Guard, PPP Solution, Tecafine Polymers Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Filler Sheet Market Evolving Landscape
Digital process control and real-time rheology monitoring are transforming how compounders validate batch consistency, reducing specification drift in high-volume automotive contracts.
Inline near-infrared spectroscopy for mineral loading verification is digitizing quality assurance workflows at extrusion lines serving automotive tier suppliers. German and Japanese OEMs now mandate digital batch records for structural interior components. This capability compresses qualification cycles from months to weeks for new compound formulations.
China's SAMR enforcement of updated GB standards for plastic product labeling and restricted substance limits is tightening import eligibility criteria. Domestic producers must reformulate to maintain access to automotive and electronics supply chains. European compounders with pre-validated REACH compliance capture displaced volume from non-compliant Asian competitors.
Specification-driven procurement contracts now dominate automotive and construction verticals, replacing spot-market purchasing for structural applications. Buyers consolidate supplier panels to three approved compounders per region, demanding captive inventory and VMI arrangements. This concentration is most visible in German automotive supply chains and Japanese electronics packaging.
Polypropylene Filler Sheet Market Segmentation
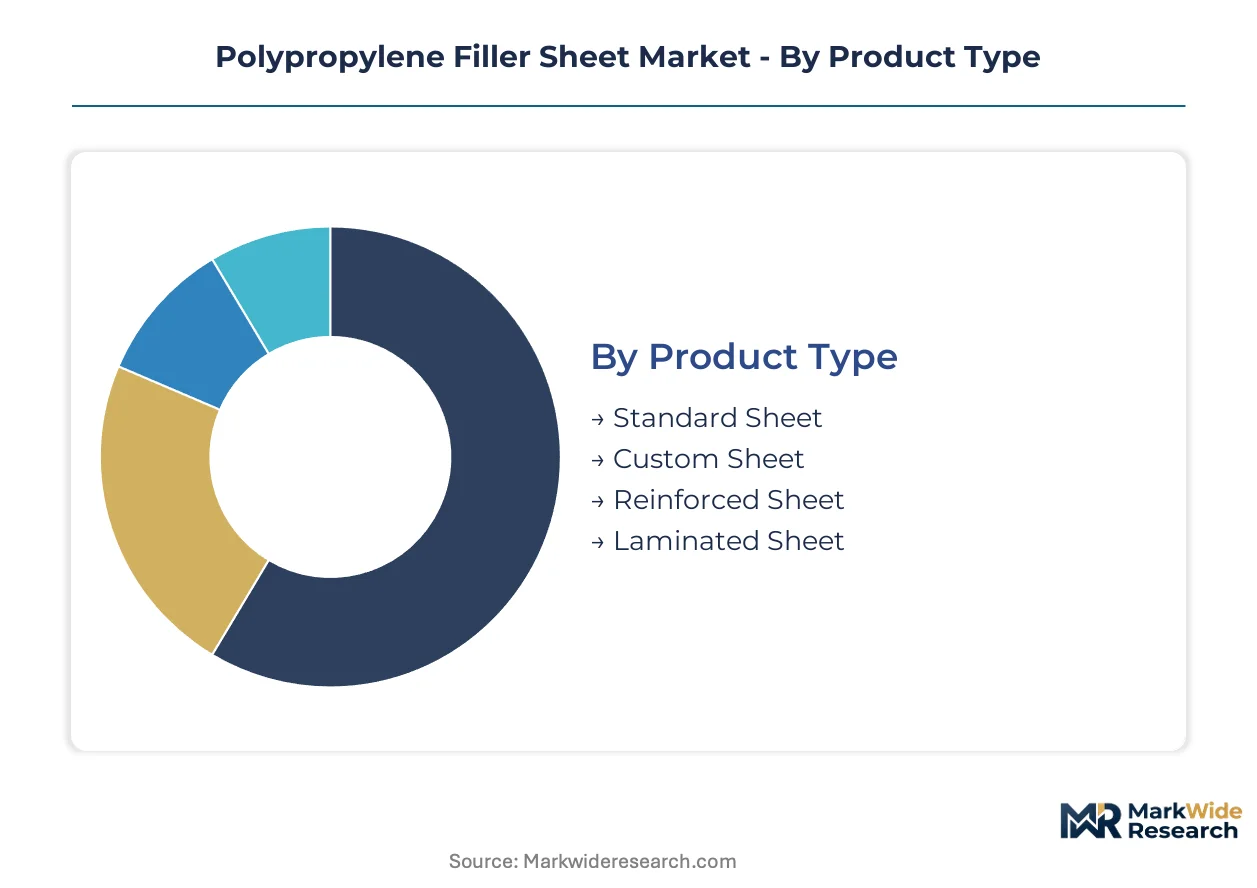
Polypropylene filler sheet procurement cycles vary dramatically by formulation complexity and end-use criticality. Standard grades turn inventory weekly for packaging dunnage, while laminated automotive grades require months-long qualification. This velocity dispersion shapes working capital requirements and supplier relationship structures across the value chain.
Product Type:
Cycle times compress from months to days as mineral loading decreases and surface finishing simplifies, creating distinct cash-flow profiles across the four formulation tiers.
- Standard Sheet:Unfilled or lightly loaded PP resin extruded at 0.6-0.9 g/cm³ density serves high-volume packaging dunnage and temporary surface protection. Guangdong converters turn this inventory every 5-7 days for export-oriented electronics packaging, though calcium carbonate price volatility squeezes compounder margins unpredictably.
- Reinforced Sheet:Glass fiber or high-talc loading pushes flexural modulus above 2,500 MPa for automotive load floors and construction formwork. German and Japanese OEMs mandate 12-18 month qualification cycles, but specification lock-in delivers multi-year contract visibility once approved.
- Custom Sheet:Formulation-tuned products for proprietary customer specifications occupy mid-cycle velocity, typically 4-8 week production runs.
- Laminated Sheet:UV-stable printable surfaces for retail displays require longest cycle times due to multi-layer coextrusion and surface coating steps.
Standard Sheet dominates installed base. Reinforced Sheet is where expansion concentrates.
Application:
Cost tiers separate dramatically: automotive commands formulation premiums above 40% versus commodity packaging, while construction sits at mid-tier pricing with volume scale advantages.
- Automotive:Interior paneling and load floor substrates must satisfy NHTSA flammability and German OEM flexural specifications simultaneously. Mineral-reinforced grades from Zhejiang compounders now displace ABS in door trim applications as OEMs chase fleet efficiency mandates.
- Packaging:Returnable dunnage and temporary surface protection consume the highest tonnage at thinnest margins, with Guangdong extruders serving electronics exporters on 30-day payment terms.
- Construction:Concrete formwork and temporary protection boards favor medium-density talc-filled grades with rebar-puncture resistance.
- Consumer Goods:Point-of-purchase displays specify color-matched, UV-stable surfaces with shortest production runs and highest SKU fragmentation.
Packaging commands volume leadership. Automotive delivers margin expansion.
End User:
Procurement sophistication stratifies sharply: manufacturers enforce specification-driven panel consolidation, while distributors maintain spot-market flexibility for smaller accounts.
- Manufacturers:Tier-1 automotive and electronics OEMs maintain approved-supplier panels of three compounders per region, demanding VMI inventory and digital batch traceability. REACH pre-validation now filters Asian supplier eligibility for European manufacturing footprints.
- Distributors:Regional stocking intermediaries absorb demand volatility for construction and packaging segments, though working capital intensity limits their formulation customization capabilities.
- Retailers:Big-box chains and specialty retailers source laminated display sheets through consolidated procurement, specifying California-compliant recycled content thresholds.
- Exporters:Trading companies in Yiwu and Shenzhen bridge domestic Zhejiang extrusion capacity to Southeast Asian and Middle Eastern end-users.
Manufacturers anchor specification control. Distributors capture volume liquidity.
Thickness:
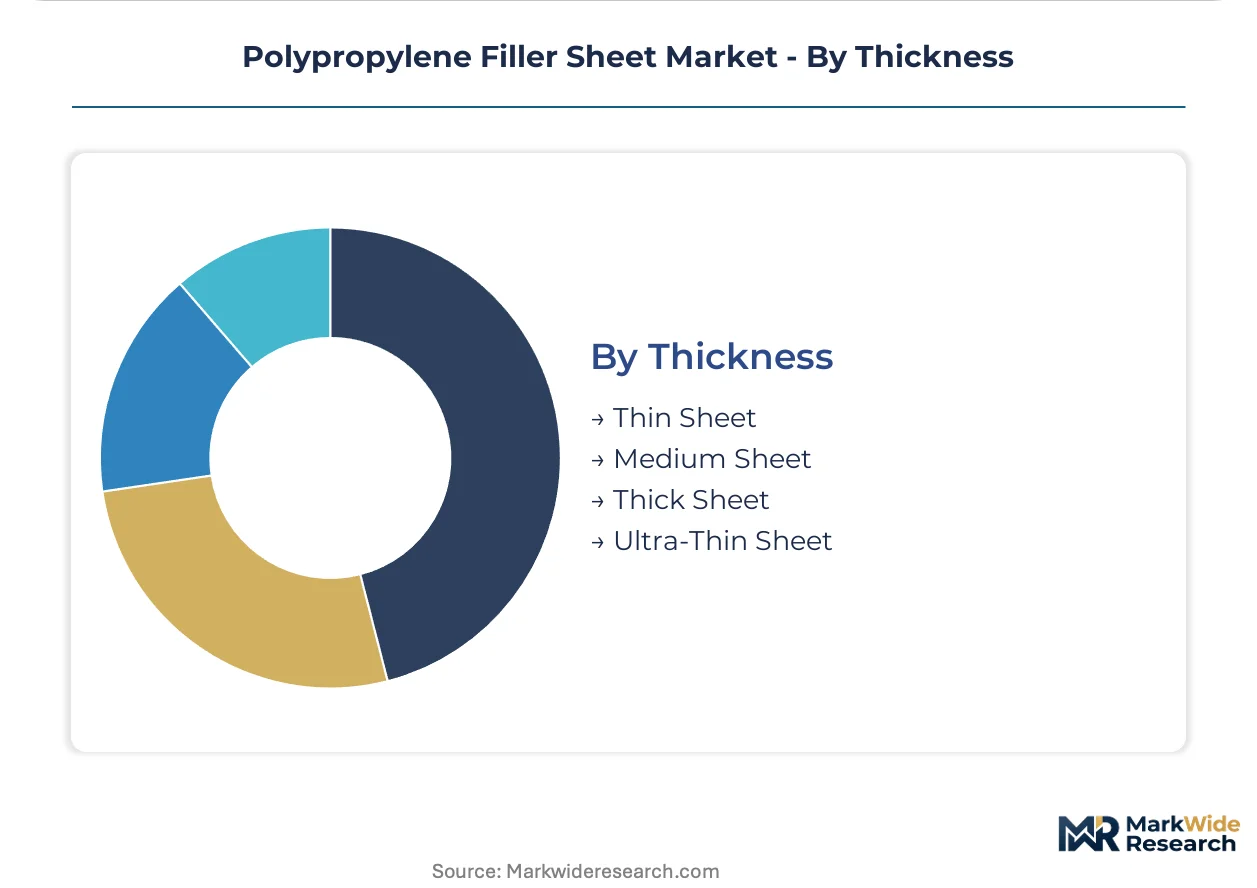
Volume concentrates at medium gauges where extrusion economies peak, while ultra-thin pushes equipment limits and thick sheet requires slower line speeds.
- Medium Sheet:2-5mm gauges balance stiffness and weight for automotive interior panels and reusable packaging dunnage. Zhejiang extruders achieve highest throughput here, with twin-screw compounding lines optimized for this density range.
- Ultra-Thin Sheet:Sub-1mm calipers for electronics interleaving and precision packaging demand specialized die design and tension control. Japanese equipment suppliers dominate this niche, constraining capacity expansion outside established manufacturing clusters.
- Thin Sheet:1-2mm grades serve consumer goods backing and light-duty protection applications with moderate technical barriers.
- Thick Sheet:Above 5mm calipers for construction formwork and heavy-duty dunnage sacrifice line speed for structural rigidity.
Medium Sheet leads throughput economics. Ultra-Thin Sheet faces tightest supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese extrusion capacity in Guangdong and Zhejiang provinces supplies automotive tier suppliers in Germany and Japan, while North American compounders serve domestic OEMs seeking California-compliant recycled content formulations.
China
Automotive interior paneling demand from German and Japanese OEMs drives mineral-reinforced sheet consumption. SAMR enforces updated GB standards for plastic product labeling and restricted substance limits that filter import eligibility. Guangdong province hosts integrated PP resin-to-sheet operations serving export-oriented electronics packaging manufacturers.
Germany
Fleet efficiency mandates push OEMs toward mineral-reinforced grades displacing ABS in door trim applications. ECHA constraints on certain mineral filler surface treatments accelerate silane-coupling agent adoption. Bavarian automotive supply chains consolidate supplier panels to three approved compounders per region with VMI requirements.
United States
EPA guidelines on recycled content thresholds reshape formulation strategies for suppliers targeting domestic OEMs. California's rigid plastic packaging regulations create compliant formulation demand from West Coast manufacturers. Midwest automotive clusters specify mineral-reinforced sheet for load floor substrates to meet NHTSA flammability standards.
Japan
METI efficiency targets drive specification of lightweight cabin substrates in domestic vehicle production. JIS standards govern mineral loading tolerances for structural interior components. Kansai region compounders serve electronics packaging exporters with ultra-thin sheet calipers for precision interleaving applications.
India
PLI scheme incentives for advanced materials attract domestic compounding investments targeting automotive tier suppliers. BIS standards for plastic product quality constrain import eligibility for non-compliant Asian competitors. Maharashtra and Gujarat manufacturing clusters absorb displaced volume from Chinese suppliers facing certification gaps.
Polypropylene Filler Sheet Market Competitive Landscape
On the supply side, the industry is structured around three strategic tiers: integrated resin-to-sheet manufacturers, specialized extrusion houses, and regional compounders serving spot markets. Twin-screw compounding expertise concentrates at European and Japanese equipment suppliers, constraining capacity expansion outside established manufacturing clusters. Dominant competitive moves include backward integration into PP resin production and geographic expansion through distribution partnerships in high-growth manufacturing corridors.
Among Asia-Pacific integrated manufacturers, Polyreflex Hi-Tech Co., Ltd anchors the resin-to-sheet archetype, while Inteplast Group exemplifies North American extrusion scale. Primex Plastics Corporation occupies a position within the specialized tier focused on customized production workflows. These three entities represent distinct strategic postures: captive raw material control, continental supply continuity, and application-specific formulation agility.
| Leading Market Players |
|---|
| Inteplast Group |
| Primex Plastics Corporation |
| Corplex |
| Polyreflex Hi-Tech Co., Ltd |
| Corex Plastics (Australia) Pty. Ltd. |
| Aerolam Group |
| Nilkamal Bubble Guard |
| PPP Solution |
| Tecafine Polymers Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Zhejiang extrusion clusters compresses compounder margins while simultaneously forcing buyers toward specification-driven contracts that lock in supply security. This utilization dynamic creates divergent pricing power between commodity-grade spot sellers and automotive-qualified suppliers with captive resin integration.
Pricing Analysis
Twin-screw compounding technology advances have collapsed the pricing spread between standard and reinforced grades, though laminated sheet with UV-stable coatings still commands substantial premiums. Price differentiation hinges on REACH pre-validation status and mineral loading precision, with German OEM contracts showing lowest price sensitivity due to 18-month qualification lock-in. Cost compression in commodity packaging grades intensifies as Guangdong exporters absorb calcium carbonate electricity cost volatility. Distributors serving construction spot markets exhibit highest price sensitivity, while automotive tier suppliers prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended 90-day payment terms from German automotive OEMs strain working capital for Zhejiang compounders without resin backward integration. Raw material sourcing draws from Saudi PP resin, Chinese calcium carbonate, and Japanese glass fiber, creating multi-currency exposure. Geographic concentration in Guangdong and Zhejiang provinces amplifies vulnerability to regional power rationing. Distribution runs through approved-supplier panels with VMI requirements for automotive, while packaging flows through Yiwu trading companies to Southeast Asian electronics exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-fiber thermoplastic composites threaten displacement above 3,500 MPa flexural modulus requirements, forcing polypropylene filler sheet incumbents to defend their structural interior positioning through formulation innovation and specification capture.
For Market Incumbents: Pre-empt composite substitution by pushing mineral loading optimization toward 3,200 MPa performance ceilings where twin-screw compounding cost advantages persist. Secure captive PP resin supply through backward integration or long-term offtake with Saudi and Korean resin producers. Invest in silane-coupling agent formulation capabilities ahead of ECHA surface treatment restrictions to capture displaced volume from non-compliant Asian competitors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized automotive compounding corridor, where BIS certification gaps displace Chinese suppliers from Maharashtrian Tier 1 clusters. Target laminated sheet for North American retail displays, where California recycled content regulations create compliant formulation demand that incumbent commodity producers underserve. Lead with digital batch traceability and 12-week qualification compression to differentiate against legacy extruders. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-driven procurement is collapsing supplier panels to three approved compounders per region with multi-year contract visibility. Target mid-cap European compounders with pre-validated REACH compliance and automotive qualification track records. Watch for ECHA enforcement acceleration on mineral filler surface treatments as the inflection signal for compliant-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PP Resin | Captive raw material control insulates compounders from Saudi-Korean resin price volatility and currency swings. |
| Silane-Coupling Agent Transition | ECHA-compliant surface treatment investment captures automotive volume displaced by restricted mineral filler competitors. |
| Digital Batch Traceability Deployment | German and Japanese OEM mandates compress qualification cycles and lock in specification-driven contract structures. |
| India PLI Corridor Manufacturing | Domestic compounding investments capture import substitution incentives from BIS-constrained Chinese supplier displacement. |
| UV-Stable Laminated Sheet Capacity | California rigid plastic packaging regulations create compliant formulation premiums for West Coast retail display supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical company filings, and automotive OEM procurement disclosures to validate mineral loading specifications and pricing spreads across formulation tiers. Interviews with twin-screw compounding plant managers, Tier 1 automotive procurement leads, and Guangdong electronics packaging converters informed capacity utilization and qualification cycle estimates. Bottom-up extrusion line counts and top-down resin consumption triangulation anchored volume estimates.
Forecast inputs include automotive lightweighting mandate trajectories in Germany and Japan, China's SAMR enforcement intensity on GB standards, and calcium carbonate processing energy cost curves across the projection horizon. Segmentation modeling spans product type, application vertical, end-user procurement sophistication, and thickness gauge. CAGRs derive from elasticity-adjusted demand curves against capacity expansion announcements.
Stress conditions across Chinese power rationing severity, ECHA surface treatment restriction timelines, and long-fiber thermoplastic composite cost-down curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding qualification cycle compression and specification lock-in persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Global Flexible Polyurethane Foam Market