
 Global HBPA Epoxy Resin Market | 2026-2036
Global HBPA Epoxy Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global HBPA Epoxy Resin Market Foresight
The electrical and electronics end-use vertical is hardening its position as the dominant demand source for HBPA epoxy resins, displacing traditional coatings volumes in several developed markets. Hexion leverages its North American manufacturing footprint to supply high-purity grades for semiconductor encapsulation. Huntsman Corporation sustains R&D intensity in amine-cured systems for advanced composites. Mitsubishi Chemical Corporation anchors supply relationships with Japanese electronics OEMs through specialized liquid resin formulations.
HBPA epoxy resin denotes hydrogenated bisphenol-A based epoxy thermosets characterized by low color, excellent UV stability, and superior weathering resistance compared to standard bisphenol-A analogs, primarily serving protective coatings and electrical insulation applications. Solid resin grades occupy the largest volume share in industrial maintenance coatings where durability commands premium pricing. UV curing technology represents the fastest-expanding segment, displacing thermal systems in furniture and flooring finishes where energy costs and throughput speed determine procurement decisions.
EPA regulations in the United States restrict volatile organic compound emissions from solventborne coatings, pushing formulators toward waterborne HBPA alternatives. ECHA's REACH framework in Europe mandates rigorous substance registration and hazard communication, elevating compliance costs for imported resins. Japan's METI chemical management protocols enforce stringent purity thresholds for electronics-grade materials. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and qualify alternative curing chemistries before compliance deadlines tighten.
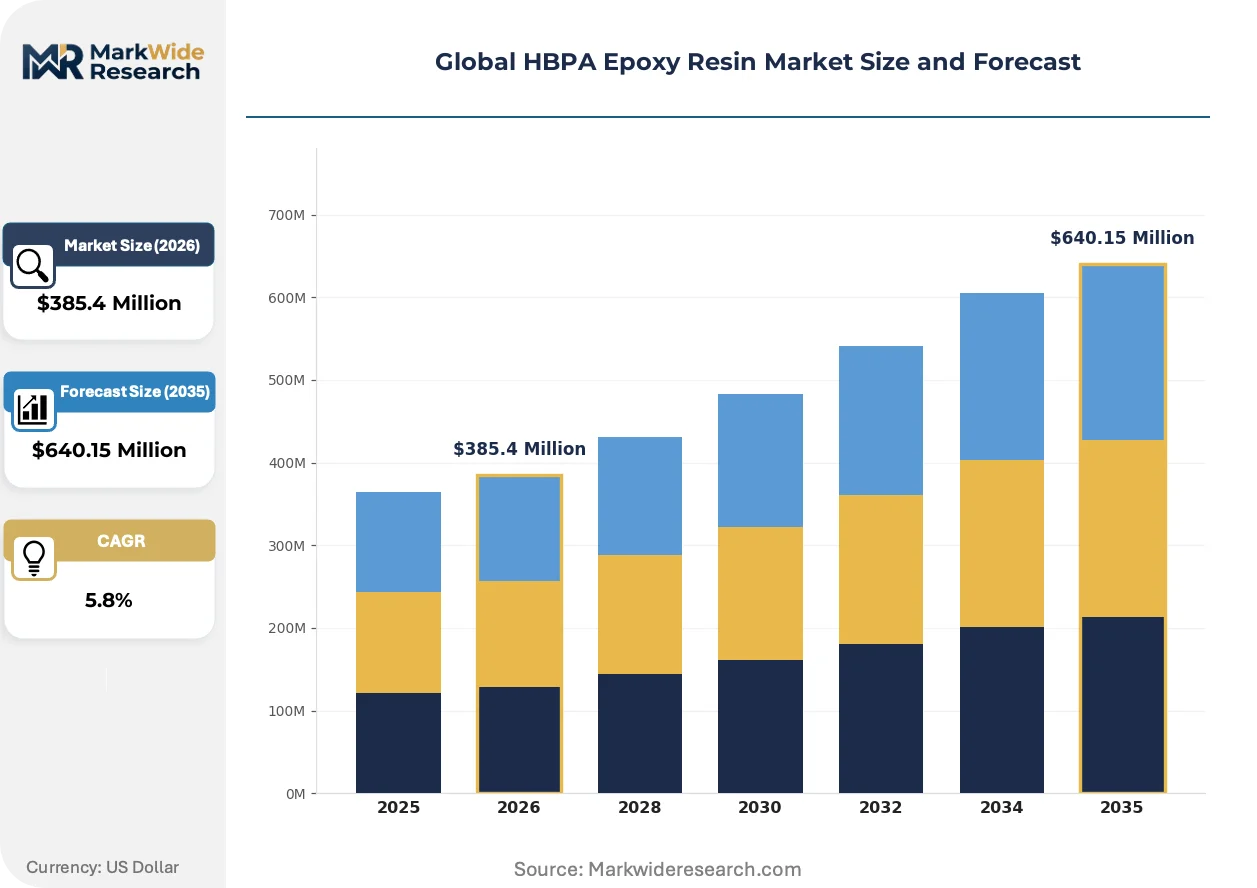
Market Dynamics
Electronics-grade purity requirements are compressing the supplier base as semiconductor packaging demands hydrogenated bisphenol-A resins with sub-50 ppm ionic contamination thresholds. REACH substance evaluation and EPA New Chemicals Program reviews are extending qualification timelines for new HBPA formulations entering Western markets.
Growth Catalysts
- Power Module Encapsulation:Electric vehicle inverters and renewable energy converters require HBPA resins with thermal conductivity above 2.0 W/m·K. Automotive OEMs in Germany and Japan are qualifying hydrogenated formulations for 175°C continuous operation.
- REACH Authorization Pathways:ECHA's streamlined registration procedures for low-volume specialty epoxies are reducing compliance burdens for European formulators developing UV-curable coatings.
- Waterborne Coating Mandates:China's GB standards for architectural coatings are accelerating solvent substitution in industrial maintenance applications across the Yangtze River Delta manufacturing corridor.
Market Restraints
- Cyclohexane Feedstock Volatility:Hydrogenation of bisphenol-A requires high-purity cyclohexane derivatives whose pricing tracks benzene-crude spreads. Asian petrochemical complexes dominate merchant supply.
- Specialty Resin Supply Concentration:Electronics-grade HBPA epoxies rely on a limited number of hydrogenation reactors capable of achieving <100 APHA color specifications. Japanese and German chemical parks host the majority of this installed base.
- Aliphatic Epoxy Substitution:Hydrogenated bisphenol-F analogs and cycloaliphatic epoxies offer comparable UV stability with lower viscosity profiles. Coatings formulators in Southern Europe are evaluating these alternatives for outdoor applications.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component production are creating virgin demand for encapsulation-grade resins. Domestic formulation capabilities remain underdeveloped.
- UV-LED Curing Convergence:Narrow-wavelength LED sources below 395 nm require photoinitiator packages compatible with hydrogenated epoxy backbones. Flooring contractors in the United States are adopting these systems for same-day return-to-service installations.
- EU Green Deal Procurement:Public infrastructure coating specifications are incorporating bio-based content thresholds. HBPA resins derived from renewable hydrogenation feedstocks qualify for preferential bidding in German and Dutch tender processes.
Industry Challenges
- Cleanroom Manufacturing Scale-Up:Electronics-grade production requires ISO Class 7 environments and ionic contamination monitoring at ppb levels. Existing industrial resin plants face multimillion-euro retrofit costs.
- Dual-Use Export Classification:High-purity HBPA formulations with specified thermal properties trigger semiconductor manufacturing equipment controls. Shippers must navigate Bureau of Industry and Security licensing for Chinese destinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HBPA Epoxy Resin Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Resin, Liquid Resin, Solvent-Free Resin, Waterborne Resin Technology: Amine Curing, Anhydride Curing, UV Curing, Thermal Curing, Photoinitiator Based Application: Coatings, Adhesives, Composites, Electronics Encapsulation, Sealants End User Industry: Construction, Electrical & Electronics, Marine, Aerospace, Packaging |
| Companies Covered | Aditya Birla Chemicals, Atul Chemicals, Hexion, Emerald Performance Materials, Anhui Xinyuan Chemical Company, Huntsman Corporation, Kukdo Chemical, New Japan Chemical Company, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HBPA Epoxy Resin Market Shifts & Advancements
Digital curing control systems and predictive formulation software are compressing development cycles for specialty epoxy systems. Material suppliers are repositioning around data-enabled service models.
Nano-silica functionalization is converging with hydrogenated epoxy backbones to produce nanocomposite encapsulants with matched coefficient of thermal expansion to silicon carbide substrates. Power semiconductor manufacturers in Japan and Germany are qualifying these materials for 200°C junction temperature operation. The technology is converging with automated dispensing equipment to enable thinner bond lines and reduced thermal resistance in module assemblies.
EPA New Chemicals Program premanufacture notifications are extending review timelines for modified HBPA structures with altered hydrogenation degrees. Formulators seeking performance differentiation face 180-day evaluation windows for substances lacking existing TSCA inventory listings. Small and mid-sized resin producers are responding by restricting innovation pipelines to incremental composition adjustments rather than novel molecular architectures.
Specification-driven procurement is consolidating buyer power among tier-one electronics assemblers. Original design manufacturers in Taiwan and South Korea are implementing resin qualification databases that pre-approve only two to three HBPA suppliers per regional manufacturing site. This concentration is compressing margin structures for non-preferred vendors and elevating technical service intensity as a competitive discriminator in East Asian supply negotiations.
Global HBPA Epoxy Resin Market Segmentation
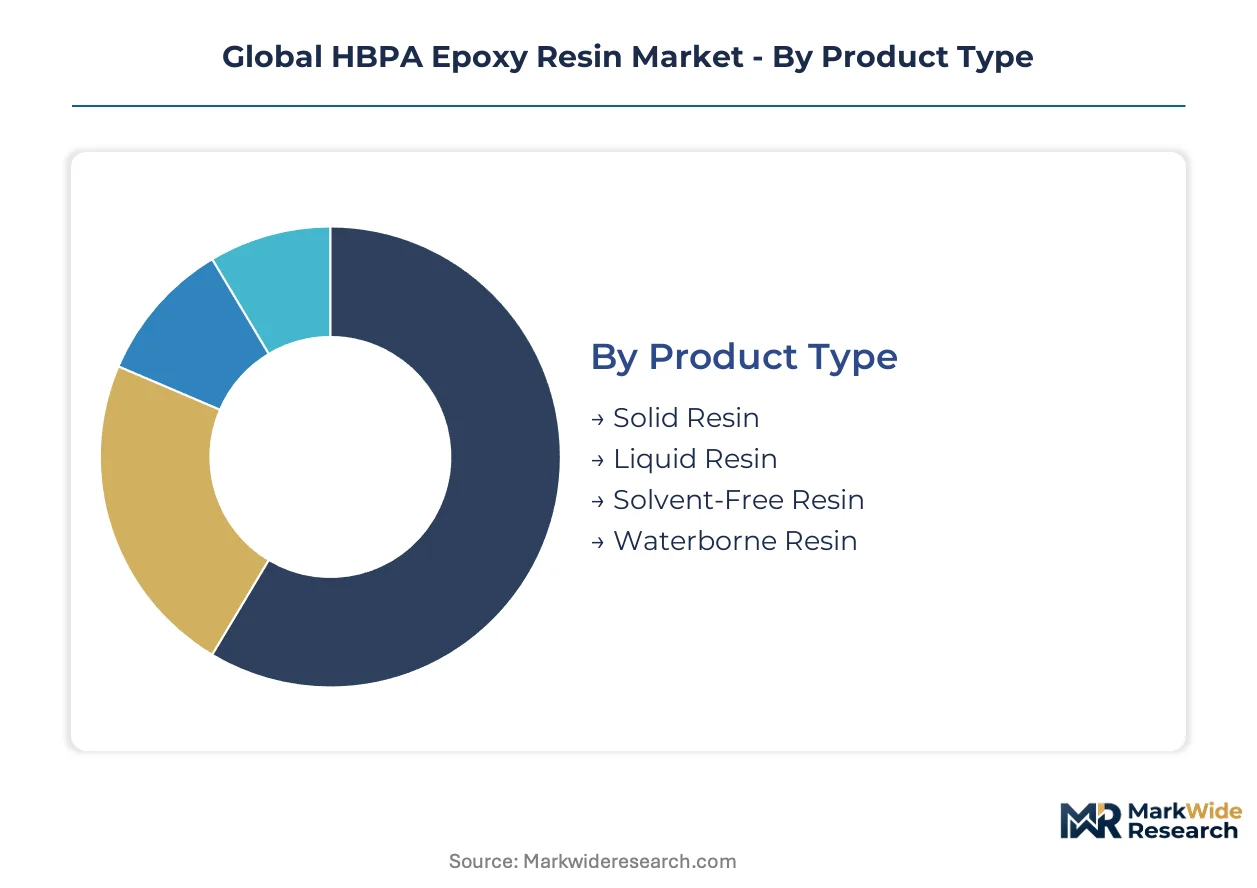
HBPA epoxy resin formulations diverge sharply across product states and curing chemistries, with each configuration commanding distinct qualification protocols and margin structures. Technology selection determines capital intensity, regulatory exposure, and end-use access. Application-driven procurement concentrates volume in coatings while electronics-grade specifications extract premium pricing.
Product Type:
Solid resin grades dominate volume shipments while liquid and waterborne variants capture expanding specification-driven demand.
- Solid Resin:Powder or flake formulations with high molecular weight and elevated glass transition temperatures serve industrial maintenance coatings requiring extended weathering resistance. Demand concentrates in German and US heavy infrastructure projects where durability specifications mandate 15-year protective lifecycles. Cyclohexane feedstock purity directly impacts color stability below 100 APHA.
- Liquid Resin:Low-viscosity hydrogenated bisphenol-A diglycidyl ether enables automated dispensing in semiconductor packaging and precision composite lamination. Japanese electronics OEMs specify sub-50 ppm ionic contamination for power module encapsulation. Viscosity control determines processing window breadth in automated manufacturing lines.
- Solvent-Free Resin:High solids formulations reduce volatile organic compound exposure in confined-space coating applications.
- Waterborne Resin:Dispersed epoxy systems comply with EPA architectural coating mandates and China's GB standards for Yangtze River Delta industrial facilities.
Mature deployment sits with solid resin grades in protective coatings. Newer deployment is concentrated in waterborne systems responding to solvent emission regulations.
Technology:
Curing chemistry selection governs thermal performance, processing speed, and workplace safety profiles across end-use environments.
- Amine Curing:Room-temperature or elevated-temperature reaction with aliphatic or cycloaliphatic amine hardeners produces crosslinked networks with excellent chemical resistance. Huntsman Corporation maintains R&D intensity in advanced amine-cured systems for aerospace composite primary structures. Cure kinetics tuning enables thick-section casting without exotherm cracking.
- UV Curing:Photoinitiator-triggered polymerization delivers instantaneous through-cure for furniture and flooring finishes where energy costs and throughput speed determine procurement decisions. US flooring contractors adopt UV-LED systems below 395 nm for same-day return-to-service installations. Narrow-wavelength sources demand specialized photoinitiator packages compatible with hydrogenated epoxy backbones.
- Anhydride Curing:Elevated-temperature curing with acid anhydrides yields high glass transition temperature networks for electrical insulation.
- Thermal Curing:Heat-activated latent hardener systems enable single-component packaging with extended shelf stability.
- Photoinitiator Based:Cationic or free-radical photoinitiator selection governs cure depth and oxygen inhibition sensitivity in coating applications.
Volume concentration favors amine curing in industrial maintenance. Steepest expansion trajectory belongs to UV curing in decorative and protective finishes.
Application:
Performance requirements and qualification burdens fragment demand across protective, structural, and electronic functions.
- Electronics Encapsulation:High-purity hydrogenated formulations protect power semiconductors, integrated circuits, and LED modules from moisture, ionic contamination, and thermal cycling. German and Japanese automotive OEMs qualify materials for 175°C continuous operation in electric vehicle inverters. Nano-silica functionalization produces nanocomposite encapsulants with coefficient of thermal expansion matched to silicon carbide substrates.
- Coatings:Decorative and protective films exploit UV stability and low color characteristics superior to standard bisphenol-A analogs. China's GB standards for architectural coatings accelerate solvent substitution in Yangtze River Delta manufacturing corridors. EPA restrictions on volatile organic compound emissions push formulators toward waterborne HBPA alternatives.
- Adhesives:Structural bonding applications leverage hydrogenated backbone stability in outdoor exposure conditions.
- Composites:Fiber-reinforced systems serve corrosion-resistant equipment and lightweight structural components.
- Sealants:Elastomer-modified formulations accommodate joint movement in construction and transportation applications.
Specification maturity concentrates in coatings procurement. Technical qualification intensity is expanding fastest in electronics encapsulation.
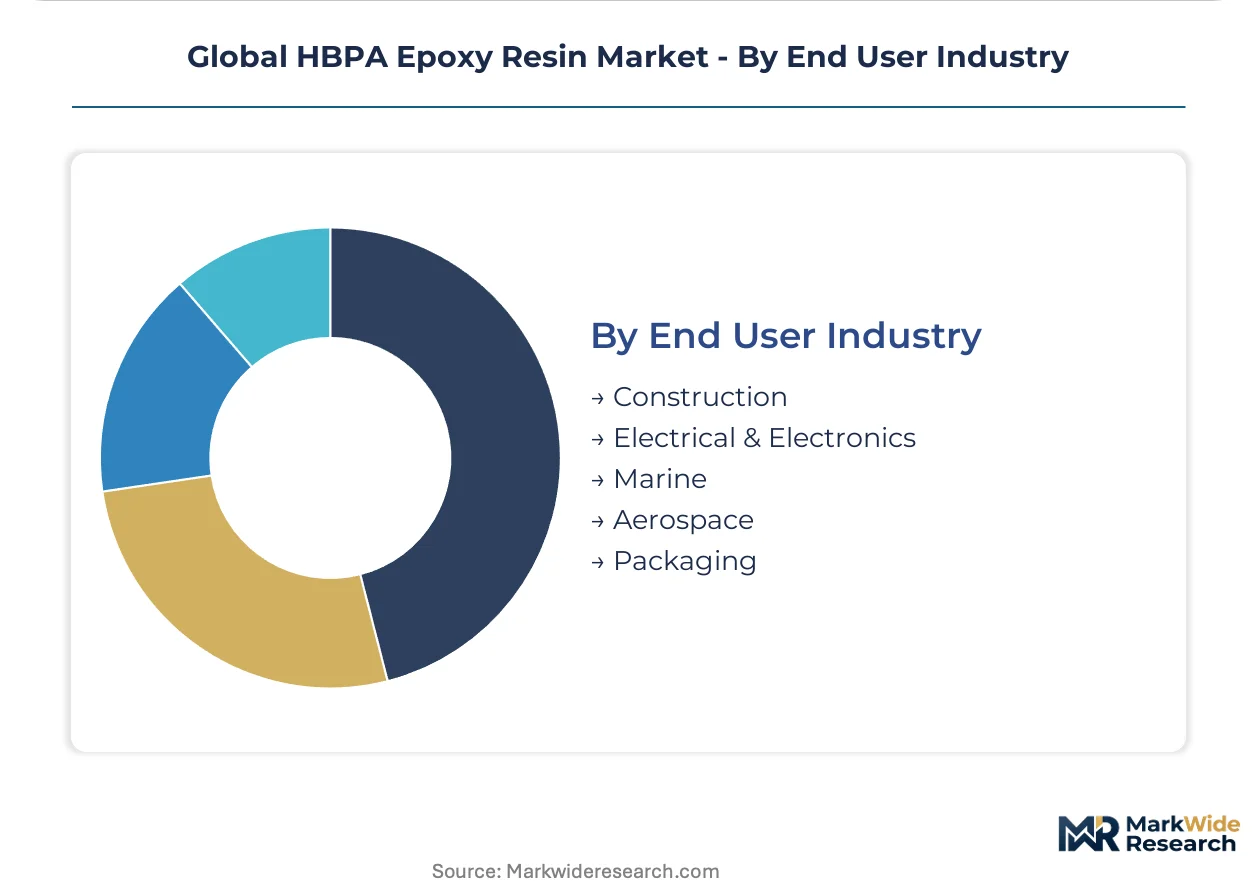
End User Industry:
Industry-specific certification regimes and performance standards govern resin selection and supplier approval processes.
- Electrical & Electronics:Semiconductor packaging, printed circuit board laminates, and power module encapsulation demand sub-50 ppm ionic contamination and ISO Class 7 manufacturing environments. Taiwan and South Korea original design manufacturers implement qualification databases pre-approving only two to three HBPA suppliers per regional manufacturing site. Dual-use export classification triggers Bureau of Industry and Security licensing for Chinese destinations.
- Construction:Protective coatings for infrastructure, flooring systems, and architectural finishes specify weathering resistance and low color drift. EU Green Deal procurement incorporates bio-based content thresholds qualifying renewable hydrogenation feedstocks for preferential bidding in German and Dutch tender processes.
- Marine:Corrosion protection and topcoat systems require salt spray resistance and antifouling compatibility.
- Aerospace:Primary and secondary structural composites demand flame resistance and outgassing control for cabin interior applications.
- Packaging:Interior can coatings and container sealants exploit hydrogenated epoxy stability in food contact applications.
Procurement consolidation is most advanced in electrical and electronics. Sustainability-linked specification growth is expanding fastest in construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate HBPA epoxy resin formulation capacity, drawing feedstock from integrated petrochemical complexes. Germany's Chemical Parks and Japan's coastal industrial corridors host hydrogenation reactors achieving electronics-grade purity specifications. Regulatory divergence between EPA, ECHA, and METI frameworks shapes regional qualification requirements.
China
Power module manufacturers in Jiangsu and Zhejiang provinces drive encapsulation-grade demand for electric vehicle inverters. GB standards for architectural coatings accelerate waterborne HBPA substitution across Yangtze River Delta industrial facilities. Shanghai and Suzhou chemical parks concentrate hydrogenation capacity serving domestic electronics OEMs.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg qualify hydrogenated formulations for 175°C continuous operation in renewable energy converters. EU Green Deal procurement thresholds favor bio-based HBPA resins in public infrastructure coating tenders. Ludwigshafen and Leverkusen chemical parks anchor European supply of sub-100 APHA color specifications.
United States
Semiconductor packaging demand from Arizona and Texas fabrication facilities strengthens high-purity resin consumption. EPA New Chemicals Program reviews extend qualification timelines for modified HBPA structures lacking TSCA inventory listings. Houston petrochemical corridors supply cyclohexane derivatives to regional hydrogenation operations.
Japan
METI chemical management protocols enforce sub-50 ppm ionic contamination thresholds for electronics-grade materials. Power semiconductor manufacturers in Kyushu and Nagoya qualify nano-silica functionalized encapsulants for silicon carbide substrates. Kawasaki and Yokkaichi industrial zones host ISO Class 7 cleanroom resin production.
South Korea
Original design manufacturers in Gyeonggi Province implement qualification databases pre-approving limited HBPA supplier pools per manufacturing site. Dual-use export classification triggers Bureau of Industry and Security licensing for high-purity formulations. Busan-Ulsan petrochemical complexes support downstream electronics resin processing.
Global HBPA Epoxy Resin Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated supply for electronics-grade purity and fragmented competition in industrial coatings. Three archetypes dominate: integrated petrochemical majors with captive hydrogenation assets, regional formulation specialists serving qualified customer lists, and Asian chemical conglomerates leveraging feedstock integration. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with cleanroom manufacturing scale-up requiring multimillion-euro capital deployment.
Among diversified chemical majors, Hexion and Huntsman Corporation exemplify the integrated archetype with North American manufacturing footprints, while Mitsubishi Chemical Corporation anchors Japanese supply relationships through specialized liquid resin positioning. Anhui Xinyuan Chemical Company and Kukdo Chemical represent Asia-Pacific regional specialists with proximity to electronics manufacturing clusters. New Japan Chemical Company occupies a position within the high-purity segment serving semiconductor packaging requirements.
| Leading Market Players |
|---|
| Aditya Birla Chemicals |
| Atul Chemicals |
| Hexion |
| Emerald Performance Materials |
| Anhui Xinyuan Chemical Company |
| Huntsman Corporation |
| Kukdo Chemical |
| New Japan Chemical Company |
| Mitsubishi Chemical Corporation |
| Others |
Supply & Pricing Matrix
Cyclohexane feedstock purity tiers cascade through hydrogenated bisphenol-A resin pricing, with benzene-crude spread volatility compressing margins at the standard-grade level while electronics-grade specifications command substantial premiums for sub-50 ppm ionic contamination thresholds. German and Japanese chemical parks anchor the high-purity segment where ISO Class 7 manufacturing environments and ppb-level contamination monitoring justify pricing stratification across industrial maintenance, semiconductor encapsulation, and automotive power module applications.
Pricing Analysis
Short lead-time premiums for electronics-grade HBPA resins widen the spread between spot inventory discounts and contract-based long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates sub-100 APHA color specifications from industrial maintenance grades and commodity coating resins. Price differentiation hinges on certification grade for REACH compliance and METI purity protocols alongside volume scale for Yangtze River Delta manufacturing corridor buyers. Cost compression in standard-grade solid resins is intensifying because aliphatic epoxy substitution threatens market share in Southern European outdoor coatings. Tier-one electronics assemblers in Taiwan and South Korea exhibit the least price sensitivity due to qualification database concentration, while Chinese industrial maintenance contractors face acute pressure from waterborne coating mandate compliance costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Taiwan and South Korea original design manufacturers with pre-approved supplier pools, while regional distributors serve fragmented European coatings formulators. Geographic supply concentration centers on China, Germany, and Japan where hydrogenation reactor assets achieve electronics-grade purity specifications. Raw material dependencies draw from high-purity cyclohexane derivatives, benzene feedstocks tracking crude spreads, and specialized photoinitiator packages for UV-LED curing systems. Single-source vulnerability concentrates in Japanese and German chemical parks hosting the majority of sub-100 APHA color capacity. Distribution runs through qualified supplier programs for semiconductor packaging and open-market procurement for industrial maintenance coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cyclohexane feedstock supply and downstream captive demand from power module manufacturers is reshaping competitive positioning as incumbents race to secure hydrogenation reactor capacity and cleanroom manufacturing scale-up.
For Market Incumbents: Lock in long-term cyclohexane supply agreements with Asian petrochemical complexes to insulate margin structures from benzene-crude spread volatility. Prioritize ISO Class 7 cleanroom retrofit investments at existing hydrogenation facilities to defend electronics-grade qualification status against emerging Indian and Southeast Asian entrants. Aliphatic epoxy substitution in Southern European coatings and REACH authorization pathway bottlenecks for novel formulations constitute immediate threats requiring defensive patent portfolio expansion. For New Entrants and Emerging Players: Capture the India electronics manufacturing white space created by PLI scheme incentives for semiconductor and component production where domestic formulation capabilities remain underdeveloped. Target waterborne HBPA substitution demand in China's Yangtze River Delta industrial facilities facing GB standards compliance deadlines. Partner with established photoinitiator suppliers for UV-LED curing compatibility certification to accelerate qualification timelines with US flooring contractors. For Investors and Strategic Acquirers: ECHA streamlined registration procedures for low-volume specialty epoxies is the leading indicator that European UV-curable coating formulators will consolidate supplier relationships around qualified hydrogenation assets. Over the projection horizon, vertically integrated specialists with captive cyclohexane supply and cleanroom manufacturing capabilities present the most defensible acquisition profile. Monitor Bureau of Industry and Security licensing activity for high-purity HBPA shipments to Chinese destinations as an inflection signal for dual-use export classification expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclohexane Feedstock | Captive supply of hydrogenation feedstock insulates margin compression from benzene-crude volatility at Asian petrochemical complexes. |
| Cleanroom Manufacturing Scale-Up | ISO Class 7 environments with ppb-level ionic contamination monitoring qualify resins for sub-50 ppm semiconductor packaging specifications. |
| UV-LED Curing Compatibility Certification | Narrow-wavelength photoinitiator packages below 395 nm enable same-day return-to-service flooring installations for US contractors. |
| Long-Term Supply Agreement with Power Module OEMs | 175°C continuous operation qualification with German and Japanese automotive OEMs locks in premium pricing for encapsulation-grade resins. |
| Bio-Based Hydrogenation Feedstock Transition | Renewable feedstock sourcing qualifies HBPA resins for EU Green Deal preferential bidding in German and Dutch infrastructure tenders. |
Research Methodology
Trade databases, SEC 10-K filings, and ECHA REACH registration records formed the secondary backbone, cross-referenced with primary interviews involving hydrogenation plant managers, procurement leads at power module OEMs, technical R&D directors at coatings formulators, and distribution channel partners across the Yangtze River Delta and German Chemical Parks. Bottom-up volume estimates from product-state and curing-chemistry segments were triangulated against top-down demand projections from end-use industries to validate market sizing.
Historical trendline analysis across the analysis window established baseline growth patterns for solid, liquid, and waterborne resin grades, with forward projections incorporating segmentation dimensions spanning purity tier, curing technology, and regional production hub concentration. CAGRs were derived from elasticity modeling against electric vehicle inverter deployment and renewable energy converter installation trajectories. Forecast inputs included semiconductor packaging capacity expansion announcements and EPA New Chemicals Program review timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cyclohexane feedstock volatility, REACH authorization pathway delays, and dual-use export classification expansion for high-purity formulations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Wood Coating Resins Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
PVDF Resin Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Polyether Block Amide Market