
 India Engineering Plastics Market | 2026-2036
India Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
India Engineering Plastics Market Insights
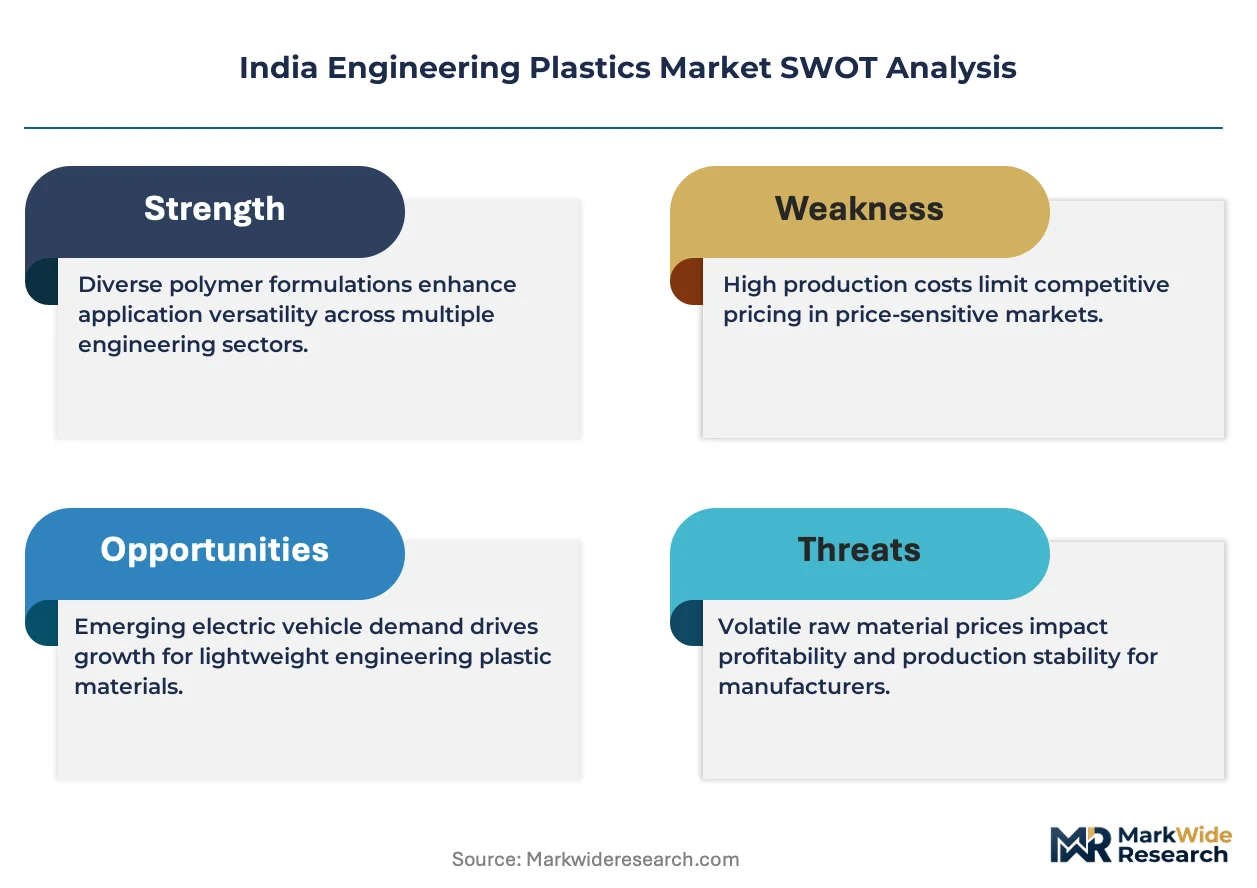
Aftermarket recycling and recompounding of engineering plastics is tilting margin pools away from virgin resin sales toward closed-loop material recovery. Reliance Industries Ltd leverages its Jamnagar petrochemical complex to anchor domestic polypropylene supply chains for automotive tier-1 suppliers. APPL Industries Limited specializes in customized polyamide and polycarbonate compounds for electrical connector applications, competing against imported technical grades. Gujarat Fluorochemicals Limited controls fluoropolymer engineering resin production, occupying a narrow but defensible niche in chemical process equipment.
India engineering plastics comprise high-performance thermoplastic polymers with mechanical strength exceeding 40 MPa tensile modulus, thermal stability above 120°C continuous service temperature, and precision moldability via injection and extrusion processes; these materials replace metal assemblies in load-bearing and thermally stressed industrial components. Polyamide dominates volume consumption in automotive underhood applications where heat resistance and oil compatibility determine specification. Polycarbonate leads optical and electronics housing segments where clarity and flame-retardant ratings drive grade selection. Acrylonitrile Butadiene Styrene competes aggressively in consumer appliance housings, with price-sensitive buyers favoring its balance of impact strength and processability over higher-performing alternatives.
BIS mandates material certification for automotive and electrical applications, while CDSCO regulates medical-grade polymer biocompatibility, and the PLI scheme for chemicals and petrochemicals subsidizes domestic compounding capacity expansion. These frameworks collectively push foreign suppliers toward local manufacturing joint ventures and compel domestic producers to upgrade testing and traceability infrastructure. Stakeholders must monitor evolving BIS test protocols and state-level environmental compliance deadlines to align capacity investments with qualifying supply windows.
Market Dynamics
Automotive OEMs in Gujarat and Tamil Nadu are accelerating polyamide and polycarbonate consumption for lightweighting and thermal management, compressing specification cycles from 36 to 18 months as tier-1 suppliers localize compounding capacity under PLI scheme incentives.
Growth Catalysts
- PLI scheme for auto components:Domestic compounding capacity expansion receives production-linked incentives, reducing import dependency for technical grades used in underhood applications.
- BIS certification mandates:Material traceability requirements for automotive and electrical applications force foreign suppliers into local manufacturing joint ventures.
- Closed-loop material recovery:Aftermarket recycling infrastructure is tilting margin pools from virgin resin sales toward recompounding services.
Market Restraints
- Crude-linked feedstock volatility:Benzene and caprolactam input costs swing with naphtha crack spreads, compressing compounder margins during upstream price spikes.
- Import concentration in specialty grades:Fluoropolymer and high-heat polyamide technical specifications remain captive to European and Japanese resin producers.
- CDSCO biocompatibility timelines:Medical-grade polymer approvals extend 14-18 months, blocking fast-track entry into surgical instrument housings.
Strategic Opportunities
- Eastern industrial corridor penetration:West Bengal and Odisha electronics manufacturing zones lack local engineering plastics compounding, creating first-mover whitespace.
- EV battery thermal management:Polycarbonate and polyamide grades for module housings and coolant manifolds represent uncontracted specification windows.
- Recycling-as-a-service models:Tier-1 suppliers are piloting take-back programs for production scrap, converting waste streams into certified recompounded feedstock.
Industry Challenges
- Polymer characterization skill scarcity:Compounders struggle to hire rheologists and thermal analysts capable of BIS protocol execution.
- Legacy equipment retrofit costs:Twin-screw extrusion lines require 40-60% capex outlays to achieve automotive-grade lot traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Engineering Plastics Market |
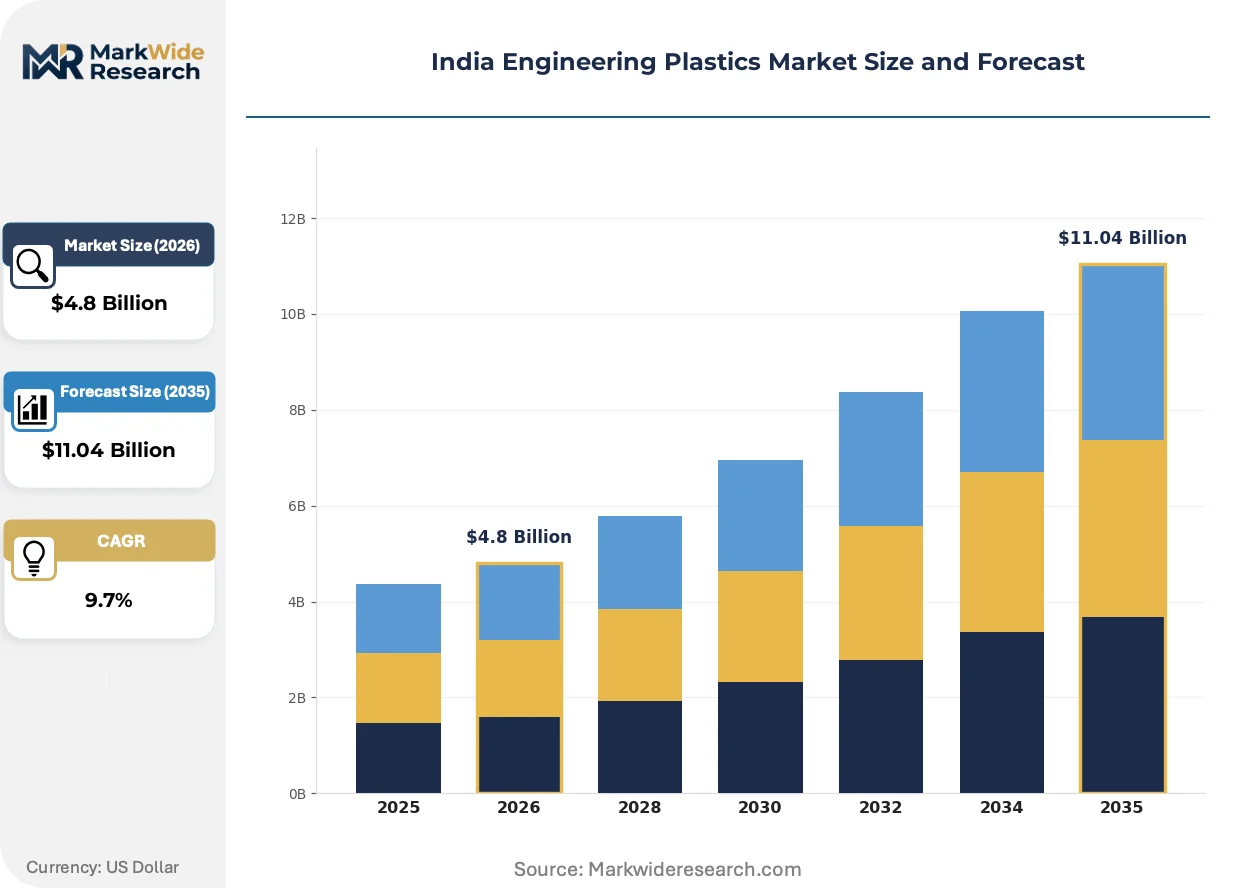
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polyamide, Polypropylene, Acrylonitrile Butadiene Styrene Application: Aerospace, Automotive Components, Consumer Electronics, Medical Devices End User: OEMs, Tier-1 Suppliers, Electronics Manufacturers, Medical Equipment Providers Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | Reliance Industries Ltd, APPL Industries Limited, Gujarat Fluorochemicals Limited, DuPont, LANXESS, Haldia Petrochemicals, LG Polymers India, Ineos Styrolution, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Engineering Plastics Market Trends and Innovations
Material science advances and regulatory compression are collapsing traditional grade hierarchies, forcing compounders to develop multi-property formulations that satisfy overlapping automotive, electrical, and medical specifications simultaneously.
Bio-based polyamide feedstocks derived from castor oil sebacic acid are hybridizing with conventional petroleum-derived chains to deliver 30-50% renewable content without sacrificing thermal stability. Automotive wiring harness producers in Pune and Chennai are qualifying these grades for connector housings. The technology is hybridizing cost structures, forcing virgin resin producers to defend position through carbon footprint certification rather than performance metrics alone.
BIS amended its automotive material testing protocols in 2024, introducing mandatory lot traceability and accelerated aging requirements for underhood polyamide grades. Compounders must now maintain 7-year documentation chains and invest in climatic chamber infrastructure. Tier-1 suppliers in the Mumbai-Pune-Ahmedabad corridor are consolidating vendor lists to those with certified testing capabilities, compressing the qualified supplier base by 30-40%.
Automotive OEM procurement teams are unbundling material specification from molding service contracts, creating direct relationships with compounders that previously sold only through processor intermediaries. This disintermediation concentrates volume with large compounders capable of direct technical service. The shift is most visible at passenger vehicle manufacturers in Tamil Nadu, where annual material reviews now prioritize compounder R&D collaboration over distributor logistics performance.
India Engineering Plastics Market Segmentation
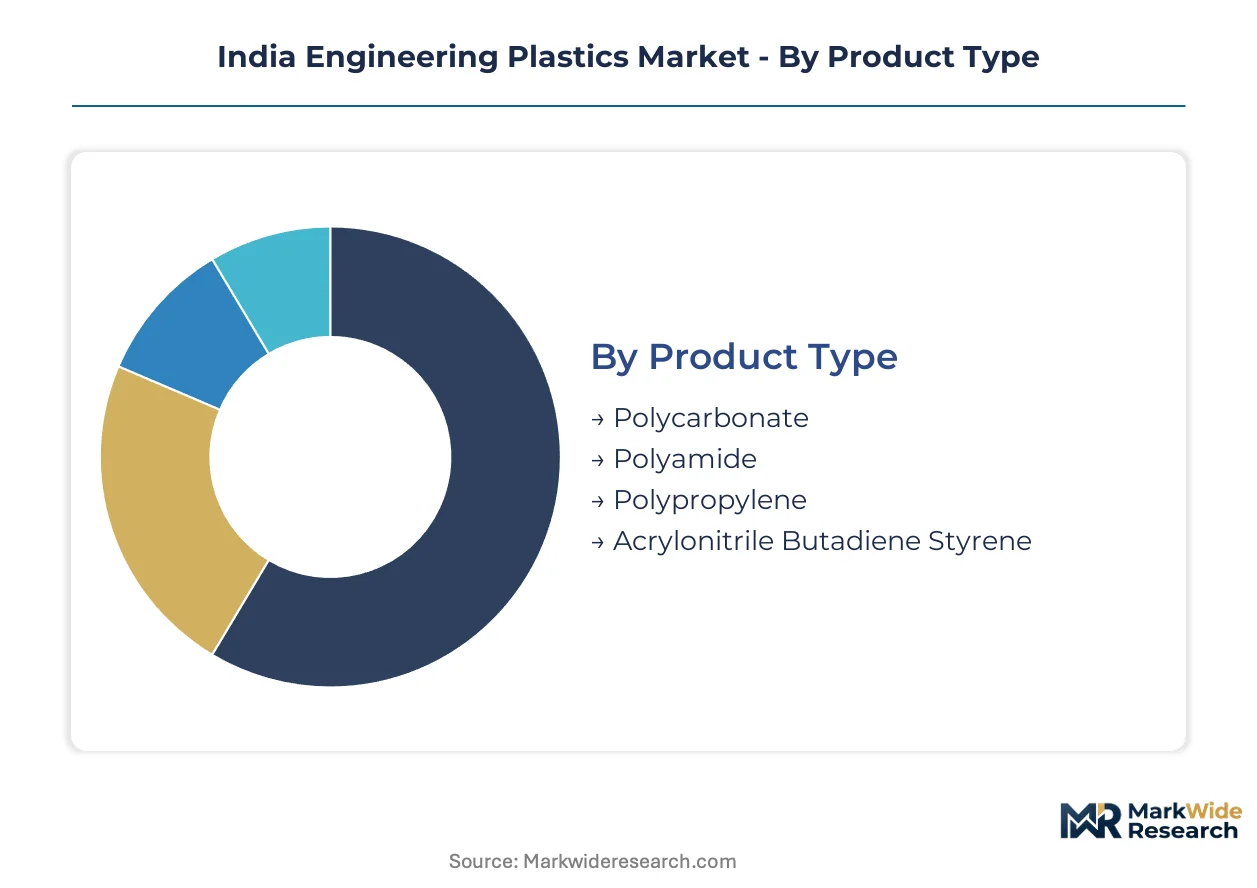
Engineering plastics selection in India hinges on thermal performance thresholds, regulatory certification requirements, and the localization status of compounding infrastructure. Specification decisions cascade from OEM material engineering teams through tier-1 suppliers, creating distinct demand patterns across polymer families and processing technologies.
Product Type:
Use-case spectrum spans load-bearing metal replacement through optical-grade transparency, with thermal stability and chemical resistance acting as primary selection filters.
- Polyamide:Aliphatic polyamides (PA6, PA66) deliver continuous service temperatures above 120°C with excellent oil and grease resistance. Demand concentrates in Gujarat and Tamil Nadu automotive clusters for underhood components—engine covers, intake manifolds, and cable ties—where BIS automotive material protocols mandate lot traceability and accelerated aging documentation.
- Polycarbonate:Amorphous thermoplastic combining optical clarity with high impact strength and inherent flame retardancy. Electronics manufacturers in the Mumbai-Pune corridor specify grades for smartphone housings, LED light diffusers, and EV battery module enclosures where dimensional stability under thermal cycling determines qualification.
- Polypropylene:Semicrystalline polymer with lowest density among engineering grades and excellent chemical resistance. Reliance Industries anchors domestic supply from its Jamnagar complex, serving automotive tier-1 suppliers for interior trim and HVAC ducting where cost-positioning outweighs thermal performance requirements.
- Acrylonitrile Butadiene Styrene:Terpolymer balancing rigidity, processability, and impact strength at price points below technical polyamides and polycarbonates. Consumer appliance manufacturers in Ahmedabad and Chennai favor ABS for refrigerator liners, vacuum cleaner housings, and small appliance enclosures where surface aesthetics and moldability drive specification.
Established volume favors polyamide; emerging adoption favors polycarbonate.
Application:
Application mix reflects India's industrial specialization—automotive manufacturing dominance, electronics assembly growth, and nascent medical device localization.
- Automotive Components:Largest demand sink encompassing powertrain, chassis, and interior systems. PLI scheme incentives for auto components are compressing specification cycles from 36 to 18 months as tier-1 suppliers localize compounding capacity for underhood polyamide and structural polycarbonate grades.
- Consumer Electronics:Smartphone, laptop, and white goods housing applications requiring flame-retardant ratings and precision moldability. Electronics manufacturing zones in Noida and Sri City are expanding polycarbonate consumption for 5G device enclosures and IoT hardware where miniaturization stresses thermal management.
- Medical Devices:Surgical instrument housings, drug delivery components, and diagnostic equipment requiring CDSCO biocompatibility certification. Approval timelines extending 14-18 months currently block fast-track market entry, though domestic compounding investments are targeting this whitespace.
- Aerospace:Interior cabin components and secondary structural elements requiring FAR 25.853 flame and smoke compliance. Limited domestic demand currently served through specialized imports; indigenization efforts at Bengaluru and Hyderabad aero-clusters may shift specification patterns.
Automotive components anchor current volume; medical devices present the steepest expansion trajectory pending regulatory streamlining.
End User:
Customer archetypes span integrated OEM material engineering functions through specialized compounder-distributor relationships, with procurement centralization varying by sector maturity.
- OEMs:Passenger vehicle and commercial vehicle manufacturers with direct material specification authority. Tamil Nadu-based OEMs are unbundling material specification from molding service contracts, creating direct compounder relationships that disintermediate traditional processor intermediaries.
- Tier-1 Suppliers:System integrators serving OEMs with compounded resin and finished component supply. Western corridor suppliers around Pune and Ahmedabad are piloting closed-loop recycling programs, converting production scrap into certified recompounded feedstock.
- Electronics Manufacturers:Contract manufacturers and branded OEMs with global specification templates. Noida and Sri City facilities import technical grades for high-heat connectors while qualifying domestic compounds for standard housings.
- Medical Equipment Providers:Device OEMs and contract manufacturers navigating CDSCO biocompatibility requirements. Limited domestic engineering plastics qualification currently forces reliance on European and US resin suppliers with established medical-grade certifications.
Procurement leverage concentrates with tier-1 suppliers; specification authority is migrating toward OEMs.
Technology:
Processing technology selection ties to part complexity, volume economics, and the precision requirements of regulated applications.
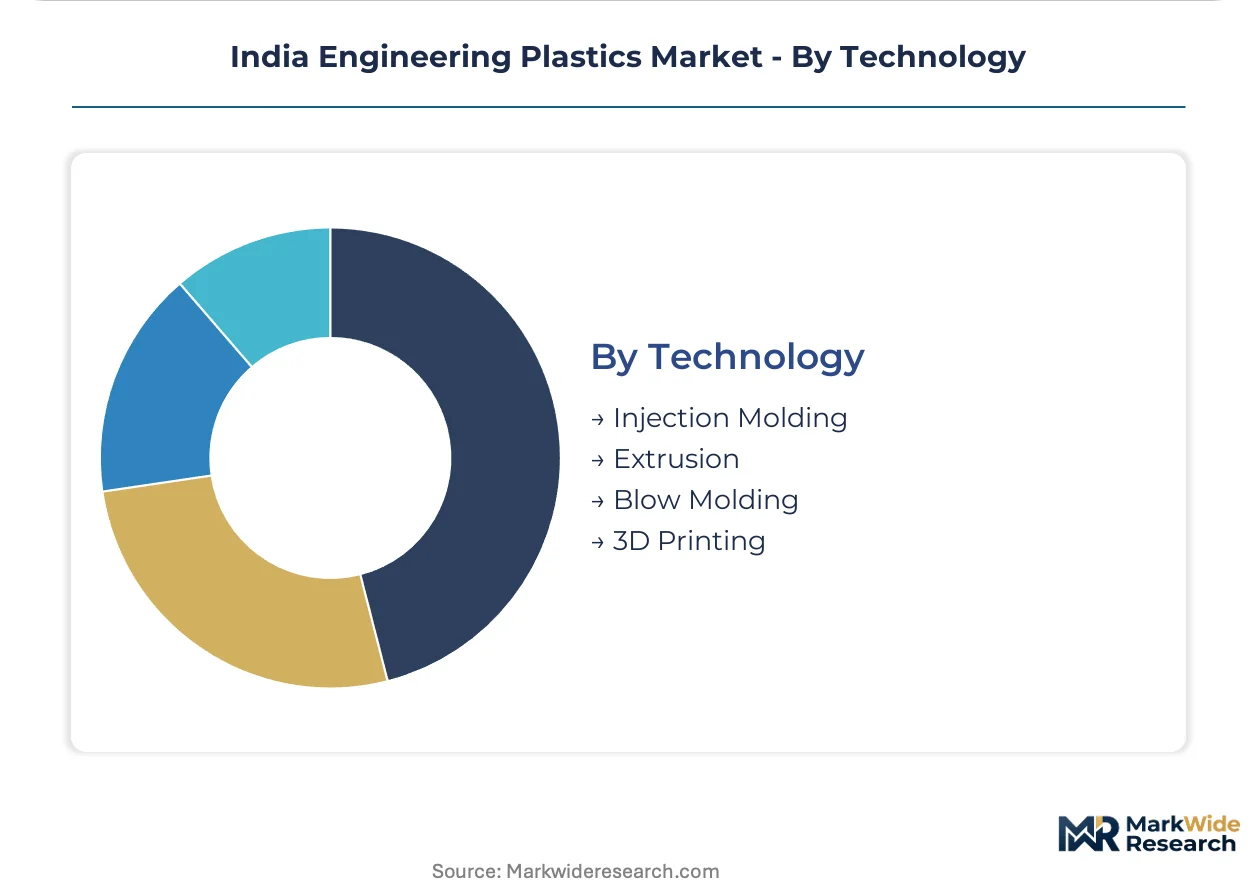
- Injection Molding:Dominant conversion method for complex, high-precision components with tight dimensional tolerances. Automotive underhood parts and electronics housings in the Mumbai-Pune-Ahmedabad corridor rely on multi-cavity tooling with robotic handling and in-line quality verification.
- Extrusion:Continuous profile production for sheets, rods, tubes, and film applications. Process equipment in Gujarat serves construction and electrical insulation markets where long-length consistency outweighs three-dimensional complexity.
- Blow Molding:Hollow part formation for fluid containers, ducts, and tanks. Limited engineering plastics penetration due to melt strength requirements; niche applications in automotive HVAC and industrial chemical handling.
- 3D Printing:Additive manufacturing using filament and powder bed fusion for prototyping and low-volume production. Pune and Bengaluru service bureaus are qualifying engineering-grade filaments for jigs, fixtures, and end-use aerospace brackets where lot sizes below 500 units defy conventional tooling economics.
Injection molding commands current capacity investment; 3D printing is climbing fastest as design-to-part iteration cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states. Gujarat and Tamil Nadu buyers prioritize technical performance and BIS certification compliance over price. West Bengal and Odisha manufacturers remain acutely price-sensitive, delaying engineering plastics adoption until domestic compounding achieves cost parity with commodity alternatives.
Gujarat
Automotive OEMs in the Sanand-Vadodara belt consume polyamide grades for underhood thermal management at specification cycles compressed to 18 months. The state's PLI scheme disbursements for auto components have attracted Reliance Industries and Gujarat Fluorochemicals to expand compounding infrastructure. Jamnagar's petrochemical complex anchors domestic polypropylene supply chains serving tier-1 suppliers clustered around Ahmedabad.
Tamil Nadu
Passenger vehicle manufacturers in Chennai-Sriperumbudur are unbundling material specification from molding contracts, creating direct compounder relationships that disintermediate traditional processors. CDSCO biocompatibility timelines extending 14-18 months currently block medical-grade polymer localization. Hosur electronics manufacturing zones are qualifying polycarbonate grades for 5G device enclosures.
Maharashtra
The Mumbai-Pune-Ahmedabad corridor concentrates India's highest engineering plastics consumption density. Tier-1 suppliers here pilot closed-loop recycling programs, converting production scrap into certified recompounded feedstock. BIS amended automotive material testing protocols in 2024, forcing compounders to maintain 7-year documentation chains and climatic chamber infrastructure.
West Bengal
Electronics manufacturing zones in Noida and Kolkata lack local engineering plastics compounding, creating first-mover whitespace for domestic producers. Price-sensitive appliance manufacturers favor ABS grades over higher-performing alternatives. The eastern industrial corridor remains dependent on western-supplied compounds, inflating logistics costs by 12-15%.
Karnataka
Bengaluru's aerospace and medical device clusters generate limited but high-specification demand for fluoropolymer and high-heat polyamide grades. These technical specifications remain captive to European and Japanese resin imports. The state's polymer characterization skill scarcity constrains local compounder qualification for regulated applications.
India Engineering Plastics Market Competitive Landscape
Capability concentration sits with integrated petrochemical conglomerates possessing captive feedstock and BIS-certified testing infrastructure; scale advantage sits with specialized compounders serving tier-1 automotive suppliers through direct technical service relationships. The vendor base stratifies across three archetypes: upstream-integrated resin producers, independent custom compounders, and foreign technical-grade importers forced into local joint ventures by certification mandates. Dominant competitive moves include backward integration into compounding capacity and strategic partnerships with OEM material engineering teams.
Within the integrated-resin tier, Reliance Industries Ltd anchors domestic polypropylene supply chains from its Jamnagar complex. Among independent compounders, APPL Industries Limited occupies a position serving electrical connector applications, while Gujarat Fluorochemicals Limited exemplifies narrow-niche specialization in fluoropolymer engineering resins. Foreign suppliers including DuPont, LANXESS, and BASF SE represent the technical-grade import archetype, with BIS mandates compelling these players toward local manufacturing joint ventures.
| Leading Market Players |
|---|
| Reliance Industries Ltd |
| APPL Industries Limited |
| Gujarat Fluorochemicals Limited |
| DuPont |
| LANXESS |
| Haldia Petrochemicals |
| LG Polymers India |
| Ineos Styrolution |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Jamnagar's petrochemical complex anchors domestic polypropylene capacity, granting Reliance Industries pricing leverage over automotive tier-1 suppliers who lack alternative feedstock sources within India. Western corridor compounders exploit this concentration to maintain margin buffers against crude-linked naphtha volatility, while eastern manufacturers absorb 12-15% logistics premiums on western-sourced materials.
Pricing Analysis
Aftermarket recompounding services are capturing lifetime value from tier-1 suppliers through take-back programs that convert production scrap into certified feedstock. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification grade and lot traceability depth, with automotive underhood polyamide commanding premiums over appliance-grade ABS. Cost compression in standard polycarbonate grades is intensifying because Reliance's Jamnagar expansion has shortened regional supply chains. Electronics manufacturers in Noida exhibit highest price sensitivity, while Tamil Nadu OEMs prioritize thermal performance over unit economics.
Supply Chain Analysis
Export-control regimes on fluoropolymer and high-heat polyamide production technology limit European and Japanese resin producers from transferring proprietary compounding know-how to Indian joint ventures. Domestic supply draws from Saudi and Singaporean benzene feedstocks, with caprolactam sourcing tethered to Chinese and South Korean producers. Single-source vulnerability concentrates in medical-grade polymer qualifications where CDSCO timelines block rapid supplier switching. Distribution runs through tier-1 compounder-distributor networks that maintain climatic chamber infrastructure for BIS protocol compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tamil Nadu and Gujarat OEM procurement consolidation is shifting specification authority from molding processors to compounders, compressing the qualified supplier base and amplifying buyer leverage over remaining vendors.
For Market Incumbents: Build certification moats by expanding Jamnagar and Ahmedabad climatic chamber capacity to capture BIS-mandated lot traceability requirements that smaller compounders cannot fund. Anchor direct technical service relationships with Chennai-Sriperumbudur OEM material engineering teams to defend against disintermediation. Threat substitution from bio-based polyamide feedstocks demands carbon footprint certification investment as a defensive lever. For New Entrants and Emerging Players: Pursue eastern corridor whitespace in West Bengal and Odisha electronics manufacturing zones where local compounding absence inflates logistics costs for incumbent western suppliers. Target medical device applications pending CDSCO regulatory streamlining, with Hosur and Bengaluru clusters offering specification entry points. Qualify through OEM material engineering direct engagement rather than distributor channel stacking. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because BIS protocol investments and 7-year documentation infrastructure favor scaled compounders over fragmented regional processors. Acquisition targets cluster around independent custom compounders with certified testing capabilities and existing tier-1 automotive relationships. Watch PLI scheme disbursement velocity as the signal indicating whether localization timelines compress or extend.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compounding | Reliance's Jamnagar expansion captures margin pools from polymerization through finished grade supply. |
| BIS Certification Infrastructure Investment | Climatic chamber and 7-year documentation capability filters qualified suppliers for automotive OEM consolidation. |
| Closed-Loop Recycling Program Launch | Tier-1 suppliers in Pune convert scrap streams into certified recompounded feedstock, tilting margins from virgin resin. |
| Direct OEM Material Engineering Partnership | Tamil Nadu passenger vehicle manufacturers unbundle specification from molding contracts, concentrating volume with technical-service compounders. |
| Eastern Corridor Distribution Expansion | West Bengal and Odisha electronics zones lack local compounding, creating first-mover logistics advantage for western suppliers. |
Research Methodology
The analysis maps polyamide, polycarbonate, polypropylene, and ABS sub-sectors, each validated through plant managers at compounding facilities, procurement leads at automotive tier-1 suppliers, technical R&D directors, and distribution channel partners. Primary interview insights triangulate against customs and trade data, BIS certification registries, SEC filings from listed petrochemical conglomerates, and PLI scheme disbursement records. Bottom-up grade-level volume estimates reconcile with top-down petrochemical capacity assessments.
Forecast assumptions hold PLI scheme continuation and BIS protocol stability fixed while varying crude-linked feedstock cost trajectories and EV battery thermal management adoption rates. The projection horizon segments by polymer family, end-use industry, regional production cluster, and certification tier. CAGRs derive from compounding capacity buildout schedules mapped against OEM localization timelines, with polycarbonate EV module housing specifications and bio-based polyamide qualification velocity serving as key demand swing factors.
Sensitivities concentrate around CDSCO regulatory streamlining timelines and naphtha crack spread volatility. Forecasts reflect documented assumptions on BIS enforcement intensity and PLI disbursement cadence. Material shifts in EV platform thermal management material specifications or eastern corridor electronics manufacturing growth would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Rotomolding Compound Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Plastisols Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Global Amino Resin Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market