
 Photocure Resins Market | 2026-2036
Photocure Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Photocure Resins Market Analytics
Capital-intensity divergence between integrated petrochemical producers and specialty resin formulators is bifurcating competitive dynamics in photocure resins. BASF SE leverages backward integration into acrylic acid and photoinitiator precursors to sustain margin compression in standard grades. Arkema anchors its position through fluorinated oligomer technology leadership for high-performance electronics coatings. IGM Resins specializes in narrow-batch photoinitiator blends that compete on cure-speed consistency for wood-finishing applicators.
Photocure resins are radiation-curable oligomer and monomer systems that polymerize upon exposure to ultraviolet or electron-beam energy, typically formulated with photoinitiators absorbing wavelengths between 200 and 400 nanometers to initiate crosslinking for protective and decorative surface applications. Acrylic formulations dominate volume in automotive clearcoats and graphic arts due to their rapid surface cure and optical clarity, while epoxy segments command premium positioning in electronics potting where thermal stability and dielectric performance are critical. Polyurethane photocure resins represent the fastest-growing chemistry in flexible packaging adhesives, driven by demand for low-odor, low-migration laminating systems.
EPA oversight of volatile organic compound emissions under the National Emission Standards for Hazardous Air Pollutants constrains solvent-borne alternatives and channels formulation investment toward 100-percent-solid UV systems in the United States. REACH registration requirements and the EU Green Deal's chemical sustainability targets are restricting certain Type I photoinitiators and accelerating industry migration to LED-optimized, benzophenone-free initiator packages. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D allocation.
Market Dynamics
LED-optimized photoinitiator chemistry is compressing cure-cycle times and forcing incumbent formulators to retire mercury-lamp-compatible product lines faster than depreciation schedules allow.
Growth Catalysts
- REACH monomer migration limits:ECHA's tightening extractable thresholds are accelerating reformulation toward low-migration laminating adhesives for food-contact flexible packaging in the European Union.
- Printed circuit board encapsulation:Electronics manufacturers in Shenzhen's assembly corridor are expanding UV-curable procurement for conformal coatings that withstand thermal cycling.
- Dual carbon goals:China's MEE enforcement of volatile organic compound caps is channeling industrial coating investment toward 100-percent-solid radiation-cure systems in Guangdong province.
Market Restraints
- Acrylic acid supply concentration:Backward-integrated petrochemical producers in Northeast Asia control feedstock pricing, squeezing margin recovery for independent specialty resin formulators.
- Type I photoinitiator regulatory friction:EU Green Deal chemical sustainability targets are restricting benzophenone-based initiators and forcing inventory write-downs for non-LED-optimized grades.
- Thermal cure substitution:Moisture-cure polyurethanes retain cost advantage in low-volume woodworking applications where capital investment in UV lamps cannot be amortized.
Strategic Opportunities
- India's electronics manufacturing clusters:PLI scheme subsidies for semiconductor packaging are creating virgin demand for high-purity epoxy photocure resins in Gujarat and Tamil Nadu.
- UV-LED convergence with inkjet deposition:Drop-on-demand graphic arts printers are integrating 395-nanometer diode arrays that require redesigned photoinitiator absorption spectra.
- California SAFER regulation:The state's framework for sustainable product certification is creating premium positioning for bio-based acrylate monomers in consumer goods coatings.
Industry Challenges
- Photoinitiator synthesis expertise scarcity:Formulation chemists capable of balancing cure speed with low-odor performance in polyurethane adhesives command compensation premiums that inflate R&D overhead.
- Multi-jurisdiction registration timelines:Separate EPA PMN filings and REACH dossier preparation for novel oligomer structures extend time-to-revenue by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photocure Resins Market |
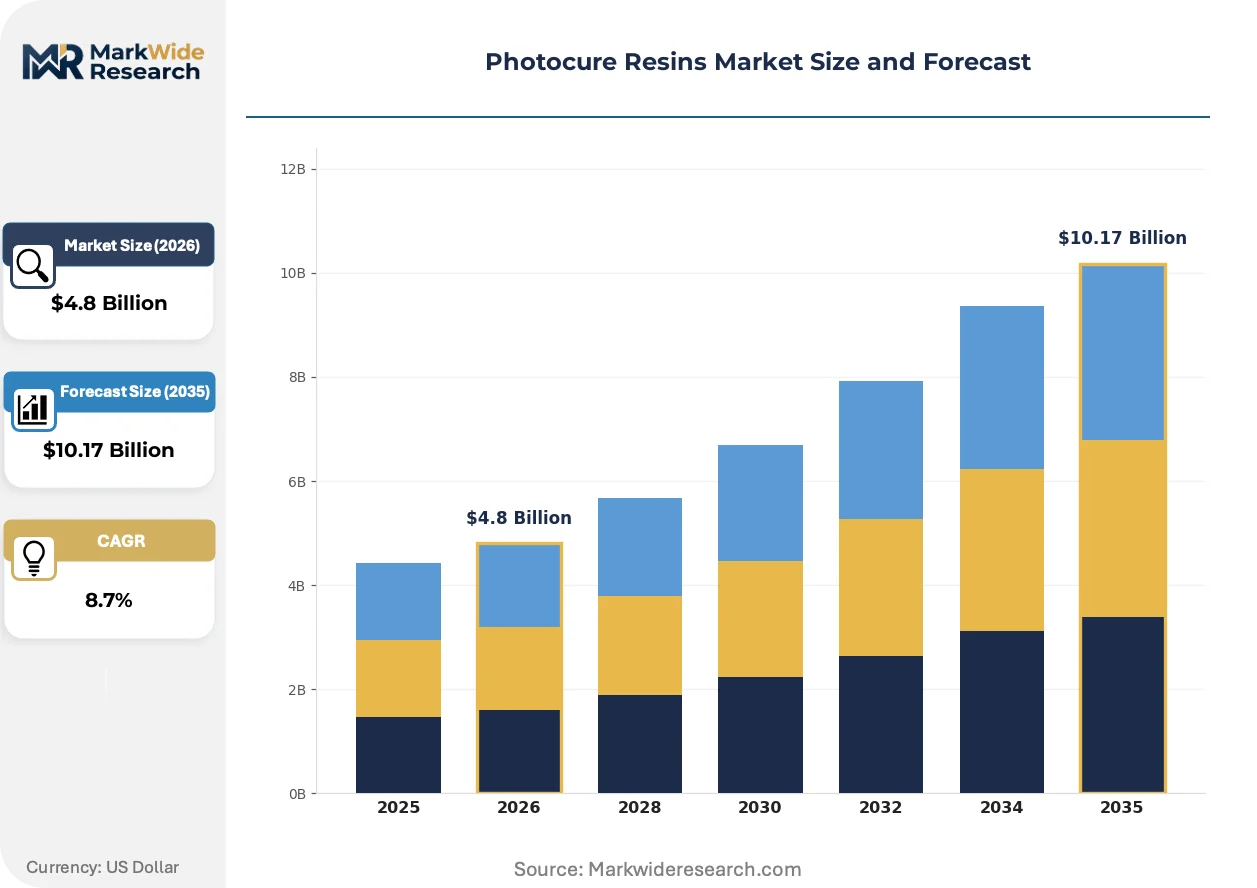
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyester Application: Automotive Coatings, Wood Finishing, Electronics, Adhesives End User: Aerospace, Furniture, Consumer Goods, Construction Feature: UV Stability, High Gloss, Quick Cure, Low Viscosity |
| Companies Covered | BASF SE, Arkema, IGM Resins, Sartomer, Cytec, Eternal Materials, Allnex Netherlands, Covestro AG, Alberdingk Boley GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photocure Resins Market Evolving Landscape
Photocure resin development is pivoting from mercury-arc compatibility toward narrow-wavelength LED optimization, compressing equipment replacement cycles and rewiring supplier-customer technical service relationships.
Cationic epoxy formulations are miniaturizing thermal expansion coefficients for semiconductor underfill applications. Advanced packaging houses in Taiwan and South Korea are qualifying these systems for flip-chip bonding at throughput rates previously achievable only with thermal cure alternatives. This chemistry is miniaturizing the gap between radiation-cure speed and thermoset reliability, collapsing the historical performance trade-off that segmented the electronics potting market.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is constraining solvent-borne coating capacity in the United States. Metal fabrication and wood finishing shops in Ohio and Pennsylvania are facing compliance deadlines that favor 100-percent-solid UV system retrofits. The rule is forcing capital allocation toward LED-curable equipment before end-of-life for existing thermal ovens, compressing supplier sales cycles.
Compounders in China's Greater Bay Area are consolidating procurement authority at the provincial level, bypassing distributor networks that historically fragmented order flows. Coating applicators in Dongguan and Foshan now negotiate directly with resin formulators for annual volume contracts with technical service attachments. This concentration is squeezing regional distributors and transferring margin to logistics-integrated suppliers with localized technical support capabilities.
Photocure Resins Market Segmentation
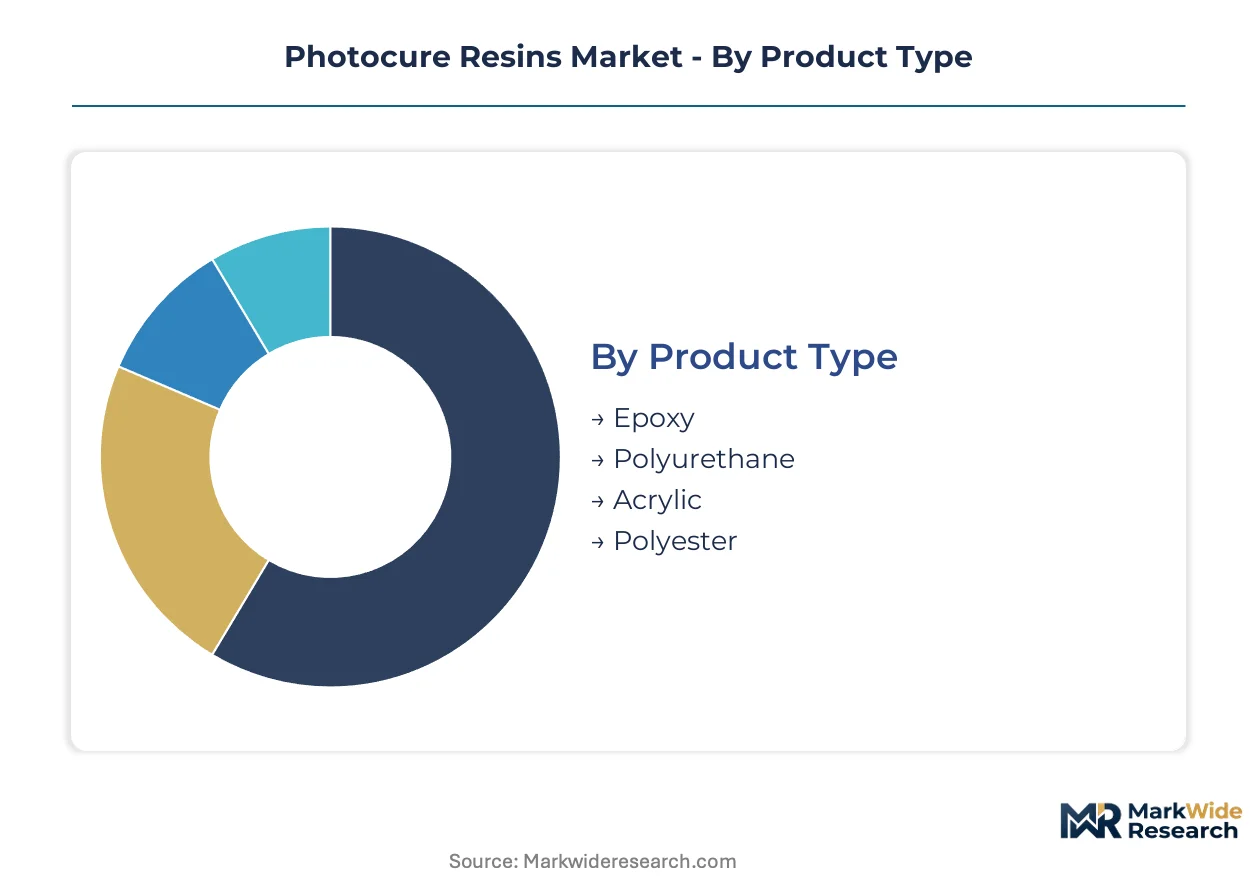
Photocure resin segmentation reveals how chemistry selection, application requirements, and regulatory constraints fragment procurement decisions across industrial buyers. Formulators must align oligomer architectures with specific cure environments and end-use performance thresholds to capture margin.
Product Type:
Margin pools concentrate in specialty oligomers where photoinitiator compatibility and substrate adhesion create formulation lock-in.
- Acrylic:These oligomers and monomers dominate automotive clearcoats and graphic arts due to rapid surface cure and optical clarity. Demand clusters in Guangdong province coating compounders serving Shenzhen's electronics assembly ecosystem, where dual carbon goals enforced by China's MEE accelerate solvent-borne displacement.
- Epoxy:Cationic formulations command premium positioning in electronics potting where thermal stability and dielectric performance are critical. Advanced packaging houses in Taiwan and South Korea qualify these systems for flip-chip bonding at throughputs previously achievable only with thermal cure alternatives.
- Polyurethane:Flexible backbone structures enable low-odor, low-migration laminating adhesives for food-contact packaging responding to REACH monomer migration limits.
- Polyester:Cost-competitive unsaturated systems serve wood-finishing applicators where capital constraints delay UV lamp investments.
The dominant share belongs to Acrylic, while Polyurethane is closing the gap fastest.
Application:
Volume distribution tracks capital equipment deployment cycles and regulatory enforcement intensity across manufacturing verticals.
- Electronics:Conformal coatings and potting compounds for printed circuit boards require cationic epoxy systems with miniaturized thermal expansion coefficients. Procurement concentrates among Shenzhen assembly corridor manufacturers expanding UV-curable encapsulation for thermal cycling resistance.
- Automotive Coatings:Clearcoat and primer layers leverage acrylic photocure resins for scratch resistance and weathering performance. OEM specification tightening in Germany and Japan drives qualification of low-VOC 100-percent-solid systems.
- Wood Finishing:Furniture and cabinetry applications face moisture-cure polyurethane substitution where UV lamp amortization fails at low production volumes.
- Adhesives:Flexible packaging laminating systems demand polyurethane photocure chemistry for migration-compliant food-contact bonding.
Electronics commands the largest application share, with Adhesives expanding most quickly on flexible packaging conversion.
End User:
Customer concentration patterns reflect downstream industry consolidation and specification authority centralization.
- Consumer Goods:Electronics device manufacturers and packaging converters drive specification of LED-optimized photoinitiator systems. California's SAFER regulation creates premium positioning for bio-based acrylate monomers in coatings for personal care and household products.
- Aerospace:MRO operations and OEM finishers require qualified systems meeting flame-resistance and outgassing specifications. India's PLI scheme subsidies for semiconductor packaging are creating virgin demand for high-purity epoxy resins in Gujarat and Tamil Nadu manufacturing clusters.
- Furniture:Mass-production wood finishing in China's Greater Bay Area consolidates procurement authority at provincial level, bypassing historical distributor fragmentation.
- Construction:Flooring and decorative concrete applications face moisture-cure competition in ambient-temperature installation environments.
Consumer Goods holds the dominant end-user position, while Aerospace gains share fastest on electronics packaging qualification.
Feature:
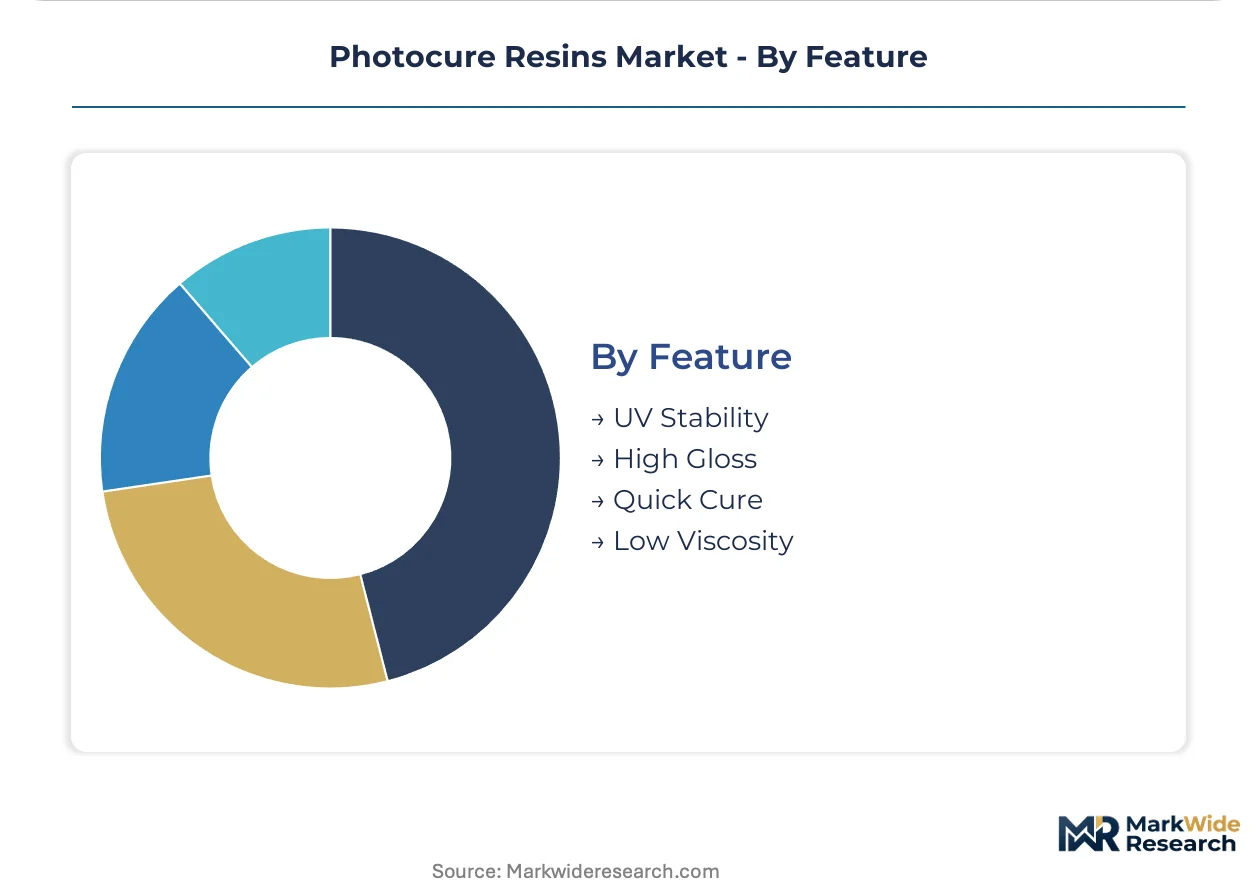
Performance attributes determine photoinitiator package selection and equipment compatibility requirements.
- Quick Cure:Formulations optimized for high-intensity LED arrays at 395 nanometers compress cycle times in high-throughput electronics and automotive lines. UV-LED convergence with inkjet deposition in graphic arts printers demands redesigned photoinitiator absorption spectra.
- UV Stability:Hindered amine light stabilizers and UV absorbers protect against photodegradation in outdoor automotive and construction applications.
- Low Viscosity:Monomer dilution strategies enable spray and curtain coating application methods without solvent addition.
- High Gloss:Surface cure optimization delivers aesthetic performance in consumer-facing furniture and electronics enclosures.
Quick Cure dominates feature demand, with UV Stability climbing fastest on outdoor durability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Northeast Asian petrochemical producers controlling acrylic acid feedstock, while European formulators absorb compliance premiums for REACH-migration-compliant laminating adhesives.
China
Dual carbon goals enforced by MEE accelerate solvent-borne coating displacement across Guangdong province. Shenzhen's electronics assembly corridor expands UV-curable procurement for conformal coatings with thermal cycling resistance. Coating compounders in Dongguan and Foshan consolidate procurement authority at provincial level, bypassing historical distributor networks.
Germany
Automotive OEMs tighten clearcoat specifications for scratch resistance and weathering performance. REACH registration requirements and EU Green Deal chemical sustainability targets restrict Type I photoinitiators. Formulators in North Rhine-Westphalia and Bavaria accelerate reformulation toward LED-optimized, benzophenone-free initiator packages.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-borne coating capacity in metal fabrication and wood finishing. Metal fabrication shops in Ohio and Pennsylvania face compliance deadlines favoring 100-percent-solid UV system retrofits. California's SAFER regulation creates premium positioning for bio-based acrylate monomers in consumer goods coatings.
South Korea
Advanced packaging houses qualify cationic epoxy systems for flip-chip bonding at throughputs matching thermal cure alternatives. MFDS oversight aligns with REACH migration limits for electronics potting compounds. Semiconductor packaging clusters in Gyeonggi-do and Suwon drive specification of miniaturized thermal expansion coefficient formulations.
India
PLI scheme subsidies for semiconductor packaging create virgin demand for high-purity epoxy photocure resins. BIS standards development lags REACH thresholds, creating regulatory arbitrage for early entrants. Manufacturing clusters in Gujarat and Tamil Nadu attract formulators seeking qualification partnerships with electronics packaging houses.
Photocure Resins Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Backward-integrated petrochemical majors control feedstock pricing and sustain margin compression in standard grades. Specialty resin formulators compete on photoinitiator package design and cure-speed consistency for application-specific segments. The dominant competitive moves are portfolio diversification into LED-optimized chemistries and geographic expansion through technical service attachments.
Among European-based integrated producers, BASF SE anchors the petrochemical archetype with captive acrylic acid supply. Arkema exemplifies technology leadership through fluorinated oligomer positioning for high-performance electronics coatings. IGM Resins occupies the specialist tier, competing on narrow-batch photoinitiator blends for cure-speed consistency in wood-finishing applications.
| Leading Market Players |
|---|
| BASF SE |
| Arkema |
| IGM Resins |
| Sartomer |
| Cytec |
| Eternal Materials |
| Allnex Netherlands |
| Covestro AG |
| Alberdingk Boley GmbH |
| Others |
Value Network & Pricing Analysis
REACH registration requirements and EU Green Deal chemical sustainability targets gate both supply qualification and price differentiation simultaneously, forcing non-compliant inventory into distressed channels while rewarding LED-optimized, benzophenone-free formulations with premium positioning.
Pricing Analysis
Configured-to-order pricing for cationic epoxy systems with miniaturized thermal expansion coefficients commands substantial premiums over standard acrylic clearcoats. Price differentiation hinges on photoinitiator package sophistication and REACH migration compliance certification. Cost compression in standard grades intensifies as backward-integrated petrochemical producers leverage captive acrylic acid supply. Wood-finishing applicators with low production volumes exhibit highest price sensitivity, while advanced packaging houses in Taiwan and South Korea demonstrate lowest sensitivity for qualified semiconductor underfill systems.
Supply Chain Analysis
Strategic stockpiling of photoinitiator precursors dominates inventory strategy among European formulators confronting ECHA registration timelines, while East Asian electronics manufacturers prefer just-in-time procurement synchronized to Shenzhen assembly corridor production schedules. Supply concentrates in China, Germany, and South Korea for oligomer synthesis. Raw material dependencies center on acrylic acid, benzophenone derivatives, and fluorinated monomer feedstocks. Single-source vulnerability from Northeast Asian petrochemical producers controlling acrylic acid pricing poses structural risk. Distribution runs through logistics-integrated suppliers with localized technical service capabilities, bypassing traditional distributor networks in Guangdong province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photocure resins market is cycling through a capital equipment replacement wave as mercury-arc systems reach end-of-life, compressing formulator sales cycles and rewarding LED-optimized chemistry portfolios.
For Market Incumbents: Consolidate technical service attachments with coating compounders in Dongguan and Foshan to defend against direct procurement authority shifts. Accelerate photoinitiator synthesis capability acquisition to offset chemist compensation premiums inflating R&D overhead. Deepen backward integration into acrylic acid or secure long-term offtake with Northeast Asian producers to recover margin compression in standard grades. For New Entrants and Emerging Players: Differentiate on LED-optimized photoinitiator package design for 395-nanometer inkjet deposition systems. Target India's PLI-subsidized semiconductor packaging clusters in Gujarat and Tamil Nadu where BIS standards lag creates regulatory arbitrage. Pursue qualification partnerships with advanced packaging houses seeking miniaturized thermal expansion coefficient alternatives to thermal cure systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underinvested photocure resin divisions lacking LED-optimization roadmaps. Long-term viability favors specialists with photoinitiator synthesis expertise and regional technical service density. Watch for inflection when EPA enforcement of National Emission Standards for Hazardous Air Pollutants accelerates Ohio and Pennsylvania retrofit demand beyond supplier capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive feedstock supply insulates margin compression from Northeast Asian pricing power. |
| LED-Optimized Photoinitiator Development | 395-nanometer absorption spectra redesign captures inkjet deposition convergence demand. |
| REACH-Compliant Formulation Migration | Low-migration laminating adhesives secure food-contact flexible packaging positioning in EU. |
| Technical Service Localization | Provincial-level procurement consolidation in Guangdong rewards logistics-integrated support capabilities. |
| Semiconductor Packaging Qualification | Flip-chip bonding approval at thermal-cure throughputs collapses historical performance trade-offs. |
Research Methodology
Initial hypotheses were tested against primary input from resin formulation chemists, procurement leads at coating compounders, photoinitiator synthesis specialists, and electronics packaging engineers and refined through secondary validation against customs trade data, SEC 10-K filings, ECHA registration dossiers, and ACC industry reports. Bottom-up volume estimates from application-level demand were triangulated with top-down petrochemical feedstock consumption analysis.
Variance decomposition across chemistry type, application vertical, end-user concentration pattern, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling calibrated to capital equipment deployment cycles. Forecast inputs incorporated photoinitiator absorption spectra migration rates and enforcement intensity of volatile organic compound caps.
The analysis sits within stated boundaries; outcomes outside sustained LED equipment replacement rates or accelerated REACH timeline enforcement would require recalibration. Forecasts reflect assumptions regarding acrylic acid supply concentration and photoinitiator regulatory restriction trajectories. Revision becomes warranted when dual carbon goal enforcement intensity in Guangdong crosses thresholds triggering non-linear solvent-borne displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market