
 Expanded Polystyrene (EPS) Market | 2026-2036
Expanded Polystyrene (EPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Expanded Polystyrene (EPS) Market Intelligence
Customer concentration among large-scale construction and cold chain logistics firms is hardening procurement terms for EPS suppliers. BASF SE leverages its significant production scale and integrated chemical value chain to serve these major accounts. Synthos specializes in developing specific EPS grades for differentiated applications, creating a niche position. Knauf Industries focuses its strategy on building and insulation solutions across key European markets.
Expanded Polystyrene is a lightweight, rigid cellular plastic foam derived from polystyrene beads containing a blowing agent. Its closed-cell structure provides low thermal conductivity and excellent shock absorption, making it ideal for thermal insulation and protective packaging. The building and construction application, particularly for insulation panels, constitutes the largest market segment by value. Molded shapes for consumer electronics packaging and automotive components represent a high-margin growth area.
Product formulation and market access are shaped by a complex web of regulations. These include the EU's REACH framework for chemical safety, US EPA rules on blowing agents, and China's GB standards for fire retardancy in building materials. These standards directly influence material composition and end-use approval. Navigating the growing pressure for circularity and recycled content while maintaining performance characteristics is the central challenge for producers.
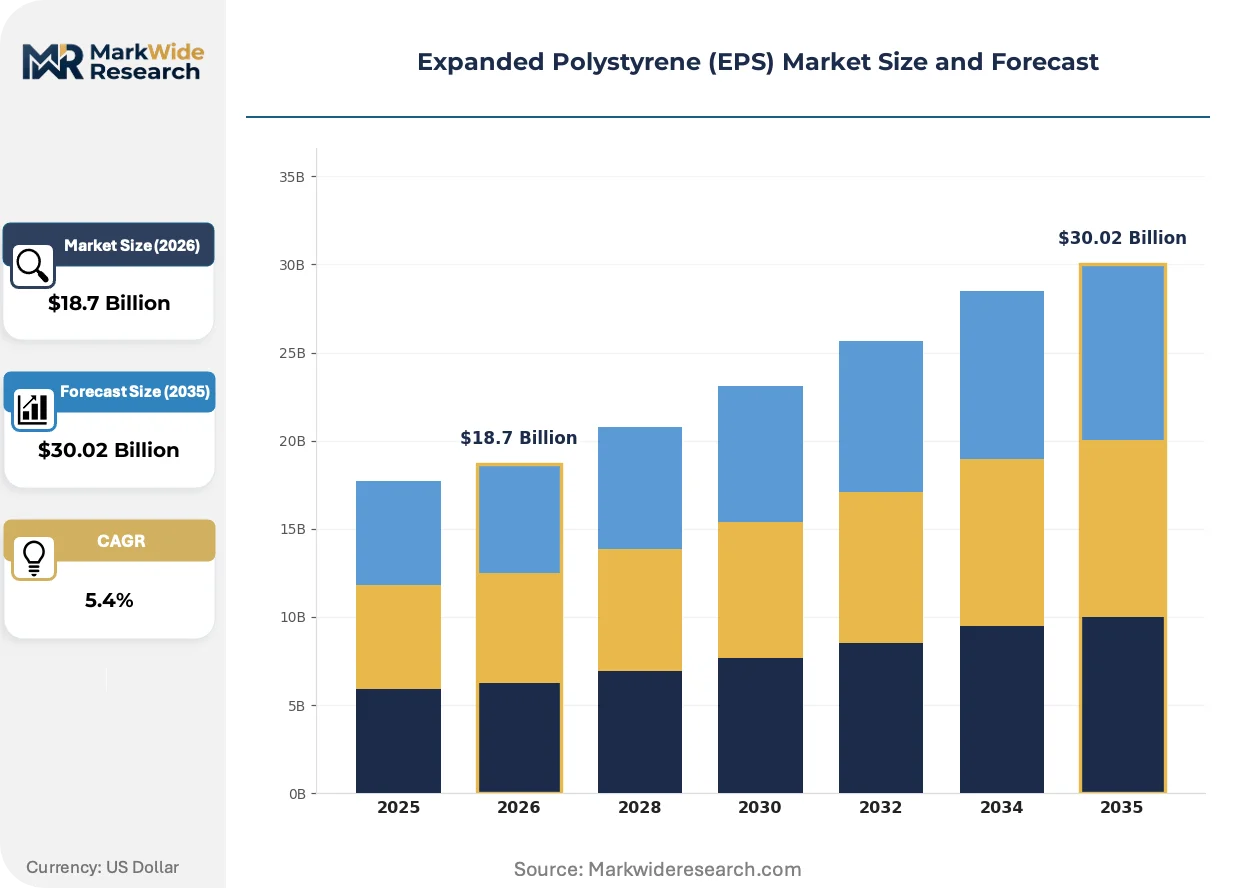
Market Dynamics
The market's structure is defined by regulatory mandates for building energy efficiency. Policy frameworks like the EU Green Deal's renovation wave and China's infrastructure development programs create sustained, large-scale demand for EPS as a primary thermal insulation material.
Growth Catalysts
- Building Energy Codes:Stricter thermal performance requirements in building codes, such as those influenced by the EU Green Deal, compel the use of high-performance insulation materials like EPS.
- Cold Chain Logistics:Expansion of the cold chain for food and pharmaceuticals requires effective, lightweight thermal packaging, where EPS provides a cost-effective and proven solution for temperature control.
- Urbanization in Developing Economies:Rapid infrastructure and housing construction, particularly in China, drives high-volume consumption of EPS for insulation panels and void-fill applications in civil engineering projects.
Market Restraints
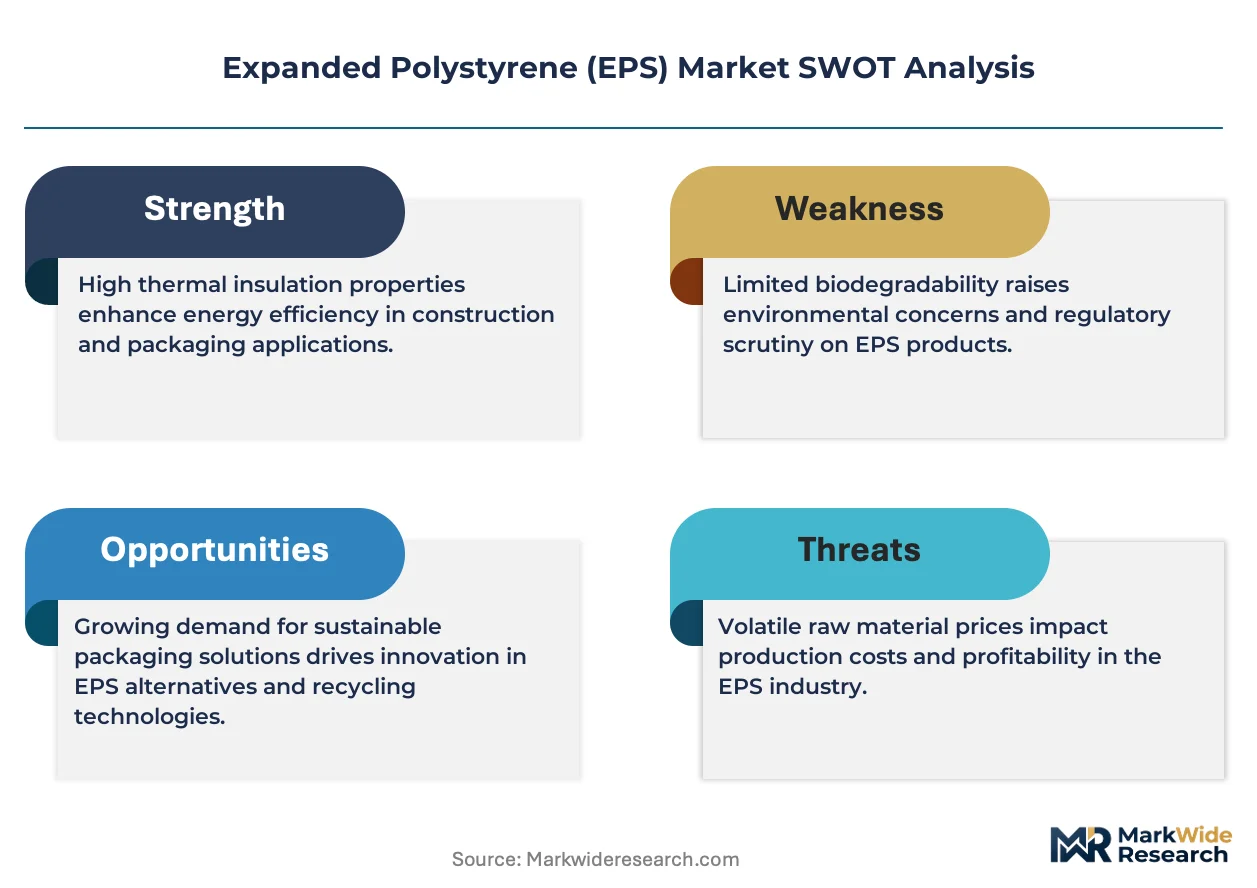
- Styrene Monomer Volatility:The price and supply of styrene monomer, a primary petrochemical feedstock for EPS, are subject to significant volatility tied to crude oil markets, impacting producer margins.
- Competition from Alternative Materials:Mineral wool, polyurethane (PUR), and polyisocyanurate (PIR) foams present viable substitutes in insulation applications, competing on fire retardancy and thermal performance characteristics.
- Blowing Agent Regulations:Phasing out of certain hydrofluorocarbons (HFCs) as blowing agents under frameworks like the US EPA's SNAP program requires costly reformulation and re-certification of EPS products.
Strategic Opportunities
- Recycled Content Integration:Developing EPS grades with high recycled content that meet performance standards for building insulation offers a path to comply with circular economy mandates and appeal to green procurement.
- Geofoam Applications:The use of EPS geofoam blocks as lightweight fill in civil engineering projects, such as highway embankments, represents an underpenetrated, high-volume market.
- Fire-Retardant Formulations:Innovations in non-halogenated, polymeric fire retardants can create premium EPS grades that meet stringent fire safety codes like China's GB standards, unlocking access to high-rise construction.
Industry Challenges
- Circularity Infrastructure:Establishing effective collection and chemical or mechanical recycling systems for post-consumer EPS waste at scale remains a significant logistical and economic hurdle for the industry.
- Public Perception:Overcoming negative public perception of polystyrene as a single-use plastic and a source of marine debris requires significant investment in education and demonstrable recycling success.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expanded Polystyrene (EPS) Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board, Molded Shapes, Insulation Panels, Packaging Blocks Application: Building & Construction, Food Packaging, Consumer Electronics Packaging, Automotive Components End User Industry: Infrastructure Development, Household Appliances, Vehicle Suppliers, Cold Chain Logistics Packaging Type: Sheet, Block, Customized Molded, Cut-to-Size |
| Companies Covered | KANEKA CORPORATION, Synthos, BASF SE, TotalEnergies, NOVA Chemicals, Alpek S.A.B. de C.V., SABIC, Knauf Industries, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expanded Polystyrene (EPS) Market Strategic Shifts & Innovations
Material science is focused on reconciling performance requirements with circular economy principles. This effort creates a new generation of EPS products designed for both higher energy efficiency and improved end-of-life management, driven by regulatory pressure.
Graphite-infused EPS, or grey EPS, integrates graphite particles to reflect and radiate thermal energy, enhancing insulation performance. Building contractors and architects are specifying these grades for projects requiring superior R-values without increasing wall thickness. This technology is absorbing the market share of standard white EPS in high-performance and net-zero energy building applications.
European Union regulations under REACH and the Circular Economy Action Plan are tightening restrictions on certain chemical additives and mandating recycled content. This forces EPS producers to invest in alternative flame retardants and develop supply chains for post-consumer feedstock. The packaging sector is most immediately affected, with producers reformulating products to maintain compliance and market access.
Large-scale construction firms increasingly specify EPS products based on Environmental Product Declarations (EPDs) and life-cycle assessments. This shift moves purchasing decisions away from simple cost-per-unit metrics toward total performance and sustainability evaluation. The trend is most prominent in North American and European commercial projects seeking green building certifications.
Expanded Polystyrene (EPS) Market Segmentation
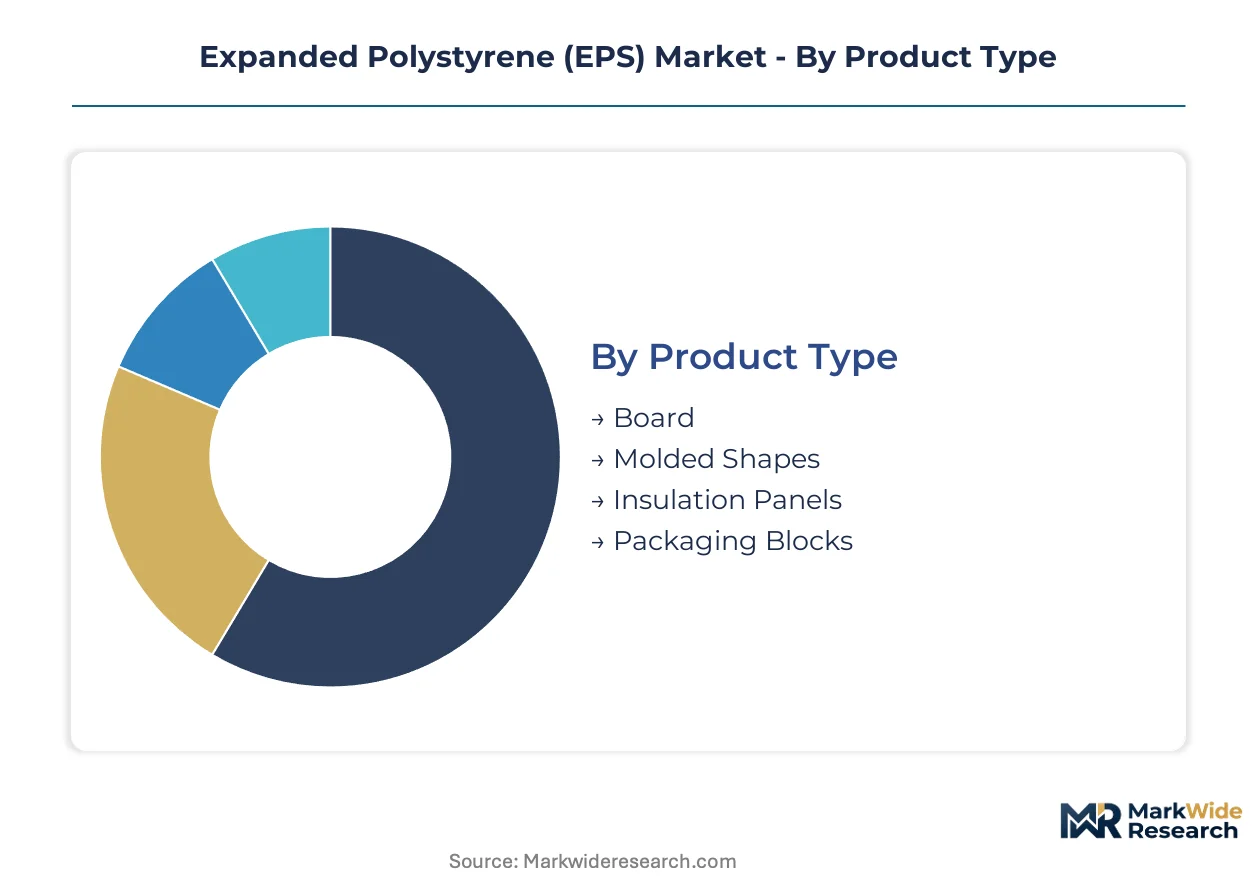
The Expanded Polystyrene (EPS) market's structure reflects diverse product forms and varied end-use requirements. Understanding these segments is crucial for producers to tailor product formulations, optimize distribution channels, and navigate specific regulatory landscapes. Strategic planning benefits from a clear delineation of demand drivers within each category.
Product Type:
The integration depth of EPS products varies significantly, from standalone insulation panels to complex molded components embedded in larger systems.
- Insulation Panels:These are rigid sheets of EPS, often graphite-infused, utilized primarily for thermal insulation in walls, roofs, and floors. Demand concentrates in European and Chinese building and construction sectors due to stringent energy efficiency codes like those influenced by the EU Green Deal.
- Molded Shapes:Custom-formed EPS components offer precise protection and structural support for sensitive goods. These shapes see high demand in consumer electronics packaging and automotive components, driven by the need for lightweight impact absorption and thermal stability.
- Board:Standard EPS boards serve as general-purpose insulation and void-fill materials in less demanding applications.
- Packaging Blocks:Large, rectangular EPS blocks are used for protective packaging, dunnage, and as lightweight fill in civil engineering projects.
Insulation Panels leads volumes today; Molded Shapes is gaining share fastest.
Application:
The application focus for EPS ranges from large-scale structural uses to highly specialized protective functions, each with distinct performance criteria.
- Building & Construction:This segment encompasses thermal insulation, void-fill, and geofoam applications within residential, commercial, and infrastructure projects. Widespread urbanization in China and stricter building energy codes in Europe drive significant consumption of EPS for these uses.
- Consumer Electronics Packaging:EPS provides lightweight, shock-absorbing protection for sensitive electronic devices during transit and storage. This application demands precise molding and high impact resistance, leading to premium product formulations.
- Food Packaging:EPS is used for insulated containers, trays, and cups, maintaining temperature and protecting perishable goods. Stringent food safety regulations and cold chain expansion in developing economies shape product requirements.
- Automotive Components:EPS finds use in vehicle interiors for energy absorption, sound dampening, and lightweight structural elements. The automotive industry's push for vehicle weight reduction and improved safety features drives innovation in this segment.
Building & Construction represents the largest application volume, while Consumer Electronics Packaging shows the steepest expansion trajectory.
End User Industry:
Customer types for EPS span critical sectors, each with unique procurement patterns and regulatory compliance needs for their material inputs.
- Infrastructure Development:This industry utilizes EPS for civil engineering projects, including road embankments, bridge abutments, and lightweight fill in unstable ground. Large-scale government-backed projects, particularly in China, drive substantial demand for EPS geofoam.
- Cold Chain Logistics:EPS is critical for maintaining temperature control during the transport and storage of temperature-sensitive goods like pharmaceuticals and fresh produce. The expansion of global supply chains for these products necessitates reliable thermal packaging solutions.
- Household Appliances:EPS provides insulation and protective packaging for refrigerators, washing machines, and other consumer electronics. Manufacturers seek cost-effective and efficient insulation materials to meet energy efficiency standards.
- Vehicle Suppliers:Automotive original equipment manufacturers (OEMs) and their suppliers integrate EPS into various vehicle components for safety, weight reduction, and thermal management.
Infrastructure Development commands significant EPS volumes, and Cold Chain Logistics is expanding most quickly.
Packaging Type:
The volume and form factor of EPS packaging are determined by the specific product it protects and the logistical requirements of its distribution.
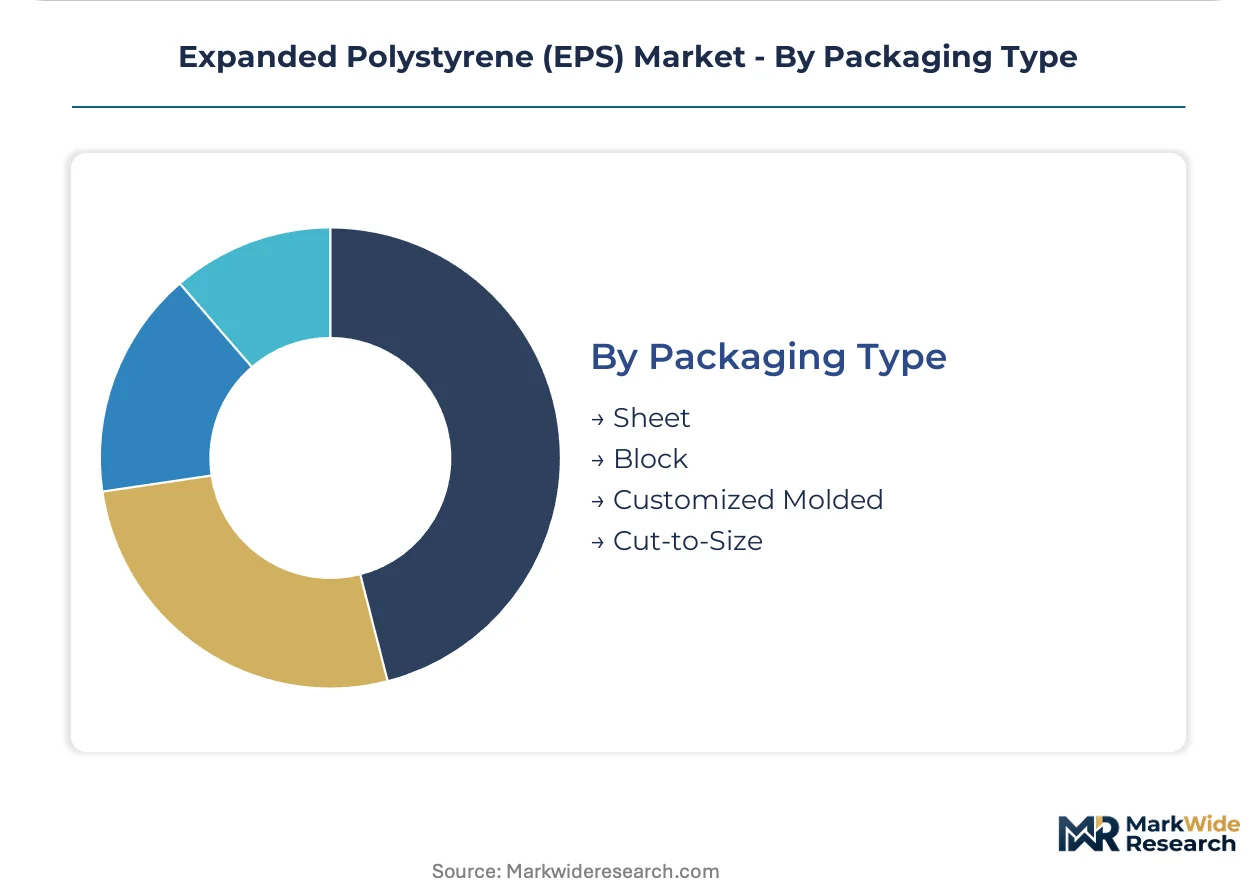
- Customized Molded:These are bespoke EPS forms designed to precisely fit and protect specific products, offering superior cushioning and thermal properties. High-value electronics and automotive parts often utilize customized molded EPS for optimal protection.
- Block:Large, rectangular blocks of EPS are used as raw material for further processing or as general void-fill and dunnage. This form is common in construction and large-scale industrial packaging.
- Sheet:Thin sheets of EPS are employed for interleaving, cushioning, and basic insulation applications. These are often used for packaging delicate items or as a component in multi-layer insulation systems.
- Cut-to-Size:EPS cut-to-size pieces are tailored for specific packaging needs, providing flexibility for diverse product dimensions without requiring custom molds.
Customized Molded packaging leads in value, while Block packaging is climbing the fastest in volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China's infrastructure development fuels high-volume EPS consumption, the United States market prioritizes advanced insulation solutions. This regional divergence shapes product demand and regulatory compliance for EPS manufacturers. Each region presents unique opportunities and challenges for market penetration and growth.
China
Rapid urbanization and extensive infrastructure projects drive significant demand for EPS in China. The country's GB standards for fire retardancy in building materials directly influence product formulation. Major construction hubs like the Yangtze River Delta and Pearl River Delta consume vast quantities of EPS for insulation panels and geofoam applications.
United States
Stricter building energy codes and a focus on green building certifications propel the market for high-performance EPS insulation in the United States. The US EPA's SNAP program influences the types of blowing agents used in EPS production. Residential and commercial construction in states like California and Texas increasingly specify advanced EPS grades.
Germany
Germany's stringent energy efficiency mandates, influenced by the EU Green Deal, create sustained demand for EPS in building insulation and renovation. REACH regulations dictate chemical safety and additive requirements for all EPS products. The construction sector in Bavaria and North Rhine-Westphalia actively integrates graphite-infused EPS for superior thermal performance.
India
Growing cold chain logistics and a burgeoning construction sector are expanding EPS consumption across India. The country's Bureau of Indian Standards (BIS) sets quality benchmarks for EPS materials in various applications. Major metropolitan areas like Mumbai and Delhi require EPS for both protective packaging and building insulation.
Japan
The Japanese market values lightweight construction materials and efficient thermal insulation, driving demand for EPS in residential and commercial buildings. JIS standards govern the quality and performance of EPS products for both construction and packaging applications. Tokyo and Osaka's advanced manufacturing sectors utilize EPS for sensitive electronics packaging and automotive components.
Expanded Polystyrene (EPS) Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the Expanded Polystyrene market. This structure creates a tiered competitive environment, where scale players leverage integrated value chains. Strategic archetypes include large chemical producers, specialized material developers, and regional building solutions providers. Capacity expansion and portfolio diversification represent dominant competitive moves.
Within the large chemical producer archetype, BASF SE and TotalEnergies demonstrate extensive production capabilities and integrated supply chains. Synthos, conversely, exemplifies a focused specialist, developing specific EPS grades for differentiated applications. These companies occupy various positions, from commodity suppliers to providers of high-performance engineered materials, influencing market dynamics through their product offerings and geographical reach.
| Leading Market Players |
|---|
| KANEKA CORPORATION |
| Synthos |
| BASF SE |
| TotalEnergies |
| NOVA Chemicals |
| Alpek S.A.B. de C.V. |
| SABIC |
| Knauf Industries |
| LG Chem |
| Others |
Cost & Logistics Intelligence
Styrene monomer price volatility cascades through the EPS supply chain, influencing the cost structure and ultimately the pricing tiers for insulation panels and molded shapes. This primary feedstock's fluctuations directly impact producer margins and the final cost for diverse end-user industries.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard EPS grades, particularly for insulation panels. Pricing operates predominantly on contract-based long-term offtake for large-volume customers and transactional models for smaller orders. Price differentiation stems from quality grades, such as graphite-infused EPS, and specific fire retardancy certifications required by China's GB standards. Pricing pressure stems from the volatile cost of styrene monomer and competition from alternative insulation materials like mineral wool. Infrastructure development and cold chain logistics firms, requiring consistent supply, are less price-sensitive than smaller construction material distributors.
Supply Chain Analysis
Single-source vulnerability sits with the petrochemical industry for styrene monomer, a critical feedstock for EPS production. Geographic supply concentration for EPS production is notable in China, Europe, and the United States, where major players like BASF SE and NOVA Chemicals operate. The supply chain draws heavily on styrene monomer and various blowing agents, including those regulated by the US EPA's SNAP program. Commodity price volatility for styrene monomer presents a significant structural risk. Distribution runs through direct sales channels to large-scale construction firms and cold chain logistics providers, supplemented by regional distributors for diverse applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Expanded Polystyrene market is evolving into a late-cycle quality story, with building energy codes in Europe and North America driving demand-shifts toward premium, high-performance insulation specifications.
For Market Incumbents: Acquire specialized recycling infrastructure to secure post-consumer feedstock and meet circularity mandates. Invest in R&D for non-halogenated, polymeric fire retardants to navigate evolving chemical safety regulations like EU REACH. Defend market share against alternative insulation materials by emphasizing EPS's cost-effectiveness and lightweight advantages. Control key distribution channels to maintain strong customer relationships with large construction and logistics firms.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for producers specializing in high-recycled content EPS grades. Target underpenetrated geofoam applications in civil engineering projects, particularly in rapidly urbanizing economies. Focus on developing fire-retardant formulations that meet stringent codes like China's GB standards for high-rise construction. A go-to-market angle emphasizing Environmental Product Declarations (EPDs) will appeal to green building projects.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized material developers and technology providers enabling circularity within the EPS value chain. The long-term viability of EPS is anchored by sustained demand from building insulation and cold chain logistics. Identify acquisition targets with proven capabilities in chemical recycling or advanced formulation science for high-performance, sustainable EPS. The signal to watch is the commercialization of economically viable post-consumer EPS recycling at scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Increases supply to meet rising infrastructure development demand in China and India. |
| Recycled Content Integration | Addresses circular economy mandates and appeals to green procurement in Europe. |
| Non-Halogenated FR Development | Unlocks access to stringent fire safety markets like high-rise construction in China. |
| Geofoam Application Expansion | Diversifies revenue streams into large-volume civil engineering projects. |
| EPD Certification Investment | Aligns product offerings with sustainability criteria of North American commercial projects. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and proprietary databases — were reconciled to construct the Expanded Polystyrene market analysis. This involved engaging with EPS producers, construction firm procurement leads, cold chain logistics managers, and chemical R&D directors. Secondary sources included industry association reports, regulatory body publications from EU REACH and US EPA, company financial filings, and global trade data. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market sizing.
Historical trends were cross-referenced with panel input from industry experts to develop the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and regional regulatory frameworks. Compound annual growth rates were derived from a blend of historical performance and expert consensus on future market drivers. Key forecast inputs included styrene monomer price forecasts and anticipated updates to building energy codes in major geographies.
Revisions become necessary when significant shifts in crude oil prices, new environmental regulations, or breakthroughs in alternative insulation materials materialize. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
Polyamide-Imide (PAI) Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Closed Cell Polyurethane Foam Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Methyl Silicone Resins Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
Polystyrene Market