
 Strontium Chloride Market | 2026-2036
Strontium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Strontium Chloride Market Analysis
Capital-intensity divergence between integrated ore-to-chemical producers and merchant processors is collapsing as strontium ore prices fluctuate and environmental compliance costs rise. Furun Chemical leverages captive access to Qinghai strontium reserves to sustain margin stability through raw material cycles. Sakai Chemical Industry Co., Ltd. anchors its position in high-purity grades for electronics and medical applications, where specification stringency limits competitor entry. BassTech International competes through specialized distribution networks serving North American pyrotechnics formulators with just-in-time delivery capabilities.
Strontium chloride is an inorganic salt with formula SrCl₂, existing as anhydrous white crystalline solid or hexahydrate form with melting point 874°C and high water solubility exceeding 500 g/L at 20°C, produced primarily via hydrochloric acid leaching of celestite ore or carbonate conversion followed by crystallization. The compound functions as a precursor in pyrotechnic red flame formulations, glass melt refining fluxes, and medical tooth desensitizing preparations. Strontium chloride hexahydrate dominates volume flows due to its lower production energy requirement and broader handling safety profile, while anhydrous grades command premium positioning in moisture-sensitive electronics and pharmaceutical synthesis. Medical applications represent the fastest-expanding segment as dental care providers adopt strontium-based sensitivity treatments and research laboratories explore bone regeneration protocols.
EPA regulations govern pyrotechnic discharge residues and manufacturing effluents in the United States, while REACH registration mandates full toxicological dossiers for strontium chloride imports into the European Union. China's MEE enforces strontium mining restoration bonds and wastewater discharge limits that reshape cost structures for domestic producers. Buyers and suppliers must monitor evolving battery-grade purity specifications as strontium salts enter solid-state electrolyte research pipelines.
Market Dynamics
Pyrotechnics manufacturers are consolidating procurement around integrated ore-to-chemical suppliers as REACH compliance in Europe tightens impurity thresholds and forces purification upgrades across the value chain.
Growth Catalysts
- REACH Registration Mandates:ECHA requirements for full toxicological dossiers on strontium chloride imports into the European Union are accelerating purification technology adoption among merchant processors seeking market access.
- Medical Tooth Desensitization:Dental care providers are expanding adoption of strontium-based sensitivity treatments, driving hexahydrate grade demand in pharmaceutical compounding.
- Qinghai Strontium Reserves:Captive access to China's dominant ore deposits enables integrated producers to sustain margin stability through raw material price cycles.
Market Restraints
- Celestite Ore Price Volatility:Fluctuations in strontium ore input costs compress margins for non-integrated merchant processors lacking backward integration into mining assets.
- Single-Geography Supply Concentration:China's dominance in strontium ore mining and downstream chemical processing clusters creates geopolitical and logistics risk for buyers.
- Moisture-Sensitive Electronics Substitution:Anhydrous grade specifications for solid-state electrolyte research face competition from alternative alkaline earth salts in battery-grade applications.
Strategic Opportunities
- Solid-State Electrolyte Research:Battery-grade purity specifications for strontium salts in next-generation energy storage represent an emerging demand vertical beyond traditional pyrotechnics.
- North American Distribution Networks:Specialized just-in-time delivery capabilities for pyrotechnics formulators remain underdeveloped relative to Asian supply chain density.
- EU Green Deal Alignment:Carbon border adjustment mechanisms and sustainable mining certification requirements create first-mover advantages for producers with verified low-carbon ore processing.
Industry Challenges
- High-Purity Crystallization Expertise:Electronics and medical applications require specialized technical talent in impurity control and batch consistency that remains scarce outside established chemical processing clusters.
- Multi-Jurisdiction Compliance Timelines:Simultaneous EPA effluent standards, REACH dossier preparation, and China's MEE wastewater discharge limits create overlapping certification burdens.
- Legacy Pyrotechnics Formulation Integration:Military signaling and display fireworks manufacturers face reformulation complexity when substituting purified grades for traditional material specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strontium Chloride Market |
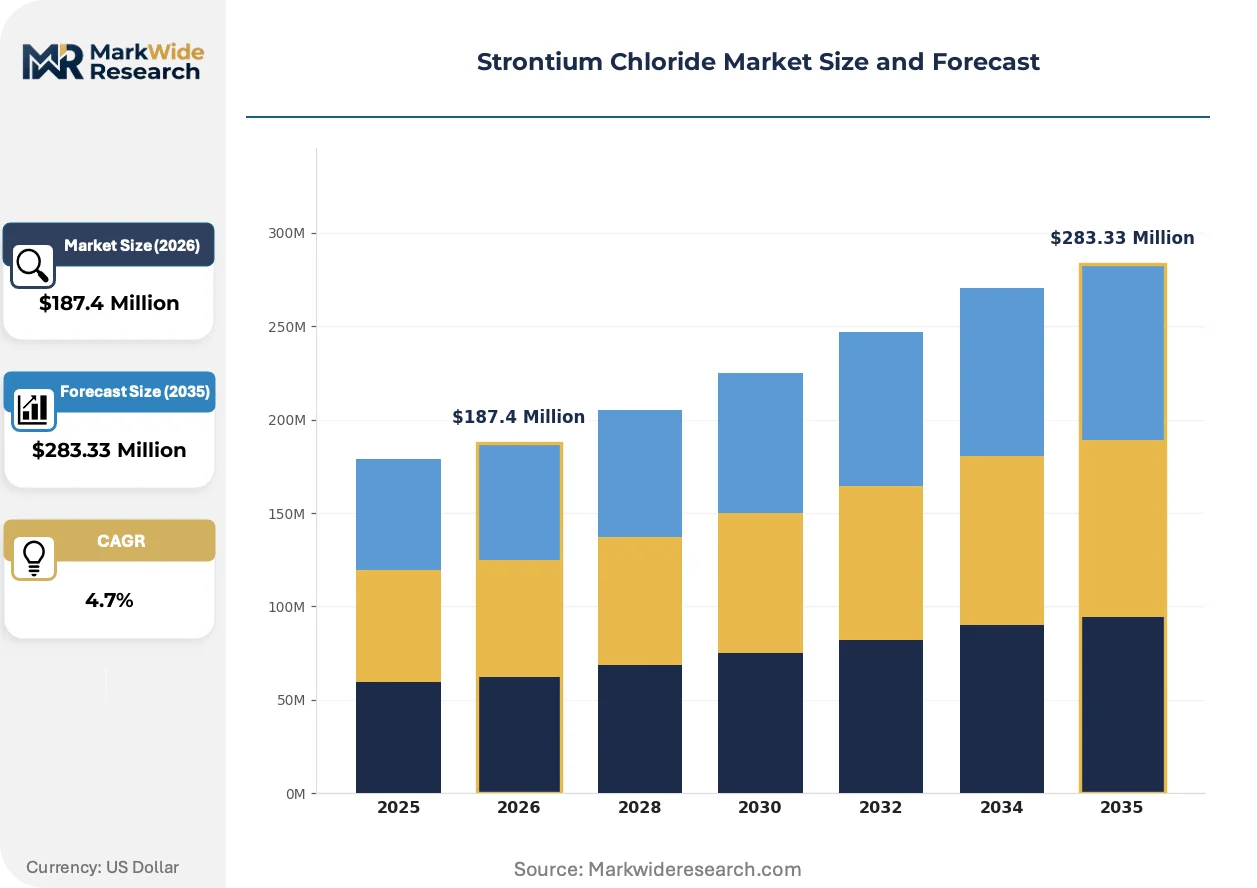
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strontium Chloride Anhydrous, Strontium Chloride Hexahydrate, Strontium Nitrate, Strontium Carbonate Application: Pyrotechnics, Glass Manufacturing, Chemical Reagents, Medical Applications End User: Chemical Manufacturers, Healthcare Providers, Research Laboratories, Educational Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Furun Chemical, Química del Estroncio S.A., Hebei Xinji Chemical, BassTech International, Yuanhe Fine Chemical, Jinyan Strontium Industry, Sakai Chemical Industry Co., Ltd., Prochem, Inc., Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strontium Chloride Market Emerging Trajectories
Carbonate conversion and crystallization process improvements are reshaping production economics while regulatory compliance technologies and buyer procurement centralization are restructuring competitive positioning across the value chain.
Continuous crystallization systems using membrane filtration are replacing batch processing in hexahydrate production. Mid-scale pyrotechnics formulators in Germany and the United States are adopting these systems to reduce energy consumption per ton. This technology is decomposing the traditional advantage of large-scale integrated producers by enabling smaller facilities to achieve comparable purity grades.
China's MEE enforcement of strontium mining restoration bonds and wastewater discharge limits is tightening operational requirements for domestic producers. Facilities in Qinghai and Sichuan provinces must now prefund ecological remediation liabilities, raising effective production costs. The hexahydrate segment faces the steepest compliance burden due to higher water intensity in crystallization.
Consolidated procurement by major pyrotechnics distributors is compressing supplier margins and lengthening payment terms. Buyers in the United States and Europe are centralizing purchases through specialized chemical distributors rather than direct mill relationships. This pattern concentrates volume with integrated producers offering multi-grade portfolios and documented regulatory compliance.
Strontium Chloride Market Segmentation
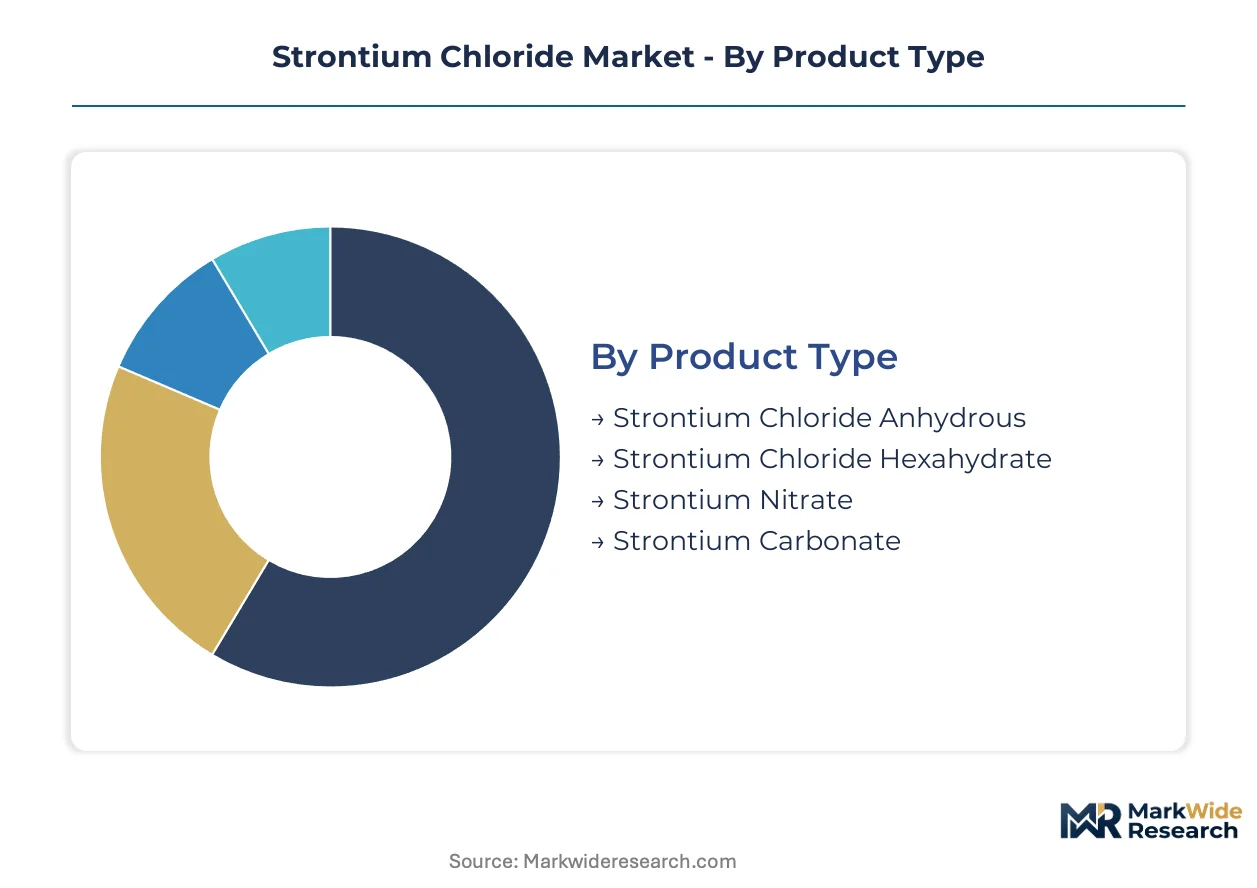
Segmentation in strontium chloride reveals how product form, application purity requirements, and procurement patterns create distinct margin architectures. Buyers prioritize hexahydrate stability for volume pyrotechnics while reserving anhydrous grades for moisture-sensitive electronics and pharmaceutical synthesis.
Product Type:
Margin pools concentrate in anhydrous grades where moisture control commands substantial premiums, while hexahydrate volumes drive cash flow through pyrotechnics scale.
- Strontium Chloride Anhydrous:White crystalline solid with melting point of 874°C and hygroscopic properties requiring sealed storage. Electronics manufacturers in Japan and Germany absorb premium pricing for battery-grade electrolyte research where moisture thresholds below 50 ppm are mandatory.
- Strontium Chloride Hexahydrate:Lower energy crystallization process yields colorless crystals with broader handling safety profile. Pyrotechnics formulators across the United States and China standardize procurement around this grade for red flame formulations where solubility exceeds 500 g/L simplifies aqueous processing.
- Strontium Nitrate:Oxidizer compound serving dual roles in pyrotechnic oxidizing agents and specialty glass manufacturing fluxes.
- Strontium Carbonate:Precursor material for magnetic ferrite production and color television tube phosphor manufacturing.
The dominant share belongs to Strontium Chloride Hexahydrate, while Strontium Chloride Anhydrous is closing the gap fastest.
Application:
Application segmentation tracks how end-use purity specifications fragment procurement into commodity and specialty tiers with divergent supplier qualification requirements.
- Pyrotechnics:Red flame colorant formulations for display fireworks and military signaling applications. REACH dossier requirements in Europe are forcing purification upgrades among German and Spanish formulators seeking import authorization.
- Medical Applications:Dental desensitizing preparations and bone regeneration research protocols. Hexahydrate compounding for sensitivity treatments is expanding through dental care networks in the United States and Switzerland.
- Glass Manufacturing:Melt refining fluxes and specialty optical glass production.
- Chemical Reagents:Laboratory-grade materials for analytical chemistry and synthesis intermediates.
Pyrotechnics commands volume leadership, though Medical Applications is expanding most quickly as dental providers adopt strontium-based sensitivity protocols.
End User:
End user structure reflects how technical specification authority concentrates with chemical manufacturers while healthcare providers delegate compounding to specialized distributors.
- Chemical Manufacturers:Integrated ore-to-chemical producers and merchant processors supplying downstream formulators. Captive access to Qinghai strontium reserves in China insulates integrated producers from ore price volatility.
- Research Laboratories:Solid-state electrolyte research programs at battery institutes in South Korea and Japan are driving anhydrous grade qualification for next-generation energy storage.
- Healthcare Providers:Dental clinics and hospital pharmacies sourcing hexahydrate for desensitizing formulations.
- Educational Institutions:University chemistry departments and teaching laboratories.
Chemical Manufacturers retain the dominant procurement position, while Research Laboratories are gaining share fastest through battery-grade purity specifications.
Distribution Channel:
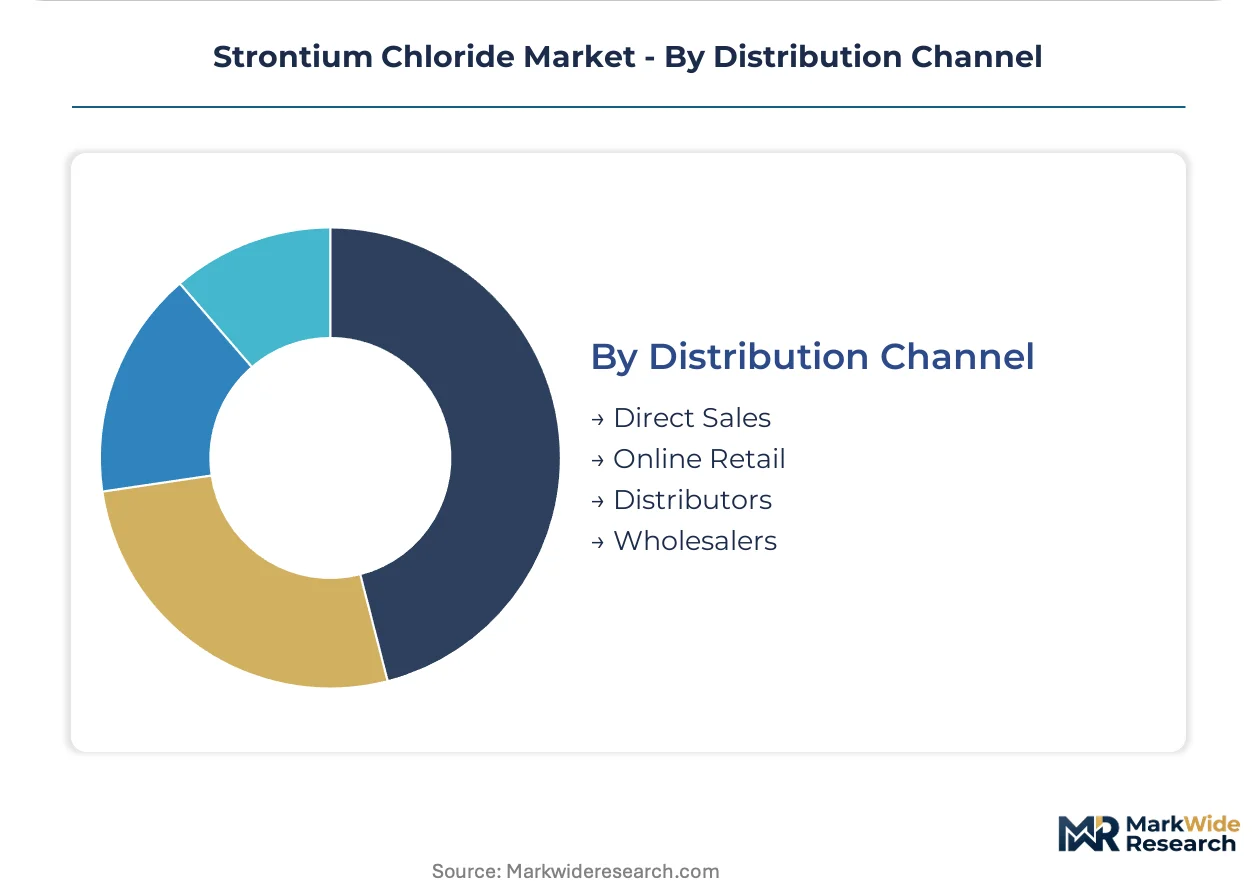
Channel segmentation exposes how regulatory documentation requirements favor direct relationships for REACH-compliant grades while commodity hexahydrate flows through distributor networks.
- Direct Sales:Mill-direct relationships for pyrotechnics manufacturers requiring lot-specific impurity certificates and REACH registration documentation. Major United States fireworks distributors have consolidated procurement through direct contracts with Qinghai-integrated producers.
- Distributors:Specialized chemical distributors serving mid-scale formulators with multi-grade portfolios and just-in-time delivery capabilities across North America.
- Online Retail:Laboratory supply platforms for research-grade quantities and educational institutions.
- Wholesalers:Bulk commodity handlers for standardized hexahydrate grades.
Direct Sales holds the dominant channel position, while Distributors are closing the gap fastest as procurement centralization compresses supplier margins and extends payment terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland absorb substantial premiums for REACH-compliant anhydrous grades, while Chinese pyrotechnics formulators drive volume through price-sensitive hexahydrate procurement.
China
Qinghai province hosts integrated ore-to-chemical producers leveraging captive strontium reserves for margin stability. China's MEE enforces mining restoration bonds and wastewater discharge limits that reshape cost structures for domestic processors. Sichuan facilities face steeper compliance burdens due to higher water intensity in hexahydrate crystallization.
United States
EPA regulations govern pyrotechnic discharge residues and manufacturing effluents across display fireworks and military signaling supply chains. Consolidated procurement by major distributors centralizes volume through direct contracts with Qinghai-integrated producers. BassTech International anchors North American distribution networks with just-in-time delivery capabilities for mid-scale formulators.
Germany
ECHA REACH registration mandates accelerate purification technology adoption among merchant processors seeking EU market access. German pyrotechnics formulators face reformulation complexity when substituting purified grades for traditional material specifications. Industrial clusters in North Rhine-Westphalia concentrate hexahydrate processing for pharmaceutical compounding and dental desensitizing preparations.
Japan
METI standards and battery-grade purity specifications drive anhydrous grade qualification for solid-state electrolyte research programs. Sakai Chemical Industry Co., Ltd. anchors high-purity positioning in electronics and medical applications where specification stringency limits competitor entry. Research laboratories in Osaka and Nagoya prioritize moisture thresholds below 50 ppm for next-generation energy storage development.
Switzerland
Swissmedic regulations and dental care provider networks expand hexahydrate compounding for strontium-based sensitivity treatments. Swiss buyers delegate procurement to specialized chemical distributors rather than direct mill relationships. Zurich and Basel clusters concentrate pharmaceutical synthesis demand for bone regeneration research protocols.
Strontium Chloride Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the strontium chloride value chain. Integrated ore-to-chemical producers with captive Qinghai reserves command cost advantages through raw material cycle insulation, while high-purity specialists capture premium positioning in moisture-sensitive electronics and pharmaceutical synthesis. Three archetypes dominate: reserve-integrated volume players, purity-focused specialty processors, and distribution-anchored regional suppliers. Competitive dynamics center on backward integration into mining assets and purification technology licensing for REACH compliance.
Among Chinese reserve-integrated producers, Furun Chemical exemplifies cost leadership through captive Qinghai strontium access. Hebei Xinji Chemical occupies a parallel position in northern China’s processing corridor. Sakai Chemical Industry Co., Ltd. represents the premium-tier archetype for electronics and medical grades, while BassTech International anchors North American distribution specialization.
| Leading Market Players |
|---|
| Furun Chemical |
| Química del Estroncio S.A. |
| Hebei Xinji Chemical |
| BassTech International |
| Yuanhe Fine Chemical |
| Jinyan Strontium Industry |
| Sakai Chemical Industry Co., Ltd. |
| Prochem, Inc. |
| Solvay SA |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles for REACH-compliant anhydrous grades concentrate pricing power with Qinghai-integrated producers, while hexahydrate spot markets fragment procurement leverage across mid-scale pyrotechnics formulators. This lead-time divergence separates premium-grade margin capture from commodity-grade price erosion.
Pricing Analysis
After-sales service contracts for technical-grade certification support anchor lifetime value in electronics and pharmaceutical tiers. The market runs on a contract-based long-term offtake model for anhydrous grades, with spot purchasing dominating hexahydrate pyrotechnics flows. Price differentiation separates battery-grade purity (sub-50 ppm moisture) from standard industrial grades, with REACH dossier completeness commanding additional premiums. Pricing pressure stems from consolidated procurement by major United States fireworks distributors extending payment terms. Pyrotechnics formulators exhibit highest price sensitivity; solid-state electrolyte researchers absorb premiums without volume elasticity.
Supply Chain Analysis
Strategic stockpile preferences among Japanese battery researchers contrast with just-in-time hexahydrate procurement by North American fireworks distributors. Supply concentrates in China, Germany, and Japan for differentiated grades. Raw material flows draw from Qinghai celestite ore, hydrochloric acid leaching reagents, and crystallization energy inputs. Single-geography ore concentration in Qinghai province creates geopolitical vulnerability for non-integrated buyers. Distribution runs through specialized chemical distributors for mid-scale formulators, with direct mill relationships dominating volume tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as REACH compliance splits demand into certified-premium and commodity-uncertified tiers, creating distinct supplier qualification niches. Medical and battery-grade purity specifications accelerate this bifurcation.
For Market Incumbents: Secure backward integration into Qinghai mining assets or purification technology licensing to defend against carbonate conversion process improvements eroding scale advantages. Invest in continuous crystallization membrane filtration to match energy efficiency gains by mid-scale German processors. Anchor channel control through multi-grade portfolios with documented ECHA dossier completeness. For New Entrants and Emerging Players: Regulatory documentation services for REACH-registered imports represent an under-served layer where incumbents under-serve mid-scale European formulators. Target Swiss and German dental care distributor networks for hexahydrate compounding partnerships. Enter through just-in-time delivery capabilities for North American pyrotechnics manufacturers lacking Asian supply chain density. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because purification expertise scarcity in high-purity crystallization limits competitor entry in electronics and medical tiers. Acquire reserve-integrated volume players with captive Qinghai access or purity-focused specialty processors with METI-qualified anhydrous capacity. Watch solid-state electrolyte research program announcements at Osaka and Nagoya battery institutes as inflection indicators for anhydrous grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Qinghai Mining Assets | Captive celestite ore access insulates margin stability through raw material price cycles for integrated producers. |
| Continuous Crystallization Technology Deployment | Membrane filtration systems reduce energy consumption per ton, enabling mid-scale facilities to match large-producer purity grades. |
| REACH Dossier Completion and Registration | Full toxicological documentation unlocks EU market access for merchant processors seeking German and Spanish formulator contracts. |
| North American Distribution Network Expansion | Just-in-time delivery capabilities capture mid-scale United States pyrotechnics procurement centralizing through specialized distributors. |
| Battery-Grade Purity Qualification Programs | Sub-50 ppm moisture certification positions anhydrous grades for solid-state electrolyte research pipelines at Japanese institutes. |
Methodological Framework
Initial hypotheses were tested against primary input from pyrotechnics procurement managers, pharmaceutical compounding specialists, battery research laboratory directors, and chemical distribution channel partners and refined through secondary validation. Sources included customs trade data for strontium compound flows, ECHA REACH registration databases, SEC filings by listed chemical processors, and China MEE environmental compliance disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Variance decomposition across grade tier, end-use application, and regional production hub segmentation dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from trend extrapolation of historical volume flows adjusted for regulatory compliance cost step-changes and substitution risk in moisture-sensitive electronics. Forecast inputs incorporated Qinghai mining restoration bond implementation timelines and solid-state electrolyte research program scale-up trajectories.
Forecasts assume regulatory continuity in ECHA REACH, EPA effluent standards, and China MEE wastewater discharge regimes; material policy shifts would require re-modeling. Specific risks include alternative alkaline earth salt substitution in battery applications and celestite ore export restriction scenarios. Revision becomes warranted when anhydrous grade qualification volumes for solid-state electrolyte research cross commercialization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Furniture Foam Market
Specialty Compounds
Polyoxin Market