
 Middle-East and Africa Thermoplastics Market | 2026-2036
Middle-East and Africa Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Thermoplastics Market Foresight
Saudi petrochemical capacity additions are rebalancing resin availability across the Middle-East and Africa region. SABIC leverages its integrated feedstock position to dominate polyethylene supply chains. LyondellBasell Industries Holdings B.V. competes through polypropylene specialization and catalyst technology leadership. BASF SE anchors high-performance polymer segments with engineering thermoplastics tailored to automotive specifications.
Thermoplastics are polymers that soften upon heating and solidify when cooled, enabling repeated melt-processing via injection molding, extrusion, or blow molding without chemical degradation. Polyethylene and polypropylene together constitute the volume backbone, serving packaging films, rigid containers, and pipe applications across construction and consumer goods. Injection molding commands premium margins in automotive and precision components, while extrusion processes sustain bulk demand for sheeting and profiles in building infrastructure. Packaging applications lead volume consumption, though construction-grade formulations represent the fastest-expanding margin pool as Gulf states execute megaproject pipelines.
Saudi Standards, Metrology and Quality Organization (SASO) and South African Bureau of Standards (SABS) enforce product certification and material specifications that gate market access for imported resins. REACH-aligned regulations in Gulf Cooperation Council jurisdictions are tightening additive and recyclate disclosure requirements, redirecting formulation strategies among compounders. Environmental frameworks from South Africa's Department of Forestry, Fisheries and the Environment and emerging extended producer responsibility schemes across the region are elevating post-consumer recycled content mandates. Stakeholders must monitor regulatory divergence between Gulf and sub-Saharan enforcement regimes when allocating technical compliance resources.
Market Dynamics
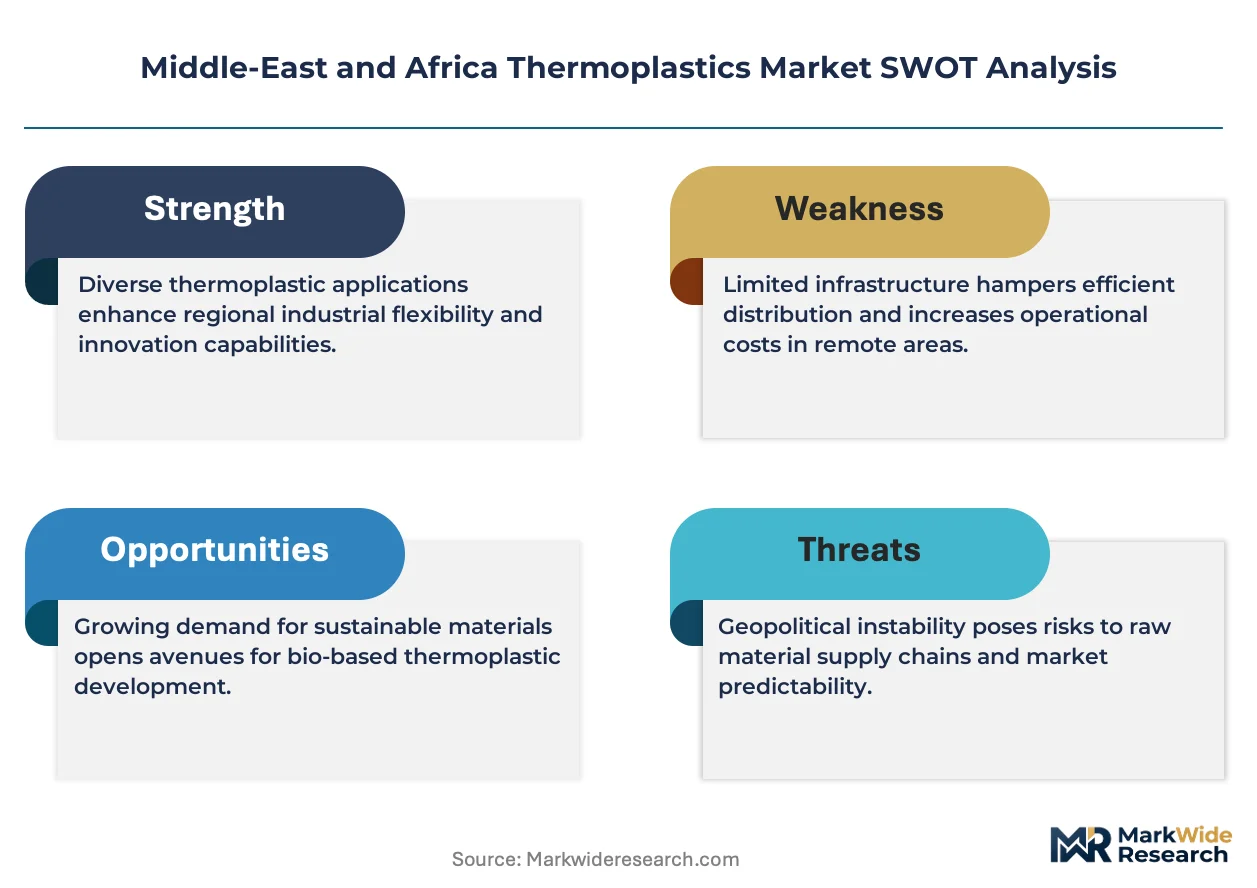
Saudi Aramco's feedstock integration and SABIC's polyethylene expansions are concentrating resin supply power in Gulf Cooperation Council states, redirecting trade flows and compressing margins for importers across sub-Saharan Africa.
Growth Catalysts
- GCC Megaproject Pipelines:Construction-grade polypropylene demand accelerates as Saudi Arabia and the United Arab Emirates execute infrastructure investment programs. Pipe extrusion and geomembrane applications absorb rising resin volumes.
- SASO Certification Alignment:Saudi Standards, Metrology and Quality Organization specifications for construction materials are standardizing import requirements. Compounders reformulating to meet these thresholds gain preferential market access.
- Post-Consumer Recyclate Mandates:South Africa's Department of Forestry, Fisheries and the Environment extended producer responsibility schemes elevate recycled content specifications. Packaging converters invest in compatibilization technology to meet compliance thresholds.
Market Restraints
- Naphtha Feedstock Volatility:Ethylene production costs fluctuate with crude oil price movements. Gulf petrochemical margins compress when benchmark differentials narrow against Asian spot naphtha.
- Import Dependency Concentration:Sub-Saharan African markets rely on resin shipments from Saudi Arabia and the United Arab Emirates. Port congestion at Durban and Lagos creates inventory cycles that disrupt converter operations.
- Engineering Thermoplastics Substitution:High-performance applications in automotive underhood components face metal and composite displacement. Polyamide and PBT specifications compete with aluminum casting and carbon fiber reinforced polymers.
Strategic Opportunities
- Egyptian Manufacturing Base:Suez Canal Economic Zone incentives attract compounders serving North African and Levantine markets. Local production reduces duty exposure versus Gulf-sourced imports.
- Medical Device Extrusion:IV tubing and diagnostic housing specifications create demand for medical-grade PVC and TPE formulations. Egyptian and South African converters target hospital procurement tenders.
- Recycling Infrastructure Investment:South African waste management privatization opens collection and sorting asset opportunities. Mechanical recycling of polyethylene films supports circular economy compliance.
Industry Challenges
- Polymer Processing Technician Shortage:Injection molding and extrusion operations in Nigeria and Kenya lack skilled machine operators. Training programs at technical institutes lag equipment deployment timelines.
- Multi-Jurisdiction Certification Burden:SASO, SABS, and Egyptian Organization for Standardization and Quality specifications require parallel testing protocols. Compliance costs escalate for pan-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Thermoplastics Market |
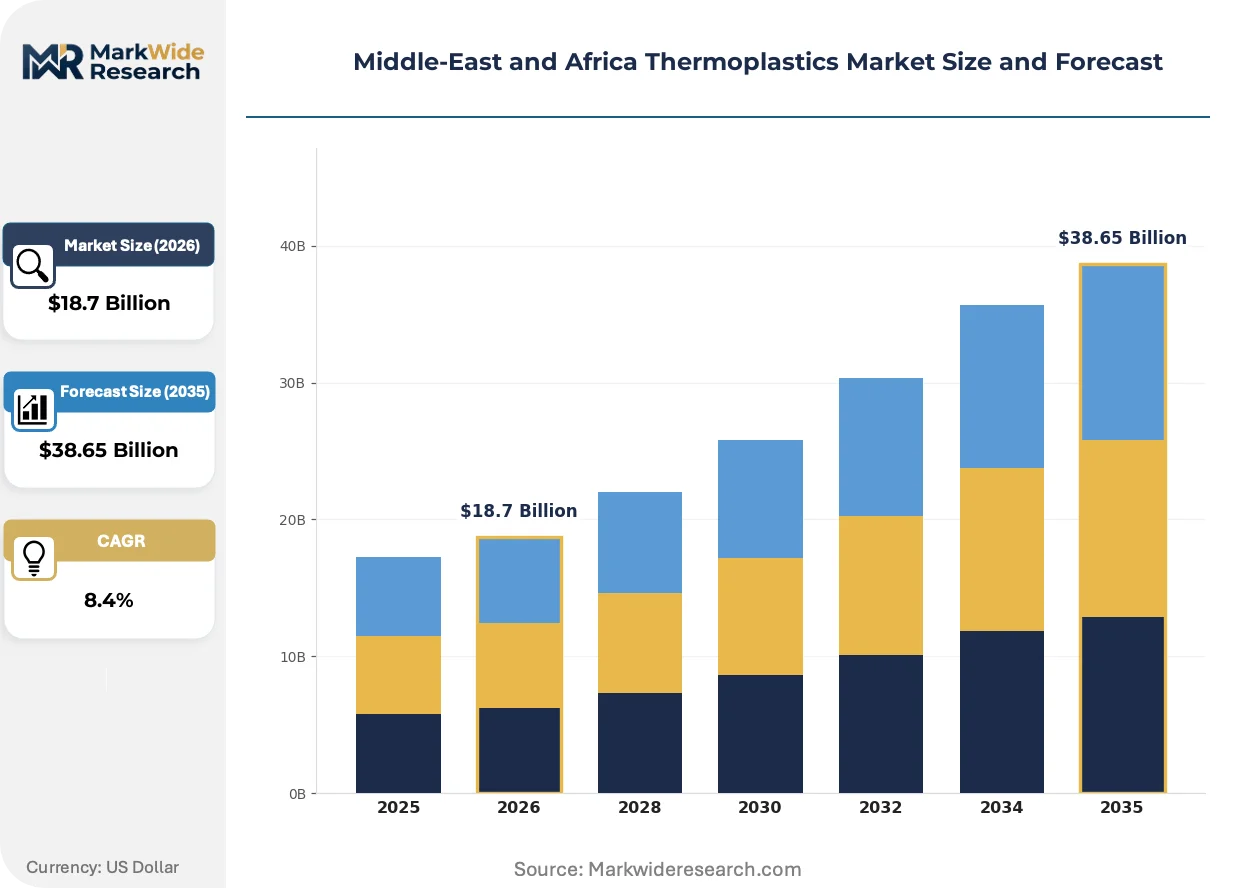
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Automotive, Consumer Goods, Packaging, Construction Application: Injection Molding, Extrusion, Blow Molding, Thermoforming Form: Pellets, Sheets, Films, Granules |
| Companies Covered | SABIC, LyondellBasell Industries Holdings B.V., BASF SE, Solvay, LANXESS, Evonik Industries AG, Arkema, DuPont, Chevron Phillips Chemical Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Thermoplastics Market Shifts & Advancements
Metallocene catalyst systems and advanced recycling technologies are redefining resin performance specifications and circularity credentials across Middle-East and African conversion operations.
Metallocene linear low-density polyethylene is expanding into flexible packaging films with superior puncture resistance and seal integrity. Saudi and Emirati food processors adopt these grades for retort pouch and lidding applications. The technology is expanding into traditional Ziegler-Natta volume segments, compressing commodity margin pools for conventional resin suppliers.
REACH-aligned chemical disclosure requirements in Gulf Cooperation Council jurisdictions are tightening additive and stabilizer documentation obligations. Compounders must reformulate masterbatches to meet substance registry thresholds. Automotive specification sheets in Saudi Arabia and the United Arab Emirates now require full material composition disclosure, forcing supply chain transparency investments.
Converter procurement patterns favor toll compounding arrangements over merchant resin spot purchases. Egyptian and South African packaging manufacturers contract dedicated extrusion lines with guaranteed offtake volumes. This concentration is most visible in polyethylene film operations serving multinational fast-moving consumer goods brands with sustainability audit requirements.
Middle-East and Africa Thermoplastics Market Segmentation
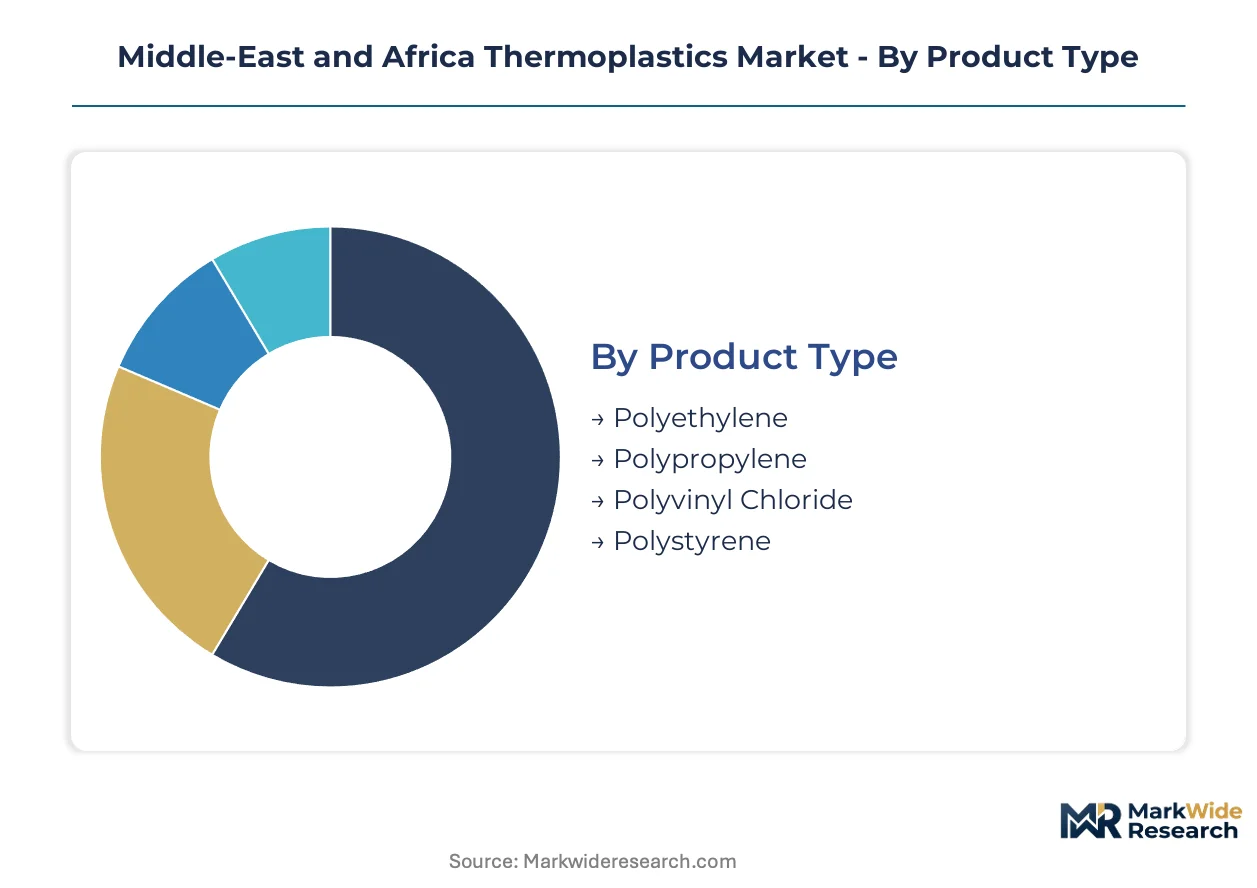
Thermoplastics demand across the Middle-East and Africa fragments across resin chemistry, conversion technology, and end-use specifications. Understanding these segment boundaries clarifies where formulation investments concentrate and which processing routes command premium positioning.
Product Type:
Polyethylene and polypropylene function as standalone commodity resins in high-volume applications, while PVC and polystyrene embed more deeply into specialized construction and packaging systems requiring additive packages.
- Polyethylene:Linear low-density and high-density grades dominate flexible packaging films and rigid pipe extrusion. Saudi Aramco feedstock integration has concentrated polyethylene supply power in Gulf Cooperation Council states, redirecting trade flows toward sub-Saharan African converters.
- Polypropylene:Homopolymer and copolymer specifications serve automotive interior components, woven sacks, and construction-grade geomembranes. LyondellBasell catalyst technology leadership differentiates polypropylene supply chains across Egyptian and South African compounding operations.
- Polyvinyl Chloride:Rigid and plasticized formulations target pipe systems, cable insulation, and medical device extrusion. SASO construction material certifications gate market access for imported PVC compounds.
- Polystyrene:General-purpose and high-impact grades supply food service disposables and appliance housings. Expanded polystyrene insulation boards absorb volumes in Saudi megaproject thermal envelope specifications.
Polyethylene leads volumes today; polypropylene is gaining share fastest.
End User:
Cost tier stratification separates specification-grade automotive and construction demand from price-sensitive consumer goods procurement.
- Automotive:Engineering thermoplastics specifications for underhood components and interior trim require heat resistance and dimensional stability. Polyamide and PBT compounds compete with metal casting in Saudi vehicle assembly plants.
- Consumer Goods:Polypropylene homopolymer dominates housewares and appliance housings through injection molding efficiency. Durability requirements lag automotive specifications, permitting broader supplier qualification.
- Packaging:Polyethylene films and polypropylene rigid containers absorb the largest resin volumes across the region. South African extended producer responsibility schemes mandate recycled content thresholds for flexible packaging converters.
- Construction:Pipe extrusion, geomembrane liners, and insulation boards drive the fastest-expanding demand pool. GCC megaproject pipelines accelerate construction-grade polypropylene and PVC specifications.
Packaging leads volumes today; construction is climbing the fastest.
Application:
Volume concentration favors continuous extrusion processes, while batch-mode injection molding captures margin premiums in precision components.
- Injection Molding:High-pressure clamping systems produce automotive interior panels, medical device housings, and consumer appliance components. Cycle time optimization and tool steel durability differentiate competitive positioning among Egyptian and South African processors.
- Extrusion:Single-screw and twin-screw systems sustain bulk resin consumption for pipe, sheet, and film production. GCC construction pipelines absorb rising extrusion capacity for pressure-rated polyethylene pipe.
- Blow Molding:Extrusion blow and injection blow configurations supply rigid containers for food, chemical, and lubricant packaging. Parison programming controls wall thickness distribution in high-volume dairy bottle operations.
- Thermoforming:Vacuum and pressure forming processes convert extruded sheet into disposable cups, trays, and medical device blisters. Thin-gauge polystyrene and polypropylene sheet specifications dominate food service applications.
Extrusion leads volumes today; injection molding captures the steepest margin expansion.
Form:
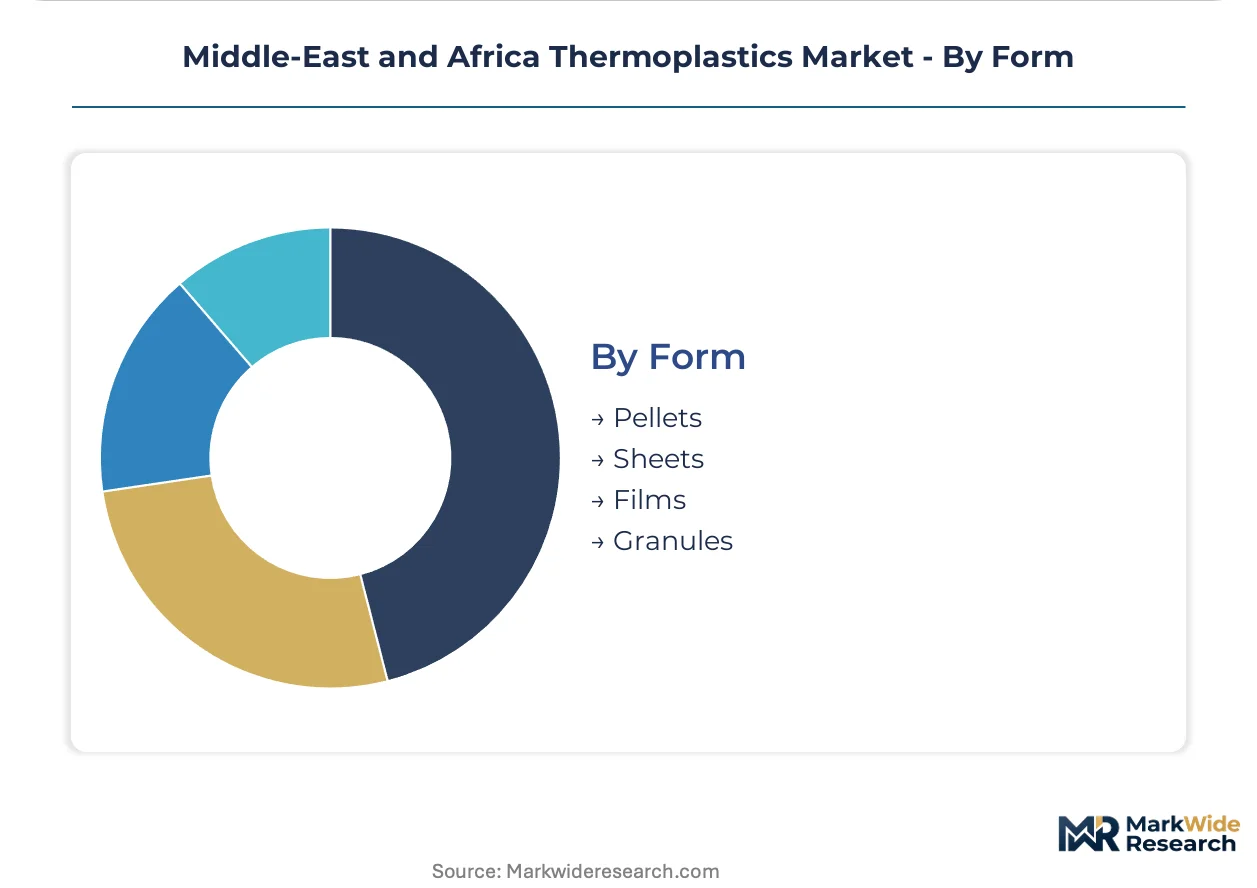
Supply chain configuration separates bulk pellet shipments for compounders from value-added film and sheet deliveries to downstream converters.
- Pellets:Cylindrical resin pellets constitute the standard feedstock form for injection molding and extrusion operations. SABIC and regional petrochemical producers ship bulk pellet volumes to compounders across sub-Saharan Africa.
- Sheets:Extruded flat and corrugated thermoplastic panels serve signage, glazing, and thermoforming feedstock applications. Local sheet extrusion reduces freight costs versus pellet conversion for Egyptian packaging manufacturers.
- Films:Blown and cast film processes produce flexible packaging substrates with controlled thickness and optical properties. Metallocene linear low-density polyethylene grades expand into retouch pouch applications with superior puncture resistance.
- Granules:Irregular regrind and compounded granules supply lower-specification molding operations and recycling feedstreams. South African mechanical recyclers process post-consumer polyethylene films into granules for circular economy compliance.
Pellets lead volumes today; films are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia concentrates polyethylene supply power while South Africa absorbs the region's most complex regulatory compliance burdens for recycled content mandates.
Saudi Arabia
SABIC's Yanbu and Jubail complexes feed construction-grade polypropylene into NEOM and Red Sea Project pipelines. SASO certification requirements for pipe extrusion materials standardize import thresholds across Gulf Cooperation Council jurisdictions. The Eastern Province petrochemical cluster redirects resin trade flows toward sub-Saharan African converters.
United Arab Emirates
Dubai and Abu Dhabi megaprojects drive geomembrane and insulation board specifications. MOHAP medical device regulations create compliance pathways for PVC compounders serving hospital procurement. Jebel Ali industrial zone hosts toll compounding operations for multinational packaging brands.
South Africa
Extended producer responsibility schemes from the Department of Forestry, Fisheries and the Environment mandate post-consumer recycled content in flexible packaging. Durban port congestion disrupts resin inventory cycles for converters across the Southern African Development Community. Gauteng's mechanical recyclers process polyethylene films into circular economy feedstock.
Egypt
Suez Canal Economic Zone incentives attract compounders targeting North African and Levantine markets. The Egyptian Organization for Standardization and Quality enforces parallel testing protocols that escalate compliance costs for pan-regional suppliers. Alexandria's extrusion operations reduce duty exposure versus Gulf-sourced pellet imports.
Nigeria
Lagos port infrastructure constraints create inventory volatility for resin-dependent converters. The country's national standards body maintains material specification gates for construction-grade imports. Technical institutes in Lagos and Kano lag injection molding technician training behind equipment deployment timelines.
Middle-East and Africa Thermoplastics Market Competitive Landscape
Gulf Cooperation Council producers anchor the commodity resin tier; European and North American specialists hold premium positions in engineering thermoplastics and catalyst technologies. Market structure concentrates polyethylene supply power among vertically integrated petrochemical complexes while polypropylene and specialty segments retain more fragmented participation. Three archetypes dominate: feedstock-integrated Gulf producers, catalyst-technology licensors, and high-performance polymer compounders. Capacity expansion and strategic technology licensing represent the dominant competitive moves across the forecast window.
Within the feedstock-integrated tier, SABIC and LyondellBasell Industries Holdings B.V. occupy positions defined by captive ethylene supply and catalyst specialization respectively. BASF SE sits within the high-performance polymer segment, exemplifying the engineering thermoplastics archetype tailored to automotive specification requirements. These three companies represent the structural fault lines between commodity volume production and premium formulation capabilities across Middle-East and African supply chains.
| Leading Market Players |
|---|
| SABIC |
| LyondellBasell Industries Holdings B.V. |
| BASF SE |
| Solvay |
| LANXESS |
| Evonik Industries AG |
| Arkema |
| DuPont |
| Chevron Phillips Chemical Company |
| Others |
Supply & Pricing Matrix
Sovereign-backed petrochemical producers in the Gulf Cooperation Council anchor supply concentration and pricing discipline across Middle-East and African thermoplastics markets. Their captive ethane feedstock positions compress delivered resin costs versus naphtha-dependent European and Asian competitors, forcing importers in sub-Saharan Africa to absorb margin compression or cede market share.
Pricing Analysis
Capacity additions in Saudi Arabia and the United Arab Emirates are reshaping price floors for polyethylene and polypropylene across the region. Three-tier pricing structure across metallocene premium, standard Ziegler-Natta, and recycled-economy grades separates specification-driven automotive buyers from price-sensitive construction converters. Cost compression in commodity polyethylene is intensifying because SABIC's Yanbu and Jubail expansions redirect trade flows toward East African markets. Packaging converters in Nigeria and Kenya exhibit the highest price sensitivity, while medical device compounders in South Africa accept premium spreads for SASO-certified PVC formulations.
Supply Chain Analysis
Regional distribution centers in Jebel Ali, Durban, and Alexandria organize hub-and-spoke patterns for pellet shipments across sub-Saharan Africa. Supply concentrates in Saudi Arabia, the United Arab Emirates, and South Africa, with Egyptian extrusion operations drawing from Gulf-sourced resin to reduce duty exposure. Raw material dependencies rest on ethane feedstock from Saudi Aramco's gas processing complexes, naphtha cargoes from Asian spot markets, and calcium carbonate fillers from Egyptian mining operations. Single-source vulnerability runs through Lagos and Durban port infrastructure, where congestion creates inventory cycles that disrupt converter operations. Distribution runs through toll compounding arrangements rather than merchant resin spot purchases, particularly for multinational fast-moving consumer goods brands with sustainability audit requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa thermoplastics market functions as a geographic-arbitrage play where Egyptian and North African compounders exploit duty advantages against Gulf-sourced imports, while South African recyclers capture regulatory premiums from extended producer responsibility mandates that lack equivalent enforcement in sub-Saharan markets.
For Market Incumbents: Hedge feedstock exposure by securing long-term ethane supply agreements with Saudi Aramco or diversifying into recycled-content compounding to preempt South Africa's Department of Forestry, Fisheries and the Environment mandates. Capacity additions in Egypt's Suez Canal Economic Zone threaten margin compression for Gulf-based polyethylene suppliers serving Levantine markets. Backward integration into mechanical recycling infrastructure in Gauteng offers defensive positioning against post-consumer recyclate specifications tightening across the Southern African Development Community. For New Entrants and Emerging Players: South Africa's extended producer responsibility schemes open a window for compatibilization technology specialists serving packaging converters struggling to meet recycled content thresholds. Medical device extrusion in Egypt represents the most penetrable white-space target, given MOHAP regulatory alignment with Gulf Cooperation Council jurisdictions and underdeveloped local PVC compounding capacity. Target hospital procurement tenders through toll manufacturing partnerships with established Egyptian converters already holding ISO 13485 certification. For Investors and Strategic Acquirers: Valuations sit cheapest among sub-Saharan African distribution-dependent compounders lacking feedstock integration, particularly Nigerian and Kenyan operations exposed to Lagos port congestion and skilled technician shortages. Long-term viability across the analysis window favors asset-light recycling technology licensors over capital-intensive resin production. The signal to watch is SASO certification harmonization across Gulf Cooperation Council states, which would elevate compliance costs for pan-regional suppliers and trigger consolidation among multi-jurisdiction compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | South African waste management privatization opens collection and sorting asset opportunities for circular economy compliance. |
| Capacity Expansion in Suez Canal Economic Zone | Egyptian incentives attract compounders reducing duty exposure versus Gulf-sourced imports for North African markets. |
| Long-term Supply Agreement with Feedstock Integrators | SABIC's polyethylene expansions concentrate supply power, making captive ethane access a competitive differentiator. |
| Joint Venture for Medical Device Compounding | MOHAP regulations in the United Arab Emirates create compliance pathways for PVC compounders serving hospital procurement. |
| Green Manufacturing Transition to Metallocene Catalysts | Advanced catalyst systems expand into retort pouch applications with superior puncture resistance for Saudi food processors. |
Research Methodology
Multiple input streams — plant manager interviews at Saudi and Emirati petrochemical complexes, procurement lead discussions with Egyptian packaging converters, and regulatory affairs consultations with South African compounders — were reconciled against customs and trade data, SABIC and regional producer disclosures, and SASO certification databases. Secondary validation drew from GCC petrochemical association reports, extended producer responsibility filings with South Africa's Department of Forestry, Fisheries and the Environment, and Suez Canal Economic Zone investment authority records. Bottom-up resin consumption estimates by end-use application were triangulated against top-down capacity and trade flow analysis.
Historical volume trajectories were cross-referenced against panel input from technical directors at compounding operations across Nigeria, Kenya, and Egypt to establish baseline elasticity parameters. The analytical framework models demand across resin chemistry, conversion technology, end-use specification, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic infrastructure investment indicators and petrochemical capacity expansion timelines. Industry-specific forecast inputs include GCC megaproject pipeline execution schedules and South African mechanical recycling capacity buildout trajectories.
Revisions become necessary when crude oil-naphtha benchmark differentials shift substantially, GCC megaproject timelines accelerate or delay, or sub-Saharan port infrastructure investments alter inventory cycle dynamics. Forecasts reflect assumptions about regulatory harmonization continuity and feedstock cost pass-through mechanisms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market