
 Global Polyolefin Resins Market | 2026-2036
Global Polyolefin Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyolefin Resins Market Foresight
REACH is decoupling virgin resin economics from historical feedstock advantages across European conversion markets. LyondellBasell Industries Holdings N.V. leverages its Spheripol and Spherizone process technologies to sustain differentiated polypropylene output. ExxonMobil Chemical anchors North American supply through its Baytown and Baton Rouge integrated complexes. Dow competes on metallocene polyethylene platforms that command premium positioning in flexible packaging.
Polyolefin resins comprise thermoplastic polymers synthesized primarily from ethylene and propylene monomers through Ziegler-Natta or metallocene catalysis, yielding crystalline structures with densities ranging from 0.86 to 0.97 g/cm³ and melt flow indices spanning 0.01 to 1500 g/10 min. These materials serve as foundational inputs for durable goods, flexible films, rigid containers, and infrastructure piping due to their chemical inertness, processability, and tunable mechanical properties. Polypropylene injection molding grades dominate automotive Tier-1 supplier contracts where weight reduction targets favor density advantages over engineering plastics. High-density polyethylene pipe compounds occupy margin-rich positions in potable water and gas distribution infrastructure where PE100 and PE4710 certifications create supply stickiness. Film-grade linear low-density polyethylene sustains volume leadership across e-commerce packaging stretch and shrink applications.
FDA food-contact regulations, EPA emissions standards for olefin production, and EU F-Gas Regulation on fluorinated process agents collectively reshape formulation pathways and capital allocation for new capacity. BIS certification requirements in India and China's GB standards for plastic piping add compliance layers that favor producers with established testing infrastructure. Stakeholders must monitor how polymer-to-monomer recycling technologies and mass-balance certification schemes alter feedstock qualification criteria.
Market Dynamics
REACH decoupling is severing virgin polyolefin economics from historical naphtha feedstock advantages across European conversion markets, while China's state-owned refiners commission world-scale propylene complexes that compress regional supply curves.
Growth Catalysts
- E-commerce fulfillment networks:Asia-Pacific packaging converters are expanding polyethylene film capacity to serve automated warehouse systems and last-mile delivery packaging.
- EU Green Deal recyclability mandates:Binding targets for single-use plastics are forcing resin producers to reformulate grades with higher recycled content thresholds.
- Automotive lightweighting protocols:Tier-1 suppliers are specifying polypropylene injection molding grades to replace engineering plastics in interior and under-hood applications.
Market Restraints
- Naphtha-crude price volatility:European steam crackers remain exposed to volatile naphtha differentials against US ethane feedstock economics.
- Chinese state-owned supply concentration:Sinopec and PetroChina commissioning capacity creates regional oversupply risk that depresses export netbacks.
- Mechanical recycling contamination limits:Multi-layer flexible packaging structures exceed current sorting and reprocessing capabilities at industrial scale.
Strategic Opportunities
- India BIS certification infrastructure:Domestic testing capabilities for plastic piping standards create first-mover advantages for compliant resin suppliers.
- Polymer-to-monomer recycling:Pyrolysis and chemical depolymerization technologies are converging with mass-balance certification schemes to qualify recycled feedstocks.
- Hydrotreated vegetable oil feedstocks:Bio-based olefin production pathways align with EU taxonomy criteria for sustainable finance eligibility.
Industry Challenges
- Metallocene catalyst IP licensing:Proprietary single-site catalyst systems require complex royalty structures and technical service agreements.
- PE100 and PE4710 certification timelines:Potable water and gas distribution infrastructure grades demand multi-year testing protocols for hydrostatic stress ratings.
- Legacy Ziegler-Natta asset retrofit:Converting existing polypropylene lines to broad-reactor-grade flexibility requires significant reactor modification capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyolefin Resins Market |
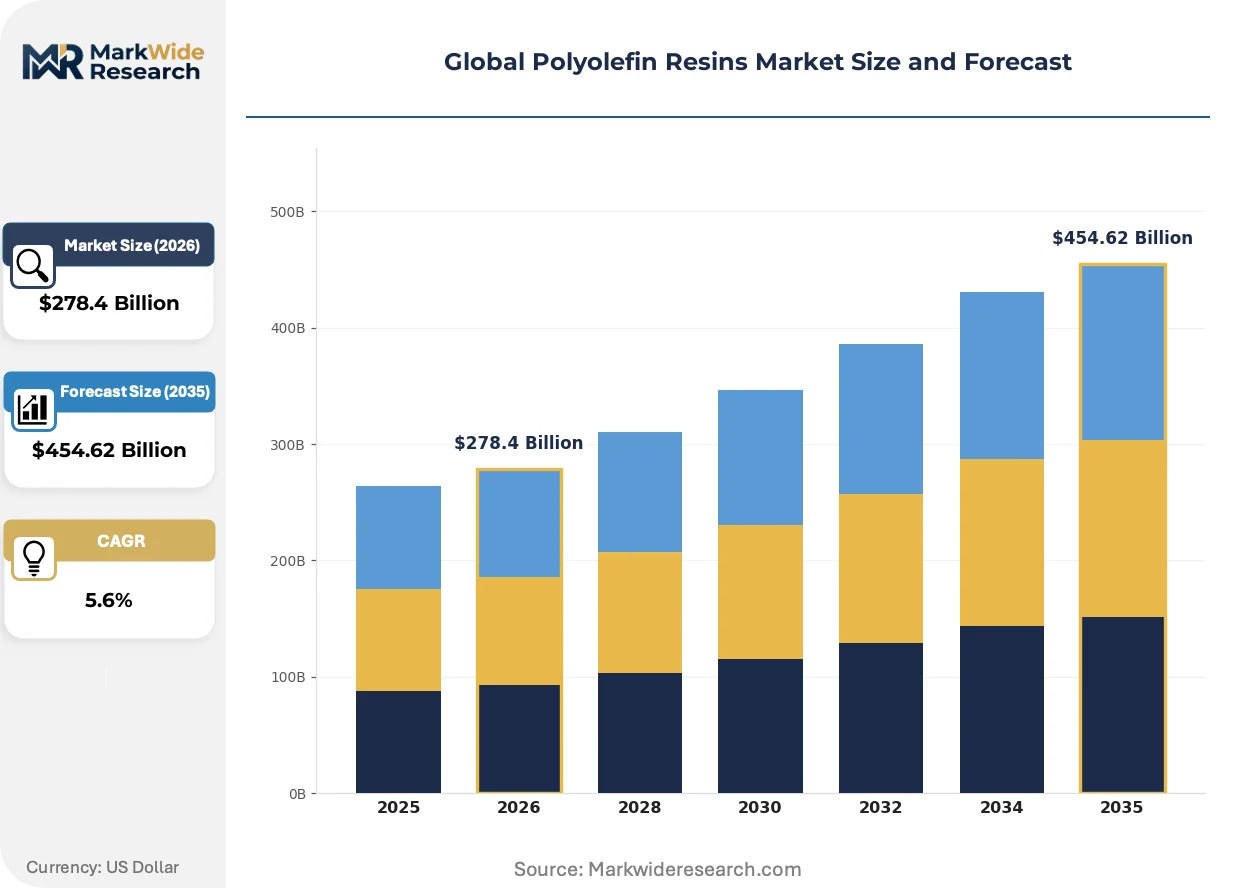
| Market Size in 2026 | $278.4 Billion |
| Market Size in 2035 | $454.62 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Polyethylene, Low-Density Polyethylene, Linear Low-Density Polyethylene, Polypropylene, Ethylene Vinyl Acetate Grade: Injection Molding, Blow Molding, Film Grade, Extrusion Grade, Compounding Grade Application: Packaging, Automotive Tier-1 Suppliers, Electrical Insulation, Consumer Goods, Agriculture Film End User: Plastic Fabricators, Pipe Manufacturers, Wire & Cable Producers, Consumer Durable Makers, Textile Processors |
| Companies Covered | LyondellBasell Industries Holdings N.V., ExxonMobil Chemical, Sinopec Corporation, Dow, SABIC, PetroChina Company Limited, Borealis AG, Braskem S.A., TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyolefin Resins Market Shifts & Advancements
Advanced catalyst architectures and regulatory compliance frameworks are actively restructuring how polyolefin producers compete on grade differentiation and carbon intensity credentials.
Metallocene polyethylene platforms are integrating precise molecular weight distribution control to enable down-gauging in flexible packaging without sacrificing seal integrity. Food and personal care brand owners are specifying these grades for premium mono-material structures that satisfy EU recyclability mandates. The technology is integrating premium positioning into commodity resin portfolios by collapsing the performance gap between LLDPE and specialty plastomers.
REACH authorization procedures are restricting conventional process aids and stabilizer packages used in high-clarity film grades. ECHA substance evaluations are forcing reformulation toward bio-based nucleating agents and phenol-free antioxidant systems. Flexible packaging converters in Germany and France are accelerating qualification of alternative additive suites to maintain uninterrupted market access.
Brand-led packaging redesign is consolidating demand around mono-material polyethylene structures that bypass mechanical recycling sortation failures. Major beverage and food companies are retiring multi-layer barrier laminates in favor of metallized or coated mono-PE alternatives. This specification shift is most visible in Western European retail channels where extended producer responsibility fees penalize non-recyclable formats.
Global Polyolefin Resins Market Segmentation
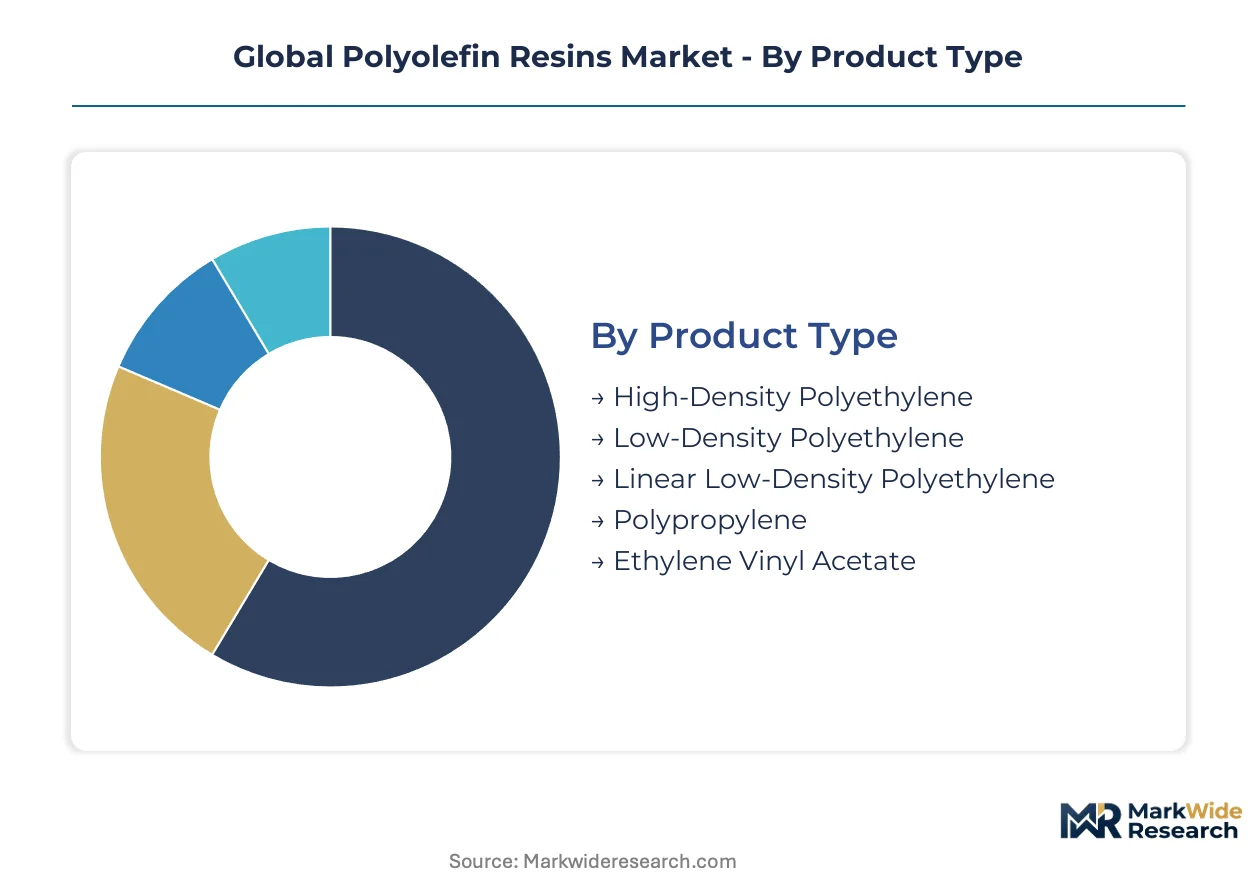
Polyolefin resin producers compete through grade-specific formulation capabilities that lock in multi-year supply contracts. Segmentation reveals where technical specifications create switching costs versus where commodity arbitrage dominates purchasing decisions.
Product Type:
Some polyolefin types function as standalone materials with direct converter relationships, while others embed into compounder formulations as performance modifiers.
- High-Density Polyethylene:Semi-crystalline structure with density above 0.941 g/cm³ delivers stiffness and chemical resistance for pressure-rated pipe applications. PE100 and PE4710 certified grades command supply stickiness in German and French municipal water infrastructure where hydrostatic stress ratings require multi-year validation protocols.
- Polypropylene:Isotactic configuration yields high melting point and flexural modulus for thin-wall injection molding. Automotive Tier-1 suppliers in Stuttgart and Detroit specify homopolymer and impact copolymer grades to replace engineering plastics in instrument panels and bumper fascias under weight reduction mandates.
- Linear Low-Density Polyethylene:Short-chain branching from butene or hexene comonomers enables puncture resistance in stretch film.
- Low-Density Polyethylene:High-pressure autoclave or tubular process creates long-chain branching for clarity and processability.
- Ethylene Vinyl Acetate:Polar copolymer with VA content ranging 2-40% for hot-melt adhesives and solar encapsulant films.
Volume placements concentrate in Polypropylene; the faster expansion belongs to Linear Low-Density Polyethylene.
Grade:
Grade differentiation separates resin portfolios into specification-driven premium tiers versus volume-driven commodity positions.
- Film Grade:Narrow molecular weight distribution and controlled melt flow index optimize bubble stability in blown film extrusion. E-commerce fulfillment networks in China and India specify metallocene-catalyzed film grades for automated warehouse stretch wrap where down-gauging reduces material intensity per pallet.
- Injection Molding:High melt flow rates above 20 g/10 min enable thin-wall packaging and complex automotive components. Tier-1 suppliers in Bavaria and Michigan qualify broad-reactor-grade polypropylene for just-in-sequence delivery contracts that penalize off-specification deliveries.
- Blow Molding:High molecular weight with broad polydispersity supports parison stability in bottle and drum production.
- Extrusion Grade:Balanced rheology for sheet, profile, and pipe extrusion with consistent swell characteristics.
- Compounding Grade:Base resin for mineral-filled and glass-reinforced formulations in appliance and automotive under-hood applications.
Film Grade captures the largest shipment volumes; Injection Molding delivers the steepest margin expansion.
Application:
Application segmentation tracks how regulatory pressure and end-use performance requirements reshape formulation priorities across conversion markets.
- Packaging:Flexible films, rigid containers, and closures represent the dominant demand sink with specification diversity spanning food-contact FDA compliance to industrial dunnage. EU Green Deal recyclability mandates are forcing mono-material polyethylene redesigns in French and German retail channels where extended producer responsibility fees penalize multi-layer laminates.
- Automotive Tier-1 Suppliers:Interior, exterior, and under-hood components specify talc-filled and glass-reinforced grades for dimensional stability. Lightweighting protocols in Detroit and Wolfsburg favor density advantages over ABS and polycarbonate in non-structural applications.
- Electrical Insulation:Cross-linkable polyethylene compounds for medium and high-voltage cable sheathing.
- Consumer Goods:Housewares, furniture, and appliances utilize impact-modified grades for durability.
- Agriculture Film:UV-stabilized formulations for greenhouse covers and silage wrap with controlled degradation profiles.
Packaging anchors volume demand; Automotive Tier-1 Suppliers generate the fastest specification upgrades.
End User:
End user categories reveal where captive integration versus merchant market dynamics govern procurement patterns.
- Pipe Manufacturers:PE100 and PE4710 certified compounders serve gas distribution and potable water infrastructure with multi-decade service life requirements. German and Italian pipe extruders maintain approved supplier lists that lock out uncertified resin sources.
- Plastic Fabricators:General-purpose converters span blow molding, thermoforming, and rotational molding with grade flexibility and price sensitivity. Indian fabricators in Gujarat and Maharashtra face BIS certification requirements for plastic piping that favor established testing infrastructure.
- Wire & Cable Producers:Compounding-intensive segment requiring flame-retardant and cross-linkable formulations.
- Consumer Durable Makers:Appliance and electronics housings with color consistency and surface finish specifications.
- Textile Processors:Polypropylene fiber and filament for non-wovens, carpet backing, and geotextiles.
Pipe Manufacturers concentrate premium grade offtake; Plastic Fabricators drive volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces and India's western industrial corridors concentrate polyolefin resin conversion capacity through tax holidays and duty exemptions on imported catalysts.
China
E-commerce fulfillment networks in Zhejiang and Jiangsu provinces drive polyethylene film demand for automated warehouse stretch wrap. MIIT's GB standards for plastic piping mandate BIS-equivalent certification for domestic infrastructure projects. Sinopec and PetroChina are commissioning world-scale polypropylene complexes in Ningbo and Dalian that compress regional supply curves.
United States
Shale-derived ethane feedstock economics anchor Gulf Coast polyethylene exports to Latin American packaging converters. EPA emissions standards for olefin production require flare-gas recovery systems at Baytown and Baton Rouge integrated complexes. ExxonMobil Chemical maintains merchant market supply dominance through captive cracker capacity along the Texas-Louisiana corridor.
Germany
Automotive Tier-1 suppliers in Stuttgart and Wolfsburg specify polypropylene injection molding grades for interior lightweighting protocols. REACH authorization procedures restrict conventional process aids in high-clarity film grades, forcing reformulation toward bio-based nucleating agents. Flexible packaging converters in Bavaria accelerate qualification of phenol-free antioxidant systems to maintain EU market access.
India
BIS certification requirements for plastic piping create first-mover advantages for resin suppliers with established testing infrastructure in Gujarat and Maharashtra. The PLI scheme for specialty chemicals incentivizes domestic catalyst manufacturing partnerships. Pipe extruders in Ahmedabad and Mumbai maintain approved supplier lists that lock out uncertified resin sources from municipal water infrastructure tenders.
Saudi Arabia
SABIC's Yanbu and Jubail complexes leverage stranded gas economics for cost-advantaged polyethylene export supply to African and South Asian markets. SAMR-aligned standards for food-contact materials align with FDA equivalency recognition for polymer imports. The kingdom's downstream conversion parks in Ras Al-Khair attract film-grade offtake commitments from Turkish and Egyptian packaging converters.
Global Polyolefin Resins Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology licensing, feedstock integration, and grade differentiation vectors. The market structures around three tiers: integrated majors with captive olefin production, regional champions with government-backed expansion programs, and technology licensors monetizing proprietary catalyst IP. Strategic moves concentrate on metallocene platform licensing agreements and backward integration into alpha-olefin comonomer supply.
Within the integrated major tier, LyondellBasell Industries Holdings N.V. and ExxonMobil Chemical occupy positions defined by Spheripol process technology and Gulf Coast feedstock access respectively. Sinopec Corporation represents the state-backed archetype with domestic market prioritization and world-scale capacity commissioning. These three exemplify how geographic feedstock advantages and catalyst IP ownership separate premium-grade suppliers from commodity resin arbitrageurs.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings N.V. |
| ExxonMobil Chemical |
| Sinopec Corporation |
| Dow |
| SABIC |
| PetroChina Company Limited |
| Borealis AG |
| Braskem S.A. |
| TotalEnergies |
| Others |
Supply & Pricing Matrix
Automotive Tier-1 supplier concentration in Stuttgart and Wolfsburg anchors contract-based long-term offtake pricing for polypropylene injection molding grades. PE100 and PE4710 certified pipe compounds command premium positioning through multi-year hydrostatic stress validation protocols that lock out spot-market arbitrage.
Pricing Analysis
Short lead-time premiums separate emergency spot purchases from scheduled contract deliveries in European conversion markets. Three-tier pricing structure across premium metallocene-catalyzed grades, standard Ziegler-Natta film grades, and economy bulk polyethylene levels reflects certification intensity and volume scale. Cost compression in commodity LLDPE runs through Chinese state-owned capacity additions that depress export netbacks. Plastic fabricators in India exhibit highest price sensitivity due to BIS certification cost pass-through constraints, while German pipe manufacturers accept premiums for certified supply security.
Supply Chain Analysis
Container freight rates from Saudi Arabia's Yanbu and Jubail complexes to African and South Asian markets tether export economics to Red Sea corridor stability. Supply concentrates in China, the United States, and Saudi Arabia, with Sinopec and PetroChina commissioning world-scale propylene complexes that reshape regional availability. Feedstock draws from stranded gas economics in the Gulf, shale-derived ethane along the Texas-Louisiana corridor, and naphtha cracking in European coastal refineries. Single-source vulnerability concentrates in alpha-olefin comonomer supply for metallocene catalyst systems. Distribution runs through merchant market spot sales, long-term offtake contracts with automotive OEMs, and approved supplier lists for municipal infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
World-scale polypropylene commissioning timelines in Ningbo and Dalian prop pricing power for incumbent producers with validated catalyst IP. Capacity absorption rates across Asia-Pacific e-commerce fulfillment networks determine margin sustainability.
For Market Incumbents:Cement supply stickiness through PE100 and PE4710 certification investments that extend validation timelines beyond competitor reach. Defend against pyrolysis-based polymer-to-monomer recycling entrants by locking mass-balance certification schemes with EU brand owners. Prioritize backward integration into alpha-olefin comonomer supply to secure metallocene platform economics.
For New Entrants and Emerging Players:Pyrolysis technology licensing partnerships offer entry into circular feedstock qualification where incumbents lack certified capacity. Target India's BIS certification infrastructure gap in Gujarat and Maharashtra for plastic piping grades. Pursue hydrotreated vegetable oil feedstock pathways aligned with EU taxonomy sustainable finance eligibility to bypass naphtha cost disadvantages.
For Investors and Strategic Acquirers:Distressed-cycle entries favor metallocene catalyst IP holders in European markets where REACH authorization costs burden legacy additive portfolios. Long-term viability centers on producers with demonstrated mass-balance certification and polymer-to-monomer recycling partnerships. Watch EU Green Deal extended producer responsibility fee implementation rates as inflection indicator for mono-material polyethylene specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Supply | Captive comonomer access secures metallocene catalyst economics against spot market volatility. |
| Mass-Balance Certification Partnership | Pyrolysis feedstock qualification unlocks EU Green Deal compliant supply contracts with brand owners. |
| PE100/PE4710 Validation Investment | Multi-year hydrostatic stress testing locks out uncertified competitors from German municipal water tenders. |
| BIS Certification Infrastructure Buildout | Domestic testing capabilities in Gujarat and Maharashtra create first-mover advantage in Indian pipe extrusion markets. |
| Hydrotreated Vegetable Oil Feedstock Transition | Bio-based olefin pathways align with EU taxonomy criteria for sustainable finance eligibility and premium positioning. |
Research Methodology
Independent corroboration across customs and trade data, SEC 10-K filings, and American Chemistry Council sector reports underwrites the qualitative findings. Primary interviews with plant managers at integrated polyolefin complexes, procurement leads at automotive Tier-1 suppliers, distribution channel partners in European flexible packaging markets, and technical R&D directors at catalyst technology licensors combined with secondary validation from BIS certification records and ECHA substance evaluation databases. Bottom-up grade-specific volume estimates and top-down regional demand aggregation triangulate market sizing.
Rate-of-change decomposition across ethylene and propylene monomer supply curves, e-commerce packaging intensity metrics, and automotive lightweighting content-per-vehicle trends drives the analytical framework. Segmentation dimensions modeled include product type tier, grade certification level, end-use industry, regional production hub, and feedstock source configuration. CAGRs derive from monomer cost pass-through elasticity, capacity utilization assumptions, and substitution dynamics against engineering plastics. Forecast inputs incorporate REACH authorization timelines and EU extended producer responsibility fee structures.
Several conditions sit outside the modeled scope, including unannounced capacity cancellations, breakthroughs in mechanical recycling contamination removal, and geopolitical disruptions to Red Sea shipping corridors. Forecasts reflect documented assumptions about catalyst technology licensing availability and mass-balance certification scheme adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Green Polyols Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Poly Propylene Glycol Market