
 Chelating Resins Market | 2026-2036
Chelating Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Chelating Resins Market Analysis
Specialized polymer chemist talent is reorganizing supply capability across the Chelating Resins Market as formulation complexity rises. LANXESS leverages its integrated ion-exchange resin production network to serve European water treatment operators. Mitsubishi Chemical Corporation anchors Asian supply through captive manufacturing of high-selectivity resins for semiconductor wastewater. Purolite competes on custom-engineered bead geometries that target specific metal ion capture in pharmaceutical streams.
Chelating resins are crosslinked polymer matrices functionalized with ligand groups such as iminodiacetic acid or aminophosphonic acid that form stable coordination complexes with dissolved metal ions; manufacturers produce these via suspension polymerization followed by chemical grafting, yielding bead sizes typically between 0.3 and 1.2 millimeters for fixed-bed column applications. Cationic resins dominate current volume due to established deployment in copper and nickel recovery circuits, while amphoteric resins represent the fastest-expanding category as dual-charge functionality addresses mixed-metal effluents from electroplating operations. Application-level margin pools concentrate in pharmaceutical manufacturing where validation requirements and batch consistency command premium pricing over commodity water treatment grades.
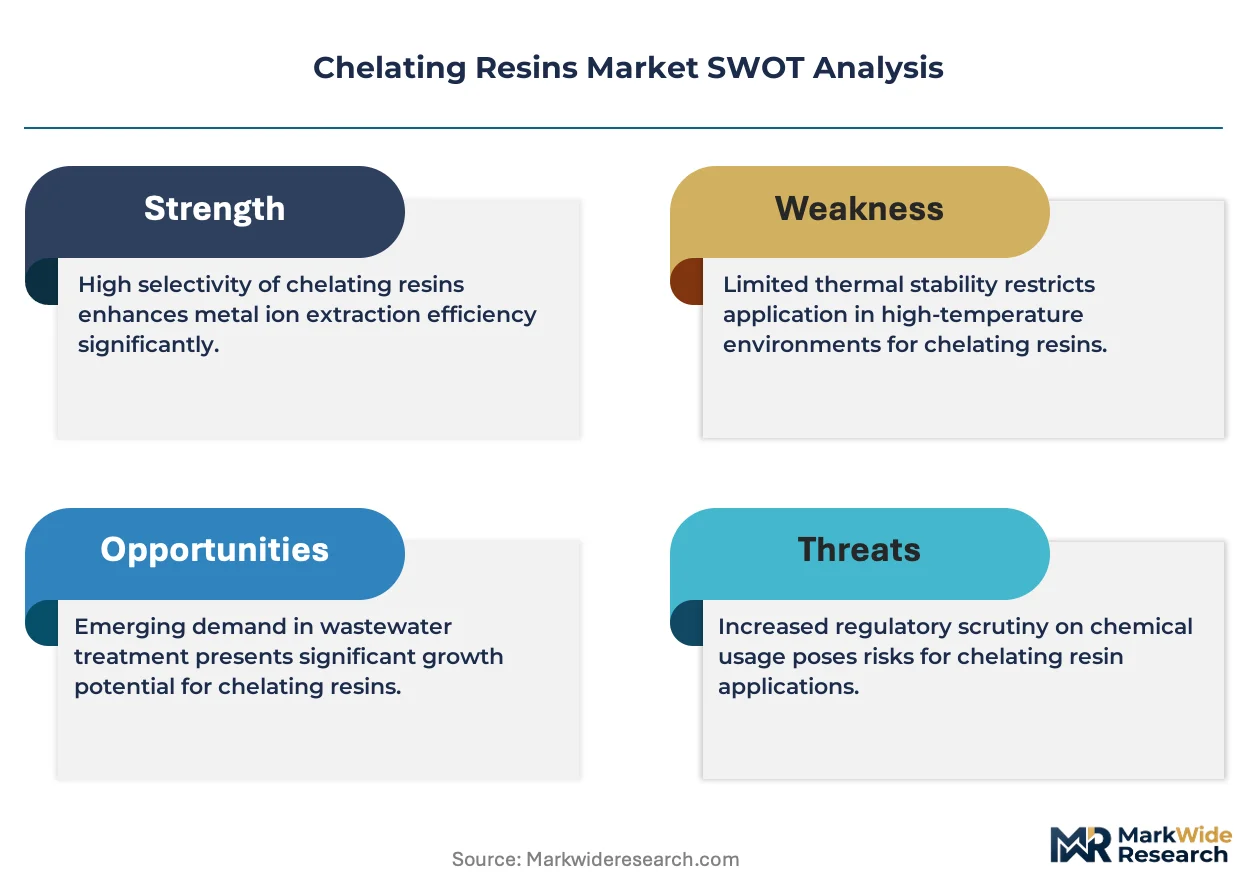
EPA effluent limitation guidelines and REACH Annex XVII restrictions on heavy metal discharges are compelling industrial facilities to install advanced ion-exchange polishing steps, directly expanding resin replacement cycles and system upgrade demand. China's MEE standards on wastewater reuse in chemical parks are creating parallel compliance-driven procurement in Asia. Stakeholders must monitor regulatory tightening timelines and resin regeneration chemistry costs to optimize between single-use and regenerable system economics.
Market Dynamics
EPA effluent limitation guidelines and REACH Annex XVII restrictions on heavy metal discharges are compressing replacement cycles for ion-exchange systems while forcing facilities toward higher-selectivity resin grades. This regulatory tightening is restructuring procurement patterns across chemical processing, electronics manufacturing, and pharmaceutical purification.
Growth Catalysts
- REACH Annex XVII heavy metal restrictions:European electroplating facilities must install advanced polishing steps, expanding demand for high-capacity cationic resins in Germany and Poland.
- Semiconductor wastewater complexity:Mixed-metal effluents from chip fabrication in Taiwan and South Korea are accelerating adoption of amphoteric resin systems with dual-charge functionality.
- China MEE wastewater reuse mandates:Chemical park operators in Jiangsu and Zhejiang provinces face compulsory treatment upgrades, driving bulk procurement of regenerable resin systems.
Market Restraints
- Styrene-divinylbenzene feedstock volatility:Crude oil price swings directly impact crosslinked polymer matrix costs, squeezing formulation margins for commodity-grade producers.
- Specialized polymer chemist scarcity:Talent concentration in Germany and Japan limits supply expansion for complex aminophosphonic acid functionalization processes.
- Regenerable system economics:Sulfuric acid and sodium hydroxide regeneration chemistry costs create payback period uncertainty against single-use disposable alternatives.
Strategic Opportunities
- Lithium brine purification:Argentina and Chile extraction projects require selective magnesium and calcium removal, opening demand for iminodiacetic acid resins in South American salar operations.
- Pharmaceutical validation premiums:FDA and EMA batch consistency requirements for active pharmaceutical ingredient manufacturing command pricing multiples over water treatment grades.
- Modular skid-mounted systems:Containerized ion-exchange units are displacing fixed-bed installations at remote mining sites in Australia and Canada.
Industry Challenges
- Bead geometry customization timelines:Pharmaceutical clients demand 12-18 month validation cycles for custom-engineered particle sizes, compressing commercialization windows.
- Legacy system integration friction:Brownfield chemical plants face piping and control system incompatibility when retrofitting advanced chelating resin columns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chelating Resins Market |
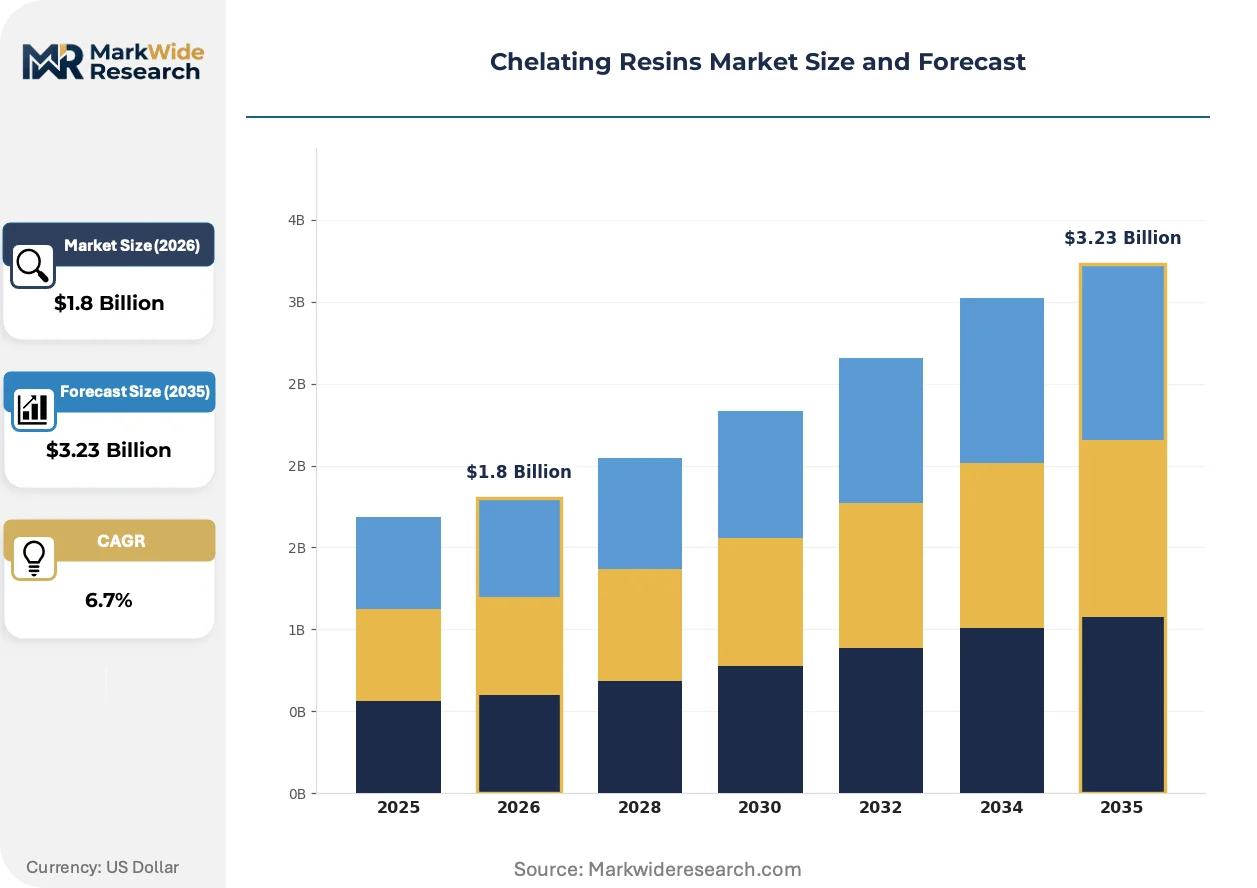
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cationic Resins, Anionic Resins, Neutral Resins, Amphoteric Resins Application: Water Treatment, Chemical Processing, Pharmaceutical Manufacturing, Food Industry End User: Industrial, Agricultural, Healthcare, Environmental Services Distribution Channel: Direct Sales, Online Retail, Distributors, Third-Party Vendors |
| Companies Covered | LANXESS, Mitsubishi Chemical Corporation, Purolite, DuPont, Dow, BASF, Sunresin New Materials Co. Ltd., ResinTech, Ion Exchange (India) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chelating Resins Market Emerging Trajectories
Formulation complexity is splitting the competitive landscape between integrated polymer producers and specialized functionalization houses. Three developments are restructuring how chelating resins are specified, procured, and deployed across end-use verticals.
Amphoteric resin technology is bifurcating the product mix as dual-charge functionality captures mixed-metal effluents from electroplating and semiconductor operations. Electronics manufacturers in Taiwan and South Korea are specifying these systems for simultaneous cation and anion removal. The technology is compressing demand for sequential single-resin trains while expanding total addressable volume in high-complexity wastewater streams.
REACH authorization requirements for chromium compounds are forcing electroplating facilities toward closed-loop water systems with resin-based metal recovery. German and Italian operators face 2026 compliance deadlines for hexavalent chromium reduction. The policy is accelerating replacement of conventional precipitation with ion-exchange polishing in automotive coating supply chains.
Specification authority is migrating from plant engineers to corporate sustainability officers with ESG reporting mandates. Large chemical processors in the Netherlands and Belgium now require resin suppliers to document carbon footprint and regeneration chemistry circularity. This shift is favoring European producers with verified supply chain transparency over lower-cost Asian imports in premium tender evaluations.
Chelating Resins Market Segmentation

Segmentation in the Chelating Resins Market reveals how resin chemistry, application intensity, and procurement channel economics split margin pools across radically different customer workflows. Manufacturers configure production lines and technical service teams around these divides.
Product Type:
Geographic demand spread varies sharply by resin chemistry — cationic grades serve domestic water treatment utilities while amphoteric formulations concentrate in export-led semiconductor clusters.
- Cationic Resins:Functionalized with sulfonic acid or iminodiacetic acid groups, these matrices preferentially bind positively charged metal ions in fixed-bed configurations. Demand concentrates in German municipal water utilities and Chinese chemical park operators facing MEE discharge mandates. EPA effluent guidelines in the United States compress replacement cycles for these established grades.
- Amphoteric Resins:Dual-charge functionality enables simultaneous cation and anion capture through combined acidic and basic ligand sites. Taiwanese and South Korean semiconductor fabs specify these for complex mixed-metal effluents from copper interconnect etching. REACH Annex XVII tightening on chromium compounds accelerates specification in European electroplating supply chains.
- Anionic Resins:Quaternary ammonium functionalization targets negatively charged metal complexes in mining and metallurgical streams.
- Neutral Resins:Non-ionic coordination chemistry serves specialized pharmaceutical extraction where charge-based selectivity would degrade active ingredients.
Cationic resins hold the largest share; momentum sits with amphoteric grades climbing the fastest on semiconductor wastewater complexity.
Application:
Cost tier differentiation separates commodity water treatment grades from validation-intensive pharmaceutical specifications.
- Water Treatment:Municipal and industrial effluent polishing consumes standardized bead geometries in high volume. German operators facing REACH deadlines and Chinese chemical parks under MEE reuse mandates drive procurement concentration. Regeneration chemistry economics determine system selection between reusable and single-use configurations.
- Pharmaceutical Manufacturing:FDA and EMA batch consistency requirements enforce 12-18 month validation cycles for custom-engineered particle sizes. Active pharmaceutical ingredient purification commands pricing multiples over commodity grades due to documentation burdens and contamination risk premiums.
- Chemical Processing:Electroplating and hydrometallurgy circuits deploy resins for metal recovery and closed-loop water systems.
- Food Industry:Decolorization and contaminant removal applications require food-grade certification and migration testing compliance.
Water treatment dominates volume; pharmaceutical manufacturing captures the steepest margin expansion trajectory.
End User:
Customer type fragmentation splits procurement authority between plant engineers and corporate sustainability officers with divergent technical priorities.
- Industrial:Electroplating facilities, semiconductor fabs, and chemical processors specify resins based on metal ion selectivity and regeneration efficiency. German automotive coating supply chains and Taiwanese chip manufacturers represent concentrated demand clusters with distinct technical specifications.
- Environmental Services:Remediation contractors and wastewater treatment operators prioritize total cost of ownership and regulatory compliance documentation. ESG reporting mandates in the Netherlands and Belgium now require carbon footprint transparency from resin suppliers.
- Agricultural:Soil remediation and water purification applications in water-stressed regions drive intermittent procurement.
- Healthcare:Dialysis water preparation and pharmaceutical manufacturing support require medical-grade certification.
Industrial users command the largest share; environmental services are expanding most quickly on regulatory tightening and outsourcing trends.
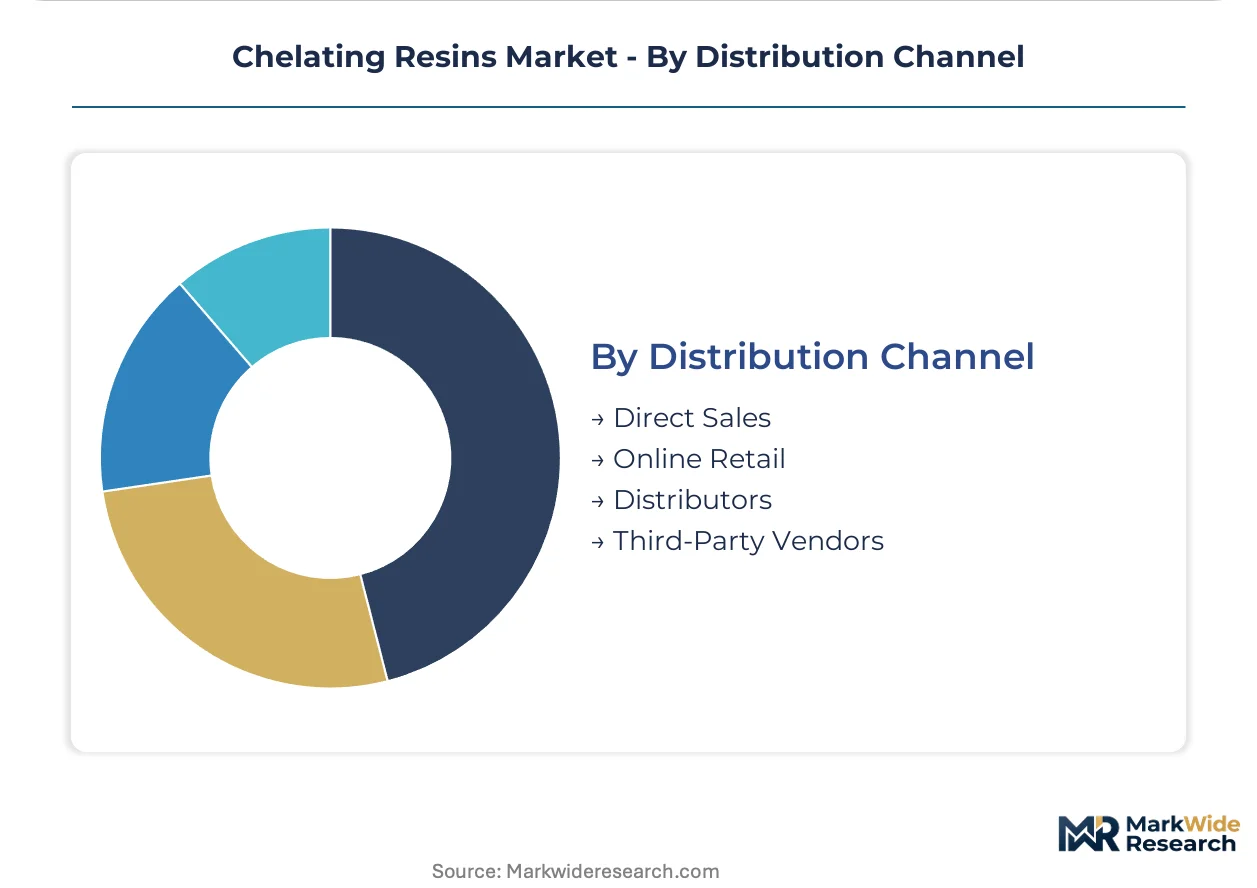
Distribution Channel:
Supply concentration favors direct relationships for complex specifications while distributors capture commoditized volume.
- Direct Sales:Technical resin specification for pharmaceutical and semiconductor applications requires application engineering support and custom formulation development. LANXESS and Mitsubishi Chemical Corporation maintain captive sales organizations for these high-touch segments.
- Distributors:Regional chemical distributors stock standardized grades for water treatment utilities and smaller industrial accounts with predictable replacement schedules.
- Online Retail:Catalog sales serve research laboratories and pilot-scale operations requiring small-batch procurement with rapid delivery.
- Third-Party Vendors:System integrators and engineering-procurement-construction firms bundle resins into turnkey ion-exchange installations.
Direct sales holds the largest share; distributor volume is gaining share fastest on chemical park standardization and modular system proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electroplating operators deploy chelating resins for hexavalent chromium recovery, while Chinese chemical parks favor regenerable systems for MEE-mandated wastewater reuse. This consumption-mix differential separates European closed-loop metal recovery from Asian bulk purification economics.
United States
EPA effluent limitation guidelines compress replacement cycles for municipal water utilities and automotive coating facilities. The agency's 2024 tightening on heavy metal discharge limits forces electroplating operators in Ohio and Michigan toward higher-selectivity resin grades. Semiconductor fabs in Arizona and Texas specify amphoteric formulations for copper interconnect wastewater.
Germany
REACH Annex XVII restrictions on chromium compounds accelerate ion-exchange polishing adoption in automotive supply chains. The 2026 compliance deadline for hexavalent chromium reduction concentrates procurement in Baden-Württemberg and North Rhine-Westphalia plating clusters. LANXESS leverages its captive resin production network to serve these operators directly.
China
MEE wastewater reuse mandates in Jiangsu and Zhejiang provinces drive bulk procurement of regenerable cationic systems. Chemical park operators in the Yangtze River Delta face compulsory treatment upgrades for discharge permits. Sunresin New Materials anchors domestic supply for these standardization-driven installations.
South Korea
Semiconductor wastewater complexity from Samsung and SK Hynix fabs accelerates amphoteric resin specification for mixed-metal effluents. The country's chip manufacturing concentration in Gyeonggi Province creates dense demand clusters for dual-charge functionality. MFDS pharmaceutical regulations parallel this technical intensity in biologics purification applications.
Japan
METI industrial water recycling targets push precision manufacturers toward advanced ion-exchange systems. Mitsubishi Chemical Corporation's captive manufacturing serves domestic electronics and pharmaceutical producers with high-selectivity grades. Osaka-based plating operations adopt closed-loop configurations ahead of 2025 regulatory milestones.
Chelating Resins Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with formulation complexity determining competitive position. German and Japanese conglomerates with captive polymer production networks command premium segments, while regional functionalization houses capture commoditized water treatment volume. Three archetypes define the field: integrated polymer producers, specialized resin functionalizers, and distributor-dependent regional suppliers. Capacity expansion in aminophosphonic acid grafting and strategic partnerships for pharmaceutical validation services represent the dominant competitive moves.
Within the integrated producer tier, LANXESS and Mitsubishi Chemical Corporation exemplify the polymer-backward model, leveraging in-house styrene-divinylbenzene matrix production to control formulation cost and supply security. Purolite occupies a position among the specialized functionalizers, with custom-engineered bead geometries serving validation-intensive pharmaceutical streams. Sunresin New Materials represents the scale-driven regional archetype, capturing standardized procurement in China's chemical park standardization wave.
| Leading Market Players |
|---|
| LANXESS |
| Mitsubishi Chemical Corporation |
| Purolite |
| DuPont |
| Dow |
| BASF |
| Sunresin New Materials Co. Ltd. |
| ResinTech |
| Ion Exchange (India) Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German automotive coating operators and integrated resin producers lock in styrene-divinylbenzene supply access while capping price volatility exposure across multi-year regeneration service agreements. These arrangements bind procurement volumes to REACH compliance timelines, converting regulatory deadlines into predictable revenue streams for polymer-backward suppliers.
Pricing Analysis
Contract-based long-term offtake structures dominate pharmaceutical and semiconductor applications, while spot purchasing persists for standardized water treatment grades. Price differentiation rests on FDA and EMA certification tiers versus commodity NSF/EN grades, with validation documentation commanding substantial premiums. Cost compression in commodity cationic resins is intensifying because Chinese chemical park standardization favors bulk tenders. Municipal utilities exhibit highest price sensitivity due to constrained capital budgets; pharmaceutical manufacturers show lowest sensitivity given contamination risk premiums.
Supply Chain Analysis
Inventory buffers for aminophosphonic acid functionalized resins stretch to sixteen weeks given specialized polymer chemist scarcity in Germany and Japan. Manufacturing concentrates in Germany, China, and Japan, with feedstock supply drawing from crude oil derivatives and specialized ligand chemical producers. Single-source vulnerability sits with iminodiacetic acid grafting capacity concentrated at three European functionalization houses. Distribution runs through direct technical sales for complex specifications and regional chemical distributors for standardized grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resin regeneration chemistry services and validation documentation support are expanding faster than bead sales, creating recurring revenue layers that decouple supplier economics from commodity polymer cycles. This service-attach dynamic favors incumbents with captive technical field organizations over pure manufacturing plays.
For Market Incumbents: Secure backward integration into aminophosphonic acid ligand production to defend formulation margins against feedstock volatility. Expand pharmaceutical validation service capacity in Switzerland and Singapore to capture EMA and MFDS documentation premiums. Counter Sunresin's chemical park standardization momentum through modular skid-mounted system partnerships with Australian and Canadian mining operators. For New Entrants and Emerging Players: FDA certification fast-track through 510(k) pathway alignment offers the most penetrable entry point for pharmaceutical-grade resin qualification. Target lithium brine purification in Argentina and Chile where iminodiacetic acid selectivity requirements outstrip established supplier presence. Lead with containerized pilot systems that displace fixed-bed installations at remote salar operations before scaling to full production contracts. For Investors and Strategic Acquirers: Capital is best deployed toward specialized functionalization houses with validated pharmaceutical customer relationships and proprietary bead geometry IP. The five-to-ten year viability window favors acquisition targets with demonstrated ESG reporting transparency for Netherlands and Belgium chemical processor procurement panels. Monitor REACH authorization timelines for chromium compounds as inflection indicator for European electroplating retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ligand Chemistry | Captive aminophosphonic acid supply secures formulation margins against petrochemical volatility. |
| Pharmaceutical Validation Service Expansion | FDA and EMA documentation capabilities capture premium pricing multiples over commodity grades. |
| Modular Skid-Mounted System Partnerships | Containerized units displace fixed-bed installations at remote Australian and Canadian mining sites. |
| ESG Reporting Transparency Certification | Verified carbon footprint documentation wins Dutch and Belgian chemical processor tenders. |
| Amphoteric Resin Capacity Addition | Dual-charge functionality serves Samsung and SK Hynix mixed-metal effluent complexity in Gyeonggi Province. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with resin plant managers, pharmaceutical procurement leads, wastewater treatment operators, and EPC contractors; and secondary validation through ECHA REACH filings, EPA effluent guideline updates, MEE wastewater reuse permits, and SEC 10-K disclosures from integrated polymer producers. Bottom-up demand modeling across end-use verticals triangulated against top-down supply capacity assessments from German and Japanese manufacturing clusters.
Across the analysis window, forecasts incorporate resin chemistry grade tier, application intensity, regional regulatory cluster, and procurement channel economics as segmentation dimensions. CAGRs derive from replacement cycle compression under EPA and REACH tightening, lithium brine project development pipelines, and semiconductor fab wastewater complexity trajectories. Styrene-divinylbenzene feedstock cost curves and regeneration chemistry economics anchor cost-side assumptions.
Decision-makers should treat outputs as directional under sustained regulatory tightening and petrochemical price stability assumptions; material deviation in crude oil volatility or REACH enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
Nylon 66 Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Fluorine Polymer Films Market