
 Circular Polymers Market | 2026-2036
Circular Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Circular Polymers Market Analysis
Modular packaging formats that separate barrier layers from structural polymers is recalibrating how converters specify circular feedstocks. BASF SE leverages its ChemCycling operations to anchor supply of chemically recycled polyamide for food-contact applications. LyondellBasell Industries Holdings B.V. sustains mechanical recycling dominance across Europe through its Quality Circular Polymers joint venture with Suez. Dow Inc. differentiates by integrating circular polyethylene into flexible packaging films at scale.
Circular polymers comprise post-consumer and post-industrial resins, bio-based monomers, and chemically depolymerized feedstocks reconstituted through pyrolysis, glycolysis, or enzymatic processes to meet virgin-equivalent melt-flow and mechanical-property specifications for reintroduction into durable goods and packaging. Bio-based polymers and compostable plastics occupy premium price tiers where brand-owners fund green premiums, while recycled polystyrene competes on cost parity in non-food packaging. Food-grade specifications command the tightest certification requirements and deepest margin pools across the grade taxonomy.
The EU Green Deal, REACH, and EFSA food-contact frameworks collectively mandate recycled-content minimums and restrict substances of very high concern in circular feedstocks, compressing timelines for certification and traceability infrastructure. Germany's national packaging regulator and France's extended producer responsibility authority enforce divergent sorting and recycling targets that fragment compliance costs across the value chain. Stakeholders must monitor how chemical recycling mass-balance accounting rules crystallize under EU-level standardization bodies, as these definitions will determine which technologies qualify for green finance and offtake premiums.
Market Dynamics
Automotive OEMs are embedding circularity mandates into tier-one supply contracts, forcing converters to certify recycled-content thresholds and traceability systems ahead of regulatory deadlines.
Growth Catalysts
- EU Green Deal thresholds:Extended producer responsibility frameworks in Germany and France mandate minimum recycled content in packaging, pulling chemical recycling capacity online near Ludwigshafen and Cologne.
- Automotive procurement mandates:Tier-one suppliers face contractual penalties for virgin plastic use in interior and under-hood components, redirecting specification teams toward mass-balanced polyamide and polypropylene grades.
- Pyrolysis scale-up:Commercial plants in the Netherlands and Spain are converting mixed plastic waste into naphtha-equivalent feedstocks that qualify for food-contact certification under EFSA mass-balance rules.
Market Restraints
- Feedstock cost volatility:Baled post-consumer PET and HDPE prices fluctuate with crude oil benchmarks and seasonal collection rates, squeezing mechanical recyclers' margin stability.
- Sorting infrastructure concentration:Germany and the Netherlands control over half of Europe's automated optical sorting capacity, creating bottleneck risk for converters in Southern and Eastern Europe.
- Chemical recycling energy intensity:Pyrolysis and gasification units require sustained natural gas or renewable hydrogen supply at prices that currently exceed mechanical reprocessing economics.
Strategic Opportunities
- Poland and Romania feedstock capture:Underdeveloped collection systems in these markets represent stranded plastic waste volumes that integrated operators can secure through long-term municipal contracts.
- Flexible packaging film specifications:Brand-owners in personal care and household products are relaxing color and clarity requirements to accept higher recycled content in non-food barrier films.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are compelling mid-size converters to purchase certified circular polymers with documented Scope 3 emissions reductions.
Industry Challenges
- EFSA food-contact certification timelines:Novel recycling processes face 18-24 month safety evaluation queues that delay commercial offtake agreements with dairy and beverage packagers.
- Mass-balance accounting disputes:Divergent national interpretations of free attribution versus fuel-exclusion methods are fragmenting audit standards across Germany, France, and Italy.
- Pyrolysis off-gas handling:Operators struggle to consistently valorize wax and char byproducts, complicating unit economics at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circular Polymers Market |
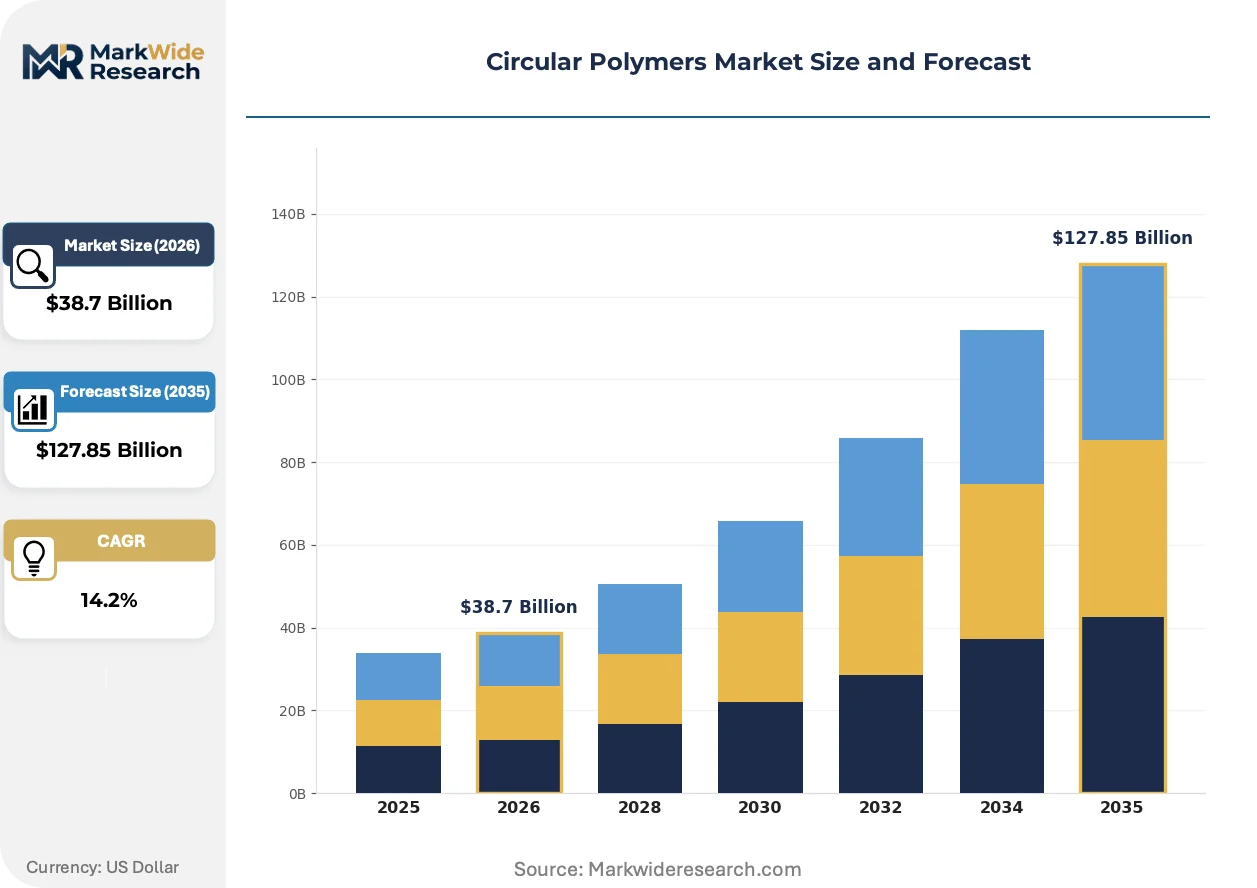
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled Polystyrene, Biodegradable Plastics, Bio-based Polymers, Compostable Plastics Application: Packaging, Automotive Parts, Textiles, Consumer Goods End Use Industry: Construction, Electronics, Agriculture, Healthcare Grade: Food Grade, Industrial Grade, Technical Grade, Engineering Grade |
| Companies Covered | BASF SE, LyondellBasell Industries Holdings B.V., SABIC, Dow Inc., Borealis AG, ExxonMobil Corporation, Veolia, Arkema S.A., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circular Polymers Market Emerging Trajectories
Technology convergence and regulatory precision are compressing the gap between laboratory-scale depolymerization and commercial-grade polymer output, reshaping how converters qualify feedstock suppliers.
Enzymatic depolymerization is unifying selective molecular breakdown with ambient-temperature processing, cutting energy inputs versus thermal routes. PET-focused biotech platforms in France and California are licensing to packaging converters seeking food-grade rPET without yellowing degradation. This technology is unifying quality thresholds across mechanical and chemical recycling streams, forcing certification bodies to rewrite purity protocols.
REACH restrictions on substances of very high concern are tightening impurity thresholds in recycled feedstocks, particularly for legacy additives like flame retardants and plasticizers. ECHA's 2024 update to annex XVII restricted substance lists is forcing recyclers to deploy advanced spectroscopic detection before pelletization. Food-contact applications face the steepest compliance cost escalation, diverting investment toward pharmaceutical and automotive-grade polymer recovery.
Brand-owner sustainability teams are consolidating supplier rosters around vertically integrated recyclers that control collection, sorting, and reprocessing. Unilever and Nestlé procurement departments in Germany and the UK now require single-source accountability for recycled-content claims, displacing fragmented broker networks. This concentration is most visible in rigid HDPE personal care packaging, where three-year framework agreements are replacing spot-market purchasing.
Circular Polymers Market Segmentation
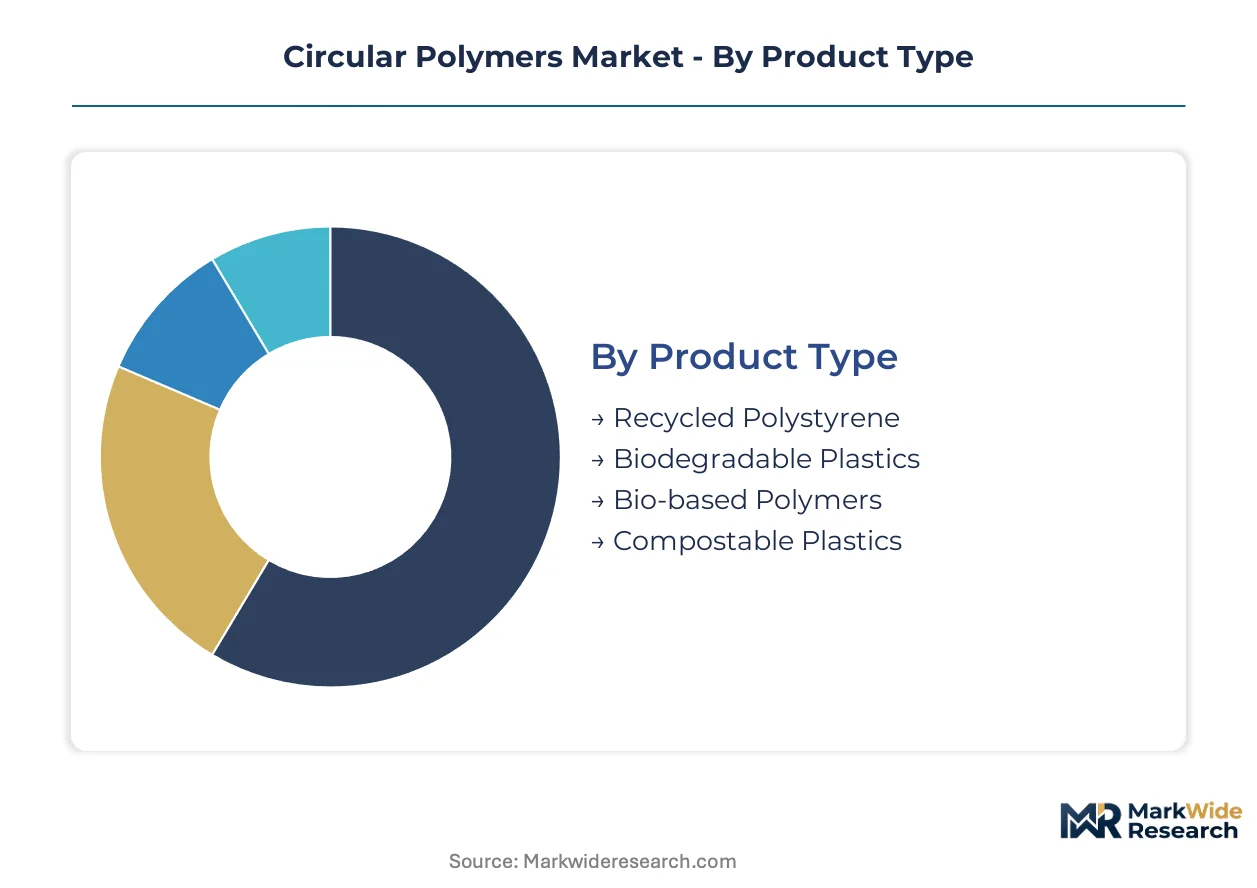
Converters specify circular feedstocks through multiple overlapping taxonomies that determine certification pathways and margin capture. Grade distinctions and application requirements fragment procurement strategies across mechanical recyclers, chemical recyclers, and bio-based producers.
Product Type:
Replacement cycles for virgin plastics accelerate where circular alternatives achieve cost parity or regulatory compliance thresholds.
- Recycled Polystyrene:Post-consumer and post-industrial streams reconstituted through mechanical reprocessing for non-food packaging. Demand concentrates in Germany's electronics packaging sector as EPR frameworks penalize virgin polystyrene use in protective foam applications.
- Bio-based Polymers:Monomers derived from agricultural feedstocks such as corn starch or sugarcane reconstituted into polyethylene and polypropylene equivalents. Brand-owners in personal care packaging fund green premiums where mass-balance certification supports Scope 3 reporting under CSRD mandates.
- Biodegradable Plastics:Materials engineered for microbial decomposition in industrial composting facilities.
- Compostable Plastics:Certified grades meeting EN 13432 standards for home and industrial composting.
Volume placements concentrate in recycled polystyrene; the faster expansion belongs to bio-based polymers.
Application:
Cost tier differentiation separates specification teams by compliance burden and performance requirements.
- Packaging:Flexible films, rigid containers, and protective formats incorporating recycled content or bio-based layers. Food-contact specifications command the deepest margin pools as EFSA certification timelines compress supplier rosters.
- Automotive Parts:Interior trim, under-hood components, and structural elements utilizing mass-balanced polyamide and polypropylene. OEMs embed circularity mandates into tier-one contracts that redirect procurement from virgin feedstocks.
- Textiles:Recycled polyester and polyamide fibers for apparel and industrial fabrics.
- Consumer Goods:Durable products including furniture, appliances, and electronics housings.
Packaging captures the largest volume placements; automotive parts are climbing the fastest as procurement mandates tighten.
End Use Industry:
Customer type segmentation separates price-sensitive commodity buyers from premium-grade specification teams.
- Construction:Insulation, piping, and structural composites utilizing recycled PVC and polyethylene. Demand in Germany concentrates where green building certification schemes reward recycled-content thresholds.
- Electronics:Housings, connectors, and internal components requiring flame-retardant specifications. REACH restrictions on legacy additives force recyclers toward pharmaceutical-grade recovery streams to avoid compliance costs.
- Agriculture:Mulch films, irrigation tubing, and greenhouse coverings.
- Healthcare:Medical packaging and disposable equipment with stringent purity requirements.
Construction dominates current volume; electronics represents the steepest expansion trajectory as OEMs face EPR penalties.
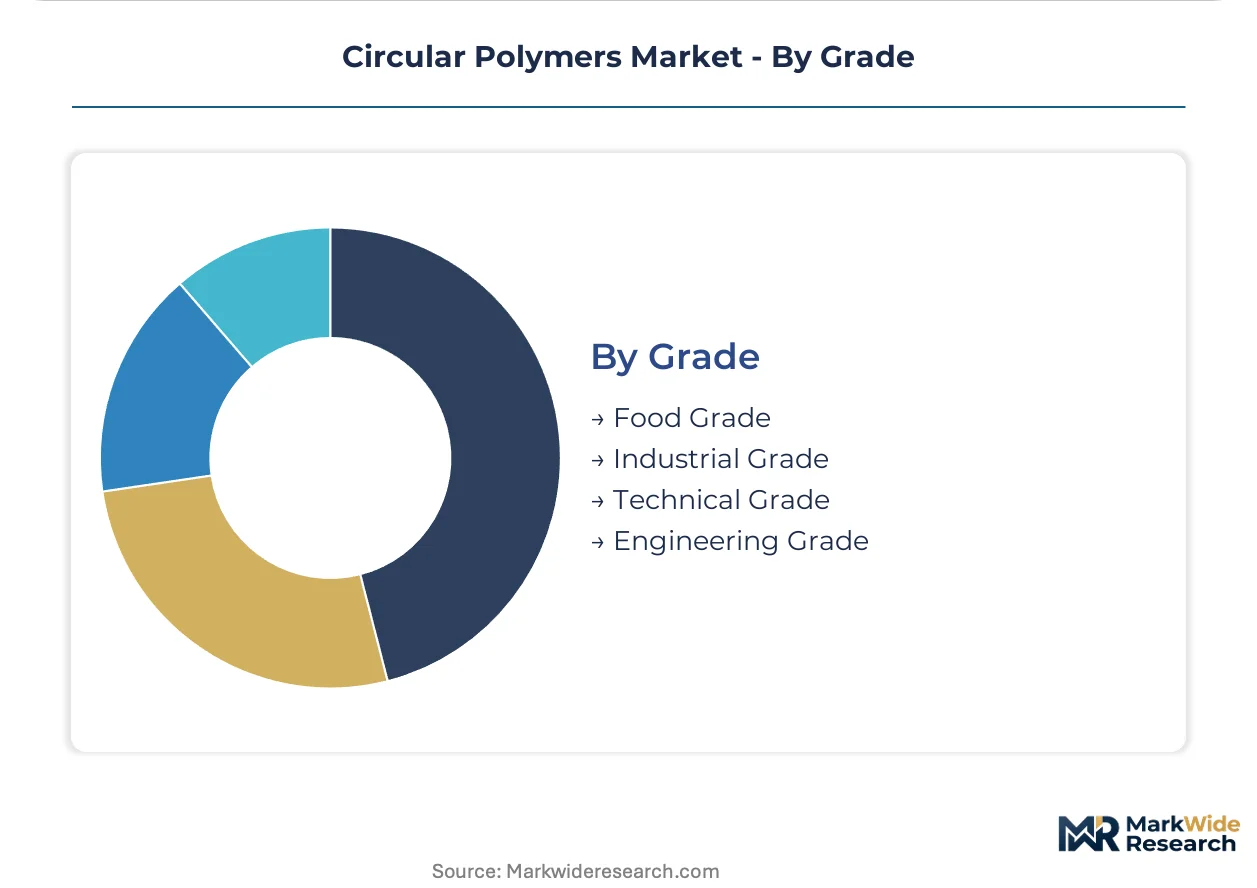
Grade:
Supply concentration in food-grade certification creates bottleneck conditions for converters seeking premium positioning.
- Food Grade:Recycled polymers meeting EFSA safety evaluations for direct food contact. Certification queues extending 18-24 months compress commercial timelines for dairy and beverage packagers.
- Engineering Grade:High-performance polymers with virgin-equivalent mechanical properties for automotive and industrial applications. Mass-balance accounting disputes fragment audit standards across Germany, France, and Italy.
- Industrial Grade:General-purpose recycled polymers for non-critical applications.
- Technical Grade:Specialized specifications for electronics and medical devices.
Food grade commands premium positioning; engineering grade is gaining share fastest as automotive procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes the largest volumes of circular polymers in Europe while chemical recycling capacity clusters near its industrial heartland. This production-consumption asymmetry shapes procurement patterns across the continent.
Germany
Automotive OEMs in Stuttgart and Munich enforce circularity mandates through tier-one contracts that specify mass-balanced polyamide for interior components. The national packaging regulator enforces extended producer responsibility thresholds that pull chemical recycling capacity online near Ludwigshafen. BASF SE anchors European supply through its ChemCycling operations, converting mixed plastic waste into food-contact certified feedstocks.
France
Personal care brand-owners in Paris fund green premiums for bio-based polyethylene packaging that supports CSRD disclosure requirements. The country's extended producer responsibility authority mandates minimum recycled content in household product containers. Enzymatic depolymerization startups in the Lyon biotech cluster license PET-focused platforms to converters seeking food-grade rPET without thermal degradation.
Netherlands
Commercial pyrolysis plants near Rotterdam convert mixed plastic waste into naphtha-equivalent feedstocks for flexible packaging films. EFSA mass-balance rules negotiated in Brussels determine which outputs qualify for food-contact certification. Automated optical sorting infrastructure concentrates near Amsterdam, creating bottleneck conditions for Southern European converters dependent on Dutch preprocessing capacity.
Spain
Underdeveloped collection systems in Mediterranean municipalities represent stranded plastic waste volumes that integrated operators target through long-term municipal contracts. REACH restrictions on legacy additives force recyclers toward pharmaceutical-grade recovery streams to avoid compliance cost escalation. Chemical recycling investments near Barcelona aim to capture feedstock from Iberian packaging waste streams.
United States
Eastman Chemical Company anchors domestic chemical recycling capacity through methanolysis operations targeting polyester waste from apparel and packaging. State-level extended producer responsibility frameworks in California and Maine diverge from federal EPA guidelines, fragmenting compliance costs for national brand-owners. Mechanical recyclers in the Southeast face feedstock cost volatility as baled post-consumer PET prices fluctuate with crude oil benchmarks.
Circular Polymers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology licensing, feedstock security, and certification infrastructure. The market structure concentrates around vertically integrated chemical majors that control pyrolysis capacity alongside mechanical recyclers dependent on municipal collection contracts. Three archetypes dominate: petrochemical incumbents retrofitting crackers for circular feedstocks, waste management operators backward integrating into polymer recovery, and biotech platforms licensing enzymatic depolymerization. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure offtake agreements ahead of regulatory deadlines.
Within the petrochemical incumbent tier, BASF SE and LyondellBasell Industries Holdings B.V. exemplify divergent circular strategies. BASF SE represents the integrated chemical recycling archetype through mass-balanced polyamide supply for automotive and food-contact applications. LyondellBasell Industries Holdings B.V. anchors mechanical recycling dominance through joint venture structures with waste management operators. Dow Inc. occupies a position between these models, integrating circular polyethylene into flexible packaging films at commercial scale. SABIC and Borealis AG sit within the Middle East-European nexus, leveraging feedstock cost positions to supply converters seeking virgin-equivalent circular polymers.
| Leading Market Players |
|---|
| BASF SE |
| LyondellBasell Industries Holdings B.V. |
| SABIC |
| Dow Inc. |
| Borealis AG |
| ExxonMobil Corporation |
| Veolia |
| Arkema S.A. |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Specialized chemical recycling engineers concentrated near Ludwigshafen and Rotterdam command wage premiums that compress margin spreads between food-grade and industrial-grade circular polymer tiers. Labor-cost differentials between these clusters and mechanical recycling operations in Southern Europe widen pricing stratification across certification levels.
Pricing Analysis
Margin tightening in food-grade tiers reflects EFSA certification queues extending eighteen to twenty-four months. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified food-contact grades from engineering-grade automotive specifications and industrial-grade non-food applications. Cost compression in mechanical recycling accelerates because baled post-consumer PET prices fluctuate with crude oil benchmarks. Brand-owners in personal care packaging exhibit lowest price sensitivity, while construction sector buyers drive hardest volume negotiations.
Supply Chain Analysis
Regional distribution centers near Amsterdam and Cologne operate hub-and-spoke patterns feeding converters across Western Europe. Supply concentrates in Germany, the Netherlands, and France for chemical recycling capacity, while mechanical reprocessing clusters in Spain and Italy. Feedstock security rests on baled post-consumer PET, mixed plastic waste, and bio-based monomers from agricultural processors. Single-source vulnerability pervades automated optical sorting infrastructure controlled by German and Dutch operators. Distribution runs through long-term offtake agreements with tier-one automotive suppliers and personal care brand-owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The circular polymers market functions as a cost-of-compliance story where REACH restrictions and EFSA food-contact frameworks erect barrier-to-entry moats favoring incumbents with certified infrastructure already deployed.
For Market Incumbents: Anchor mass-balance certification capacity ahead of EU-level standardization on chemical recycling accounting rules. Defensive consolidation around enzymatic depolymerization licensing protects against biotech platform disruption. Capacity addition in Poland and Romania secures stranded feedstock volumes before municipal contracts lock up. Certification investment in pharmaceutical-grade recovery streams sidesteps REACH additive restrictions.
For New Entrants and Emerging Players: Mid-size converters facing CSRD disclosure requirements represent the most accessible buyer archetype for certified circular polymers with documented Scope 3 emissions reductions. White-space targets concentrate in Southern European flexible packaging film specifications where brand-owners relax color and clarity requirements. Spain and Romania offer the most penetrable geographies for long-term municipal waste contracts. Go-to-market positioning as single-source accountability partners displaces fragmented broker networks.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated operators controlling collection, sorting, and reprocessing infrastructure. Long-term viability across the five-to-ten year horizon rests on feedstock security rather than technology differentiation. Acquisition targets should display captive municipal contracts and EFSA queue positions. Mass-balance accounting standardization at EU level signals inflection toward consolidated certification infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Captive municipal contracts in Poland and Romania secure stranded plastic waste volumes ahead of competitor lock-up. |
| EFSA Food-Contact Certification Investment | Queue positions for novel recycling processes compress commercial timelines with dairy and beverage packagers. |
| Joint Venture with Waste Management Operators | LyondellBasell's Quality Circular Polymers structure demonstrates mechanical recycling dominance through Suez partnership. |
| Enzymatic Depolymerization Licensing | French biotech platforms license PET-focused technologies to converters seeking food-grade rPET without thermal degradation. |
| Mass-Balance Accounting Infrastructure | Audit standard alignment across Germany, France, and Italy determines green finance qualification and offtake premiums. |
Methodological Framework
Independent corroboration across regulatory filings with ECHA and EFSA, trade association data from Cefic and Plastics Europe, and customs records tracking polymer waste flows underwrites the qualitative findings in this study. Primary interviews with chemical recycling plant managers, procurement leads at automotive OEMs, sustainability directors at personal care brand-owners, and technical R&D directors at packaging converters combined with secondary validation from REACH restriction updates, EU Green Deal implementation documents, and SEC 10-K disclosures from listed petrochemical majors. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth into feedstock availability expansion, regulatory mandate compliance, and technology cost reduction vectors. Segmentation dimensions modeled include product type tier, application grade, end-use industry vertical, and regional production hub cluster. CAGRs derive from iterative convergence between supply-side capacity buildout schedules and demand-side procurement mandate timelines. Industry-specific forecast inputs incorporate pyrolysis plant commissioning schedules and EFSA certification queue progression rates.
Revisions become necessary when mass-balance accounting standardization delays, feedstock cost volatility spikes, or pyrolysis off-gas valorization breakthroughs materialize. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology scale-up trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Polyamide 12 Market