
 Amla Extract Market | 2026-2036
Amla Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Amla Extract Market Analysis
Indian amla processing capacity is shifting from seasonal fruit collection toward year-round extraction infrastructure. Biomax Life Sciences Limited leverages its Hyderabad-based R&D campus to sustain phytochemical standardization across powder and oil grades. Arjuna Natural anchors supply contracts with European cosmetic houses through its Kerala extraction complex. Taiyo International competes on Japan-grade polyphenol consistency for nutraceutical clients.
Amla extract is a concentrated preparation derived from Emblica officinalis fruit, typically standardized to contain gallic acid, ellagic acid, and ascorbic acid at concentrations ranging from ten to forty percent by dry weight, produced through solvent extraction or supercritical CO2 methods for use as an antioxidant, anti-inflammatory, and hair-conditioning agent in formulated consumer products. Powder formulations dominate pharmaceutical and dietary supplement channels where dose precision and shelf stability command premium positioning, while oil extracts lead cosmetics applications due to lipid-soluble bioavailability in topical delivery systems. Liquid amla extract occupies the fastest-growing position within the form segmentation as beverage manufacturers integrate functional botanical shots into ready-to-drink wellness portfolios.
India's FSSAI mandates heavy metal and pesticide residue thresholds for herbal extracts destined for domestic consumption, while the EU REACH framework governs amla-derived cosmetic ingredient registration and safety dossier submission for European market access. The US FDA exercises oversight through dietary supplement Current Good Manufacturing Practice regulations that require identity testing and contamination controls for amla extract sold in capsule and tablet formats. Stakeholders must monitor evolving botanical novel food approvals under EFSA and adapt extraction protocols to meet divergent purity specifications across regulatory jurisdictions.
Market Dynamics
India's PLI scheme for herbal manufacturing is concentrating extraction capacity around Hyderabad and Kerala, pulling investment away from seasonal fruit trading toward standardized year-round processing infrastructure.
Growth Catalysts
- EU REACH cosmetic registration:German clean-label personal care brands are reformulating with plant-derived actives to meet ECHA-compliant safety standards, creating compliant procurement pipelines for Indian extractors.
- Supercritical CO2 extraction technology:This solvent-free method preserves heat-sensitive gallic acid and ellagic acid profiles, enabling premium positioning in nutraceutical capsules and antioxidant serums.
- Beverage functionalization:Ready-to-drink wellness shot manufacturers in Japan and South Korea are integrating liquid amla extract for polyphenol fortification, expanding addressable volume beyond traditional supplement channels.
Market Restraints
- Raw material seasonality:Emblica officinalis fruit harvests concentrate in autumn months across Uttar Pradesh and Madhya Pradesh, creating six-month supply gaps that force processors to maintain expensive cold-storage inventory.
- Heavy metal compliance costs:FSSAI-mandated arsenic and lead testing for domestic Indian consumption adds per-batch analytical expenses that squeeze margin at small-scale extraction units.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and ascorbyl palmitate remain cost-competitive in mass-market cosmetics, limiting amla extract penetration in economy-tier personal care formulations.
Strategic Opportunities
- Brazilian nutraceutical market:ANVISA's evolving botanical novel food approval pathway for Emblica officinalis extracts remains underexploited by Indian suppliers, creating first-mover positioning for phytochemical-standardized entrants.
- Supercritical-fluid extraction convergence with nanoencapsulation:Combining lipid-soluble amla oil extracts with liposomal delivery systems targets enhanced bioavailability claims in premium anti-aging skincare.
- Direct-to-practitioner distribution:Ayurvedic clinicians in Germany and Switzerland are bypassing traditional retail channels to source standardized extracts for personalized compound formulations.
Industry Challenges
- Phytochemical standardization expertise:Consistent gallic acid and ellagic acid quantification requires HPLC-capable analytical chemists, a skill set scarce outside Hyderabad and Kochi extraction clusters.
- Dual certification timelines:Simultaneous pursuit of USDA Organic and India Organic seals demands parallel audit tracks that extend market-readiness by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amla Extract Market |
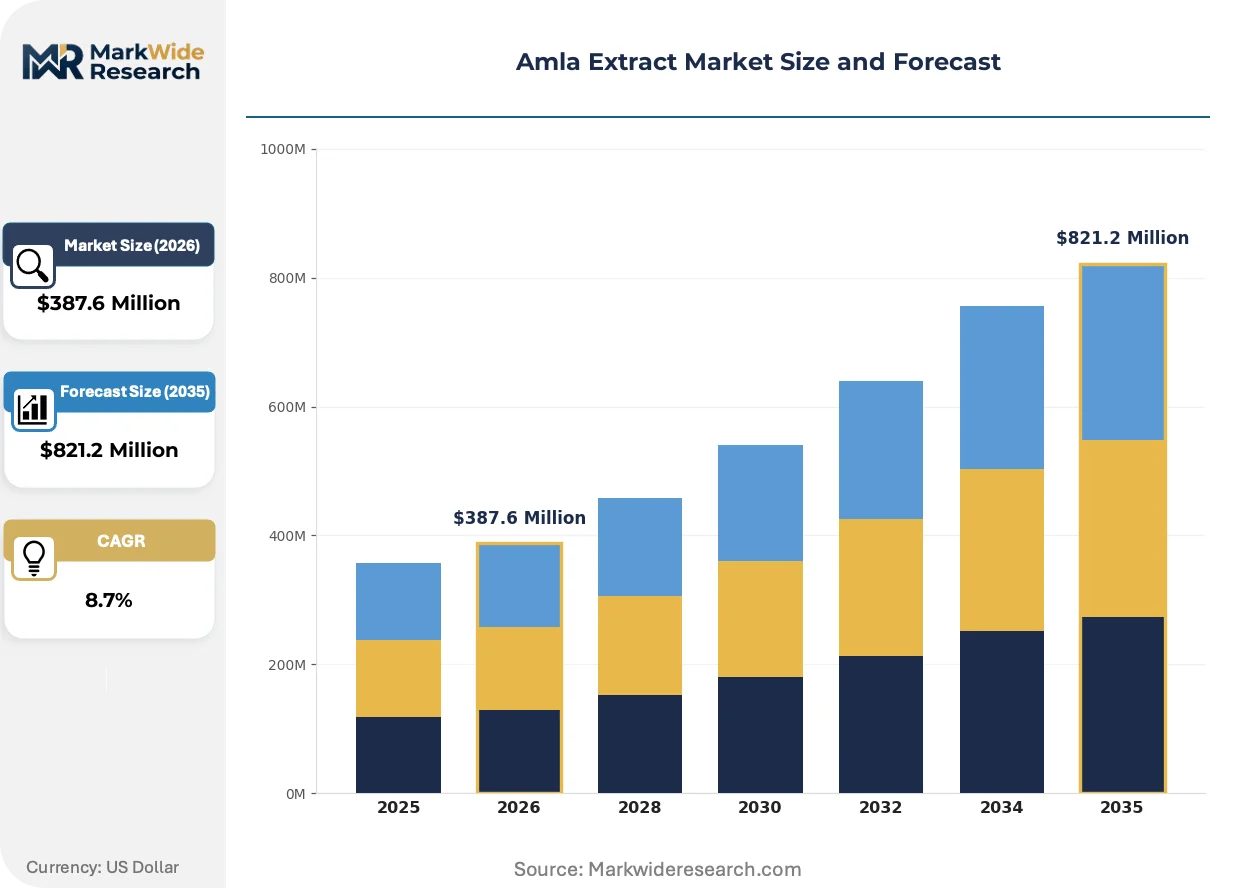
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil, Capsule, Juice Application: Cosmetics, Food & Beverages, Pharmaceuticals, Dietary Supplements Form: Liquid, Solid, Paste, Granules End User: Health-conscious Consumers, Herbal Product Manufacturers, Nutraceuticals, Cosmetic Companies |
| Companies Covered | Taiyo International, Biomax Life Sciences Limited, Arjuna Natural, Patanjali Ayurveda Limited, Ambe Phytoextracts Pvt. Ltd., RiSun Bio-Tech Inc, Archerchem, SYDLER, Herbeno Herbals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amla Extract Market Emerging Trajectories
Extraction technology and regulatory compliance frameworks are compressing the competitive set toward processors capable of certifiable phytochemical consistency across multiple jurisdictions.
Supercritical CO2 extraction is decentralizing capacity deployment across mid-scale Indian processors. This solvent-free technology enables on-site gallic acid preservation without volatile organic compound handling permits. Cosmetic formulators in France and Germany now specify CO2-derived grades for antioxidant serum lines. The method is decentralizing production geography away from centralized solvent-based facilities toward regional fruit-collection hubs.
EFSA's evolving botanical novel food approval requirements are reshaping extract dossier preparation standards. The framework demands comprehensive toxicological and compositional data for Emblica officinalis-derived ingredients entering European food supplements. Indian exporters to Germany and the Netherlands are restructuring analytical protocols to generate batch-to-batch stability documentation. Compliance investment is concentrating contract allocations toward extraction houses with in-house regulatory affairs capabilities.
Clean-label procurement patterns are fragmenting buyer-seller relationships in Western European cosmetics. German formulators now require chain-of-custody documentation from specific Indian districts rather than aggregated national sourcing. This specification shift is compressing supplier lists toward vertically integrated processors with direct farmer contracts. The behavioral change is most visible in Hamburg and Munich personal care manufacturing clusters.
Amla Extract Market Segmentation
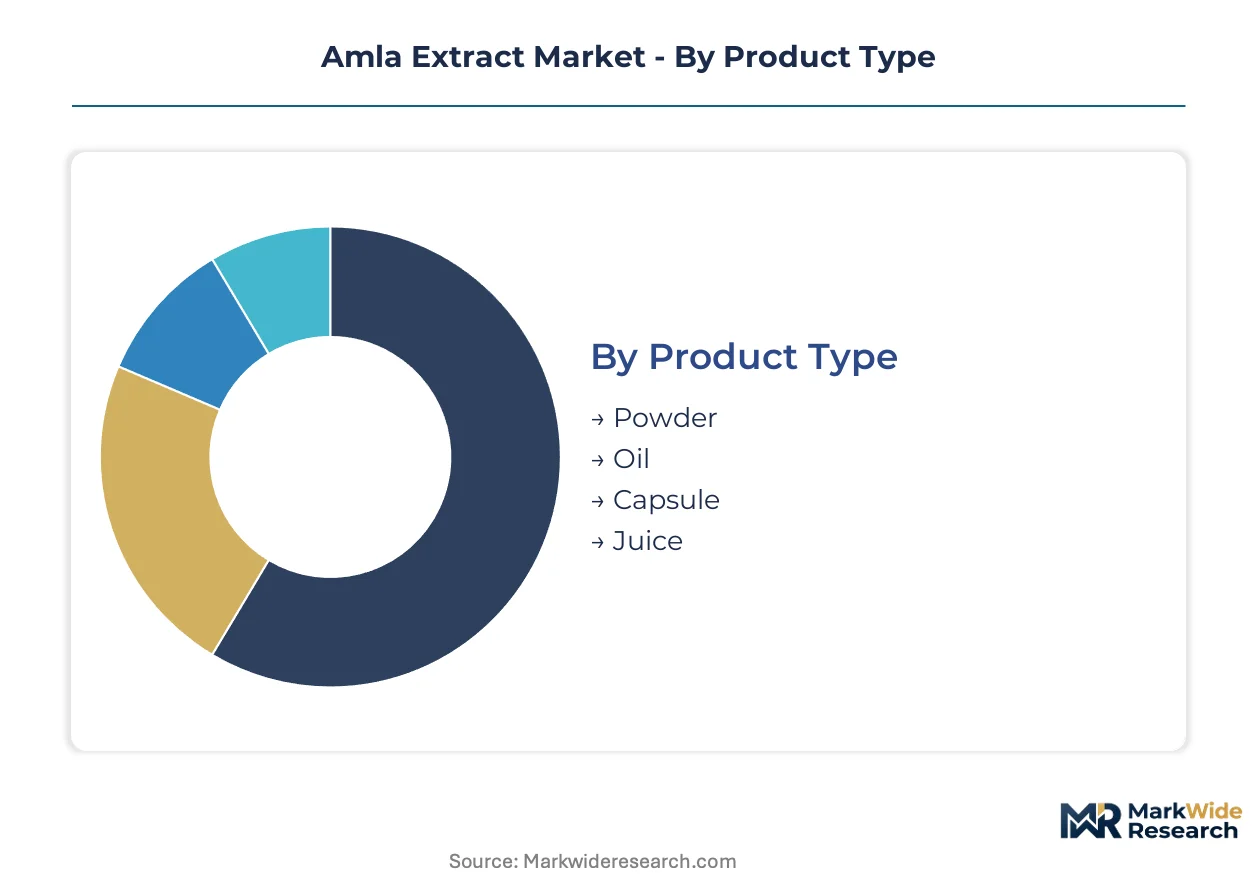
Amla extract segmentation reflects divergent technical requirements across oral delivery, topical application, and industrial formulation channels. Product form and end-use specifications create distinct margin tiers and certification demands that reshape supplier competitive positioning.
Product Type:
Powder formats command volume leadership in pharmaceutical and supplement channels, while oil extracts capture premium positioning in cosmetics. The split between commodity-scale powder production and specialized lipid-soluble extraction defines supplier capability requirements.
- Powder:Standardized to ten-to-forty percent gallic acid and ellagic acid by dry weight through spray-drying or freeze-drying protocols. Demand concentrates in German and Swiss dietary supplement manufacturing where dose precision and shelf stability justify premium procurement contracts.
- Oil:Lipid-soluble fractions produced via cold-pressing or supercritical CO2 methods for enhanced topical bioavailability. Cosmetic formulators in France specify CO2-derived grades for antioxidant serum lines requiring heat-sensitive phytochemical preservation.
- Capsule:Pre-measured gelatin or vegetable-based delivery systems targeting convenience-driven health-conscious consumers in Japan and South Korea.
- Juice:Aqueous preparations for beverage functionalization, gaining traction in ready-to-drink wellness shot portfolios across East Asian markets.
Mature deployment sits with Powder. Newer deployment is concentrated in Oil as supercritical extraction capacity expands beyond traditional solvent-based infrastructure.
Application:
End-use channels impose divergent purity thresholds and documentation requirements that fragment supplier competitive sets across regulated and discretionary purchase environments.
- Cosmetics:Antioxidant serums, hair-conditioning treatments, and anti-aging formulations requiring ECHA-compliant safety dossiers for EU REACH registration. German clean-label brands in Hamburg and Munich clusters drive compliant procurement pipeline development.
- Food & Beverages:Functional botanical shots and polyphenol-fortified ready-to-drink products. Japanese and South Korean beverage manufacturers represent the steepest expansion trajectory for liquid extract integration.
- Pharmaceuticals:Standardized extracts for Ayurvedic compound formulations and clinical applications requiring CDSCO or equivalent national regulator approval.
- Dietary Supplements:Capsule and tablet formats governed by FDA Current Good Manufacturing Practice regulations for identity testing and contamination controls in US-bound shipments.
Cosmetics commands the highest certification burden. Food & Beverages is climbing the fastest as beverage functionalization transcends traditional supplement boundaries.
Form:
Physical state determines handling infrastructure, stability profiles, and integration complexity across manufacturing workflows.
- Liquid:Aqueous or hydroalcoholic preparations enabling rapid dispersion in beverage matrices and topical emulsions. Korean and Japanese functional drink manufacturers prioritize liquid formats for manufacturing line compatibility.
- Solid:Compressed tablets or dried blocks for traditional medicine practitioners and compound pharmacies in Germany and Switzerland.
- Paste:Semi-concentrated preparations for Ayurvedic therapeutic applications and specialized cosmetic bases.
- Granules:Free-flowing intermediate formats bridging powder and liquid processing requirements in contract manufacturing environments.
Solid formats dominate established supplement channels. Liquid deployment is expanding most quickly through beverage functionalization partnerships.
End User:
Buyer sophistication and procurement scale create tiered supplier relationships from direct-to-practitioner channels to multinational manufacturing contracts.
- Health-conscious Consumers:Direct-to-consumer and retail-facing purchasers prioritizing organic certification and traceability documentation. German and Swiss Ayurvedic clinicians increasingly bypass traditional retail to source standardized extracts for personalized formulations.
- Herbal Product Manufacturers:Mid-scale processors requiring consistent raw material supply for traditional medicine production lines.
- Nutraceuticals:Science-backed supplement houses demanding batch-to-batch phytochemical standardization with HPLC verification protocols.
- Cosmetic Companies:Formulation houses in France and Germany specifying chain-of-custody documentation from named Indian districts rather than aggregated national sourcing.
Herbal Product Manufacturers represent established volume relationships. Cosmetic Companies are gaining share fastest as clean-label procurement fragments buyer-seller contracting patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uttar Pradesh and Madhya Pradesh orchards supply the raw fruit that Indian processors convert into standardized extracts for export markets. Seasonal harvests concentrate in autumn months, forcing cold-storage investment to bridge supply gaps. Processing capacity clusters around Hyderabad and Kerala, where extraction infrastructure is expanding under government incentive programs.
Germany
Clean-label personal care brands in Hamburg and Munich drive compliant procurement pipelines for Indian extractors. ECHA's REACH framework governs cosmetic ingredient registration and safety dossier submission. Formulators specify chain-of-custody documentation from named Indian districts rather than aggregated national sourcing.
India
FSSAI mandates heavy metal and pesticide residue thresholds for domestic herbal extract consumption. The PLI scheme for herbal and nutraceutical manufacturing redirects investment toward standardized botanical extraction facilities. Processing capacity concentrates in Hyderabad and Kerala extraction complexes.
Japan
Beverage manufacturers integrate liquid amla extract into ready-to-drink wellness portfolios for polyphenol fortification. METI standards govern functional food ingredient specifications. Tokyo-based nutraceutical houses demand Japan-grade polyphenol consistency from suppliers.
South Korea
Functional drink manufacturers prioritize liquid formats for manufacturing line compatibility. MFDS regulates health functional food claims and novel botanical approvals. Seoul-area beverage formulators represent the steepest expansion trajectory for liquid extract integration.
United States
Dietary supplement manufacturers source amla extract for capsule and tablet formats. FDA Current Good Manufacturing Practice regulations require identity testing and contamination controls. California and New York-based wellness brands drive procurement for antioxidant positioning.
Amla Extract Market Vendor Landscape
Global majors compete with regional champions across phytochemical standardization capabilities and regulatory compliance breadth. The supplier base organizes into tiered clusters: integrated processors with farmer-direct contracts, mid-scale extraction houses with R&D campuses, and commodity traders lacking analytical infrastructure. Dominant competitive moves include backward integration into orchard management and technology licensing for supercritical CO2 deployment.
Within the integrated processing tier, Biomax Life Sciences Limited and Arjuna Natural exemplify capacity concentration around Hyderabad and Kerala extraction complexes. Taiyo International occupies a position emphasizing polyphenol consistency for Japanese nutraceutical specifications. These three entities anchor the competitive set visible in procurement pipelines serving German cosmetic houses and East Asian beverage manufacturers.
| Leading Market Players |
|---|
| Taiyo International |
| Biomax Life Sciences Limited |
| Arjuna Natural |
| Patanjali Ayurveda Limited |
| Ambe Phytoextracts Pvt. Ltd. |
| RiSun Bio-Tech Inc |
| Archerchem |
| SYDLER |
| Herbeno Herbals |
| Others |
Supply Flow & Price Mechanics
German cosmetic formulators in Hamburg and Munich clusters anchor procurement demand, creating contract-based pricing power for extraction houses with ECHA-compliant safety dossiers and direct farmer contracts.
Pricing Analysis
Certification-bundling separates quoted prices, with CO2-derived grades including batch-to-batch HPLC verification while solvent-extracted variants leave testing costs unbundled. Three-tier pricing structure across premium, standard, and economy levels tracks phytochemical standardization precision and organic seal status. Cost compression in economy-tier powder grades is intensifying because synthetic antioxidant substitutes retain cost advantage in mass-market cosmetics. Nutraceutical manufacturers in Japan exhibit lowest price sensitivity due to polyphenol consistency requirements, while commodity traders in domestic Indian channels face acute margin pressure from FSSAI-mandated heavy metal testing expenses.
Supply Chain Analysis
Single-source vulnerability sits with autumn-harvested raw fruit from Uttar Pradesh and Madhya Pradesh orchards, where six-month supply gaps force processors into expensive cold-storage inventory positions. Manufacturing draws from extraction complexes in Hyderabad and Kerala, with equipment and analytical chemist talent feeding from these regional clusters. Tariff exposure runs through EU REACH registration timelines that extend market-readiness for new entrants. Distribution runs through vertically integrated processors with direct farmer contracts, bypassing fragmented seasonal fruit traders lacking HPLC-capable quality verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction is displacing legacy solvent-based infrastructure, compressing competitive advantage toward processors with solvent-free technology deployment and in-house regulatory affairs capabilities.
For Market Incumbents: Deepen backward integration into orchard management across Uttar Pradesh and Madhya Pradesh to secure captive raw material supply against seasonal volatility. Expand supercritical CO2 capacity in Kerala extraction complexes to defend premium positioning as synthetic antioxidant substitutes threaten economy-tier powder margins. Prioritize dual USDA Organic and India Organic certification investment to extend contract duration with German clean-label cosmetic houses. For New Entrants and Emerging Players: Begin with Brazil's underexploited ANVISA botanical novel food approval pathway for Emblica officinalis extracts, where phytochemical-standardized entrants face limited incumbent competition. Target South Korean beverage functionalization partnerships for liquid extract integration, leveraging manufacturing line compatibility priorities in Seoul-area formulators. Pursue direct-to-practitioner distribution channels in Germany and Switzerland, bypassing traditional retail markups to serve Ayurvedic clinicians with personalized compound formulation demand. For Investors and Strategic Acquirers: The window for entry favors extraction houses with in-house HPLC analytical capabilities and existing EFSA dossier preparation infrastructure. Long-term viability centers on processors capable of certifiable phytochemical consistency across multiple regulatory jurisdictions, with defensible positioning emerging from regulatory affairs expertise rather than commodity scale. Monitor EFSA botanical novel food approval timelines as the inflection signal for European food supplement channel expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables solvent-free gallic acid preservation for French and German cosmetic serum specifications. |
| Backward Integration into Orchard Management | Secures captive Emblica officinalis supply from Uttar Pradesh and Madhya Pradesh harvest zones. |
| Dual Organic Certification Investment | Extends contract duration with Hamburg and Munich clean-label personal care manufacturers. |
| Regulatory Affairs Capability Buildout | Accelerates EU REACH dossier preparation and EFSA novel food approval pathway navigation. |
| Liposomal Nanoencapsulation Partnership | Targets enhanced bioavailability claims in premium anti-aging skincare formulations. |
Methodological Framework
Multi-period observation of extraction technology deployment, PLI scheme investment flows, and EFSA regulatory timeline progression anchored the trend analysis, supplemented by interviews with extraction plant managers, cosmetic formulator procurement leads, Ayurvedic clinician practitioners, regulatory affairs directors at nutraceutical houses, and FSSAI compliance officers. Secondary validation drew from CDSCO filings, ECHA registration databases, FSSAI notification records, and India PLI scheme disbursement disclosures. Bottom-up volume modeling across powder, oil, and liquid form factors triangulated against top-down value estimates from contract manufacturing agreements and import-export customs records.
Input-output matrices mapped phytochemical standardization requirements to end-use certification demands across cosmetics, food and beverages, pharmaceuticals, and dietary supplements. Segmentation dimensions spanned product type, application channel, physical form, and end-user sophistication tier. CAGRs were derived from regression analysis of historical capacity expansion and procurement contract growth rates. Forecast inputs incorporated supercritical CO2 technology adoption curves, EFSA novel food approval probability assessments, and German clean-label procurement pattern shifts.
Underlying measurement precision varies by segment; liquid extract beverage integration carries tighter precision than traditional Ayurvedic practitioner channels due to disclosed manufacturing partnerships. Forecasts reflect assumptions around regulatory timeline stability, harvest yield consistency, and technology cost reduction trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Herb and Spice Extracts Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Organic Extracts Market
Extracts
Eucommia Extract Market
Extracts
Polygonum Cuspidatum Extract Market
Extracts
Tagetes Oil Market
Extracts
Pectinase Market
Extracts
Yucca Extract Material Market
Extracts
Palmarosa Oil Market
Extracts
Cochineal Extract Market
Extracts
Cassia Extract Market
Extracts
Irish Moss Market
Extracts
Plum Extract Market
Extracts
Flower Extract Market
Extracts
Nootkatone Market
Extracts
Herba Houttuyniae Extract Market