
 PEKK Market | 2026-2036
PEKK Market Size, Share, and Industry Trends Forecast 2026-2036
PEKK Market Analytics
Advanced thermoplastic composite manufacturing is reshaping how aerospace and medical device producers specify structural polymers. Solvay leverages its European polymer heritage to sustain leadership in aviation-grade PEKK formulations. Arkema SA anchors its position through backward integration into ketone monomer supply. Victrex plc competes by dominating the high-purity medical implant segment with stringent biocompatibility protocols.
Polyetherketoneketone (PEKK) is a semi-crystalline high-performance thermoplastic belonging to the polyaryletherketone (PAEK) family, characterized by a ketone-to-ether ratio of 2:1 and a glass transition temperature near 162°C, engineered for load-bearing applications requiring chemical resistance and flame retardancy. The material serves critical functions in aerospace structural brackets, spinal implant cages, and oilfield components where metal replacement reduces weight without sacrificing mechanical integrity. Aerospace applications lead current volume consumption as OEMs qualify PEKK for primary flight structures, while medical-grade resin commands premium positioning due to multi-year FDA 510(k) validation timelines. Powder formulations for laser sintering represent the fastest-growing form factor as additive manufacturing protocols mature for patient-specific orthopedic devices.
FDA enforces biocompatibility ISO 10993 standards for implantable PEKK devices, while EMA aligns with MDR requirements that extend clinical evidence obligations for permanent polymer implants. REACH restricts certain aromatic amine precursors, compelling European producers to certify alternative synthesis pathways. China's NMPA accelerates medical device registration reforms that streamline PEKK implant approvals for domestic manufacturers. Stakeholders must monitor evolving aviation certification timelines from FAA and EASA as thermoplastic primary structures transition from demonstration programs to serial production commitments.
Market Dynamics
PEKK's market trajectory hinges on aerospace OEMs transitioning thermoplastic composites from demonstration airframes to serial production, a shift that compresses qualification timelines while amplifying resin purity requirements across medical and aviation supply chains.
Growth Catalysts
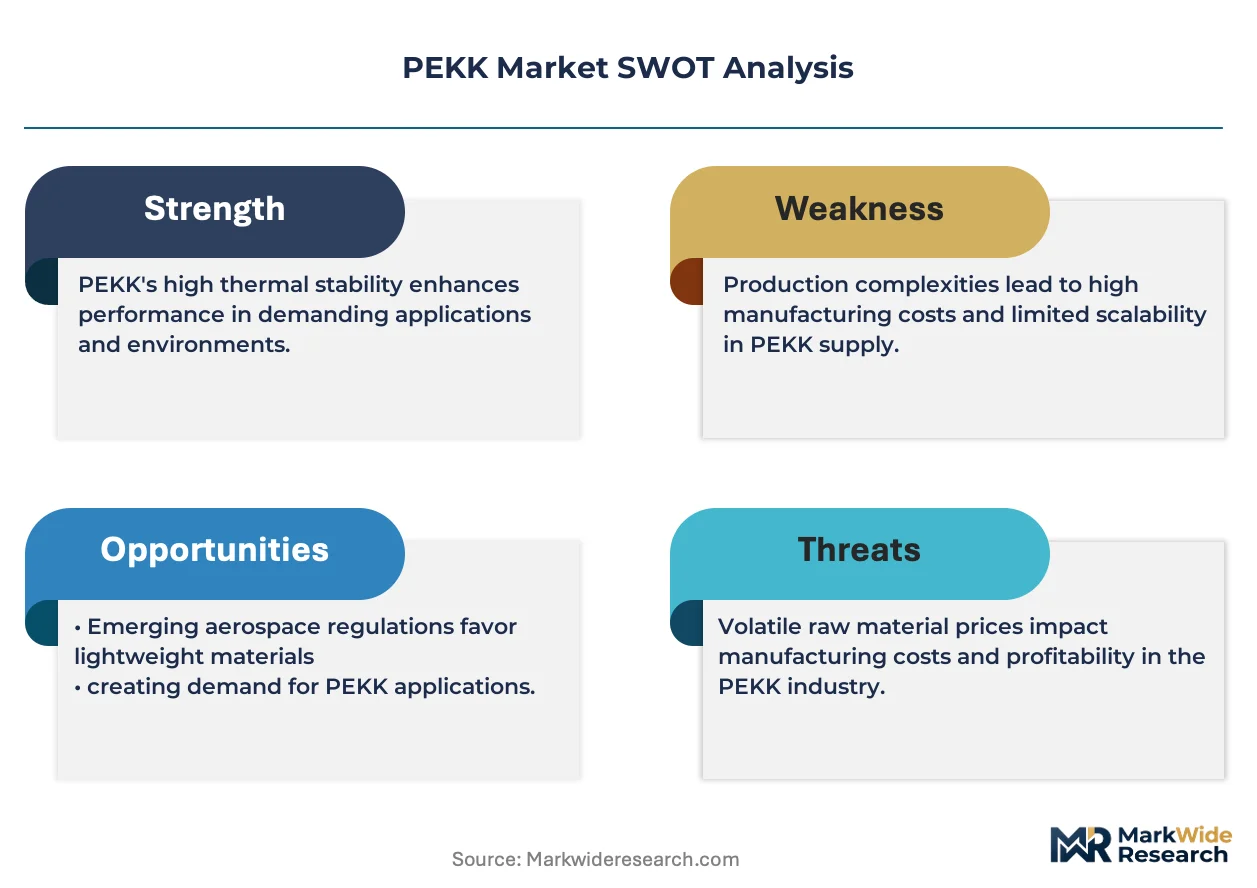
- REACH chemical compliance frameworks:European tightening of aromatic amine precursor restrictions accelerates certified alternative synthesis pathways, advantaging producers with established European polymer heritage.
- Aviation thermoplastic qualification:FAA and EASA certification progress for primary flight structures pulls volume from metal and thermoset replacement programs.
- China's aviation manufacturing clusters:Domestic airframe production expansion concentrates demand for high-performance resin formulations near Shanghai and Xi'an assembly facilities.
Market Restraints
- Fluorinated monomer cost volatility:Ketone feedstock price swings compress margin predictability for non-integrated compounders lacking captive monomer supply.
- European supply concentration:REACH-compliant production capacity clusters in Germany and Belgium, creating geographic single-source risk for qualified aerospace resin.
- Thermoset epoxy substitution:Qualified carbon-epoxy prepregs retain cost advantage in secondary structures where temperature requirements permit.
Strategic Opportunities
- Patient-specific orthopedic devices:Laser sintering powder formulations for additive manufacturing open premium pricing in spinal and cranial implant segments.
- India's medical device PLI scheme:Domestic manufacturing incentives attract PEKK compounders to establish implant-grade resin production for NMPA-aligned export markets.
- Digital twin convergence with additive protocols:Topology optimization software integration with powder bed fusion enables mass-customized surgical guides and fixation plates.
Industry Challenges
- FDA 510(k) validation timelines:Multi-year biocompatibility protocols under ISO 10993 standards delay revenue recognition for new medical-grade resin entrants.
- High-purity polymer processing expertise:Scarce technicians capable of maintaining medical-grade contamination controls limit qualified production scale-up.
- Aviation certification synchronization:Misaligned FAA and EASA timeline expectations create inventory risk for producers holding dual-qualified resin stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PEKK Market |
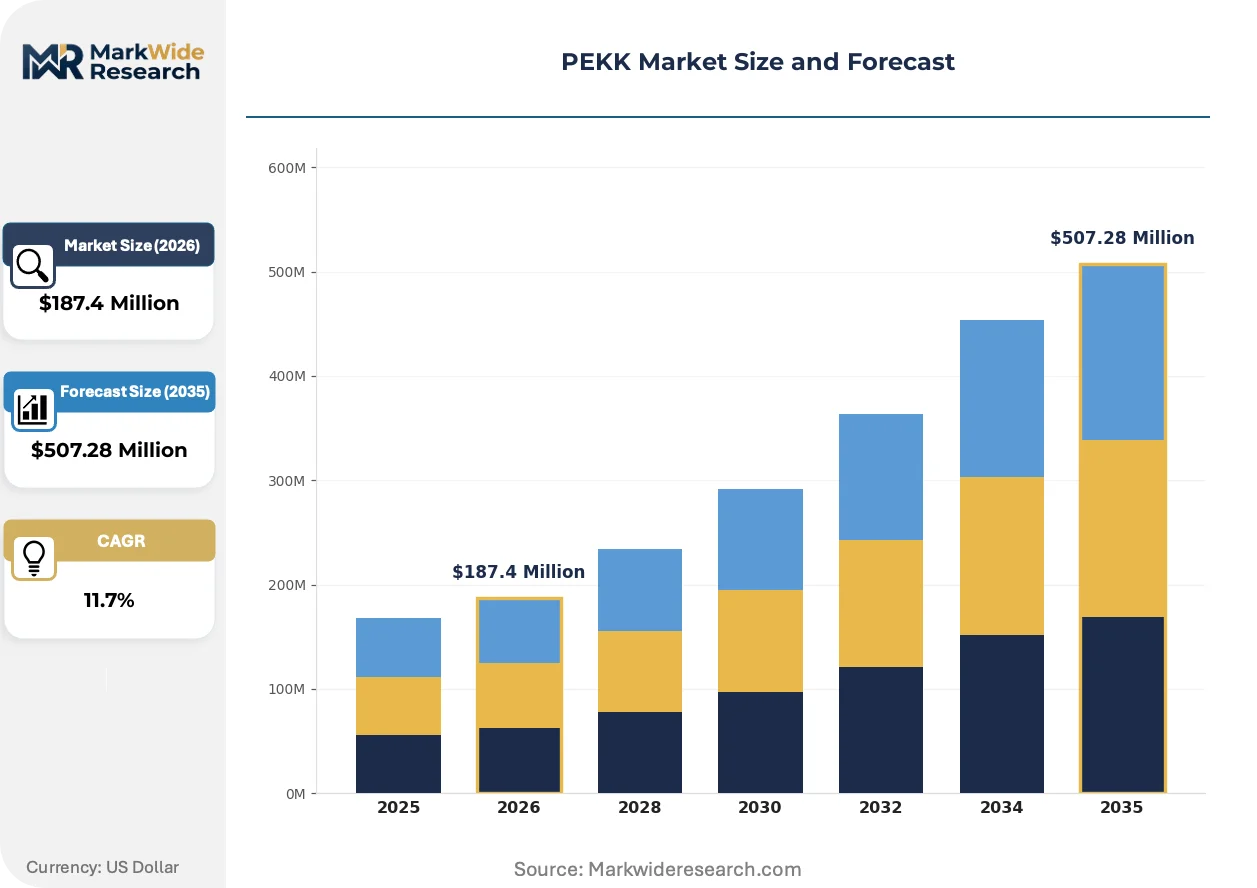
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Resin, Sheets Application: Aerospace, Automotive, Medical, Industrial End User: Manufacturers, OEMs, Research Institutions, Distributors Form: Extruded, Molded, Coated, 3D Printed |
| Companies Covered | Shandong Kaisheng New Materials Co., Ltd., Evonik Industries AG, Solvay, Ensinger, Polymics, Ltd., Arkema SA, Victrex plc, RTP Company, Inc., Panjin Zhongrun High Performance Polymers Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PEKK Market Evolving Landscape
Material science advances and regulatory harmonization efforts are compressing the gap between laboratory formulation and qualified aerospace production, while digital manufacturing protocols reshape how implantable devices reach surgical markets.
In-situ polymerization of low-melt-viscosity PEKK variants is rendering obsolete conventional high-temperature compression molding for complex aerospace brackets. Tier-one suppliers at Airbus and Boeing qualification programs adopt these modified rheology grades to enable automated fiber placement at reduced processing temperatures. The shift collapses cycle times for thermoplastic composite aerostructures while demanding reformulated catalyst packages from resin producers.
EU Green Deal chemical transition mandates force European PEKK manufacturers to document carbon footprint across ketone monomer supply chains. ECHA reporting requirements extend to imported precursors, compelling Asian suppliers to adopt mass-balance certification or lose access to German and French aerospace compounders. The regulatory pressure accelerates investment in bio-based diphenyl ether feedstock development.
Hospital procurement consortia now specify implantable polymer traceability from resin pellet to sterilized device. Group purchasing organizations in Germany and the United States displace distributor intermediaries with direct compounder contracts that bundle material certification with lot-level blockchain documentation. The behavioral shift concentrates buying power among three national procurement networks serving academic medical centers.
PEKK Market Segmentation
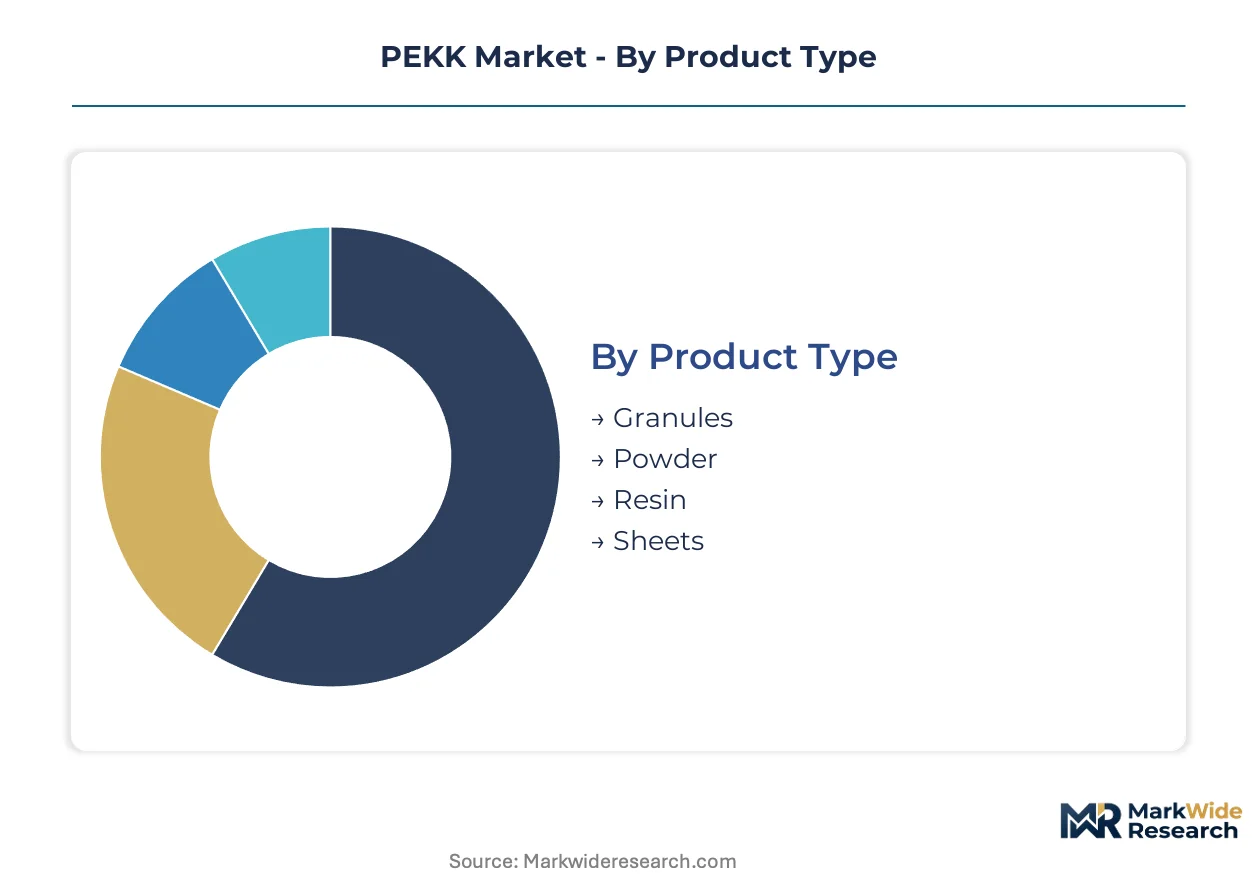
PEKK procurement patterns diverge sharply across product forms and end-use specifications, with aerospace compounders demanding aviation-grade purity while medical device manufacturers prioritize lot-level biocompatibility documentation. Understanding these segment boundaries clarifies where formulation investments yield qualified supply positions versus commodity exposure.
Product Type:
Mature industrial grades anchor baseline volume, while emerging powder formats for additive manufacturing command development attention from compounders targeting orthopedic personalization.
- Granules:Standard pelletized feedstock for injection molding and compression forming of structural brackets and industrial bushings. Airbus and Boeing tier-one suppliers in Germany and France concentrate procurement for thermoplastic composite consolidation, though REACH aromatic amine restrictions complicate alternative synthesis certification for European compounders.
- Powder:Finely milled particles optimized for laser sintering and powder bed fusion in patient-specific spinal cages and cranial implants. Hospital procurement consortia in Germany and the United States now specify blockchain traceability from resin pellet to sterilized device, bundling material certification with lot-level documentation.
- Resin:Unfilled virgin polymer for custom compounding and specialty formulation by medical device manufacturers.
- Sheets:Pre-consolidated thermoplastic laminates for machining and thermoforming of structural panels.
Granules retain volume leadership; powder holds the steepest expansion curve.
Application:
Cost tier separation distinguishes flight-critical primary structures from secondary industrial components, with medical applications occupying premium pricing through FDA 510(k) validation barriers.
- Aerospace:Primary flight structures, brackets, and clips replacing aluminum and thermoset epoxy in next-generation narrow-body programs. EASA and FAA certification progress for thermoplastic primary structures pulls resin volume from metal replacement programs, though misaligned timeline expectations between regulators create inventory risk for dual-qualified stock.
- Medical:Permanent implantable devices including spinal fusion cages, cranial plates, and dental fixtures requiring ISO 10993 biocompatibility protocols. Multi-year validation timelines delay revenue recognition for new resin entrants, while scarce technicians capable of maintaining medical-grade contamination controls limit qualified production scale-up.
- Automotive:Thermal management components and under-hood applications where chemical resistance exceeds PEEK temperature limits.
- Industrial:Oilfield seals, chemical processing equipment, and semiconductor fabrication components.
Aerospace commands current volume concentration; medical delivers the highest margin realization per kilogram.
End User:
Customer type determines specification intensity, with OEMs driving qualification standards that cascade through distributor and research channels.
- Manufacturers:Tier-one and tier-two component fabricators serving aviation and medical device assembly. China's aviation manufacturing bases near Shanghai and Xi'an concentrate demand for high-performance resin formulations as domestic airframe production expands.
- OEMs:Original equipment manufacturers including airframers and implantable device developers setting material specifications. Direct compounder contracts displace distributor intermediaries as hospital procurement consortia consolidate buying power among three national networks serving academic medical centers.
- Research Institutions:Universities and national laboratories evaluating modified rheology grades and bio-based feedstock alternatives.
- Distributors:Intermediary stockists serving fragmented industrial and automotive accounts with lower specification requirements.
Manufacturers process the highest resin tonnage; OEMs dictate qualification standards that determine supplier viability.
Form:
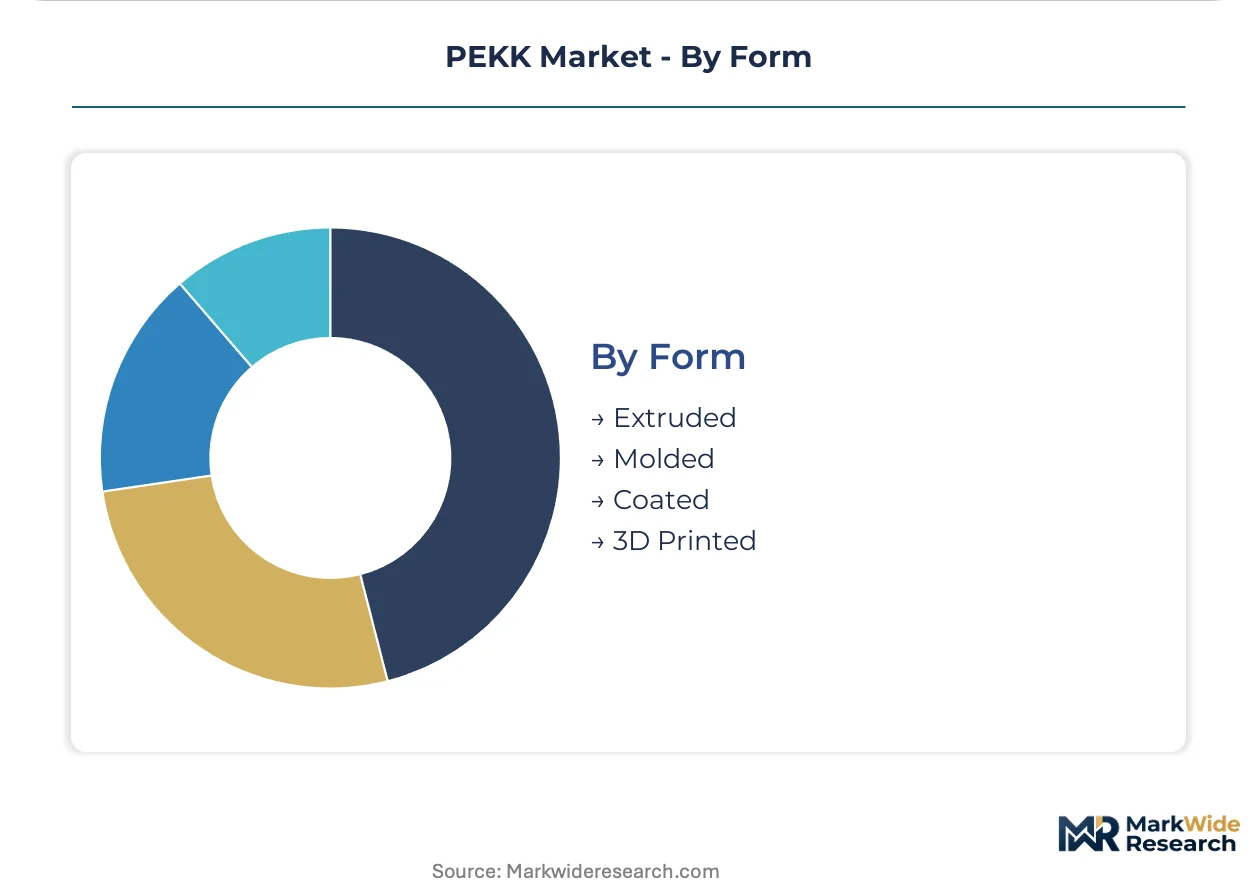
Supply concentration clusters around extruded and molded formats, with 3D printed geometries representing the frontier of mass-customized surgical device production.
- Extruded:Continuous profiles and stock shapes for machining into final dimensions. Germany's industrial clusters anchor European supply of REACH-compliant extruded grades for qualified aerospace resin.
- Molded:Compression and injection molded complex geometries for brackets, housings, and structural nodes. In-situ polymerization of low-melt-viscosity variants collapses cycle times while demanding reformulated catalyst packages from resin producers.
- Coated:Surface-modified substrates for wear resistance and electrical insulation applications.
- 3D Printed:Additively manufactured patient-specific geometries from powder bed fusion and laser sintering. Topology optimization software integration enables mass-customized surgical guides and fixation plates with premium positioning in spinal and cranial segments.
Molded forms dominate current shipment volumes; 3D printed geometries are gaining share fastest in medical personalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace compounders and medical device manufacturers concentrate procurement in Germany, the United States, China, France, and Japan, with each market shaped by distinct regulatory frameworks and industrial clustering patterns.
Germany
REACH aromatic amine precursor restrictions compel alternative synthesis certification for PEKK compounders serving Airbus tier-one suppliers. ECHA reporting requirements extend to imported ketone monomers, forcing mass-balance documentation from Asian feedstock sources. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg anchor European supply of aviation-grade resin formulations.
United States
FAA certification progress for thermoplastic primary structures pulls resin volume from metal replacement programs at Boeing and emerging eVTOL manufacturers. FDA enforces ISO 10993 biocompatibility standards for implantable devices, extending multi-year validation timelines for medical-grade entrants. Procurement consortia serving academic medical centers in Boston and the Midwest consolidate buying power through direct compounder contracts.
China
Domestic airframe production expansion near Shanghai and Xi'an assembly facilities concentrates demand for high-performance resin formulations. NMPA accelerates medical device registration reforms that streamline PEKK implant approvals for domestic manufacturers. MIIT industrial policy supports ketone monomer capacity expansion to reduce import dependence for aviation supply chains.
France
EU Green Deal chemical transition mandates force documentation of carbon footprint across ketone monomer supply chains for aerospace compounders. EASA certification timelines for thermoplastic primary structures create inventory risk for dual-qualified resin stock held by suppliers. The Paris-Saclay research cluster advances modified rheology grades for automated fiber placement applications.
Japan
METI industrial standards for high-performance polymers guide specification development among precision component manufacturers. PMDA regulatory frameworks for permanent implants align with ISO 10993 protocols, creating parallel validation requirements for medical-grade resin entrants. The Nagoya aerospace manufacturing corridor qualifies PEKK for structural brackets in regional jet programs.
PEKK Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. European chemical conglomerates with polymer heritage anchor aviation-grade formulation supply, while Asian compounders scale ketone monomer integration. Three archetypes dominate: integrated monomer-to-resin producers, medical-grade purity specialists, and regional compounders serving industrial accounts. Competitive moves center on backward integration into ketone feedstock and capacity expansion near qualified aerospace assembly sites.
Among European-based integrated producers, Solvay and Arkema SA exemplify the monomer-anchored archetype with established REACH-compliant synthesis pathways. Victrex plc occupies a position within the medical-grade purity tier, serving implantable device specifications. These three names represent distinct competitive vectors—European polymer heritage, ketone monomer integration, and biocompatibility certification—rather than overlapping market positions.
| Leading Market Players |
|---|
| Shandong Kaisheng New Materials Co., Ltd. |
| Evonik Industries AG |
| Solvay |
| Ensinger |
| Polymics, Ltd. |
| Arkema SA |
| Victrex plc |
| RTP Company, Inc. |
| Panjin Zhongrun High Performance Polymers Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Germany's REACH-compliant ketone monomer production anchors margin capture for aviation-grade resin, concentrating pricing power among backward-integrated European compounders while non-integrated Asian suppliers absorb fluorinated feedstock volatility.
Pricing Analysis
Cost-plus contracts with fluorinated monomer indexation dominate long-term aerospace supply agreements, separating medical-grade biocompatibility-certified resin at premium tiers from industrial granules competing on volume scale. Price differentiation hinges on FDA 510(k) validation status and REACH aromatic amine compliance certification. Pricing pressure intensifies in standard industrial grades as Chinese ketone capacity expansion feeds spot market liquidity. Tier-one aviation compounders exhibit lowest price sensitivity; fragmented automotive seal buyers drive hardest bargain negotiations.
Supply Chain Analysis
Extended payment terms from Airbus and Boeing tier-one suppliers cascade through supply-chain finance facilities, squeezing working capital for mid-size compounders lacking captive monomer production. Raw material sourcing concentrates in Germany, Belgium, and China's Shandong province, drawing from diphenyl ether, fluorinated ketones, and high-purity catalyst precursors. Single-source vulnerability persists in REACH-certified aromatic amine alternatives. Distribution runs through direct compounder contracts with hospital procurement consortia and aviation OEM qualification programs, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PEKK demand cycles track aviation production rates, with Boeing and Airbus narrow-body ramp schedules constituting the primary cyclical recovery driver through thermoplastic composite qualification commitments.
For Market Incumbents: Entrench aviation-grade supply positions through in-house ketone monomer capacity expansion near Toulouse and Hamburg assembly corridors. Solvay and Arkema SA's backward integration into fluorinated feedstock represents the defensive template; replicate this upstream control or cede margin to integrated rivals. Counter thermoset epoxy substitution threats by accelerating low-melt-viscosity grade deployment for automated fiber placement protocols.
For New Entrants and Emerging Players: India's medical device PLI scheme offers underpenetrated white-space for implant-grade resin production serving NMPA-aligned export markets. Target laser sintering powder formulations for patient-specific orthopedic devices, where blockchain traceability requirements and ISO 10993 validation barriers deter commodity competition. Establish direct contracts with German and US hospital procurement consortia rather than distributor channel buildout.
For Investors and Strategic Acquirers: Capital is best deployed toward medical-grade purity specialists with established FDA 510(k) dossiers and captive biocompatibility testing infrastructure. Long-term viability hinges on aviation thermoplastic primary structure certification maturation from demonstration programs to serial production commitments. Monitor EASA-FAA timeline synchronization as the inflection signal for qualified resin inventory velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ketone Monomer Supply | Captive fluorinated feedstock production insulates margin from aromatic amine price volatility affecting European compounders. |
| Medical-Grade Biocompatibility Certification Investment | FDA 510(k) validation and ISO 10993 compliance unlock premium pricing in spinal implant and cranial fixation segments. |
| Low-Melt-Viscosity Grade Development | Modified rheology PEKK enables automated fiber placement at reduced temperatures, collapsing aerospace bracket cycle times. |
| Blockchain Traceability System Deployment | Lot-level documentation from resin pellet to sterilized device satisfies German and US hospital procurement consortia requirements. |
| Additive Manufacturing Powder Capacity Expansion | Laser sintering formulations for patient-specific orthopedic devices command fastest-expanding demand within medical applications. |
Research Methodology
Operator-level perspectives from aerospace tier-one procurement directors, medical device regulatory affairs leads, polymer plant managers, and hospital GPO contracts managers anchored the qualitative base. Primary interview insights combined with secondary validation from ECHA REACH filings, FAA certification progress databases, NMPA medical device registration records, and customs trade data for fluorinated ketone monomers. Bottom-up resin demand modeling by application and grade tier triangulated against top-down aerospace production forecasts and medical implant procedure volumes.
Scenario-bracketing around aviation thermoplastic qualification timelines and medical device regulatory reform trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form, application end-use, purity grade tier, and regional manufacturing hub concentration. CAGRs derived from weighted average of demand elasticity coefficients and supply capacity expansion schedules, with specific inputs capturing REACH aromatic amine restriction compliance costs and NMPA registration reform implementation pace.
Practitioners should monitor EASA-FAA certification synchronization delays, ketone monomer feedstock price spikes, and medical device reimbursement policy shifts for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market