
 Super Absorbent Polymer Market | 2026-2036
Super Absorbent Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Super Absorbent Polymer Market Analytics
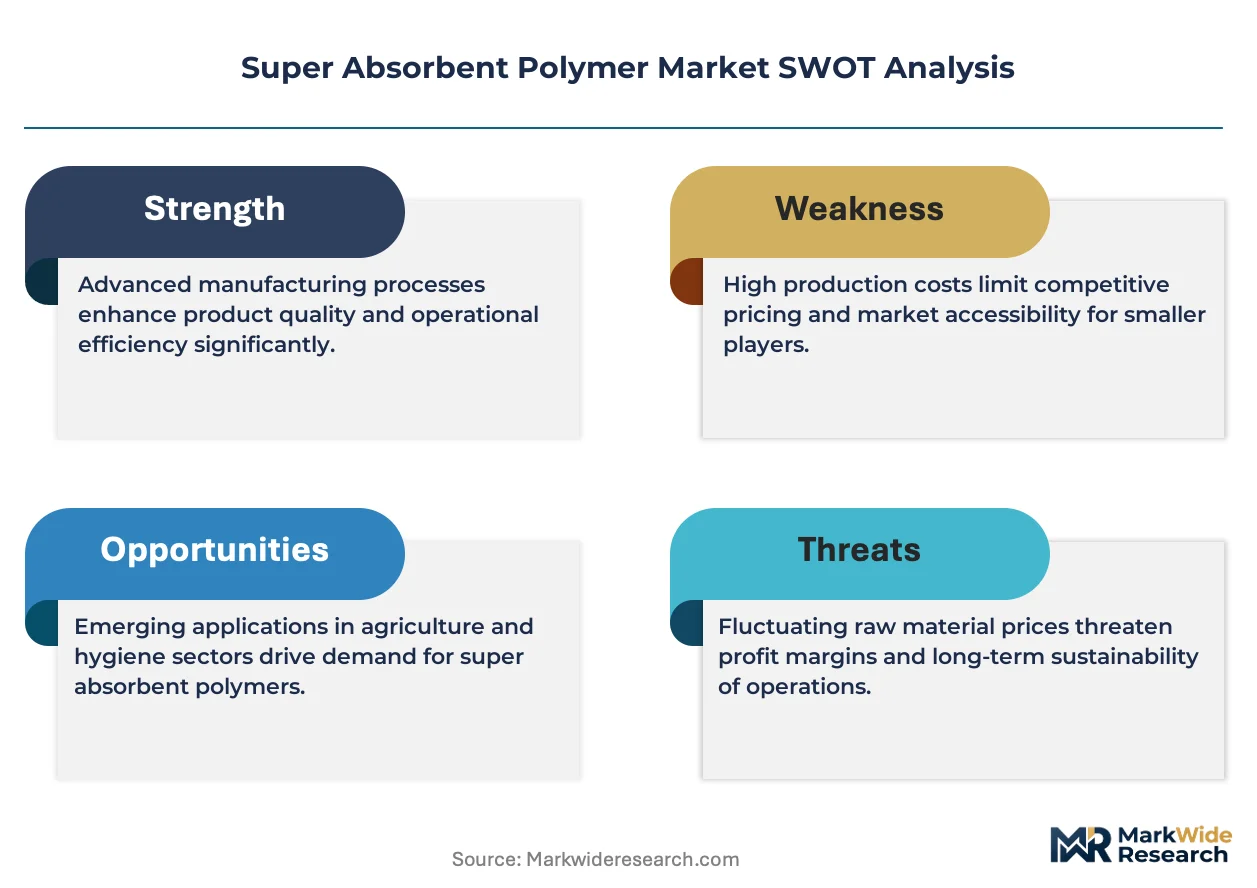
ISO 10993 biocompatibility certification is redrawing competitive boundaries in medical-grade super absorbent polymer supply. Nippon Shokubai leverages its acrylic acid backward integration to sustain cost leadership across Asian personal care supply chains. Evonik Industries AG anchors its position through high-purity hydrogel R&D intensity for wound care applications. BASF SE competes on granular SAP scale, dominating European diaper material procurement networks.
Super absorbent polymer denotes cross-linked hydrophilic polymers capable of absorbing aqueous solutions up to hundreds of times their dry mass, primarily synthesized through inverse suspension or aqueous solution polymerization of acrylic acid neutralized with sodium hydroxide. The material functions as a core fluid-management agent in disposable hygiene products, agricultural substrates, and medical dressings. Granule-form SAP occupies the largest share of personal care procurement due to established diaper manufacturing compatibility, while biodegradable SAP captures the fastest growth trajectory as European REACH restrictions on petroleum-derived acrylates tighten formulation requirements. Medical applications concentrate margin pools where ISO and FDA biocompatibility standards elevate pricing power for qualified suppliers.
REACH registration in Europe, FDA 21 CFR oversight in the United States, and China's GB standards under SAMR collectively shape product composition, migration limits, and market access pathways for super absorbent polymer manufacturers. These frameworks increasingly favor low-residual-monomer formulations and biodegradable feedstock documentation, raising compliance costs for non-integrated producers. Stakeholders must monitor regulatory divergence between European chemical restrictions and Asian industrial standards when allocating capacity across regional supply networks.
Market Dynamics
REACH compliance deadlines in Europe are compressing formulation windows for petroleum-derived acrylates, forcing producers to revalidate supply chains before 2030 registration phases. This regulatory pressure is accelerating capital allocation toward bio-based feedstock pilot plants and monomer recycling infrastructure.
Growth Catalysts
- GB Standards Modernization:China's SAMR has tightened residual monomer limits for hygiene-grade SAP, compelling domestic producers to upgrade purification systems and creating replacement demand for imported high-purity material.
- Agricultural Drought Management:Subsurface water retention applications in water-stressed growing regions are absorbing technical-grade SAP volumes previously directed toward commodity markets.
- ISO 10993 Certification Expansion:Medical device manufacturers seeking biocompatibility credentials for wound care dressings are qualifying secondary suppliers beyond traditional hydrogel incumbents.
Market Restraints
- Acrylic Acid Feedstock Volatility:Propylene price swings transmitted through naphtha cracking economics compress margin stability for non-integrated polymer producers.
- East Asian Supply Concentration:Over two-thirds of global nameplate capacity sits within 500 kilometers of Shanghai and Osaka, exposing buyers to port congestion and regional carbon policy divergence.
- Biodegradable Performance Gap:Starch-graft and cellulose-based alternatives exhibit 40-60% lower absorption capacity under saline loading, limiting substitution in premium diaper cores.
Strategic Opportunities
- Indian Subcontinent Underpenetration:Per-capita diaper consumption remains below ten units annually versus 1,400 in Japan, creating latent demand as urban sanitation infrastructure expands.
- EU Green Deal Procurement Mandates:Public tenders for agricultural substrates now require biodegradable content documentation, opening specification windows for certified bio-based SAP.
- Digital Twin Process Control:Real-time crosslink density monitoring via inline rheometry is reducing off-spec batches and enabling mass customization for medical hydrogel contracts.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Universities have downsized emulsion and suspension polymerization programs, narrowing the hiring pipeline for process development roles.
- ISO 10993 Timeline Compression:Cytotoxicity and sensitization testing cycles now exceed eighteen months, delaying market entry for reformulated bio-based candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Absorbent Polymer Market |
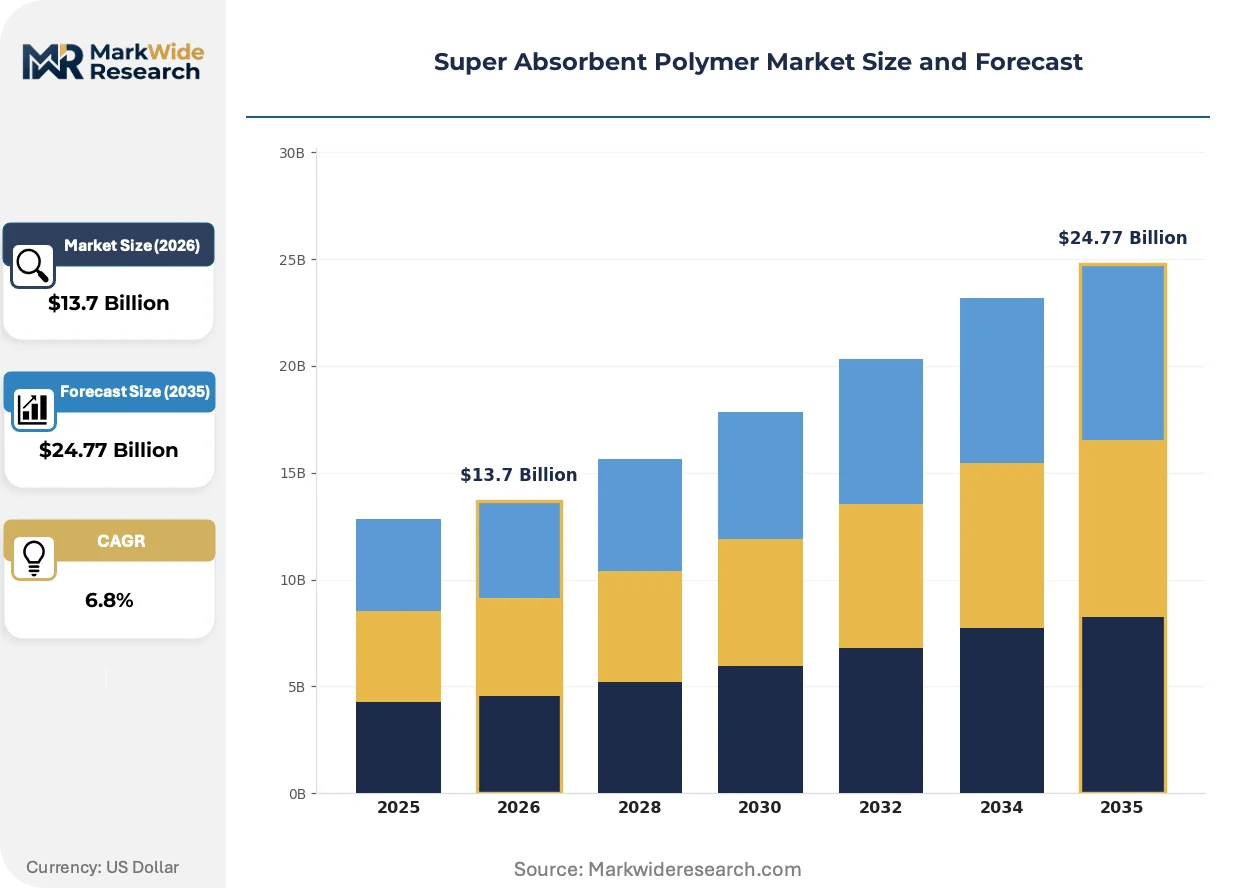
| Market Size in 2026 | $13.7 Billion |
| Market Size in 2035 | $24.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
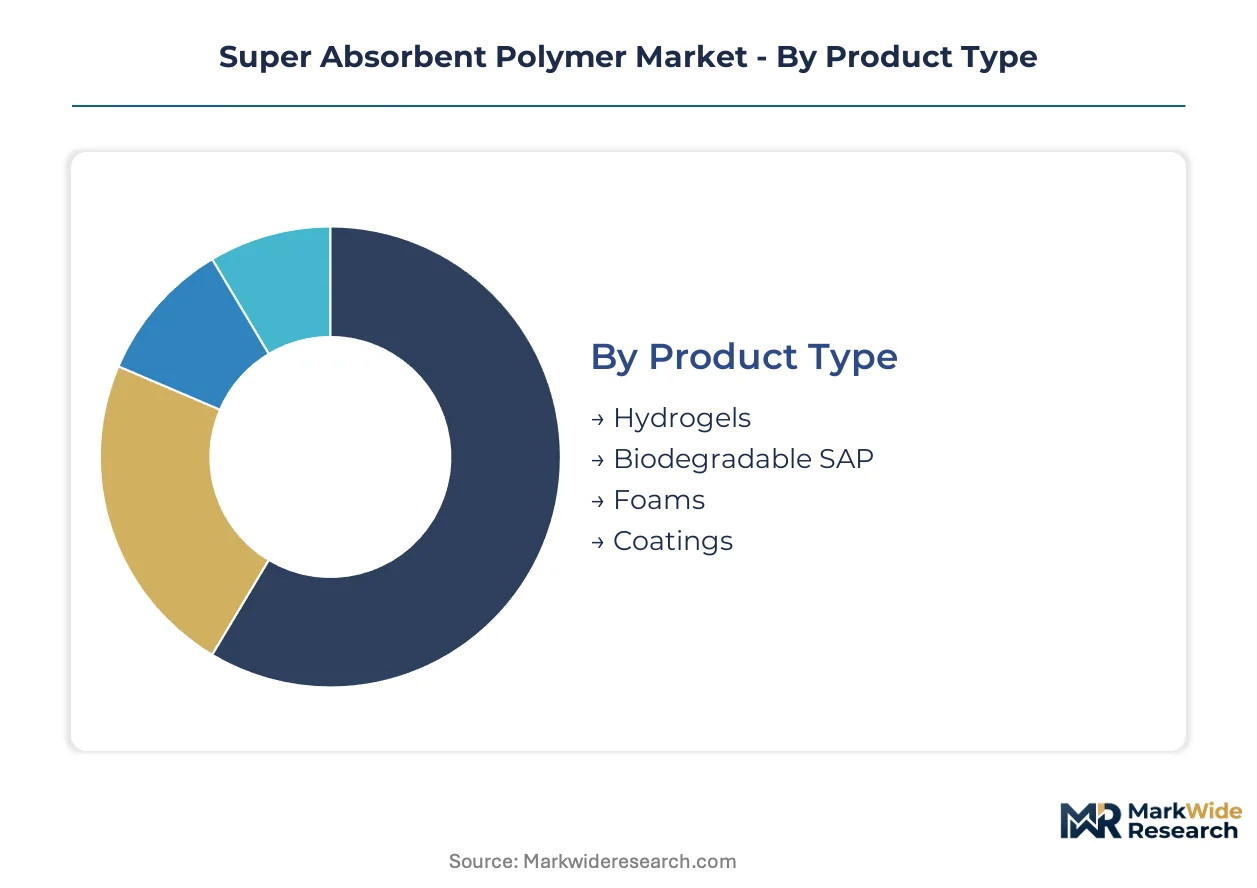
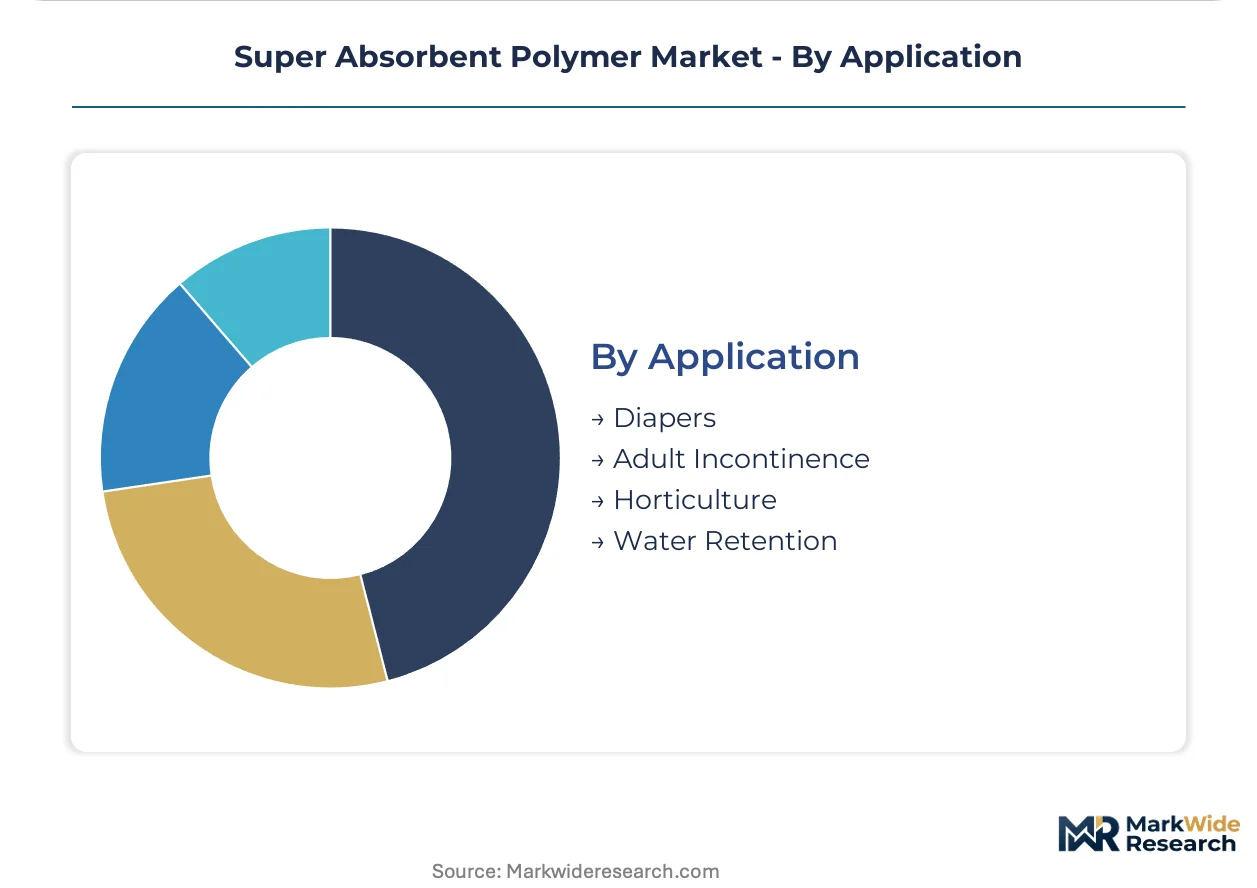
| Segmentation | Product Type: Hydrogels, Biodegradable SAP, Foams, Coatings End User: Personal Care, Agriculture, Construction, Medical Form: Granules, Powders, Sheets, Beads Application: Diapers, Adult Incontinence, Horticulture, Water Retention |
| Companies Covered | Nippon Shokubai Co., Ltd., Evonik Industries AG, BASF SE, Sumitomo Seika Chemicals Co., Ltd., LG Chem Ltd., Kao Corporation, SDP Global Co., Ltd., Sanyo Chemical Industries, Ltd., Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Absorbent Polymer Market Evolving Landscape
Bio-based feedstock validation and precision crosslinking control are converging to redefine performance benchmarks across hygiene, medical, and agricultural end-uses. These technical currents are redistributing competitive advantage toward producers with captive monomer supply and advanced characterization capabilities.
Surface-crosslinked granular SAP is displacing conventional homogeneous particles in ultra-thin diaper cores. Personal care manufacturers in Japan and South Korea have adopted this architecture for premium product lines. The technology is displacing legacy fluff-pulp hybrid structures by enabling 30% core mass reduction without leakage performance degradation.
REACH restriction proposals on microplastic release are tightening documentation requirements for synthetic polymer content in agricultural applications. ECHA's 2023-2025 evaluation timeline is forcing substrate formulators to establish biodegradability certification pathways. Agricultural SAP suppliers with EU compostability credentials are securing multi-year supply agreements ahead of anticipated enforcement phases.
Direct mill integration contracts are consolidating procurement decisions for hygiene-grade material. Major diaper manufacturers in China and Southeast Asia are bypassing distributors to secure volume commitments with polymer producers. This channel compression is most visible in the Yangtze River Delta, where three converters now account for the majority of regional SAP offtake.
Super Absorbent Polymer Market Segmentation
Segmentation in super absorbent polymers reveals how procurement channels, technical specifications, and regulatory requirements fragment supply relationships. Manufacturers configure production lines around specific form factors and purity grades, creating distinct margin pools that resist commoditization.
Product Type:
Channel mix varies sharply by product chemistry, with petroleum-derived hydrogels flowing through established diaper manufacturer direct contracts while bio-based alternatives route through specialty distributors serving EU agricultural tenders.
- Hydrogels:Cross-linked polyacrylic acid networks neutralized with sodium hydroxide dominate procurement volumes through inverse suspension polymerization. Personal care manufacturers in Japan and South Korea specify surface-crosslinked variants for ultra-thin diaper cores where 30% mass reduction targets compress core thickness without leakage degradation. REACH registration phases in Europe are forcing reformulation timelines for acrylate-based hydrogels ahead of 2030 deadlines.
- Biodegradable SAP:Starch-graft copolymers and cellulose-based architectures absorb aqueous solutions at 40-60% lower capacity under saline loading than synthetic counterparts. EU Green Deal procurement mandates for agricultural substrates now require compostability documentation, opening specification windows ahead of ECHA enforcement phases. Performance gaps in premium diaper cores limit substitution despite regulatory pressure.
- Foams:Open-cell polyurethane structures with superabsorbent particulate loading serve wound care and medical packaging applications requiring conformability.
- Coatings:Thin-film SAP depositions on nonwoven substrates enable functionalized layers in advanced hygiene products.
By volume, hydrogels lead. By growth pace, biodegradable SAP is climbing the fastest.
End User:
Cost tier stratification separates commodity hygiene procurement from medical-grade contracts where ISO 10993 certification elevates pricing power.
- Personal Care:Diaper and feminine hygiene manufacturers absorb the majority of nameplate capacity through direct mill integration contracts. Three converters in China's Yangtze River Delta now account for the majority of regional SAP offtake, bypassing traditional distributor networks. GB standards modernization under SAMR has tightened residual monomer limits, compelling purification system upgrades.
- Agriculture:Subsurface water retention substrates in drought-stressed growing regions redirect technical-grade volumes from commodity markets. EU public tenders now mandate biodegradable content documentation, favoring suppliers with compostability credentials.
- Construction:Concrete curing and waterproofing membranes absorb moisture-control grade material.
- Medical:Wound care dressings and surgical drapes require biocompatibility certification where cytotoxicity testing cycles exceed eighteen months. FDA 21 CFR oversight and ISO standards elevate barriers for secondary supplier qualification.
Personal care commands procurement scale. Medical applications capture margin concentration.
Form:
Volume concentration in granule production reflects diaper manufacturing equipment compatibility and established handling infrastructure.
- Granules:Spherical particles 100-800 microns in diameter flow through conventional diaper core forming equipment without retrofit. Surface-crosslinked architectures displace homogeneous particles in premium product lines. East Asian supply concentration within 500 kilometers of Shanghai and Osaka exposes buyers to port congestion risk.
- Powders:Fine particulate below 100 microns serves coatings and specialized medical applications requiring rapid dissolution.
- Sheets:Laminated SAP layers enable integrated absorbent cores for adult incontinence products.
- Beads:Larger diameter spheres 1-3 millimeters target agricultural water retention where soil permeability matters.
Granules dominate shipment tonnage. Powders gain share in medical formulation.
Application:
Customer type bifurcation separates high-volume hygiene contracts from specification-driven agricultural and medical procurement.
- Diapers:Infant disposable hygiene products specify ultra-thin core architectures with surface-crosslinked granular SAP enabling fluff-pulp hybrid displacement. Per-capita consumption in India remains below ten units annually versus 1,400 in Japan, creating latent demand as urban sanitation infrastructure expands.
- Adult Incontinence:Aging demographics in developed markets absorb premium-grade material with odor-control additives. Product lines differentiate through core thickness and skin-contact layer specifications.
- Horticulture:Soil amendment and hydroponic substrates require biodegradable certification under tightening European microplastic restrictions.
- Water Retention:Agricultural drought management applications concentrate in water-stressed growing regions.
Diapers anchor volume demand. Adult incontinence shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deep-water port infrastructure underwrites China's dominance in SAP procurement, while Osaka-Kobe's chemical handling terminals anchor Japanese supply chain reliability for medical-grade material.
China
Domestic diaper manufacturers in Jiangsu and Zhejiang provinces absorb expanding nameplate capacity through direct mill integration contracts. SAMR's tightened GB standards on residual monomer limits compel purification system upgrades among local producers. Three converters in the Yangtze River Delta now account for the majority of regional SAP offtake, bypassing traditional distributor networks entirely.
Japan
Surface-crosslinked granular architectures for ultra-thin diaper cores command premium procurement from personal care manufacturers in Tokyo and Osaka. METI guidance on chemical substance management elevates documentation requirements for petroleum-derived acrylates. Kansai region producers leverage captive acrylic acid supply to sustain cost leadership across Asian supply chains.
Germany
REACH registration phases compress formulation windows for synthetic hydrogels ahead of 2030 deadlines, accelerating bio-based feedstock pilot investments. ECHA restriction proposals on microplastic release tighten agricultural substrate specifications. Ludwigshafen and Marl chemical clusters host integrated producers dominating European diaper material procurement networks.
United States
FDA 21 CFR oversight elevates barriers for medical-grade SAP qualification where cytotoxicity testing cycles exceed eighteen months. Adult incontinence product lines absorb premium-grade material as aging demographics expand addressable demand. Gulf Coast petrochemical corridors transmit propylene price volatility through naphtha cracking economics.
India
Per-capita diaper consumption below ten units annually versus 1,400 in Japan creates latent demand as urban sanitation infrastructure expands. BIS standards for hygiene-grade material remain less stringent than Chinese or European equivalents, attracting technical-grade imports. Maharashtra and Gujarat industrial corridors concentrate converting capacity for emerging domestic brands.
Super Absorbent Polymer Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D intensity in a market structure that concentrates volume among integrated petrochemical conglomerates while fragmenting specialty niches. Three archetypes dominate: backward-integrated acrylic acid producers, high-purity hydrogel specialists, and bio-based feedstock pioneers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure offtake commitments ahead of regulatory phase-ins.
Within the integrated petrochemical tier, BASF SE and Nippon Shokubai Co., Ltd. exemplify producers with captive monomer supply sustaining cost leadership across regional procurement networks. Evonik Industries AG occupies a position among high-purity hydrogel specialists where ISO 10993 certification elevates pricing power for wound care applications. These three entities anchor the competitive landscape through distinct capability configurations rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Nippon Shokubai Co., Ltd. |
| Evonik Industries AG |
| BASF SE |
| Sumitomo Seika Chemicals Co., Ltd. |
| LG Chem Ltd. |
| Kao Corporation |
| SDP Global Co., Ltd. |
| Sanyo Chemical Industries, Ltd. |
| Formosa Plastics Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Yangtze River Delta diaper converters and acrylic acid-integrated producers lock in both supply access and price visibility, compressing distributor margins while insulating integrated players from propylene volatility transmitted through naphtha cracking economics.
Pricing Analysis
Certification level creates the primary spread between medical-grade ISO 10993-qualified material and technical-grade agricultural supply. Three-tier pricing structure separates premium hydrogels with surface-crosslinked architectures from standard granular SAP and economy-grade biodegradable alternatives. Cost compression in hygiene-grade material is intensifying because direct mill integration contracts consolidate procurement decisions among three dominant converters. Personal care manufacturers exhibit highest price sensitivity, while wound care device makers absorb premiums for biocompatibility documentation.
Supply Chain Analysis
Inventory cycles for acrylic acid feedstock now extend beyond traditional just-in-time windows as buyers buffer against propylene price swings. Production gravity centers on China, Japan, and South Korea, with over two-thirds of nameplate capacity clustered within 500 kilometers of Shanghai and Osaka. Supply chains draw from propylene derivatives, sodium hydroxide neutralizing agents, and crosslinking monomer inputs. Single-source vulnerability concentrates in East Asian port infrastructure where congestion disrupts just-in-time diaper manufacturing. Distribution runs through direct mill integration contracts bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three Yangtze River Delta converters now accounting for majority regional offtake, shifting negotiation leverage toward volume-commitment extractors and away from fragmented distributor channels.
For Market Incumbents: Shield margin pools in medical-grade hydrogels by accelerating ISO 10993 certification timelines before secondary suppliers complete eighteen-month cytotoxicity testing cycles. Deepen backward integration into acrylic acid monomer supply to sustain cost leadership against propylene volatility. Prioritize surface-crosslinked granular R&D to defend premium positioning in ultra-thin diaper core specifications.
For New Entrants and Emerging Players: ISO 10993 fast-track qualification creates entry pathways into wound care dressing supply where biocompatibility barriers delay incumbent expansion. Target Indian subcontinent diaper manufacturing as urban sanitation infrastructure expands per-capita consumption from below ten units annually. Pursue EU Green Deal agricultural substrate tenders requiring biodegradable certification ahead of ECHA microplastic enforcement phases.
For Investors and Strategic Acquirers: Bio-based feedstock pioneers with validated starch-graft copolymer performance represent the most defensible acquisition profile as REACH registration phases compress petroleum-derived acrylate windows. Evaluate long-term viability through lens of regulatory divergence between European chemical restrictions and Asian industrial standards. Monitor ECHA restriction proposal timelines as inflection indicator for bio-based capacity valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive monomer supply insulates margin stability against propylene volatility from naphtha cracking economics. |
| ISO 10993 Certification Investment | Eighteen-month biocompatibility testing cycles create qualification moats around wound care hydrogel pricing power. |
| Direct Mill Integration Contracts | Bypassing distributor networks locks in volume commitments with Yangtze River Delta diaper converters. |
| Bio-based Feedstock Pilot Scale-Up | REACH registration deadlines accelerate capital allocation toward compostable alternatives for agricultural substrates. |
| Surface-Crosslinked Granular R&D | Thirty percent core mass reduction enables fluff-pulp hybrid displacement in premium Japanese and South Korean diaper lines. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with plant managers at acrylic acid-integrated producers, procurement leads at personal care OEMs, distribution channel partners serving agricultural substrates, and technical R&D directors developing hydrogel formulations; alongside secondary validation through customs and trade flow databases, chemical industry association reports, SEC filings from listed petrochemical conglomerates, and regulatory submission records from ECHA and FDA. Bottom-up capacity and demand modeling triangulated against top-down market sizing from trade statistics.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product chemistry tier, end-use industry concentration, regional production hub configuration, and certification grade stratification. CAGRs were derived from elasticity-adjusted demand projections incorporating diaper per-capita consumption trajectories, agricultural drought management adoption curves, and medical device qualification timelines. Forecast inputs included propylene price volatility indices and regulatory phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of continued REACH enforcement trajectory and stable East Asian port infrastructure; material deviation in either would warrant model refresh. Specific risks include accelerated biodegradable performance gap closure, abrupt SAMR standard tightening, or acrylic acid supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Polymer Plastic Plain Bearings Market