
 North America Polyvinylpyrrolidone (PVP) Market | 2026-2036
North America Polyvinylpyrrolidone (PVP) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyvinylpyrrolidone (PVP) Market Analytics
Pharmaceutical-grade specification upgrades is redrawing competitive boundaries across the North America PVP landscape. Ashland Global Holdings Inc. leverages its captive supply of high-purity grades to anchor pricing power in specialty pharmaceutical contracts. BASF SE sustains R&D intensity at its North American technical centers, while Merck KGaA differentiates through channel control in life-science distribution networks.
Polyvinylpyrrolidone is a water-soluble synthetic polymer synthesized via free-radical polymerization of N-vinylpyrrolidone monomer, with molecular weights ranging from K-15 to K-90 grades that determine viscosity and binding strength in formulated products. Its primary commercial purpose centers on serving as a film-former, binder, and dispersant across pharmaceutical tablets, cosmetic serums, and industrial adhesives. Pharmaceutical-grade material commands the deepest margin pools due to excipient validation burdens, while cosmetic-grade volumes expand fastest as clean-label personal care brands reformulate away from petrochemical alternatives. Industrial-grade supply competes primarily on scale economics in adhesive and coating applications.
FDA excipient guidelines, EPA chemical data reporting under TSCA, and Health Canada's ICH Q3D impurity standards collectively shape product qualification timelines and cross-border shipment protocols for PVP suppliers. These frameworks elevate compliance costs for smaller distributors while creating structural advantages for integrated manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor pending EPA risk evaluation outcomes for N-vinylpyrrolidone monomer residuals to anticipate potential reformulation mandates or supply chain requalification cycles.
Market Dynamics
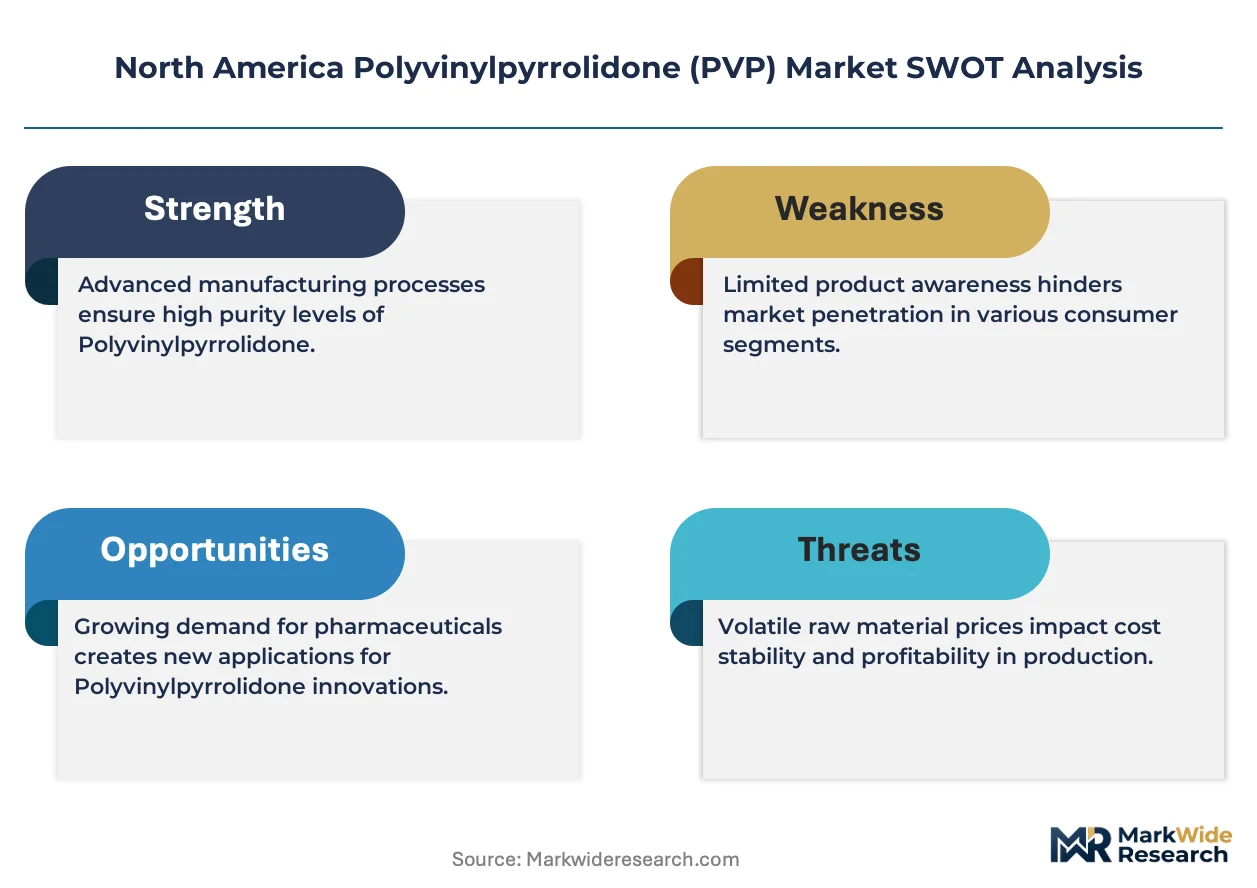
Pharmaceutical-grade specification upgrades are redrawing competitive boundaries across the North America PVP landscape, forcing suppliers to requalify production lines and consolidate quality assurance functions.
Growth Catalysts
- Controlled-release drug formulations:Pharmaceutical companies across the United States and Canada are expanding PVP adoption in tablet binders and film coatings. FDA guidelines on excipient purity are tightening quality benchmarks for cross-border supply.
- EPA chemical safety frameworks:Evolving reporting requirements under TSCA are elevating compliance costs for smaller distributors while creating structural advantages for integrated manufacturers with dedicated regulatory affairs teams.
- Clean-label personal care reformulation:Cosmetic-grade volumes expand fastest as brands reformulate away from petrochemical alternatives, with molecular weight grades K-15 through K-30 finding new applications in serum formulations.
Market Restraints
- N-vinylpyrrolidone monomer residual volatility:Feedstock price swings compress margins for non-integrated producers lacking captive monomer supply. EPA risk evaluation outcomes for residuals threaten additional reformulation mandates.
- Excipient validation burdens:Health Canada's ICH Q3D impurity standards and FDA qualification timelines extend product approval cycles, freezing smaller entrants out of pharmaceutical-grade contracts.
- Cellulose derivative substitution:Hydroxypropyl methylcellulose and croscarmellose sodium are displacing PVP in select tablet disintegration applications where cost sensitivity outweighs performance requirements.
Strategic Opportunities
- Underpenetrated Canadian pharmaceutical corridor:Ontario and Quebec manufacturing clusters show lower PVP penetration rates than the U.S. Northeast, creating whitespace for suppliers with Health Canada pre-qualification.
- 3D-printed pharmaceutical excipient convergence:Binder jetting and fused deposition modeling processes are converging with PVP film-forming properties, opening novel dosage form geometries for personalized medicine applications.
- Direct-to-formulator distribution channels:Life-science procurement teams are bypassing traditional chemical distributors, rewarding suppliers with technical service capabilities and digital ordering platforms.
Industry Challenges
- Cross-functional regulatory talent scarcity:Combined FDA, EPA, and Health Canada expertise commands premium compensation, straining mid-tier suppliers competing for qualified submission writers and quality auditors.
- Legacy batch record system integration:Pharmaceutical customers require electronic batch record compatibility, forcing PVP manufacturers to reconfigure manufacturing execution systems and validate data integrity protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyvinylpyrrolidone (PVP) Market |
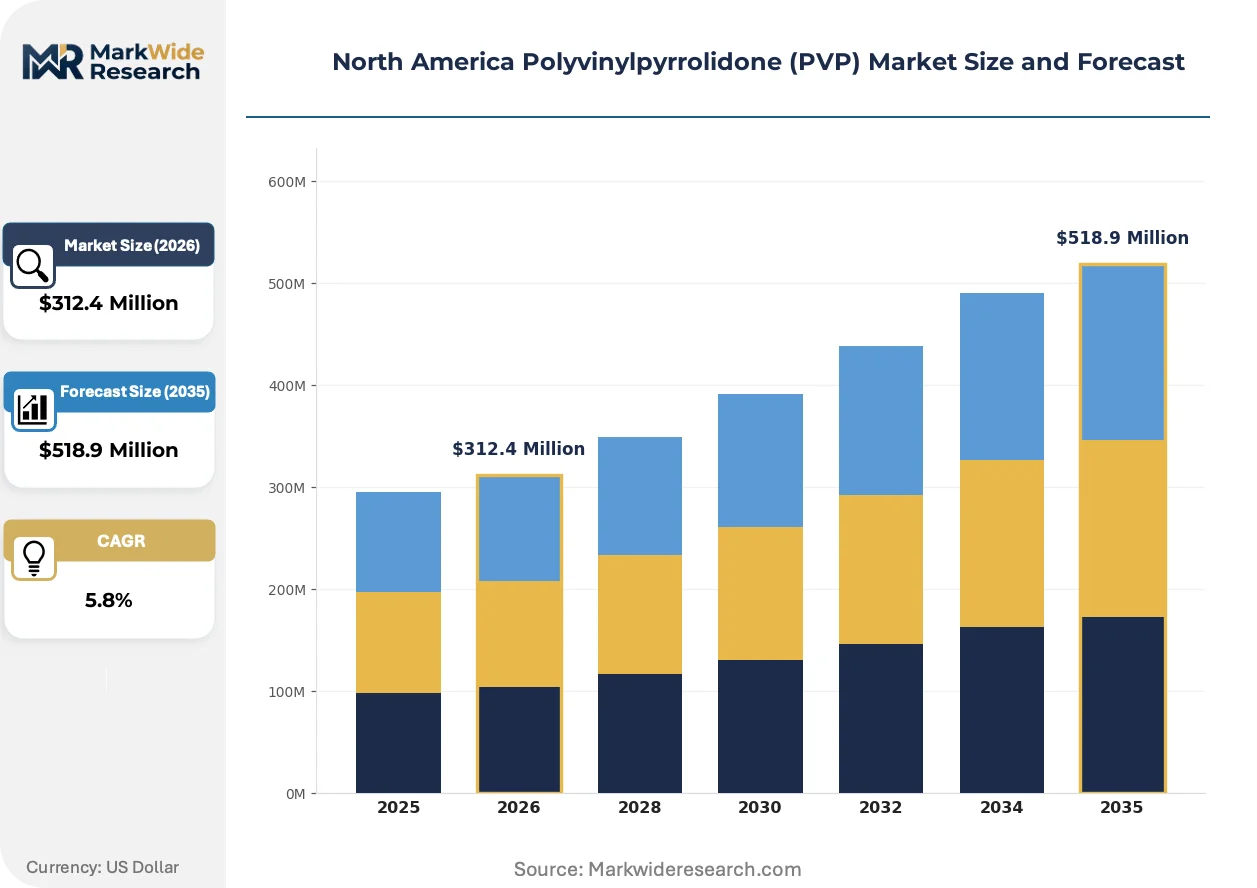
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Cosmetic Grade, Food Grade, Industrial Grade Application: Pharmaceuticals, Hair Care, Personal Care, Food Additives End User: Pharmaceutical Companies, Cosmetic Manufacturers, Food Industry, Chemical Industry Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors |
| Companies Covered | Ashland Global Holdings Inc., BASF SE, Nippon Shokubai Co., Ltd., Merck KGaA, Thermo Fisher Scientific, Hangzhou Motto Science & Technology Co., Ltd., Boai NKY Pharmaceuticals Ltd., JH Nanhang Life Sciences Co., Ltd., Alfa Aesar, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyvinylpyrrolidone (PVP) Market Evolving Landscape
Continuous processing technologies and real-time release testing are compressing production cycles for pharmaceutical-grade PVP, while regulatory data harmonization efforts are reshaping qualification protocols across the United States and Canada.
Ultra-low molecular weight PVP grades synthesized via controlled free-radical polymerization are miniaturizing particle size distributions for nanosuspension drug delivery. Specialty pharmaceutical formulators in New Jersey and Massachusetts are adopting these grades for bioavailability enhancement of poorly soluble APIs. This particle engineering is compressing dissolution timelines and enabling once-daily dosing formats previously unattainable with conventional K-30 binders.
EPA's pending risk evaluation for N-vinylpyrrolidone monomer residuals under TSCA Section 6 is forcing preemptive supply chain requalification across the Great Lakes manufacturing corridor. Integrated producers with in-house monomer recovery systems are accelerating certification documentation to maintain pharmaceutical customer contracts. The evaluation outcome will most acutely affect imported material crossing through Detroit and Buffalo port facilities.
Formulator procurement teams are consolidating excipient supplier panels from twelve-vendor rosters to three-preferred-partner structures, prioritizing technical service depth over unit pricing. This concentration is displacing regional distributors in favor of integrated manufacturers with dedicated North American technical centers. The shift is most visible among mid-cap generic pharmaceutical companies in Pennsylvania and North Carolina seeking reduced audit burdens.
North America Polyvinylpyrrolidone (PVP) Market Segmentation
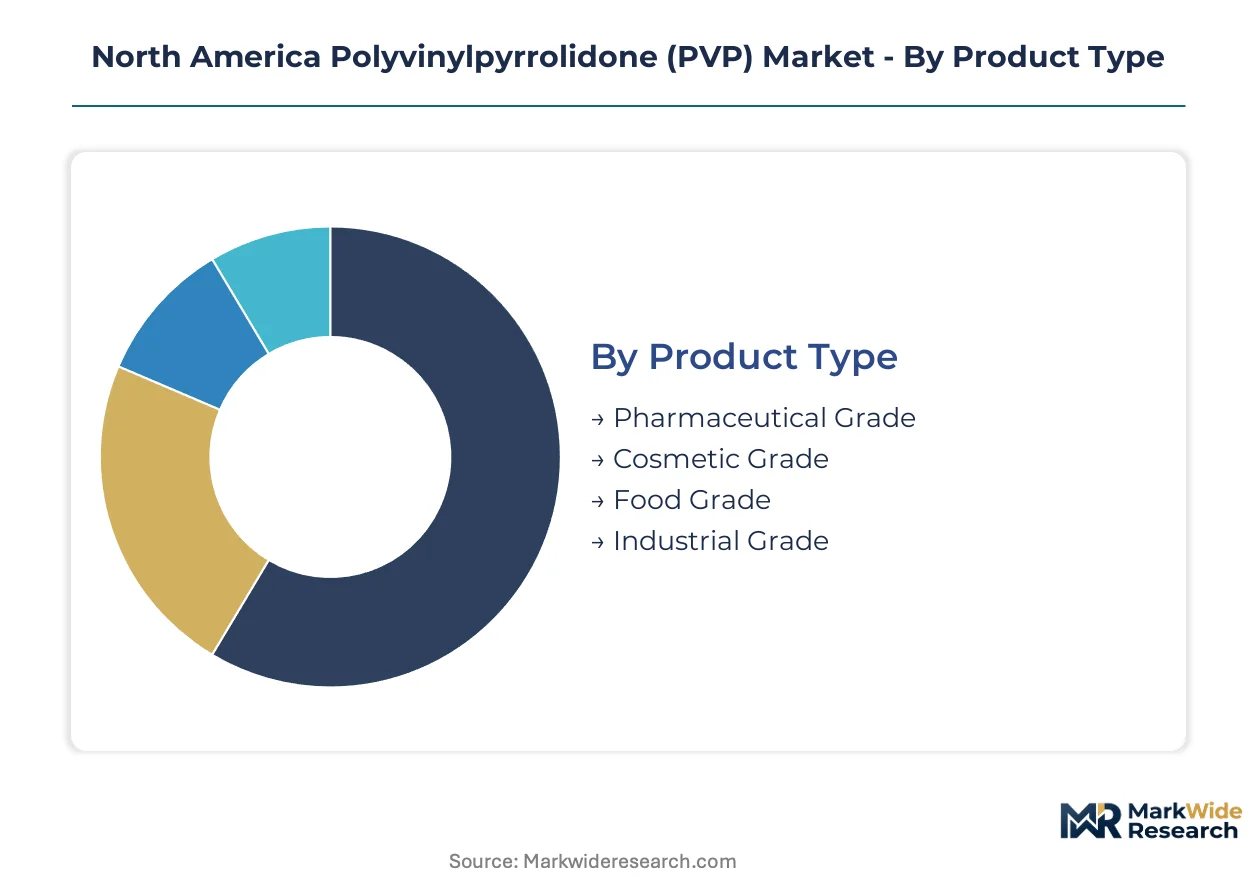
PVP grade specifications determine channel access and margin capture across North American supply chains. Pharmaceutical and industrial applications pull material through fundamentally different procurement pathways with distinct compliance burdens.
Product Type:
Pharmaceutical-grade material flows through qualified distributor networks with FDA documentation, while industrial grades move via bulk chemical wholesalers competing on volume pricing.
- Pharmaceutical Grade:Excipient purity validated under USP-NF monographs and ICH Q3D elemental impurity guidelines. Demand clusters in New Jersey and Massachusetts tablet manufacturing corridors where FDA pre-approval inspection timelines favor pre-qualified suppliers.
- Cosmetic Grade:K-15 through K-30 molecular weight grades formulated into clean-label serums and hair styling products. Reformulation away from petrochemical alternatives accelerates volume growth fastest among personal care brands in California and Ontario.
- Food Grade:PVP-Iodine complexes and film-forming additives meeting FCC specifications for beverage clarification and packaging adhesives.
- Industrial Grade:Adhesive binders, textile sizing agents, and coating formulations where K-60 and K-90 grades compete on scale economics.
Pharmaceutical Grade dominates installed base. Cosmetic Grade is where expansion concentrates.
Application:
Cost tier stratification separates validated pharmaceutical excipients from commodity personal care inputs, with pricing spreads reflecting qualification depth rather than raw material differentials.
- Pharmaceuticals:Tablet binders, film coatings, and controlled-release matrices requiring batch-specific CoA documentation. USP-grade validation creates structural barriers for non-integrated suppliers lacking dedicated regulatory affairs teams.
- Hair Care:Fixative polymers in styling sprays and conditioning agents where K-30 and K-90 grades provide humidity resistance. Reformulation trends favor PVP over synthetic alternatives in professional salon channels.
- Personal Care:Serum formulations and cosmetic delivery systems utilizing low-molecular-weight grades for skin adhesion and moisture retention.
- Food Additives:Clarification aids in brewing and wine production, plus packaging adhesive components meeting indirect food contact standards.
Pharmaceuticals command premium positioning. Hair Care is climbing the fastest.
End User:
Customer type determines technical service intensity, with pharmaceutical companies demanding formulation support that commodity chemical buyers rarely require.
- Pharmaceutical Companies:Generic tablet manufacturers and specialty dosage form developers in Pennsylvania and North Carolina consolidating supplier panels to reduce audit burdens. Electronic batch record compatibility now gates vendor qualification.
- Cosmetic Manufacturers:Clean-label personal care brands and contract manufacturers reformulating away from petrochemical-derived film formers.
- Food Industry:Beverage producers and packaging converters utilizing PVP-Iodine complexes for antimicrobial applications.
- Chemical Industry:Adhesive compounders and textile finishers purchasing industrial-grade material on specification sheets rather than validated CoA protocols.
Pharmaceutical Companies anchor procurement volume. Cosmetic Manufacturers are gaining share fastest.
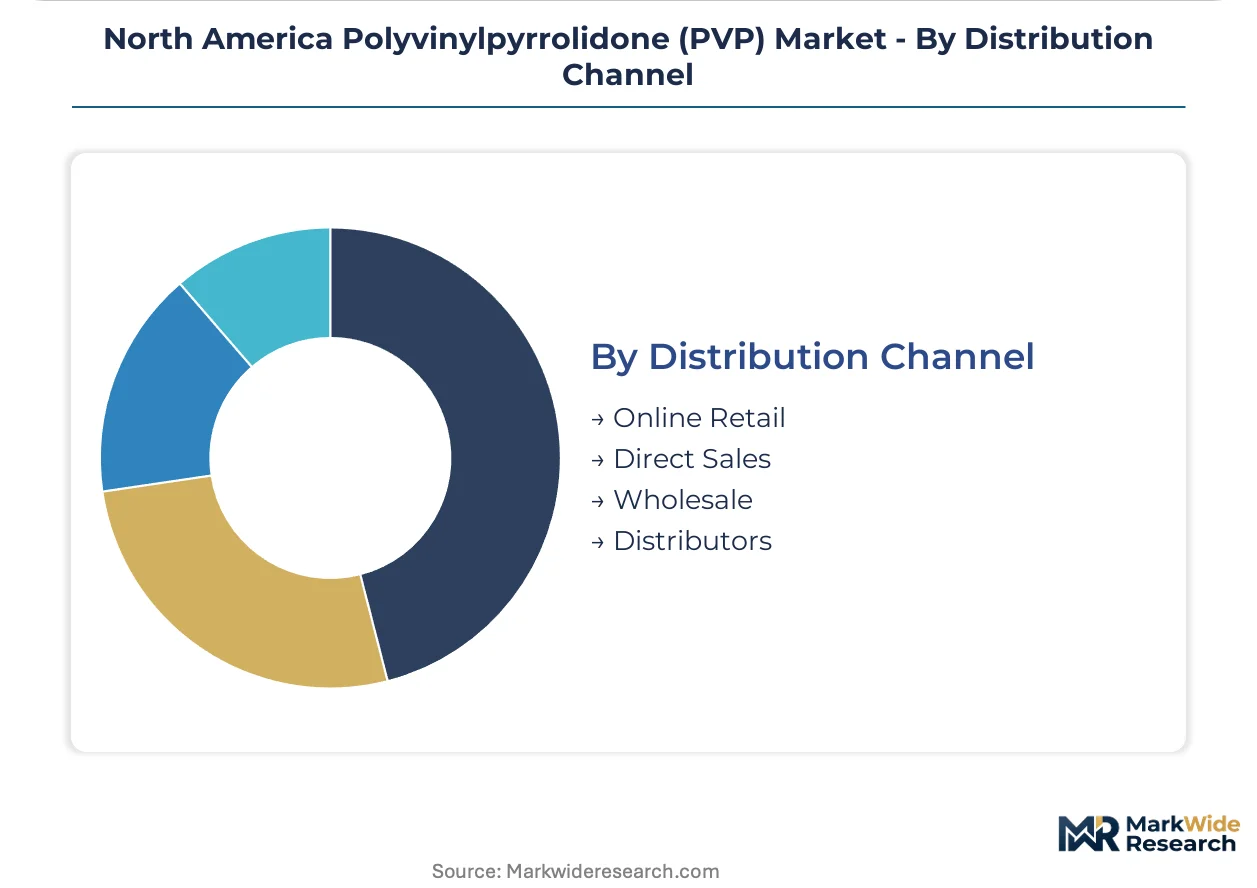
Distribution Channel:
Supply concentration shapes channel viability, with integrated manufacturers bypassing traditional distributors where technical service capabilities justify direct relationships.
- Direct Sales:Technical service teams co-located with pharmaceutical formulators in the U.S. Northeast corridor. Life-science procurement teams increasingly bypass distributors for qualified excipient supply.
- Distributors:Regional chemical distributors serving mid-tier cosmetic and industrial accounts with inventory positioning and logistics coordination.
- Wholesale:Bulk volume transactions for industrial-grade material moving through Great Lakes chemical trading hubs.
- Online Retail:Small-volume cosmetic and research-grade procurement through specialized chemical marketplaces with digital CoA delivery.
Direct Sales dominates pharmaceutical-grade flow. Distributors retain industrial-grade positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers in New Jersey and Massachusetts absorb price premiums without volume elasticity, while industrial compounders in the Great Lakes corridor treat PVP as a commodity input with high substitution sensitivity.
United States
Tablet manufacturers in Pennsylvania and North Carolina consolidate supplier panels to reduce audit burdens, while specialty dosage form developers in Greater Boston adopt ultra-low molecular weight grades for nanosuspension delivery. FDA excipient purity guidelines under USP-NF monographs extend qualification timelines for cross-border shipments. The Northeast pharmaceutical corridor spanning New Jersey and Massachusetts anchors North American pharmaceutical-grade demand.
Canada
Ontario and Quebec manufacturing clusters show lower PVP penetration rates than the U.S. Northeast, creating whitespace for suppliers with Health Canada pre-qualification. Health Canada's ICH Q3D impurity standards and PMRA chemical oversight elevate compliance costs for imported material. Toronto-area contract manufacturers are expanding clean-label personal care production utilizing K-15 through K-30 grades.
Mexico
Industrial adhesive compounders in Nuevo León and the Bajío Region source K-60 and K-90 grades through bulk chemical trading channels with minimal validation requirements. Mexico's national chemical safety regulator enforces evolving standards for N-vinylpyrrolidone monomer residuals in imported material. Mexico City Metro cosmetic manufacturers are reformulating hair care products away from petrochemical-derived film formers.
North America Polyvinylpyrrolidone (PVP) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America PVP landscape. Integrated manufacturers with captive monomer supply and dedicated regulatory affairs teams command pharmaceutical-grade contracts, while non-integrated distributors compete on inventory positioning for industrial accounts. The market structure stratifies into three tiers: global chemical conglomerates with multi-regional technical centers, mid-cap specialists with Health Canada or FDA pre-qualification, and regional distributors serving commodity cosmetic and industrial demand. Dominant competitive moves include backward integration into monomer recovery systems and consolidation of electronic batch record compatibility to meet pharmaceutical customer mandates.
Within the integrated manufacturer tier, Ashland Global Holdings Inc., BASF SE, and Merck KGaA occupy positions defined by regulatory infrastructure depth rather than unit pricing. Ashland exemplifies the captive supply archetype through high-purity grade availability, BASF represents sustained R&D intensity at dedicated North American technical facilities, and Merck KGaA anchors channel control capabilities in life-science distribution networks. These three companies collectively illustrate how qualification depth gates access to pharmaceutical-grade margin pools.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc. |
| BASF SE |
| Nippon Shokubai Co., Ltd. |
| Merck KGaA |
| Thermo Fisher Scientific |
| Hangzhou Motto Science & Technology Co., Ltd. |
| Boai NKY Pharmaceuticals Ltd. |
| JH Nanhang Life Sciences Co., Ltd. |
| Alfa Aesar |
| Others |
Value Network & Pricing Analysis
Captive monomer recovery capacity at integrated German and US Gulf Coast facilities sets minimum viable scale for pharmaceutical-grade participation, compressing price floors for non-integrated distributors while concentrating margin capture among producers with in-house N-vinylpyrrolidone supply. This scale asymmetry funnels high-purity volumes through qualified direct channels and pushes commodity grades toward bulk chemical wholesalers competing on inventory turns.
Pricing Analysis
FDA excipient validation protocols dictate the pricing tier structure across North American PVP supply, with USP-NF certified pharmaceutical grades commanding substantial premiums over cosmetic and industrial equivalents. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial levels separates validated excipients with batch-specific CoA documentation from specification-grade material moving through distributor channels. Cost compression in industrial-grade supply is intensifying because cellulose derivative substitutes are capturing tablet disintegration applications where performance requirements permit. Generic pharmaceutical manufacturers in Pennsylvania exhibit lowest price sensitivity due to audit burden reduction priorities, while adhesive compounders in Mexico's Bajío Region treat K-60 and K-90 grades as fully fungible commodity inputs.
Supply Chain Analysis
Detroit and Buffalo port clearance capacity acts as the primary chokepoint for imported pharmaceutical-grade material awaiting EPA TSCA Section 6 residual evaluation outcomes. Manufacturing concentration centers on Germany, the United States, and Japan for high-purity grades, while China and South Korea feed industrial-grade volume through bulk chemical trading channels. Feedstock exposure rests on N-vinylpyrrolidone monomer pricing set by integrated acetylene chemistry producers, with vinyl acetate co-product economics influencing regional cost curves. Single-source vulnerability runs through Health Canada pre-qualification bottlenecks for Ontario and Quebec manufacturing clusters seeking reduced cross-border shipment delays. Distribution runs through direct technical service teams for pharmaceutical accounts and regional chemical distributors for cosmetic and industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for formulation support and regulatory documentation are expanding faster than base chemical volumes as pharmaceutical customers consolidate supplier panels and outsource excipient qualification burdens. This service-layer growth justifies capability investments that commodity distributors cannot replicate.
For Market Incumbents: Shield pharmaceutical-grade margin pools by accelerating Health Canada pre-qualification documentation for Ontario and Quebec manufacturing corridors before smaller competitors achieve cross-border shipment parity. Backward integration into monomer recovery systems at US Gulf Coast and German manufacturing sites will defend against feedstock volatility while EPA TSCA residual evaluations threaten reformulation mandates for non-integrated suppliers. Electronic batch record compatibility investments will gate retention of mid-cap generic pharmaceutical accounts in Pennsylvania and North Carolina.
For New Entrants and Emerging Players: FDA fast-track excipient qualification programs for ultra-low molecular weight PVP grades offer the most penetrable entry vector into nanosuspension drug delivery applications serving New Jersey and Massachusetts specialty pharmaceutical developers. Underpenetrated Canadian pharmaceutical corridors in Toronto and Montreal present whitespace for suppliers willing to absorb Health Canada ICH Q3D compliance costs that deter mid-tier distributors. Direct-to-formulator digital platforms with automated CoA delivery can bypass entrenched distributor relationships in cosmetic-grade segments where technical service requirements remain minimal.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive monomer supply and dedicated North American regulatory affairs teams over non-integrated distributors facing structural margin compression. Long-term viability across the projection horizon rests on qualification depth rather than unit pricing power, making Health Canada and FDA pre-qualified production assets the priority acquisition archetype. The signal to monitor is EPA TSCA Section 6 risk evaluation outcomes for N-vinylpyrrolidone residuals, which would trigger supply chain requalification cycles favoring integrated producers with in-house recovery systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Recovery | Captive N-vinylpyrrolidone supply insulates margin pools from feedstock volatility and EPA residual scrutiny. |
| Health Canada Pre-Qualification Investment | Regulatory documentation for Ontario and Quebec corridors opens whitespace before competitor entry. |
| Electronic Batch Record System Deployment | FDA data integrity protocol compatibility gates retention of consolidated pharmaceutical supplier panels. |
| Ultra-Low Molecular Weight Grade Development | Controlled free-radical polymerization capabilities access nanosuspension delivery growth in Greater Boston. |
| Direct-to-Formulator Digital Platform Launch | Automated CoA delivery and technical service portals bypass distributor intermediaries in cosmetic segments. |
Research Methodology
Operator-level perspectives from pharmaceutical formulation scientists, excipient procurement managers at generic manufacturers, regulatory affairs directors, and cosmetic contract manufacturing executives anchored the qualitative base for this analysis. Primary interview findings were cross-validated against FDA 483 inspection observations, Health Canada ICH Q3D guidance documents, EPA TSCA chemical data reporting filings, and USP-NF monograph revisions. Bottom-up volume estimates from grade-specific demand segments were reconciled with top-down trade flow analysis through Detroit, Buffalo, and Laredo port facilities.
Sensitivity analysis around EPA risk evaluation timing and Health Canada pre-qualification throughput informed scenario-weighted projections across the analysis window. Segmentation modeling incorporated pharmaceutical grade tier, cosmetic molecular weight specification, end-use application, and distribution channel structure as core dimensions. CAGRs were derived from fitted growth curves calibrated to historical excipient adoption patterns and regulatory approval cycle durations. Forecast inputs included N-vinylpyrrolidone monomer pricing indices, pharmaceutical customer consolidation rates, and clean-label personal care reformulation velocities.
The analysis sits within stated boundaries; outcomes outside maintained FDA excipient validation timelines and stable EPA TSCA enforcement posture would require recalibration. Forecasts reflect documented assumptions regarding Health Canada inspection capacity expansion and sustained US Northeast pharmaceutical corridor investment levels. Practitioners should keep alternative scenarios live as EPA N-vinylpyrrolidone residual evaluation outcomes and Canadian regulatory harmonization initiatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
PE Resins Market