
 Europe Geopolymer Market | 2026-2036
Europe Geopolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Geopolymer Market Intelligence
Performance-grade geopolymer formulations is bifurcating the Europe market between specification-driven infrastructure contracts and cost-sensitive precast applications. Betolar Plc anchors its position through proprietary alkali-activation technology optimized for industrial byproduct feedstocks. České lupkové závody a.s. dominates Central European supply of metakaolin precursors with vertically integrated quarry-to-plant operations. PCI Augsburg GmbH specializes in ready-mix delivery systems that extend contractor adoption without capital-intensive batching investments.
Geopolymers are inorganic aluminosilicate binders formed through alkali-activation of pozzolanic materials such as fly ash or metakaolin, yielding ceramic-like matrices with compressive strengths exceeding 50 MPa and fire resistance above 1000°C. Their primary purpose is to replace Portland cement in structural concrete, precast elements, and refractory linings while eliminating calcium carbonate calcination emissions. Fly ash-based formulations occupy the largest volume share given abundant power-plant residue availability across Poland and Germany, though metakaolin variants command premium positioning in aerospace and energy applications where ultra-low permeability and dimensional stability under thermal cycling justify higher precursor costs. Slag-derived geopolymers are accelerating fastest in Scandinavian markets where blast furnace availability from steelmaking clusters enables cost-competitive supply.
EU Green Deal carbon-border adjustments and the Construction Products Regulation's harmonized standards for alkali-activated cements are reshaping product certification requirements across member states. ECHA's REACH oversight of sodium silicate activators and the F-Gas Regulation's indirect pressure on energy-intensive cement kilns both expand geopolymer's regulatory tailwinds. France's national building code recognition of geopolymers under DTU standards and Germany's DIBt approvals for structural applications provide template pathways for harmonized market access. Stakeholders must monitor whether forthcoming EU taxonomy thresholds for construction materials will embed geopolymer-specific carbon-intensity benchmarks that lock in preferential procurement status.
Market Dynamics
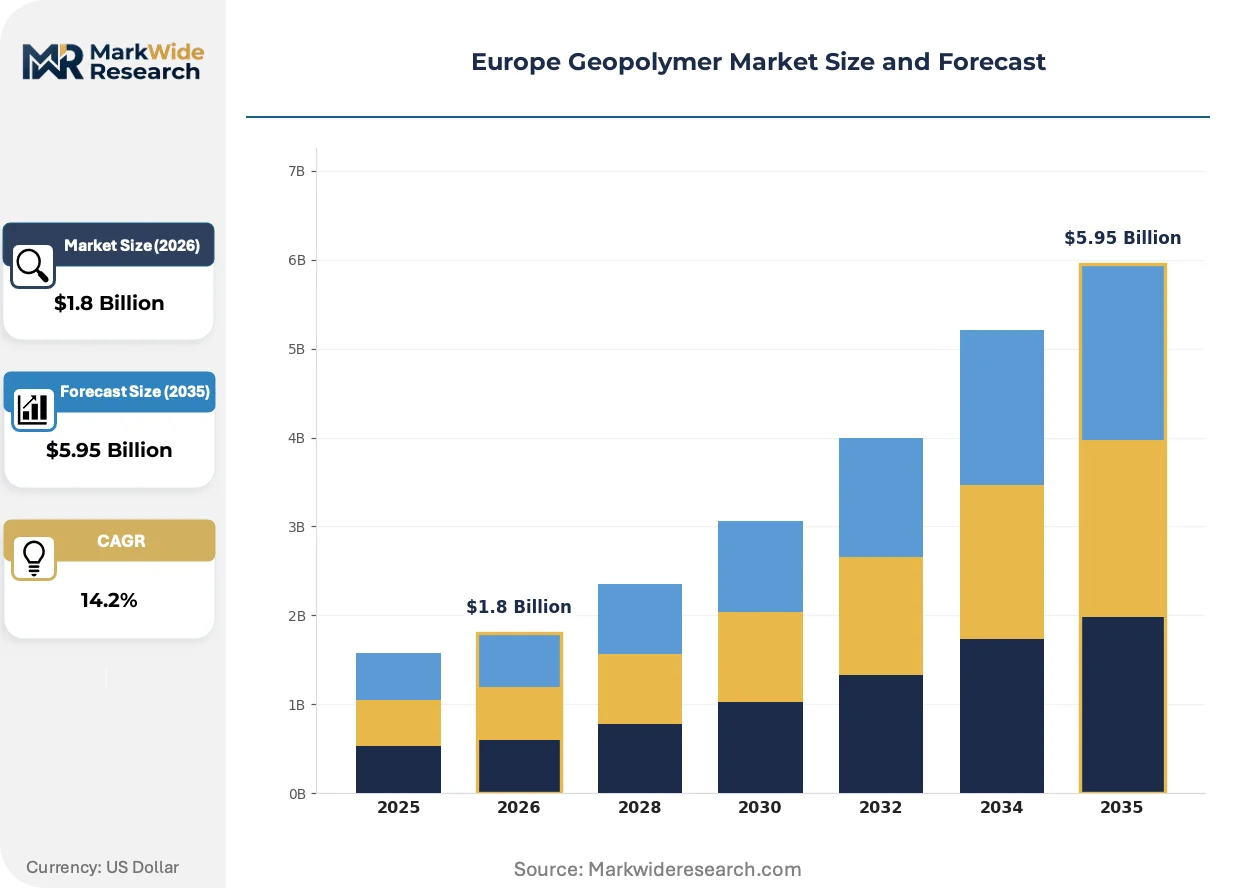
EU Green Deal carbon-border adjustments are compressing Portland cement's cost advantage while Construction Products Regulation harmonization is unlocking public procurement pathways for alkali-activated binders across member states.
Growth Catalysts
- EU Green Deal embodied carbon targets:Mandatory carbon-intensity thresholds for construction materials in public tenders are accelerating specification of low-carbon binders in French and German infrastructure contracts.
- Industrial byproduct feedstock abundance:Coal-phaseout timelines across Poland and Germany are concentrating fly ash availability near geopolymer production clusters, reducing precursor logistics costs.
- Metakaolin quarry-to-plant integration:Vertically controlled kaolin deposits in the Czech Republic and Ukraine are securing precursor supply chains for high-performance formulations serving energy-sector applications.
Market Restraints
- Sodium silicate activator cost volatility:Energy-intensive production of sodium silicate solution exposes geopolymer economics to natural gas price swings in German and Dutch chemical manufacturing corridors.
- Blast furnace slag supply concentration:Scandinavian geopolymer output depends on captive steelmaking residues from SSAB and ArcelorMittal Nordic clusters, creating single-source vulnerability.
- REACH registration timelines:ECHA's substance evaluation protocols for novel alkali-activated formulations extend product certification cycles beyond typical construction material approval windows.
Strategic Opportunities
- Portuguese and Spanish infrastructure rehabilitation:Aging bridge stock and EU cohesion fund allocations for Iberian transport networks are opening specification-driven demand for geopolymer concrete in corrosion-prone marine environments.
- CSRD-aligned embodied carbon disclosure:Corporate sustainability reporting mandates are forcing construction contractors to document supply-chain emissions, creating procurement preference for EPD-certified geopolymer products.
- Precast element 3D printing convergence:Integration of alkali-activated binders with robotic extrusion systems is enabling geometrically complex facade elements without formwork capital intensity.
Industry Challenges
- Alkali-activation chemistry expertise scarcity:Formulation optimization requires specialized knowledge of Si/Al ratios and modulus control that sits outside conventional concrete technology training programs.
- DIBt and DTU certification fragmentation:Divergent national technical approval pathways between German DIBt structural assessments and French DTU masonry standards complicate cross-border product harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Geopolymer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash, Metakaolin, Slag, Others Application: Construction, Automotive, Aerospace, Energy End User: Manufacturers, Contractors, Suppliers, Research Institutions Delivery Mode: Ready-Mix, Prefabricated, On-Site, Others |
| Companies Covered | České lupkové závody a.s., Gement Ltd, Banah UK Ltd, PCI Augsburg GmbH, MITSUI & CO., LTD., Betolar Plc, Critica Infrastructure, Pyromeral Systems, CEMEX S.A.B. de C.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Geopolymer Market Strategic Shifts & Innovations
Formulation chemistry advances and regulatory carbon accounting are converging to reposition geopolymer binders from niche refractory applications to mainstream structural concrete substitution.
Low-calcium fly ash-based geopolymer systems are supplanting slag-blended Portland cements in Dutch precast tunnel segments. Royal BAM Group and Heijmans Infrastructure have specified these formulations for Rotterdam metro extensions, compressing embodied carbon benchmarks by eliminating calcium carbonate calcination entirely from supply-chain emissions calculations.
France's DTU 26.1 standard revision incorporating alkali-activated binders is mandating performance-based specifications for public works contracts. The regulatory change is compelling regional engineering consultancies to develop geopolymer-specific mix design protocols, with Bouygues Construction and Eiffage deploying trained specification teams across Grand Est and Hauts-de-France project portfolios.
Contractor procurement departments are consolidating supplier relationships around EPD-verified product lines. French and German infrastructure buyers are disintermediating traditional ready-mix intermediaries to contract directly with geopolymer specialists offering batch-plant technical assistance, with this channel compression most visible in Bavarian and Rhône-Alpes highway rehabilitation frameworks.
Europe Geopolymer Market Segmentation
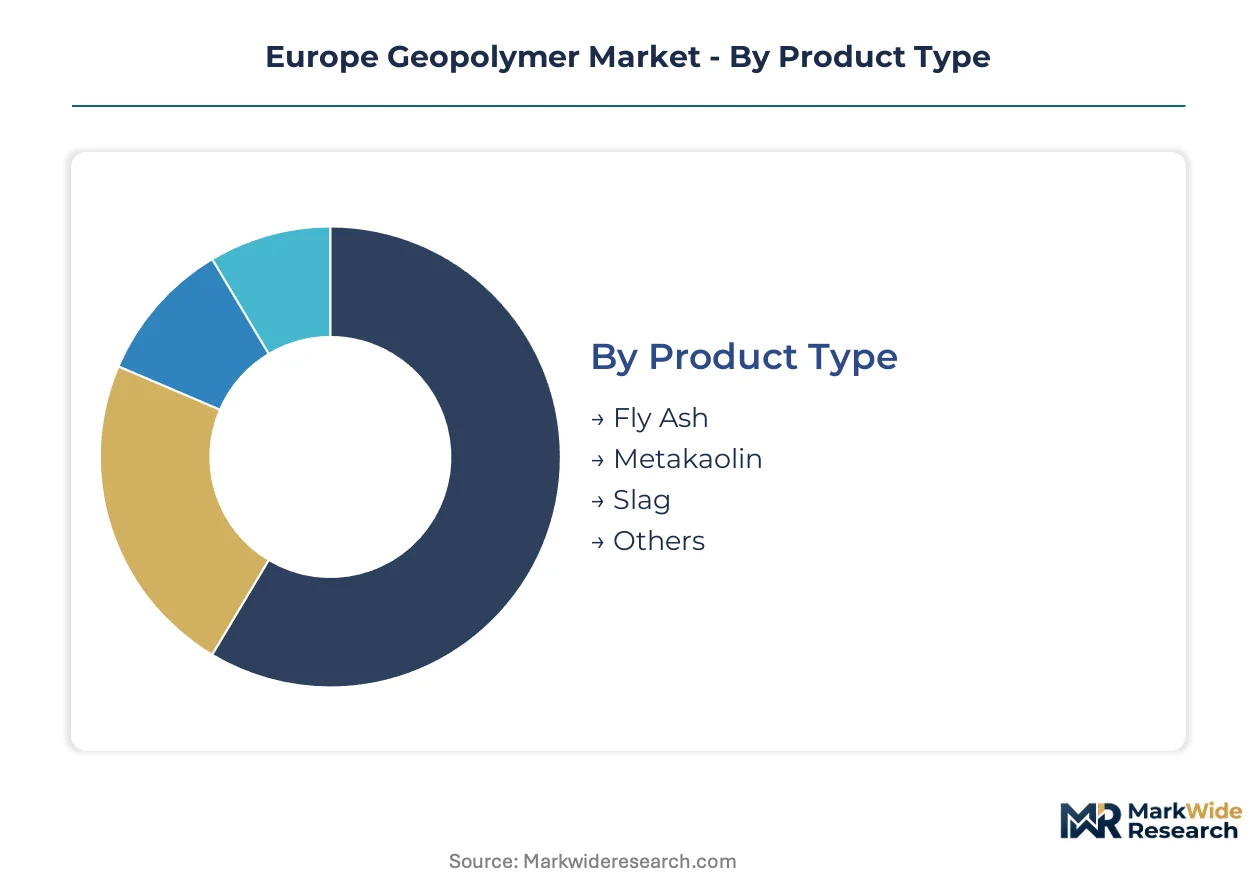
Geopolymer market segmentation reflects divergent supply chain configurations across Europe, with precursor availability and regulatory recognition shaping regional specialization patterns. Each dimension captures distinct commercial dynamics from feedstock logistics to contractor procurement behaviors.
Product Type:
Fly ash formulations dominate procurement in Poland and Germany where coal-phaseout concentrates residue availability near industrial clusters, while metakaolin variants serve export-oriented aerospace and energy contracts from Czech and Ukrainian quarries.
- Fly Ash:Coal-combustion residues activated with sodium silicate yield cost-competitive binders for infrastructure-scale concrete. German and Polish contractors specify these formulations for bridge rehabilitation where embodied carbon thresholds under EU Green Deal procurement rules eliminate Portland cement alternatives. Logistics integration with power plant decommissioning sites compresses precursor delivery costs.
- Metakaolin:Thermally processed kaolin clays deliver ultra-low permeability matrices for thermal cycling applications. Czech vertical integration from quarry to activation plant secures supply chains for French energy-sector specifications where dimensional stability under extreme temperatures justifies premium positioning.
- Slag:Blast furnace residues from SSAB and ArcelorMittal Nordic clusters enable Scandinavian production economics.
- Others:Rice husk ash and volcanic tuff variants serve niche refractory and marine applications in Italian and Greek markets.
Fly ash holds the largest share; momentum sits with slag as steelmaking decarbonization concentrates residue availability.
Application:
Construction absorbs volume through public infrastructure frameworks, while aerospace and energy applications command margin premiums through performance-based specifications.
- Construction:Structural concrete and precast elements for tunnels, bridges, and building frames constitute the foundational demand base. Dutch precast tunnel segments from Royal BAM Group and Heijmans Infrastructure deployments demonstrate specification-driven adoption where Rotterdam metro extensions mandate carbon-intensity compliance.
- Energy:Refractory linings and geothermal well cements exploit geopolymer thermal resistance above 1000°C. French nuclear maintenance contracts and Icelandic geothermal expansion projects specify metakaolin formulations for dimensional stability under thermal shock.
- Automotive:Lightweight composite panels and fire-resistant battery housings serve electric vehicle manufacturing clusters in Bavaria and Styria.
- Aerospace:High-temperature insulation and ablative coatings for propulsion systems concentrate in Toulouse and Munich supplier networks.
Construction commands volume concentration; aerospace delivers steepest expansion trajectory through performance-premium positioning.
End User:
Contractor procurement departments are consolidating direct relationships with geopolymer specialists, disintermediating traditional ready-mix channels in French and German highway frameworks.
- Contractors:Infrastructure builders across Grand Est and Hauts-de-France deploy trained specification teams following DTU 26.1 standard revisions. Bouygues Construction and Eiffage maintain dedicated geopolymer mix design protocols for public works tenders.
- Manufacturers:Precast element producers in Bavaria and Rhône-Alpes integrate alkali-activated binders with robotic extrusion systems for geometrically complex facade components.
- Suppliers:Feedstock and activator distributors manage sodium silicate logistics from German and Dutch chemical manufacturing corridors.
- Research Institutions:Technical universities in Delft, Stuttgart, and Lyon advance formulation chemistry for Si/Al ratio optimization and modulus control.
Contractors drive specification authority; manufacturers are gaining procurement influence through precast integration investments.
Delivery Mode:
Ready-mix systems extend contractor adoption without capital-intensive batching investments, while prefabricated elements capture value through manufacturing precision.
- Ready-Mix:Centralized batching with technical assistance from specialists like PCI Augsburg GmbH enables contractor adoption without dedicated plant capital. German highway rehabilitation frameworks favor this model for project-specific volume flexibility.
- Prefabricated:Factory-controlled curing environments ensure consistent compressive strength exceeding 50 MPa for structural certification. Dutch tunnel segment production demonstrates scale economics through automated casting lines.
- On-Site:Mobile batching serves remote infrastructure locations in Norwegian fjord crossings and Alpine tunnel portals.
- Others:Hybrid delivery combining prefabricated shells with on-site infill addresses complex geometries in heritage restoration.
Ready-mix maintains accessibility leadership; prefabricated delivery is climbing fastest through manufacturing quality guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precursor availability clusters geopolymer production around industrial corridors in Germany, France, the Netherlands, the Czech Republic, and Scandinavia. Regulatory recognition under national building codes is accelerating specification in public infrastructure frameworks. Each national market exhibits distinct supply chain configurations tied to feedstock logistics and certification pathways.
Germany
Bridge rehabilitation and tunnel lining projects drive procurement volumes in Bavarian and North Rhine-Westphalian construction corridors. DIBt approvals for structural geopolymer applications provide template certification pathways for alkali-activated binders in federal highway frameworks. PCI Augsburg GmbH anchors ready-mix delivery systems that extend contractor adoption without dedicated batching plant investments.
France
DTU 26.1 standard revisions mandate performance-based specifications for public works contracts across Grand Est and Hauts-de-France. Bouygues Construction and Eiffage maintain dedicated specification teams following regulatory changes that embed geopolymer compliance in national procurement frameworks. Rhône-Alpes precast manufacturers integrate robotic extrusion systems for geometrically complex facade elements.
Netherlands
Rotterdam metro extensions specify low-carbon precast tunnel segments from Royal BAM Group and Heijmans Infrastructure deployments. Embodied carbon disclosure requirements under CSRD-aligned procurement rules force documentation of supply-chain emissions for construction materials. Eindhoven-region engineering consultancies develop mix design protocols for alkali-activated binder optimization.
Czech Republic
Vertically integrated metakaolin supply chains from quarry-to-activation operations serve French energy-sector specifications requiring ultra-low permeability. České lupkové závody a.s. controls precursor extraction and thermal processing for high-performance formulations. Ukrainian kaolin deposit access secures feedstock redundancy for thermal cycling applications in aerospace and nuclear maintenance contracts.
Scandinavia
Blast furnace slag from SSAB and ArcelorMittal Nordic clusters enables cost-competitive geopolymer production in Swedish and Finnish markets. Norwegian fjord crossing projects deploy mobile batching for remote infrastructure locations. Icelandic geothermal expansion specifies metakaolin formulations for dimensional stability under thermal shock in well cementing applications.
Europe Geopolymer Market Key Industry Players
Concentration sits with specialized alkali-activation technology developers and vertically integrated precursor suppliers rather than diversified construction material conglomerates. The competitive terrain bifurcates between specification-driven infrastructure contractors demanding technical assistance and cost-optimized precast manufacturers seeking feedstock security. Three archetypes dominate: proprietary formulation developers, captive feedstock controllers, and ready-mix delivery system specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure precursor supply chains and extend geographic coverage.
Within the proprietary technology tier, Betolar Plc and Pyromeral Systems exemplify formulation developers optimizing industrial byproduct activation. Among vertically integrated suppliers, České lupkové závody a.s. occupies a position anchored to captive metakaolin deposits. PCI Augsburg GmbH represents the delivery-system specialization archetype, extending market access through technical assistance models that reduce contractor adoption barriers.
| Leading Market Players |
|---|
| České lupkové závody a.s. |
| Gement Ltd |
| Banah UK Ltd |
| PCI Augsburg GmbH |
| MITSUI & CO., LTD. |
| Betolar Plc |
| Critica Infrastructure |
| Pyromeral Systems |
| CEMEX S.A.B. de C.V. |
| Others |
Cost & Logistics Intelligence
Portland cement substitution by alkali-activated binders simultaneously redistributes supply geography toward industrial byproduct clusters and compresses pricing premiums previously commanded by specialty formulations. This dual restructuring concentrates procurement leverage with contractors who control feedstock logistics near coal-phaseout sites and steelmaking corridors.
Pricing Analysis
The EU Green Deal's carbon-border adjustment mechanism dictates the pricing tier structure across European geopolymer procurement. Three-tier pricing structure across premium metakaolin, standard slag-blend, and economy fly-ash levels separates aerospace energy applications from infrastructure concrete and mass precast segments. Cost compression in economy-tier formulations is intensifying because sodium silicate activator exposure to natural gas price volatility erodes margins in German and Dutch chemical manufacturing corridors. Public infrastructure contractors exhibit highest price sensitivity due to fixed-bid tender structures, while energy-sector buyers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Poland and Germany anchor fly-ash precursor harvesting from coal-phaseout concentration sites, while the Czech Republic and Ukraine control metakaolin quarry-to-activation operations. The supply chain draws from sodium silicate solution production, thermally processed kaolin clay deposits, and blast furnace slag from SSAB Nordic clusters. Single-source vulnerability concentrates around Scandinavian steelmaking residue dependence on ArcelorMittal and SSAB captive output. Distribution runs through ready-mix delivery specialists extending contractor access without dedicated batching capital, supplemented by prefabricated element channels for tunnel segment and facade component manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized alkali-activation chemistry expertise sits outside conventional concrete technology training programs, creating persistent capability gaps that constrain formulation optimization and quality assurance at scale. This scarcity dynamic shapes competitive positioning across proprietary technology developers, vertically integrated feedstock controllers, and technical assistance providers.
For Market Incumbents: Consolidate precursor supply security through backward integration into Czech kaolin deposits or captive arrangements with Polish coal-phaseout site operators. Deepen technical assistance capabilities to defend against ready-mix delivery specialists disintermediating traditional channel relationships. Prioritize DIBt and DTU certification harmonization investments to reduce cross-border product approval friction. For New Entrants and Emerging Players: Differentiate on mobile batching systems for remote infrastructure locations in Norwegian fjord crossings and Alpine tunnel portals where logistics complexity excludes established ready-mix competitors. Target Iberian bridge rehabilitation markets where EU cohesion fund allocations and marine corrosion exposure create specification-driven demand without entrenched supplier relationships. Pursue direct contractor engagement models bypassing traditional distribution intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed formulation developers holding proprietary alkali-activation IP but lacking feedstock vertical integration. Long-term viability hinges on whether EU taxonomy thresholds embed geopolymer-specific carbon-intensity benchmarks that institutionalize preferential procurement status. Watch for EPD certification consolidation signals indicating which technical assistance providers are capturing contractor specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metakaolin Deposits | Czech quarry-to-activation control secures supply chains for French energy-sector specifications. |
| Mobile Batching Capability Deployment | Norwegian fjord and Alpine tunnel projects demand remote infrastructure logistics solutions. |
| DIBt/DTU Certification Harmonization | Cross-border product approval streamlines access to German and French public procurement frameworks. |
| EPD Verification Program Expansion | CSRD-aligned disclosure mandates force contractor documentation of supply-chain emissions. |
| Sodium Silicate Supply Security | Natural gas price exposure in German-Dutch chemical corridors threatens activator cost stability. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU customs trade data, ECHA REACH registration filings, national building code revisions, and construction sector EPD databases. Primary engagement spans formulation chemists at alkali-activation technology developers, procurement directors at French and German infrastructure contractors, plant managers at Czech metakaolin processing facilities, and regulatory affairs leads navigating DIBt and DTU certification pathways. Bottom-up volume estimates from precursor production clusters and top-down demand assessments from public tender databases were cross-validated to establish market sizing.
Segmentation dimensions modeled encompass precursor type, application sector, end-user procurement authority, and delivery mode configuration across the projection horizon. CAGRs were derived from trend extrapolation of specification-driven infrastructure contract awards, carbon-intensity compliance adoption curves, and feedstock availability trajectories tied to coal-phaseout timelines. Industry-specific forecast inputs include sodium silicate cost sensitivity to natural gas pricing and blast furnace slag output correlation with steelmaking decarbonization pathways.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, REACH registration timeline stability, and coal-phaseout schedule adherence would require recalibration. Forecasts reflect documented assumptions regarding carbon-border adjustment implementation and national building code revision momentum. Recalibration cycles align with material shifts in ECHA substance evaluation protocols and EU taxonomy construction material threshold determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market