
 North America Activated Carbon Market | 2026-2036
North America Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
North America Activated Carbon Market Intelligence
Asset-light leasing models for mobile carbon filtration units is reconfiguring competitive dynamics for mid-size water treatment contractors. Ingevity Corporation leverages its integrated supply chain from raw material sourcing through reactivation services to sustain margin stability across volatile feedstock cycles. Calgon Carbon Corporation anchors its position through extensive reactivation facility networks that reduce customer total cost of ownership. Evoqua Water Technologies LLC differentiates by combining carbon supply with digital monitoring platforms that optimize replacement scheduling.
Activated carbon consists of highly porous carbonaceous material processed to achieve internal surface areas exceeding 500 square meters per gram, manufactured through steam or chemical activation of coconut shell, coal, or wood precursors. Its primary industrial purpose centers on adsorbing organic contaminants, chlorine compounds, and volatile chemicals from liquid and gas streams. Granular activated carbon dominates municipal water treatment installations due to lower pressure drop and regeneration compatibility, while powdered activated carbon captures faster growth in mercury emissions control at power generation facilities. Extruded activated carbon occupies specialized niches in air purification systems where uniform particle size prevents channeling.
EPA regulations under the Safe Drinking Water Act and Clean Air Act shape product specifications and demand timing across the United States, while Health Canada guidelines influence quality thresholds for cross-border suppliers. The EPA's Stage 2 Disinfectants and Disinfection Byproducts Rule forces utilities toward higher-iodine-number carbons, and pending coal combustion residual classifications may expand activated carbon injection mandates. Stakeholders must monitor reactivation capacity expansion decisions against virgin carbon price spreads to optimize procurement strategies.
Market Dynamics
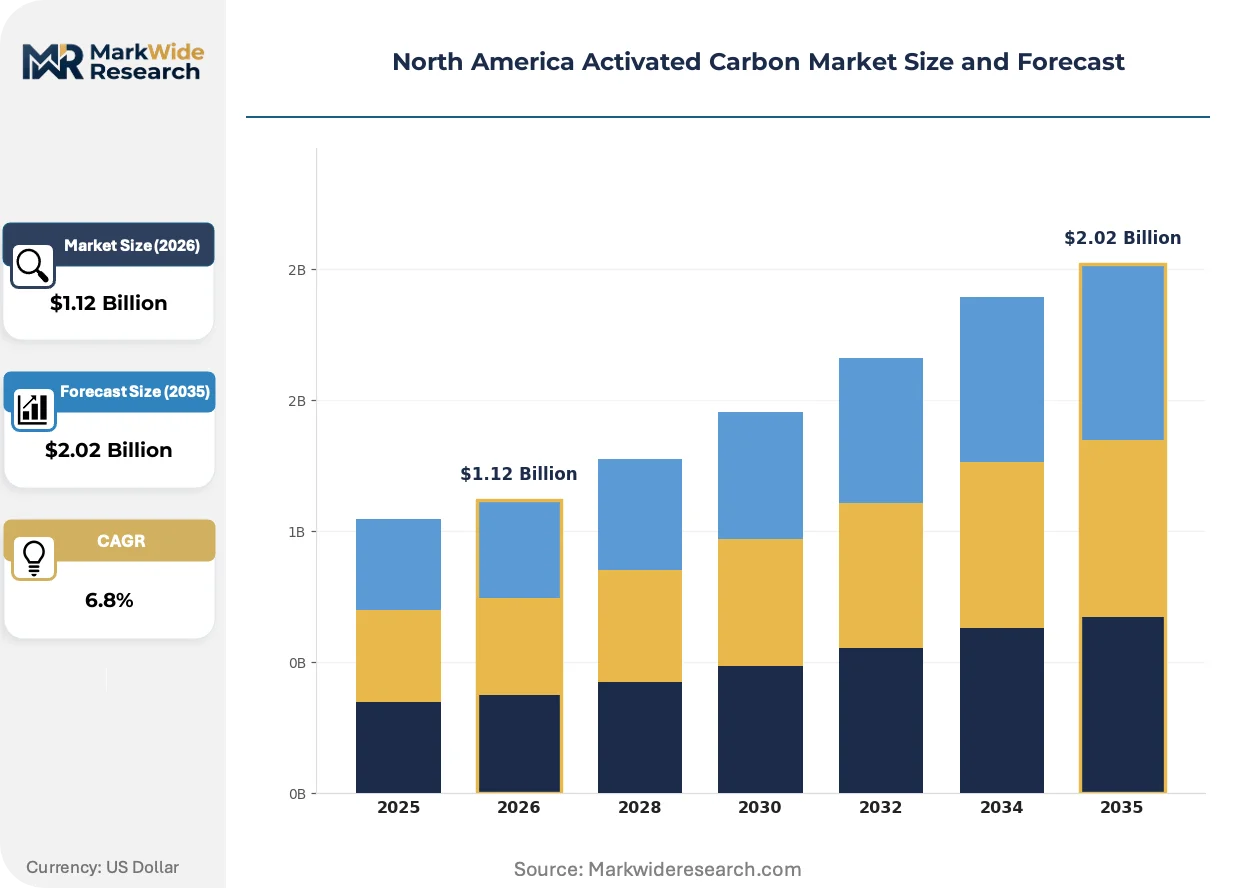
The North America activated carbon market is being restructured by the EPA's Stage 2 Disinfectants and Disinfection Byproducts Rule, which mandates higher-iodine-number carbons and accelerates replacement cycles across thousands of municipal water systems.
Growth Catalysts
- Coal Combustion Residuals Classification:Pending EPA designations for coal ash handling are expanding mandates for powdered activated carbon injection systems at power generation facilities.
- Petrochemical Corridor Concentration:The US Gulf Coast's refinery and chemical processing cluster drives continuous demand for virgin and reactivated carbon in solvent recovery and purification operations.
- Mercury and Air Toxics Standards:MATS compliance deadlines force coal-fired utilities to maintain permanent powdered activated carbon infrastructure for stack gas treatment.
Market Restraints
- Coconut Shell Feedstock Volatility:Typhoon disruptions in Southeast Asian sourcing regions create price spikes and supply uncertainty for high-iodine-number granular products.
- Reactivation Capacity Concentration:Limited North American reactivation facility networks force customers into long-haul logistics or virgin carbon dependence.
- Zeolite Molecular Sieve Substitution:Natural gas processing operators are substituting zeolites for activated carbon in specific dehydration applications.
Strategic Opportunities
- PFAS Contamination Response:Emerging state-level mandates for per- and polyfluoroalkyl substances removal in drinking water are creating demand for specialized carbon blends and treatment system retrofits.
- Mobile Filtration Leasing:Asset-light rental models for temporary carbon treatment units address seasonal industrial discharge events and emergency response scenarios.
- Digital Monitoring Convergence:Integration of IoT sensors with carbon bed performance tracking enables predictive replacement scheduling and reduces unplanned downtime.
Industry Challenges
- Reactivation Technician Shortage:Specialized furnace operations and quality control expertise for spent carbon regeneration are scarce across the US and Canada.
- Cross-Border Feedstock Certification:Health Canada guidelines for activated carbon in food contact and pharmaceutical applications create documentation burdens for US suppliers.
- Legacy Water Plant Retrofit Complexity:Municipal utilities with century-old infrastructure face space constraints and hydraulic compatibility issues when upgrading to granular activated carbon contactors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Activated Carbon Market |
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Activated Carbon, Powdered Activated Carbon, Extruded Activated Carbon, Impregnated Activated Carbon Application: Water Treatment, Air Treatment, Chemical Processing, Food & Beverage End User: Utilities, Pharmaceutical, Food Industry, Manufacturing Packaging Type: Bags, Drums, Totes, Bulk |
| Companies Covered | Jacobi Carbons AB, Haycarb PLC, Cabot Corporation, Ingevity Corporation, Carbon Activated Corporation, Calgon Carbon Corporation, Donau Carbon GmbH, Evoqua Water Technologies LLC, Kuraray Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Activated Carbon Market Strategic Shifts & Innovations
Advanced activation processes and digital service models are compressing replacement cycles while expanding addressable applications beyond traditional water and air treatment.
Steam-activated biochar derived from agricultural waste feedstocks is achieving surface area specifications competitive with coconut shell carbon. Food and beverage processors in California and the Pacific Northwest are piloting these materials for decolorization and odor control. Conventional coal-based activated carbon for low-specification applications is rendering obsolete as biochar supply scales and cost parity emerges.
The EPA's pending coal combustion residual classifications are forcing power generators to reassess activated carbon injection system permanence. Utilities operating subcritical coal units face accelerated MATS compliance timelines and are pre-positioning multi-year powdered carbon supply contracts. Coal ash landfill closure mandates in the Ohio River Valley are redirecting procurement toward suppliers with integrated reactivation services.
Leasing arrangements for mobile carbon filtration units are displacing capital purchases among mid-size industrial water treatment contractors. Equipment-as-a-service models bundle carbon supply, vessel deployment, and digital performance monitoring into single monthly fees. This shift is most visible in the Texas and Louisiana petrochemical corridor, where seasonal turnaround schedules favor flexible capacity over fixed installations.
North America Activated Carbon Market Segmentation
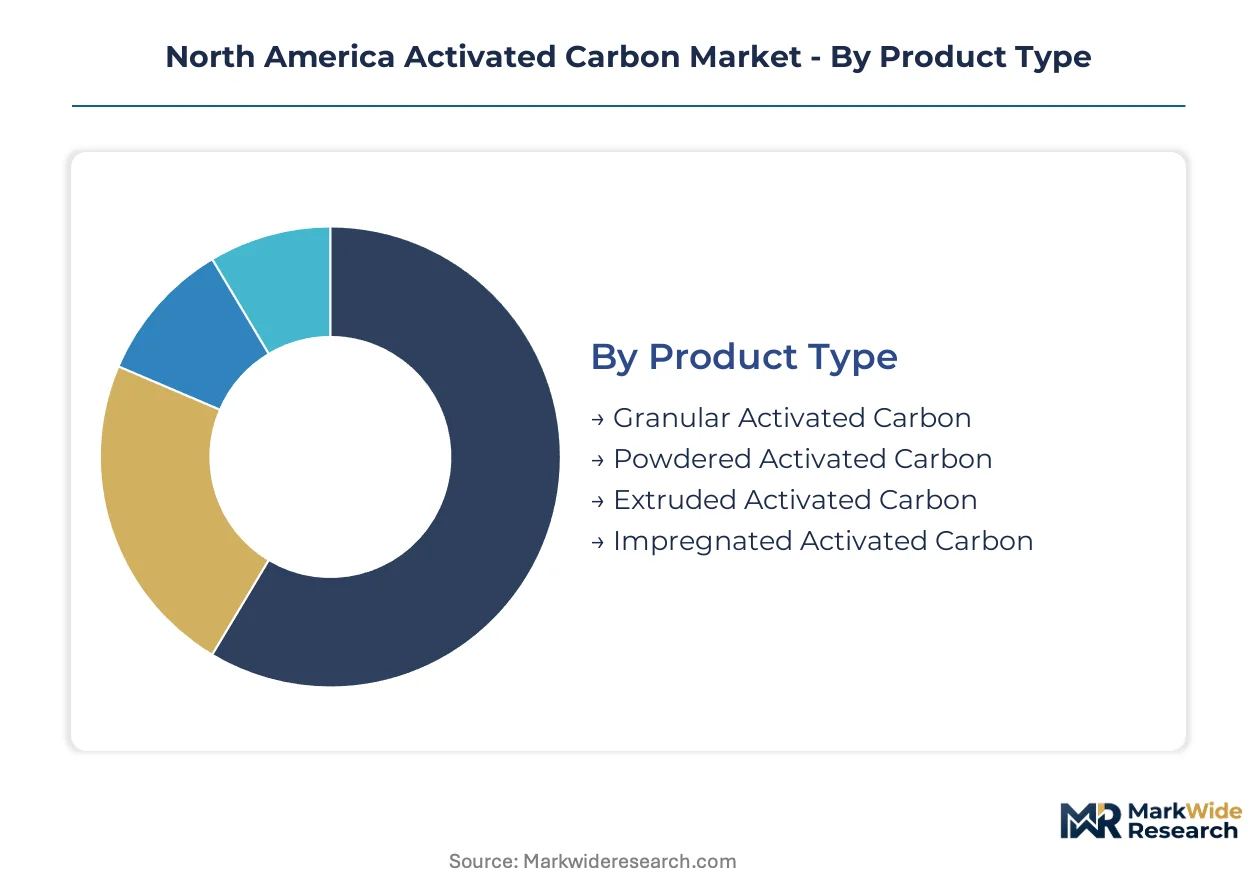
Activated carbon segmentation in North America reflects divergent technical specifications across municipal infrastructure, industrial process requirements, and regulatory compliance timelines. Product form factors, application environments, and procurement modalities each create distinct competitive arenas with specialized supply chain configurations.
Product Type:
Maturity spans from century-old granular formats to emerging impregnated variants engineered for targeted contaminant capture.
- Granular Activated Carbon:Particulate form with particle sizes ranging from 0.2 to 5 millimeters, optimized for fixed-bed adsorption systems with low pressure drop characteristics. Municipal water utilities across the US Great Lakes region specify high-iodine-number grades to meet EPA Stage 2 Disinfection Byproducts Rule mandates, driving replacement cycle compression.
- Powdered Activated Carbon:Finely ground material below 0.18 millimeters, injected directly into flue gas streams or rapid-mix water treatment basins. Coal-fired power plants in the Ohio River Valley and Appalachian basins deploy powdered carbon for Mercury and Air Toxics Standards compliance, with procurement concentrated among utilities facing accelerated MATS deadlines.
- Extruded Activated Carbon:Cylindrical pellets manufactured through binder-assisted extrusion, offering uniform particle size for controlled bed porosity. Specialized air purification installations in California semiconductor fabrication facilities favor this geometry to prevent channeling.
- Impregnated Activated Carbon:Base carbon infused with metallic salts or chemical modifiers to enhance selective adsorption of hydrogen sulfide, mercury vapor, or radioactive iodine. Emerging demand from nuclear power stations and odor control applications is expanding addressable applications beyond conventional adsorption limits.
Granular activated carbon handles the majority of throughput; powdered activated carbon is expanding most quickly on share.
Application:
Cost tier differentiation separates capital-intensive municipal installations from operational expenditure-driven industrial cycles.
- Water Treatment:Surface water and groundwater remediation through adsorption of organic micropollutants, chlorine compounds, and disinfection byproduct precursors. The US Gulf Coast petrochemical corridor and Great Lakes municipal systems anchor demand, with PFAS removal mandates in Michigan and New Jersey accelerating specialized carbon blend procurement.
- Air Treatment:Volatile organic compound capture, odor control, and hazardous air pollutant removal from industrial exhaust streams. Refinery sulfur recovery units and solvent degreasing operations in Texas and Louisiana drive continuous consumption with quarterly replacement schedules.
- Chemical Processing:Purification of process streams, catalyst support, and solvent recovery in pharmaceutical and specialty chemical manufacturing. New Jersey and Pennsylvania chemical corridors specify acid-washed grades for high-purity applications.
- Food & Beverage:Decolorization of sugar syrups, removal of off-flavors in alcoholic beverages, and purification of edible oils. California wine producers and Midwest corn processors favor steam-activated coconut shell grades for taste-neutral adsorption.
Water treatment commands the largest installed base; air treatment applications are climbing the fastest as MATS compliance deadlines concentrate.
End User:
Customer type fragmentation separates regulated public entities from private industrial operators with divergent procurement modalities.
- Utilities:Municipal drinking water and wastewater treatment authorities operating under EPA Safe Drinking Water Act compliance frameworks. Large-scale metropolitan systems in Chicago, Detroit, and Toronto specify granular carbon with reactivation service contracts to optimize lifecycle costs.
- Pharmaceutical:Active pharmaceutical ingredient manufacturers and formulation facilities requiring USP-grade activated carbon for impurity removal. New Jersey and Massachusetts clusters demand certified low-ash products with full supply chain documentation.
- Food Industry:Processors of sweeteners, beverages, and edible oils requiring food-contact compliant carbon with Kosher and Halal certifications. Midwest corn wet milling operations and Pacific Northwest beverage producers drive seasonal procurement patterns.
- Manufacturing:Diverse industrial operations including electronics, automotive, and metal finishing with process water and air treatment requirements. Automotive painting operations in Michigan and Ohio specify carbon for volatile organic compound capture from spray booth exhaust.
Utilities represent the highest volume consumption; pharmaceutical end users are gaining share fastest on specification premium capture.
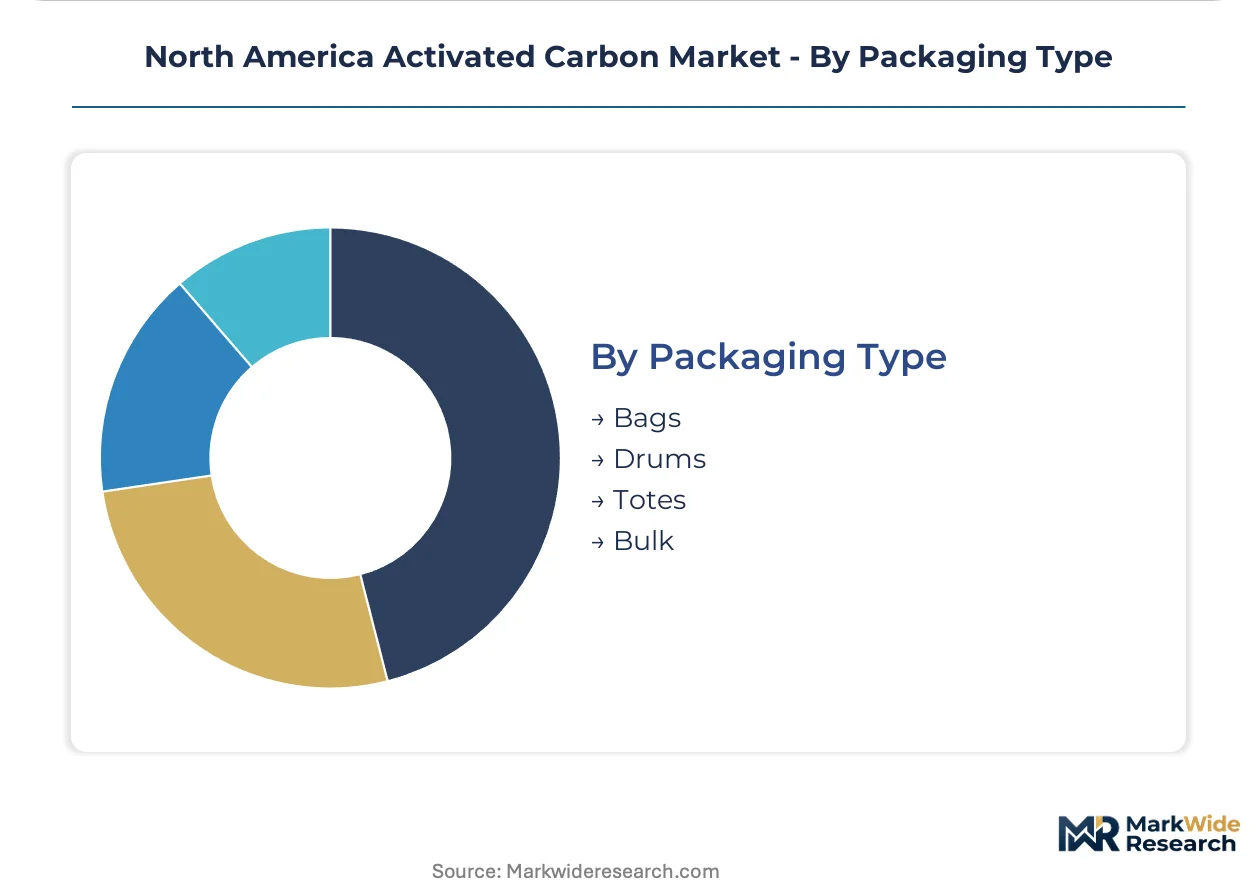
Packaging Type:
Supply concentration in bulk formats contrasts with service-oriented smaller packaging for distributed industrial users.
- Bags:25 to 50-pound multi-wall paper or polyethylene containers for laboratory, pilot-scale, and small industrial applications. Specialty chemical manufacturers and food processors in dispersed geographic locations favor bagged product for inventory flexibility.
- Drums:55-gallon fiber or steel containers for mid-volume industrial users with dedicated carbon handling equipment. Metal finishing operations and regional water treatment contractors standardize on drum quantities for predictable consumption rates.
- Totes:Intermediate bulk containers of 275 to 330 gallons for high-throughput industrial sites with carbon slurry handling systems. Petrochemical facilities along the Houston Ship Channel deploy totes for continuous solvent recovery unit feed.
- Bulk:Pneumatic truck or railcar delivery of unpackaged granular carbon directly into storage silos. Large municipal water treatment plants and major refinery operations specify bulk delivery to minimize handling labor and packaging waste.
Bulk packaging handles the majority of tonnage movement; tote formats are expanding most quickly among mid-size industrial operators seeking operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement departments and industrial water treatment contractors concentrate demand across three distinct national markets with divergent regulatory timelines and feedstock access profiles.
United States
EPA Stage 2 Disinfection Byproducts Rule mandates drive granular carbon replacement cycles across Great Lakes municipal systems. Mercury and Air Toxics Standards compliance forces coal-fired utilities in the Ohio River Valley and Appalachian basins to maintain permanent powdered activated carbon injection infrastructure. The Gulf Coast petrochemical corridor from Houston to Lake Charles anchors continuous virgin and reactivated carbon consumption for solvent recovery operations.
Canada
Health Canada guidelines for activated carbon in food contact and pharmaceutical applications create documentation requirements that favor suppliers with integrated certification capabilities. Ontario municipal utilities in Toronto and Ottawa specify high-iodine-number carbons for surface water treatment under tightening provincial quality standards. Alberta oil sands operators deploy specialized carbon blends for process water polishing in bitumen extraction facilities.
Mexico
CONAGUA water quality enforcement is expanding activated carbon adoption in Monterrey and Guadalajara municipal systems confronting industrial pollution loads. Pemex refinery operations in Tula and Salamanca drive demand for sulfur recovery and vapor emission control applications. Baja California beverage processors source steam-activated coconut shell grades for decolorization operations serving export markets.
North America Activated Carbon Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structured around reactivation service networks and virgin carbon supply security. The vendor base fragments between integrated multinational suppliers with captive raw material sourcing and regional reactivation specialists serving discrete geographic markets. Two strategic archetypes dominate: vertically integrated operators controlling supply chains from precursor sourcing through spent carbon regeneration, and technology-anchored providers bundling carbon supply with digital monitoring platforms. Capacity expansion in Southeast Asian coconut shell processing and North American reactivation furnace networks represent the primary competitive moves.
Within the integrated supply chain tier, Ingevity Corporation and Calgon Carbon Corporation exemplify operators with backward integration into raw material sourcing and forward integration into reactivation services. Evoqua Water Technologies LLC occupies a position combining carbon supply with digital performance monitoring capabilities. These three anchors illustrate divergent strategic postures: feedstock security versus service bundling versus technology convergence.
| Leading Market Players |
|---|
| Jacobi Carbons AB |
| Haycarb PLC |
| Cabot Corporation |
| Ingevity Corporation |
| Carbon Activated Corporation |
| Calgon Carbon Corporation |
| Donau Carbon GmbH |
| Evoqua Water Technologies LLC |
| Kuraray Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Southeast Asian coconut shell processing clusters in Sri Lanka and Indonesia anchor global feedstock availability, and their capacity utilization swings transmit directly into iodine-number premium spreads for North American municipal buyers. The Gulf Coast petrochemical corridor absorbs these volatility shocks through multi-year reactivation service contracts that buffer spot market exposure.
Pricing Analysis
Cost-plus contracts indexed to coconut shell commodity benchmarks dominate municipal procurement, with price differentiation separating pharmaceutical-grade acid-washed carbons from standard water treatment grades. Price erosion runs through the low-iodine coal-based segment as biochar alternatives achieve cost parity. Industrial end users in the Texas refining cluster exhibit lowest price sensitivity due to continuous replacement schedules, while mid-size food processors negotiate aggressively on bagged product volumes.
Supply Chain Analysis
Tariff exposure between Southeast Asian sourcing regions and US Gulf Coast receiving ports dominates supply chain risk planning for high-iodine granular products. Virgin carbon production draws from coconut shell plantations in Sri Lanka, Indonesia, and the Philippines, with reactivation furnace networks concentrated in Texas, Louisiana, and Ontario. Single-source vulnerability in typhoon-prone sourcing regions drives procurement diversification mandates. Distribution runs through bulk pneumatic delivery to municipal silos and tote-based industrial replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as EPA PFAS mandates splinter demand into specialized carbon blend specifications that incumbent broad-line suppliers cannot address from standardized inventories.
For Market Incumbents: Insulate margin stability through captive reactivation furnace capacity additions in the Ohio River Valley, where coal ash landfill closures are concentrating spent carbon logistics. Zeolite substitution threats in natural gas processing demand accelerated R&D into impregnated carbon variants for selective contaminant capture. Certification investment for Health Canada pharmaceutical-grade documentation preserves cross-border pricing premiums. For New Entrants and Emerging Players: Build out mobile filtration leasing operations targeting seasonal industrial turnaround schedules in the Houston Ship Channel corridor, where asset-light procurement preferences are displacing capital purchases. PFAS remediation mandates in Michigan and New Jersey municipal systems represent the most penetrable demand segment for specialized blend suppliers. Partner with digital monitoring platform providers to bundle predictive replacement scheduling with carbon supply contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized activated carbon divisions lacking reactivation service integration. Long-term viability hinges on positioning for regulatory compliance permanence rather than cyclical environmental spending. Watch for EPA coal combustion residual classification finalization as the inflection signal for powdered carbon injection system demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Reactivation Capacity Expansion | Captive furnace networks in the Ohio River Valley reduce customer logistics costs and lock in replacement cycles. |
| PFAS-Specialized Blend Development | State-level drinking water mandates in Michigan and New Jersey require customized iodine-number specifications beyond standard inventories. |
| Digital Monitoring Platform Integration | IoT sensor convergence with carbon bed performance tracking enables predictive maintenance contracts with municipal utilities. |
| Mobile Filtration Leasing Model | Equipment-as-a-service bundling addresses seasonal petrochemical turnaround demand without capital expenditure approval cycles. |
| Southeast Asian Feedstock Diversification | Multi-origin coconut shell sourcing mitigates typhoon disruption risk for high-iodine granular supply security. |
Research Approach
A spread of perspectives from municipal water utility procurement directors, petrochemical plant engineers, reactivation facility operators, and activated carbon distribution channel managers converged on the working assumptions. Primary fieldwork combined with secondary validation from EPA enforcement databases, FERC utility procurement filings, and American Water Works Association technical standards. Customs trade data on coconut shell carbon imports and SEC 10-K disclosures from integrated suppliers provided volume triangulation. Bottom-up facility capacity estimates and top-down end-use consumption models were cross-referenced for convergence.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across product form factor, application environment, end-user procurement modality, and regional regulatory cluster. CAGRs were derived from replacement cycle compression rates under EPA Stage 2 mandates and MATS compliance permanence assumptions. Forecast inputs incorporated reactivation capacity utilization rates and virgin carbon price spread elasticity for procurement optimization behavior.
Stress conditions across coconut shell feedstock availability, reactivation furnace operating rates, and municipal capital expenditure approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement permanence and substitution technology penetration limits. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Industrial Mixers Market
Industrial Materials
Precipitated Silica Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Static Mixer Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market