
 Global Sulfone Polymers Market | 2026-2036
Global Sulfone Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sulfone Polymers Market Foresight
The EU Green Deal is pivoting European buyers toward sulfone polymers with lower lifecycle carbon footprints. Syensqo leverages its integrated PES and PPSU production to sustain supply security for medical and membrane customers. BASF SE anchors its position through backward integration into monomer production, while Sumitomo Chemical differentiates via specialty grades for semiconductor fabrication equipment.
Sulfone polymers are high-performance amorphous thermoplastics containing aryl-SO2-aryl linkages, with glass transition temperatures ranging from 185°C to 220°C and inherent flame resistance without halogenated additives. These properties suit applications requiring steam sterilization durability, dielectric stability, and hydrolytic resistance across aggressive chemical environments. Polyphenylsulfone leads the product type landscape due to its superior impact strength and hot-water performance, while membrane applications represent the fastest-expanding demand pool as municipal and industrial water treatment upgrades accelerate. Polysulfone maintains mature volume dominance in electrical components and consumer goods where cost-performance balance matters most.
REACH registration requirements and RoHS substance restrictions shape material qualification timelines across European electronics and automotive supply chains. The EPA maintains emission standards that influence U.S. manufacturing process compliance for sulfone polymer resin plants. China's GB standards and MIIT industrial guidelines govern local production certification for imported engineering thermoplastics. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations, as sulfone polymers face competitive positioning shifts should fluoropolymer restrictions expand into medical and membrane end uses.
Market Dynamics
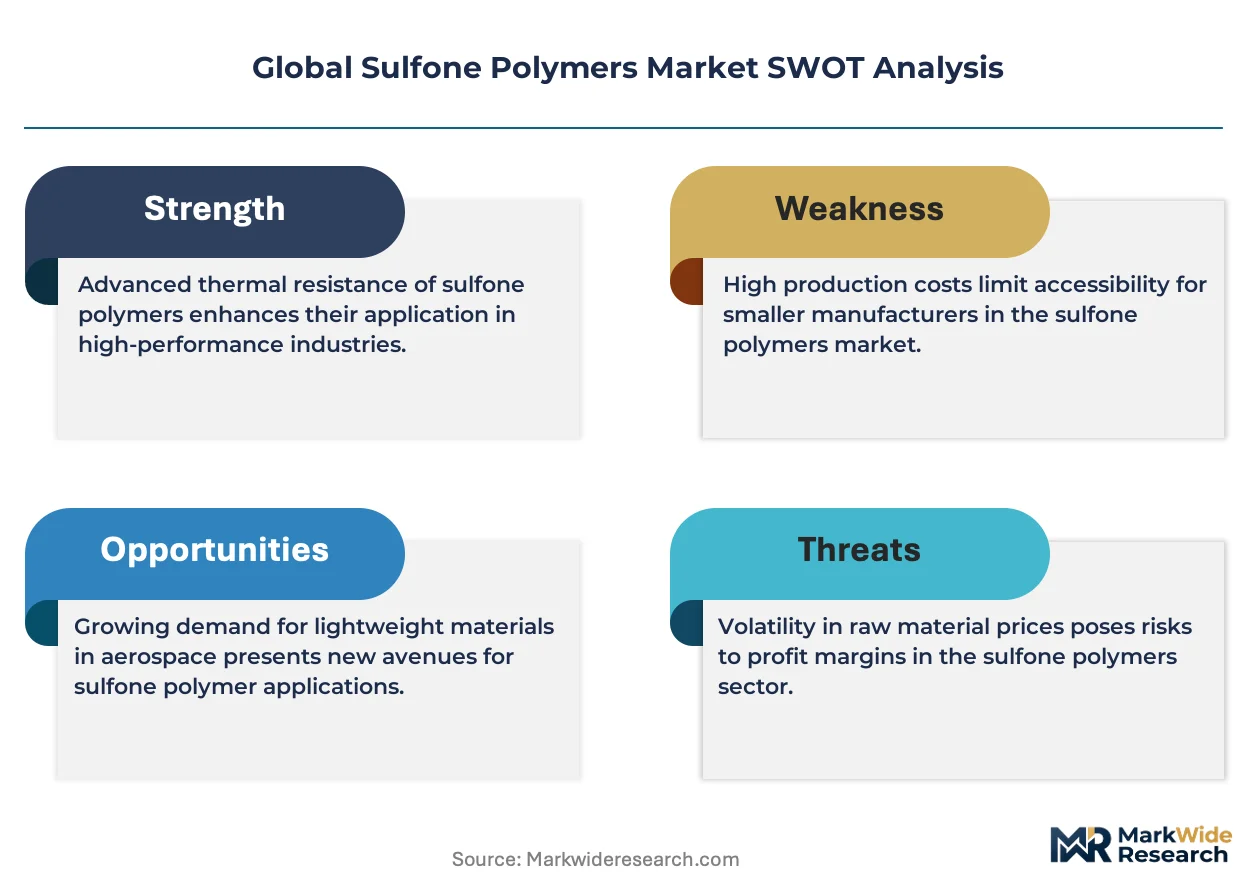
REACH registration timelines and EU Green Deal carbon accounting requirements are compressing supplier qualification windows while simultaneously elevating lifecycle transparency as a procurement criterion across European water treatment and medical device supply chains.
Growth Catalysts
- Membrane application expansion:Municipal water treatment infrastructure upgrades across Germany and China are accelerating procurement of polyphenylsulfone grades for ultrafiltration and reverse osmosis systems.
- Medical sterilization durability requirements:Steam autoclave compatibility without hydrolytic degradation positions sulfone polymers as the material of choice for reusable surgical instrument housings and dental equipment.
- REACH compliance-driven substitution:RoHS substance restrictions on halogenated flame retardants in electronics are redirecting material selection toward inherently fire-resistant sulfone polymer alternatives.
Market Restraints
- Monomer supply concentration:Bisphenol S and 4,4'-dichlorodiphenyl sulfone production remains concentrated among Asian specialty chemical manufacturers, creating input cost volatility exposure.
- High processing temperatures:Melt temperatures exceeding 350°C require specialized extrusion and injection molding equipment, limiting converter base expansion.
- Competitive fluoropolymer positioning:Perfluoroalkoxy alkane materials retain dielectric performance advantages in semiconductor fabrication equipment despite environmental scrutiny.
Strategic Opportunities
- Indian industrial water treatment:Central Pollution Control Board mandates for zero liquid discharge in textile and pharmaceutical clusters are creating membrane system demand in Gujarat and Tamil Nadu.
- EU Green Deal carbon footprint differentiation:Suppliers with verified lifecycle assessments can capture premium positioning as Scope 3 disclosure requirements tighten across automotive and electronics value chains.
- 3D printing filament development:Fused deposition modeling of sulfone polymers is enabling patient-specific medical device geometries and low-volume aerospace bracket production.
Industry Challenges
- Specialized polymer processing expertise scarcity:Drying protocols, mold temperature control, and annealing requirements demand experienced technicians that converter networks struggle to recruit.
- Extended medical device certification timelines:FDA 510(k) and EU MDR biocompatibility documentation for new sulfone polymer grades can exceed 18 months, compressing product launch windows.
- Legacy equipment incompatibility:Existing polycarbonate and polypropylene molding infrastructure requires substantial retrofit investment to handle sulfone polymer thermal profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sulfone Polymers Market |
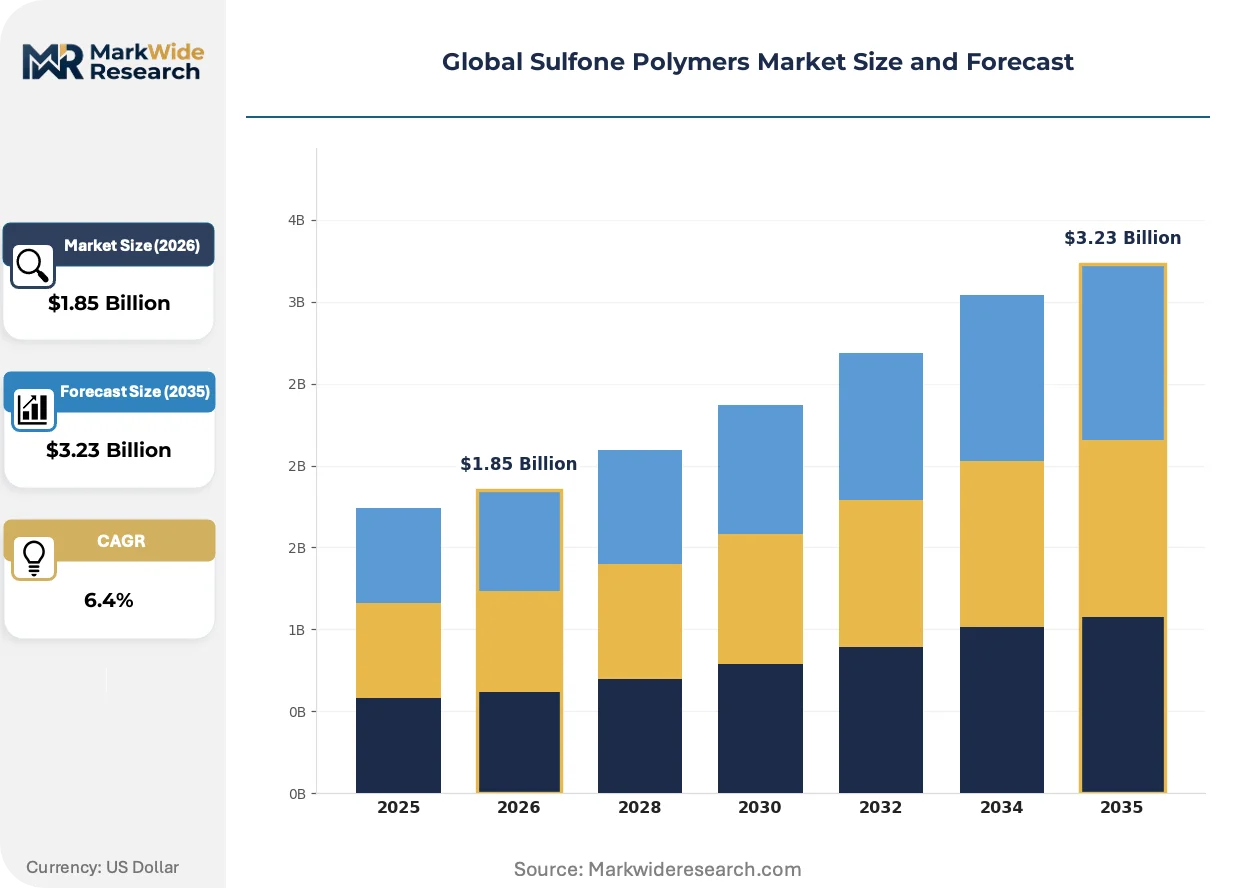
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethersulfone, Polysulfone, Polyphenylsulfone, Others Application: Membranes, Electrical Components, Automotive Components, Consumer Goods, Aerospace End Use Industry: Electronics Manufacturing, Vehicle Assembly, Aircraft Production, Household Appliances Form: Powder, Pellet, Film, Sheet |
| Companies Covered | Syensqo, BASF SE, Sumitomo Chemical, Solvay, SABIC, RTP Company, Mitsubishi Chemical Advanced Materials, Evonik Industries AG, Quadrant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sulfone Polymers Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are converging to reshape competitive positioning across high-performance thermoplastic supply chains, with sustainability verification emerging as a distinct order-qualifying capability.
Polyphenylsulfone resin formulations with enhanced hydrolytic stability are consolidating technical specification dominance in hot-water contact applications. Water treatment membrane manufacturers in Germany and China are standardizing on these grades for municipal ultrafiltration systems. This consolidation is compressing polysulfone market share in premium membrane segments where service life predictions now govern procurement decisions.
EU Green Deal carbon border adjustment mechanisms and CSRD sustainability reporting requirements are tightening material traceability expectations across European electronics and automotive supply chains. Suppliers must now document Scope 1-3 emissions for sulfone polymer grades to maintain qualified vendor status. Medical device manufacturers in Germany face the most acute compliance pressure as MDR technical documentation expands to include lifecycle environmental impact.
Certificate-of-analysis-driven procurement is displacing traditional spot-market purchasing for sulfone polymer resins. Membrane system OEMs are consolidating supplier bases to capture batch consistency guarantees and regulatory documentation packages. This behavioral shift is most visible in China's Yangtze River Delta manufacturing cluster, where municipal water treatment project tenders now specify resin grade certification from named approved suppliers.
Global Sulfone Polymers Market Segmentation
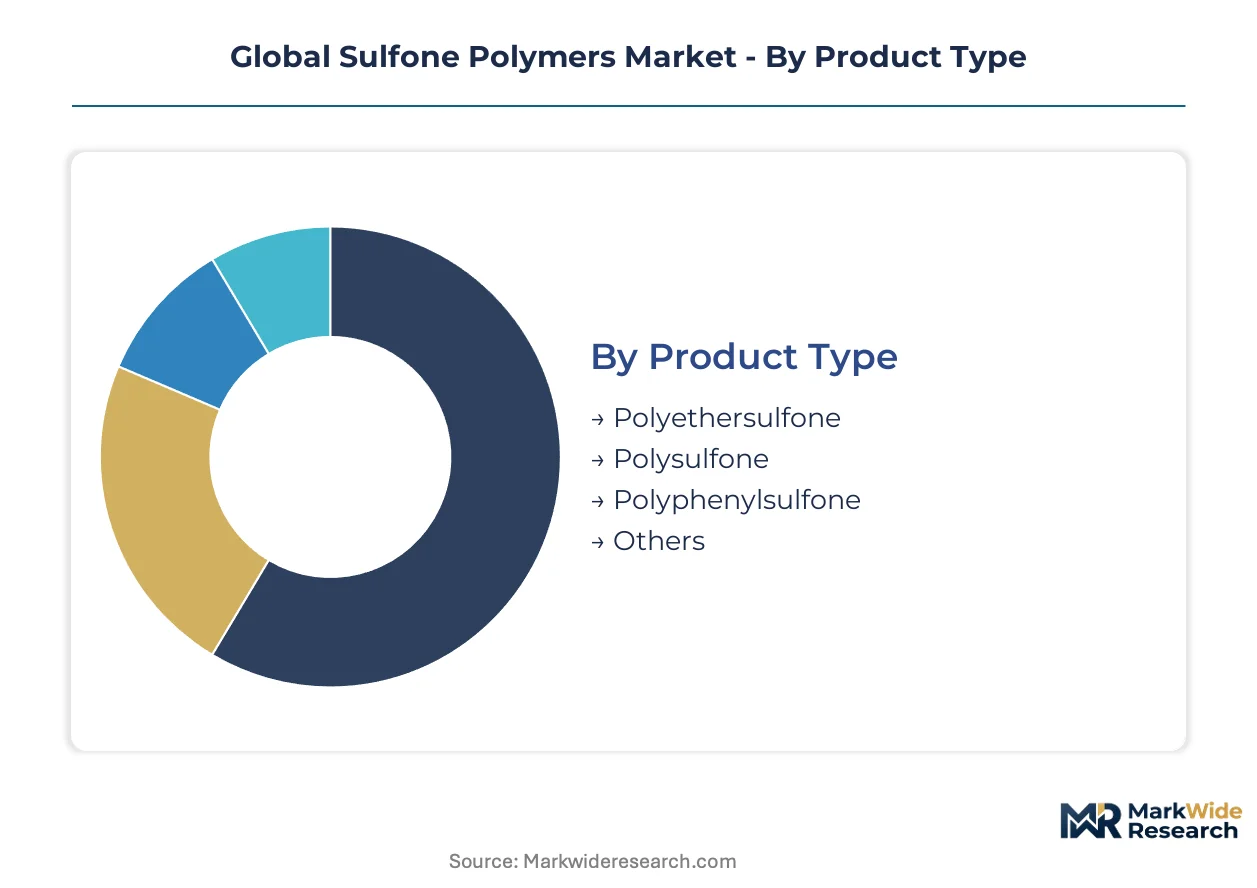
Sulfone polymer procurement decisions hinge on thermal performance thresholds and regulatory compliance requirements. Specification mismatches between product grades and end-use thermal profiles drive material qualification failures. Understanding segment boundaries prevents costly formulation errors across membrane, medical, and electronics supply chains.
Product Type:
Glass transition temperature and hydrolytic stability specifications differentiate material selection across sterilization and hot-water applications.
- Polyphenylsulfone:Aryl-SO2-aryl backbone delivers superior impact strength and steam sterilization durability. Water treatment membrane manufacturers in Germany and China specify this grade for ultrafiltration systems requiring 10+ year service life predictions. Municipal infrastructure upgrades accelerate procurement volumes.
- Polysulfone:Amorphous thermoplastic with 185°C glass transition temperature balances cost-performance for electrical housings and consumer goods. Cost-conscious electronics assemblers in China's Yangtze River Delta favor this grade for RoHS-compliant flame-resistant components.
- Polyethersulfone:Transparent variant with dielectric stability suits medical device housings requiring visual inspection capability.
- Others:Blended and modified grades address niche semiconductor fabrication equipment specifications.
Polysulfone leads on scale; polyphenylsulfone leads on momentum.
Application:
End-use thermal and chemical exposure profiles determine grade selection more than unit economics.
- Membranes:Ultrafiltration and reverse osmosis systems demand hydrolytic stability across pH extremes and chlorine exposure. Germany's municipal water treatment tenders now specify polyphenylsulfone grades with certified batch consistency for 20-year infrastructure assets.
- Electrical Components:Inherent flame resistance without halogenated additives satisfies REACH and RoHS restrictions. Connector housings and circuit breaker components in automotive electronics represent mature volume demand.
- Automotive Components:Under-hood applications requiring 150°C continuous service temperature specify sulfone polymers for charge air cooler tanks.
- Consumer Goods:Food contact applications leverage FDA-compliant grades for coffee machine and water filtration components.
- Aerospace:Interior panel and ducting applications prioritize low smoke toxicity and flame resistance per FAA regulations.
Electrical components anchor volume; membranes expand most quickly.
End Use Industry:
Regulatory certification timelines and supply chain qualification intensity vary sharply across manufacturing sectors.
- Electronics Manufacturing:RoHS substance restrictions and REACH registration requirements compress material qualification windows. German automotive electronics suppliers demand Scope 3 carbon documentation under EU Green Deal mandates.
- Vehicle Assembly:Under-hood thermal management components require 180°C continuous service capability. China's MIIT industrial guidelines govern local production certification for engineering thermoplastics in electric vehicle battery housings.
- Aircraft Production:FAA and EASA flame-smoke-toxicity certifications extend material approval timelines beyond 24 months.
- Household Appliances:Cost-driven procurement favors polysulfone grades for coffee systems and water filtration devices.
Electronics manufacturing dominates procurement value; vehicle assembly climbs fastest on electrification thermal management demand.
Form:
Processing method and part geometry requirements dictate form factor selection across converter networks.
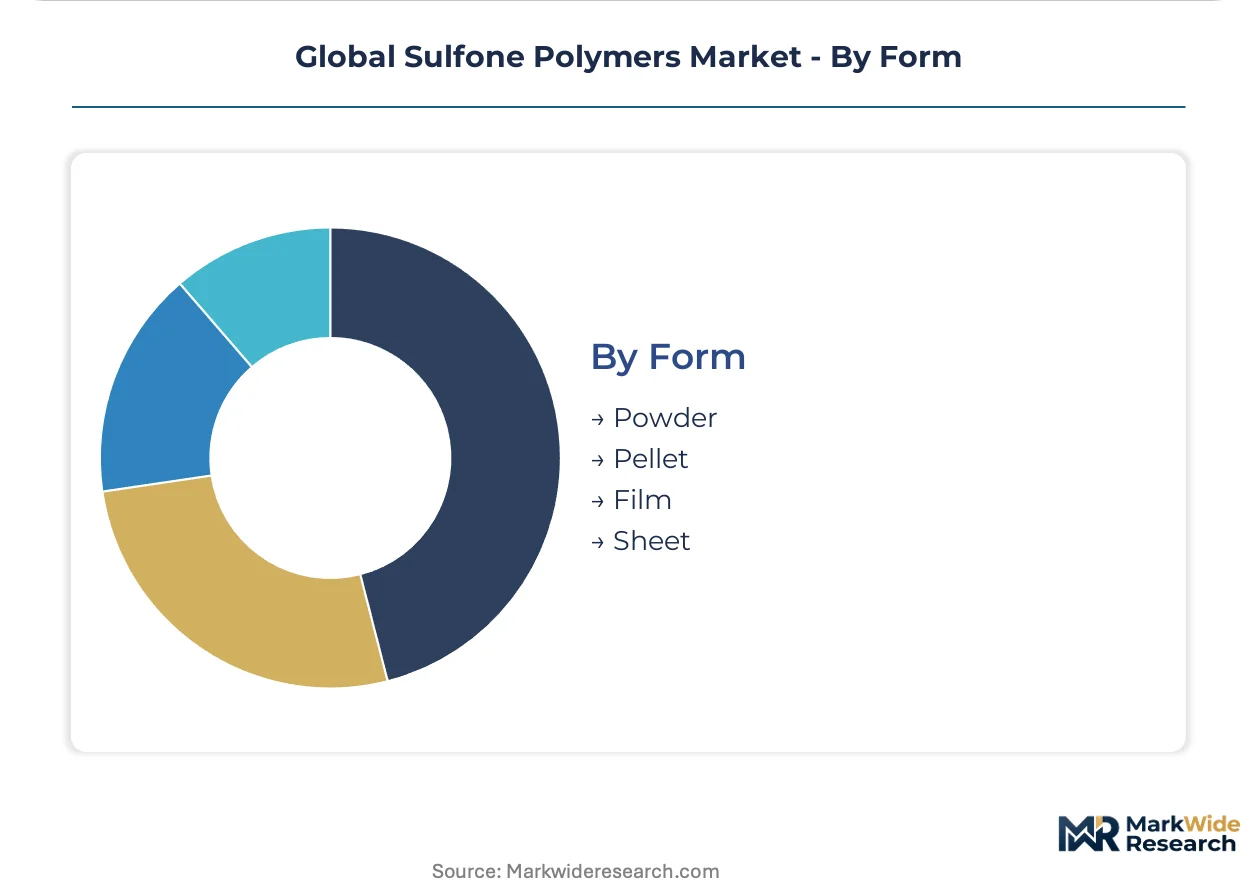
- Pellet:Standard injection molding feedstock for high-volume electrical and consumer goods production. German compounders maintain largest pellet specification libraries.
- Powder:Compression molding and solvent casting applications for membrane substrate production. China's membrane OEMs concentrate powder procurement for ultrafiltration sheet manufacturing.
- Film:Thin-gauge electrical insulation and medical packaging applications.
- Sheet:Thermoformed aircraft interior components and chemical processing equipment.
Pellet commands volume leadership; powder gains share fastest on membrane substrate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sulfone polymer commercialization traces its industrial roots to 1960s United States and Germany, where specialty chemical manufacturers first scaled aryl-sulfone backbone production for aerospace and electrical applications. This dual-origin lineage established transatlantic technical standards that persist in current certification frameworks.
United States
FDA biocompatibility documentation for medical device grades and EPA emission standards for resin manufacturing plants shape procurement compliance costs. The Inflation Reduction Act's domestic content provisions for clean water infrastructure are accelerating municipal membrane system deployments. Texas and Louisiana host the largest concentration of specialty chemical production assets serving Gulf Coast water treatment and energy sector demand.
Germany
EU Green Deal carbon border adjustments and CSRD Scope 3 disclosure mandates are compressing supplier qualification windows for automotive electronics and medical device manufacturers. REACH registration requirements for new sulfone polymer grades extend material approval timelines beyond 18 months. The Rhine-Ruhr industrial corridor concentrates compounding operations serving membrane OEMs across Benelux and Northern France.
China
MIIT industrial guidelines for engineering thermoplastics and GB standards for water treatment membrane certification govern local production and import substitution programs. Dual carbon goals are tightening energy intensity requirements for Bisphenol S monomer production. The Yangtze River Delta manufacturing cluster—spanning Shanghai, Jiangsu, and Zhejiang—hosts the fastest-expanding membrane substrate fabrication capacity for municipal ultrafiltration tenders.
Japan
METI strategic material security initiatives and JIS standards for high-performance thermoplastics are reinforcing domestic supply chain resilience for semiconductor fabrication equipment. PMDA medical device regulations extend sulfone polymer grade certification timelines for reusable surgical instruments. The Chubu region around Nagoya anchors precision molding operations serving automotive thermal management component demand.
India
Central Pollution Control Board zero liquid discharge mandates for textile and pharmaceutical clusters are creating membrane system procurement pull in Gujarat and Tamil Nadu. BIS certification requirements for imported engineering thermoplastics add compliance layers for European and East Asian resin suppliers. The Delhi-Mumbai Industrial Corridor is emerging as a concentration zone for water treatment system integrators specifying polyphenylsulfone grades.
Global Sulfone Polymers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and application specialization vectors. The vendor base stratifies into three tiers: integrated monomer-to-resin manufacturers capturing backward integration economics; compounders with medical and membrane grade certification libraries; and regional distributors serving spot-market procurement for electrical and consumer goods applications. Dominant competitive moves include captive supply security investments and lifecycle assessment documentation capabilities for EU Green Deal compliance.
Among integrated chemical conglomerates, Syensqo and BASF SE exemplify archetypes with monomer production control and medical-grade certification depth. Sumitomo Chemical occupies a specialist position serving semiconductor fabrication equipment demand. These three anchors represent the competitive spectrum from broad portfolio coverage to targeted application dominance.
| Leading Market Players |
|---|
| Syensqo |
| BASF SE |
| Sumitomo Chemical |
| Solvay |
| SABIC |
| RTP Company |
| Mitsubishi Chemical Advanced Materials |
| Evonik Industries AG |
| Quadrant AG |
| Others |
Supply & Pricing Matrix
Integrated chemical conglomerates with captive monomer production anchor pricing discipline through backward integration economics, while independent compounders face margin compression from concentrated Bisphenol S feedstock markets. This ownership structure concentrates pricing power among resin manufacturers with upstream control, forcing spot-market buyers into certificate-of-analysis contracts that bundle regulatory documentation with volume commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade certified polyphenylsulfone from industrial membrane grades and commodity polysulfone for electrical housings. Price differentiation hinges on REACH registration depth and FDA biocompatibility tier, with German automotive electronics suppliers paying Scope 3 carbon documentation premiums. Cost compression in standard-grade polysulfone is intensifying because Chinese Yangtze River Delta converters are consolidating procurement volumes. Electrical component assemblers exhibit highest price sensitivity, while membrane OEMs prioritize batch consistency over unit economics.
Supply Chain Analysis
Reverse logistics flows for sulfone polymer scrap remain underdeveloped, with limited mechanical recycling infrastructure for high-temperature thermoplastics creating disposal cost burdens for converters. Geographic supply concentration centers on Germany, China, and the United States, where integrated producers control Bisphenol S and 4,4'-dichlorodiphenyl sulfone monomer supply. Raw material dependencies rest on Asian specialty chemical manufacturers for sulfone monomers, European compounders for medical-grade certification, and Chinese membrane substrate fabricators for powder-form resin. Single-source vulnerability in Bisphenol S production creates input cost volatility exposure. Distribution runs through qualified supplier programs with batch traceability documentation rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sulfone Polymers Market functions as a stable compounder, with municipal water treatment infrastructure cycles and medical device sterilization durability requirements generating predictable replacement demand. Regulatory compliance timelines extend customer lock-in, reducing churn risk for qualified suppliers.
For Market Incumbents: Lock in membrane OEM relationships through long-term offtake agreements that bundle polyphenylsulfone supply with 20-year service life documentation packages. Defend against fluoropolymer substitution threats in semiconductor fabrication equipment by accelerating lifecycle carbon footprint verification under EU Green Deal mandates. Prioritize captive supply security investments in Bisphenol S monomer production to insulate margin structures from Asian feedstock volatility.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian membrane markets offers white-space entry potential, as Central Pollution Control Board zero liquid discharge mandates outpace established supplier certification capacity. Target Gujarat and Tamil Nadu textile clusters with polyphenylsulfone grades pre-certified for BIS import requirements. Pursue joint development agreements with water treatment system integrators rather than direct resin sales to bypass incumbent converter networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders lacking medical-grade certification libraries but possessing powder-form processing capabilities for membrane substrates. Long-term viability framing favors targets with demonstrated EU REACH registration expertise, as Scope 3 disclosure requirements tighten across automotive and electronics value chains. Monitor EPA emission standard enforcement intensity for U.S. resin manufacturing plants as an inflection indicator for domestic production cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive Bisphenol S supply insulates BASF SE and Syensqo from Asian feedstock price volatility. |
| Medical-Grade Certification Investment | FDA 510(k) and EU MDR documentation packages extend customer switching costs beyond 18 months. |
| Long-Term Supply Agreement with Membrane OEMs | Certificate-of-analysis contracts with German ultrafiltration system builders secure volume visibility. |
| Green Manufacturing Transition | Lifecycle carbon footprint verification captures premium positioning under EU Green Deal procurement criteria. |
| Joint Venture for Regional Compounding | Localized production in China's Yangtze River Delta reduces logistics costs for municipal water treatment tenders. |
Research Methodology
Bottom-up membrane application modeling reconciled against top-down monomer production tracking forms the analytical core of this study. Primary interviews with plant managers at sulfone polymer resin facilities, procurement leads at water treatment membrane OEMs, distribution channel partners serving electrical component assemblers, and technical R&D directors at medical device compounders informed demand segmentation. Secondary validation drew from ECHA REACH registration databases, U.S. EPA emission compliance filings, Chinese MIIT industrial guideline publications, and customs trade data for Bisphenol S and 4,4'-dichlorodiphenyl sulfone flows. Triangulation across these sources reconciled volume estimates with supply-side capacity assessments.
Input-output matrices mapped grade-tier demand across polyphenylsulfone, polysulfone, and polyethersulfone variants against end-use industry consumption patterns and regional production hub output across the analysis window. Segmentation dimensions included product type thermal performance tier, application exposure severity, end-use industry regulatory intensity, and form factor processing requirements. CAGRs were derived from infrastructure investment cycle timing and medical device replacement rate assumptions. Forecast inputs incorporated municipal water treatment tender pipelines, electric vehicle thermal management content per vehicle trajectories, and semiconductor fabrication equipment capital expenditure plans.
Caveats apply where REACH registration timeline delays, EPA emission standard enforcement shifts, or Chinese dual carbon goal acceleration could materially shift the outlook. Forecasts reflect assumptions regarding membrane OEM supplier consolidation behavior and medical device sterilization protocol durability requirements. Practitioners should monitor Bisphenol S production capacity announcements in China and EU Green Deal carbon border adjustment implementation schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Thermosetting Polymer Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market