
 US Potassium Methylate Market | 2026-2036
US Potassium Methylate Market Size, Share, and Industry Trends Forecast 2026-2036
US Potassium Methylate Market Insights
Drum-to-tote packaging consolidation is consolidating buyer choice across the US Potassium Methylate Market as large-volume biodiesel and chemical synthesis customers seek freight efficiencies. BASF SE leverages its integrated methanol-to-methoxide infrastructure to sustain cost-advantaged supply to Midwest refiners. Evonik anchors its position through specialty-grade production tailored to pharmaceutical manufacturing protocols. American Elements competes on high-purity powder specifications for life sciences applications.
Potassium methylate is an alkoxide salt with the formula CH3OK, typically manufactured via the reaction of potassium metal or potassium hydroxide with methanol under anhydrous conditions; it functions primarily as a strong base and transesterification catalyst in industrial processes. The solution form dominates volume flows to biodiesel production facilities, while powder and pellet grades command premium positioning in pharmaceutical manufacturing where moisture sensitivity dictates packaging and handling protocols. Energy producers represent the deepest demand pool, though specialty chemicals companies are expanding share as fine chemical synthesis requirements intensify.
EPA renewable fuel standard obligations and OSHA process safety management requirements shape product specifications, handling protocols, and market access for potassium methylate suppliers operating in the United States. FDA current good manufacturing practice standards further constrain material qualification pathways for pharmaceutical-grade grades. Stakeholders must monitor evolving state-level low-carbon fuel programs and their cascading effects on catalyst procurement volumes and purity thresholds.
Market Dynamics
Drum-to-tote packaging consolidation is compressing supplier margins while concentrating purchasing power among large Midwest biodiesel refiners seeking freight efficiencies.
Growth Catalysts
- EPA Renewable Volume Obligations:Federal mandates for renewable fuel blending are forcing refiners to secure transesterification catalysts at scale, pulling potassium methylate volumes upward.
- State Low-Carbon Fuel Standards:California's LCFS and Oregon's Clean Fuels Program are cascading procurement pressure into Iowa, Illinois, and Minnesota production facilities.
- Anhydrous Solution Dominance:Liquid-grade potassium methylate is capturing share from solid alkoxides in continuous-flow biodiesel reactors due to handling efficiency.
Market Restraints
- Methanol Feedstock Volatility:Natural gas price swings transmit directly to methanol costs, squeezing catalyst producer margins without immediate pass-through mechanisms.
- Midwest Supply Concentration:Production assets cluster along Gulf Coast methanol corridors, exposing buyers to hurricane-disruption risk and limited geographic diversification.
- Sodium Methoxide Substitution:Lower-cost sodium analogs are displacing potassium methylate in non-food-grade biodiesel applications where catalyst recovery economics favor cheaper bases.
Strategic Opportunities
- Pharmaceutical-Grade Certification:FDA current good manufacturing practice qualification for powder and pellet grades opens premium positioning in active pharmaceutical ingredient synthesis.
- Great Plains Distribution Hubs:Underdeveloped logistics infrastructure in Nebraska and Kansas creates first-mover advantage for regional blending and storage facilities.
- OSHA Process Safety Management Alignment:Suppliers investing in pyrophoric handling protocols and automated dosing systems can capture contracts from safety-conscious chemical synthesis buyers.
Industry Challenges
- Anhydrous Handling Expertise Gap:Qualified technicians for moisture-sensitive alkoxide transfer and storage are scarce in secondary biodiesel markets, constraining facility expansion timelines.
- Multi-Jurisdictional Compliance Burden:Suppliers must simultaneously satisfy EPA renewable fuel documentation, DOT hazardous materials shipping rules, and state-level environmental permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Potassium Methylate Market |
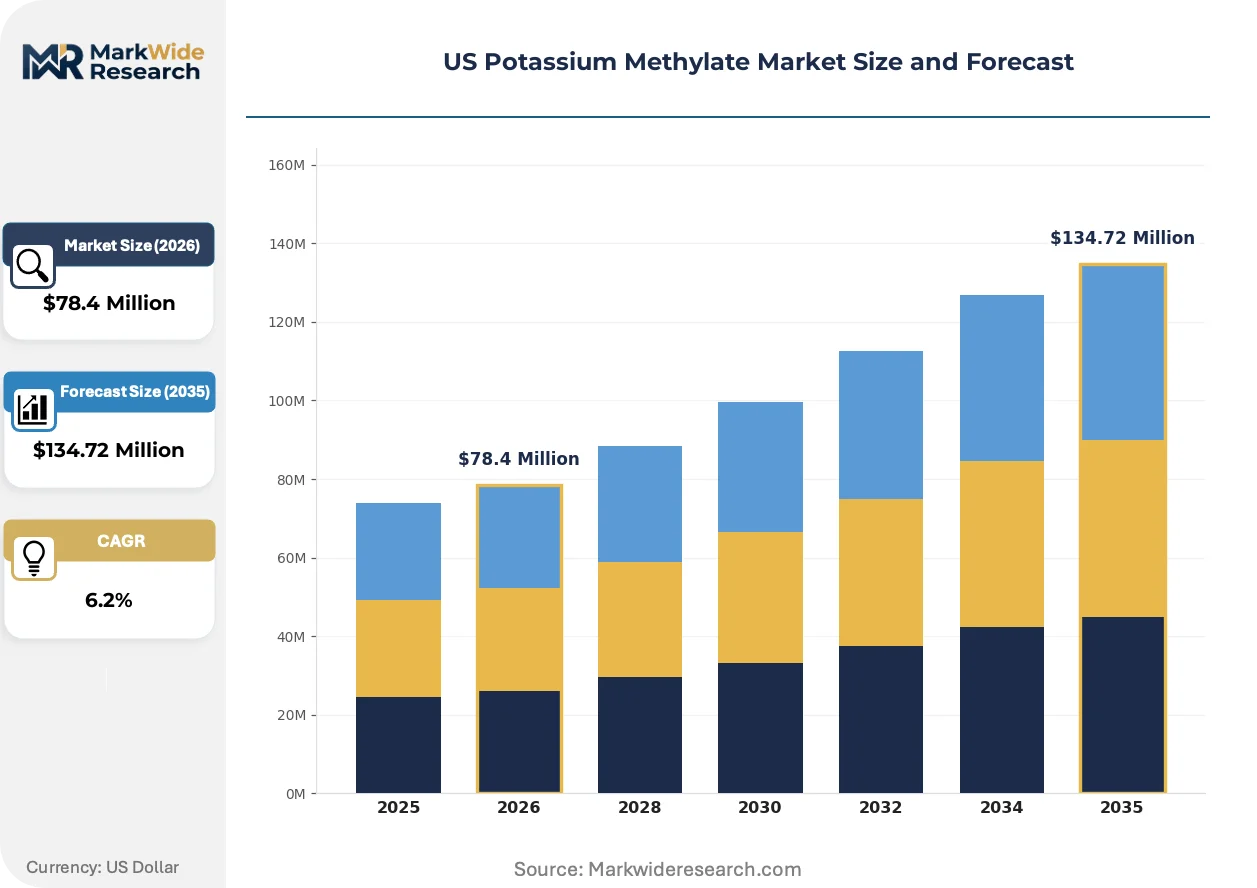
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Solution, Pellet, Granules Application: Biodiesel Production, Chemical Synthesis, Pharmaceutical Manufacturing, Agriculture Chemicals End User Industry: Energy Producers, Specialty Chemicals Companies, Crop Protection Firms, Life Sciences Organizations Packaging Type: Drums, Bulk Bags, Bottles, Totes |
| Companies Covered | GELEST, Inc., Thermo Fisher Scientific, Inc., Sigma-Aldrich Corporation, American Elements, BASF SE, Evonik, Brenntag NV, SRS International, Eastman Chemical Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Potassium Methylate Market Trends and Innovations
Automation of catalyst dosing and moisture control is compressing operational variance while regulatory pressure on carbon intensity is reshaping purity specifications across the value chain.
Closed-loop methanol recovery systems are automating solvent reclamation in continuous biodiesel production. Large refiners in Iowa and Minnesota are retrofitting reactors with automated alkoxide injection skids that eliminate manual handling exposure. This technology is automating the final link in catalyst-to-reactor logistics that previously required operator intervention.
EPA's evolving renewable fuel standard enforcement mechanisms are tightening mass-balance documentation requirements for catalyst origin and methanol source. Refiners must now trace potassium methylate back to specific methanol production facilities to qualify for renewable identification numbers. Biodiesel producers in Illinois are responding by demanding supplier-certified chain-of-custody documentation that was previously optional.
Long-term offtake agreements are displacing spot-market purchasing among integrated energy companies seeking supply security. Chemical distributors serving the Great Plains are losing share to direct supplier relationships as buyers consolidate vendor bases. This pattern is most visible among Minnesota cooperatives that have shifted from multi-supplier rotation to single-source contracts with penalty clauses for delivery failure.
US Potassium Methylate Market Segmentation
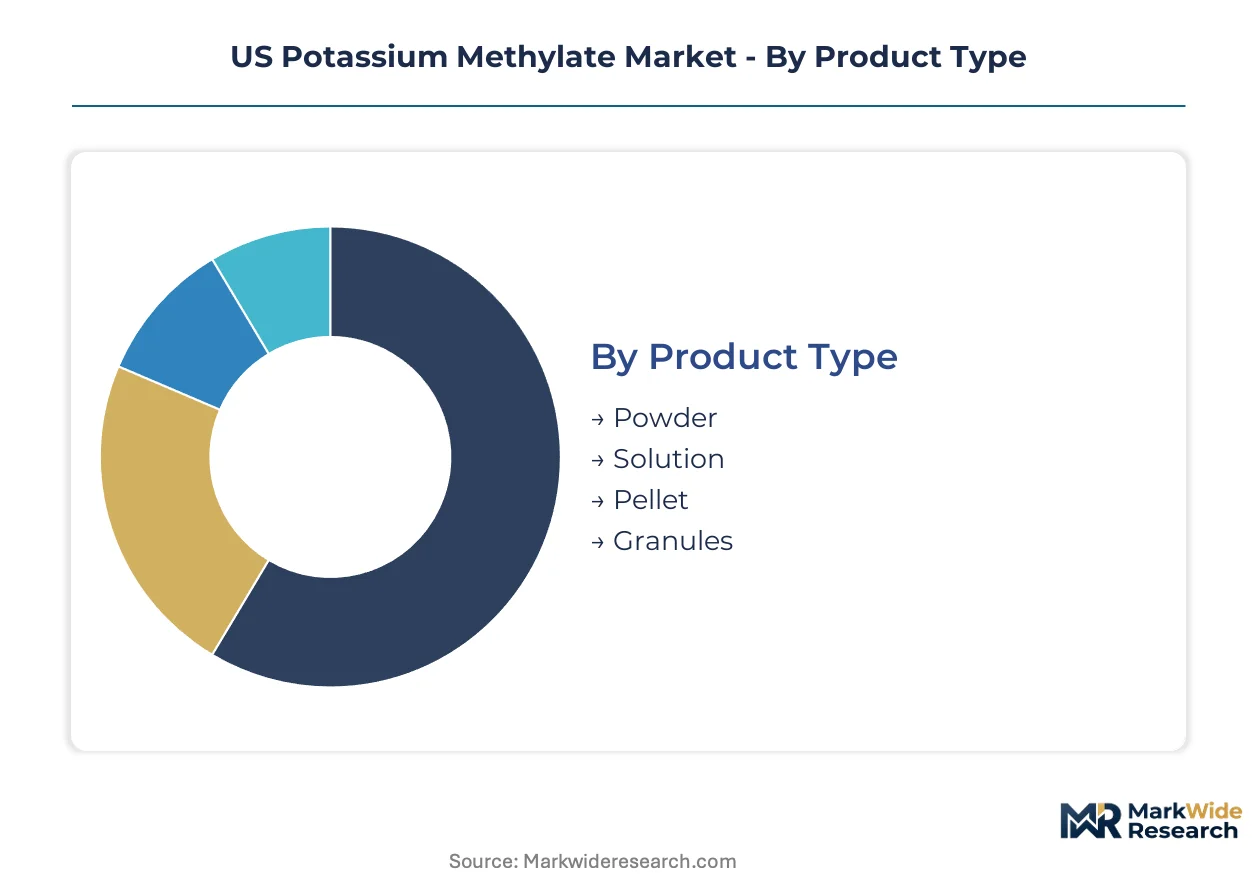
Potassium methylate procurement patterns diverge sharply across product grades and end-use specifications. EPA renewable fuel documentation, FDA current good manufacturing practice standards, and OSHA process safety management protocols create tiered compliance burdens that reshape supplier-buyer matching.
Product Type:
FDA qualification requirements and OSHA pyrophoric handling protocols apply differentially across physical forms, with moisture-sensitive grades demanding specialized containment and documentation.
- Solution:Liquid formulation typically manufactured at 25-32% concentration in methanol serves continuous-flow biodiesel reactors with automated dosing compatibility. Iowa and Illinois refiners favor this grade for transesterification efficiency, though DOT hazmat shipping rules constrain distribution radius.
- Powder:Anhydrous crystalline form commands premium positioning in pharmaceutical active ingredient synthesis where moisture content below 0.1% is mandatory. FDA cGMP batch certification and dedicated packaging lines limit supplier pool to specialty chemical houses with life sciences infrastructure.
- Pellet:Compressed solid format reduces dust exposure during handling and storage, appealing to chemical synthesis facilities with limited alkoxide expertise.
- Granules:Intermediate particle size distribution balances flowability with surface area for controlled reactivity in agricultural chemical intermediate production.
Leading the category by volume: Solution. Growing fastest: Powder.
Application:
End-use concentration determines margin structure, with pharmaceutical and agricultural chemical applications capturing value through specification stringency while biodiesel operates on throughput economics.
- Biodiesel Production:Transesterification catalyst demand concentrates among Midwest renewable fuel refiners responding to EPA renewable volume obligations and California LCFS credit arbitrage. Solution-grade material dominates as continuous reactor designs displace batch processing.
- Pharmaceutical Manufacturing:High-purity powder and pellet grades support active pharmaceutical ingredient synthesis under FDA cGMP protocols. Moisture specifications and batch traceability requirements sustain pricing premiums independent of methanol feedstock cycles.
- Chemical Synthesis:Strong base applications in fine chemical manufacturing pull standard-grade material through distributor channels serving regional synthesis operations.
- Agriculture Chemicals:Intermediate production for crop protection active ingredients utilizes technical-grade powder and granule forms with less stringent moisture constraints than pharmaceutical applications.
Deepest volume pool: Biodiesel Production. Steepest expansion trajectory: Pharmaceutical Manufacturing.
End User Industry:
Procurement sophistication varies by buyer technical capability, with integrated energy companies negotiating direct supply agreements while specialty chemicals firms rely on distributor intermediation.
- Energy Producers:Renewable fuel refiners in Minnesota and Iowa consolidate purchasing through long-term offtake contracts with penalty structures for delivery failure. Direct supplier relationships displace distributor channels as volume commitments climb.
- Specialty Chemicals Companies:Fine chemical synthesis operations demand technical-grade material with flexible lot sizing and rapid specification documentation for multi-step process validation.
- Crop Protection Firms:Agricultural chemical manufacturers prioritize cost-efficient technical grades with reliable supply continuity over premium purity metrics.
- Life Sciences Organizations:Pharmaceutical and biotechnology entities impose the most stringent qualification protocols, requiring dedicated manufacturing lines and audit rights extending to methanol source documentation.
Dominant procurement volume: Energy Producers. Expanding most quickly: Life Sciences Organizations.
Packaging Type:
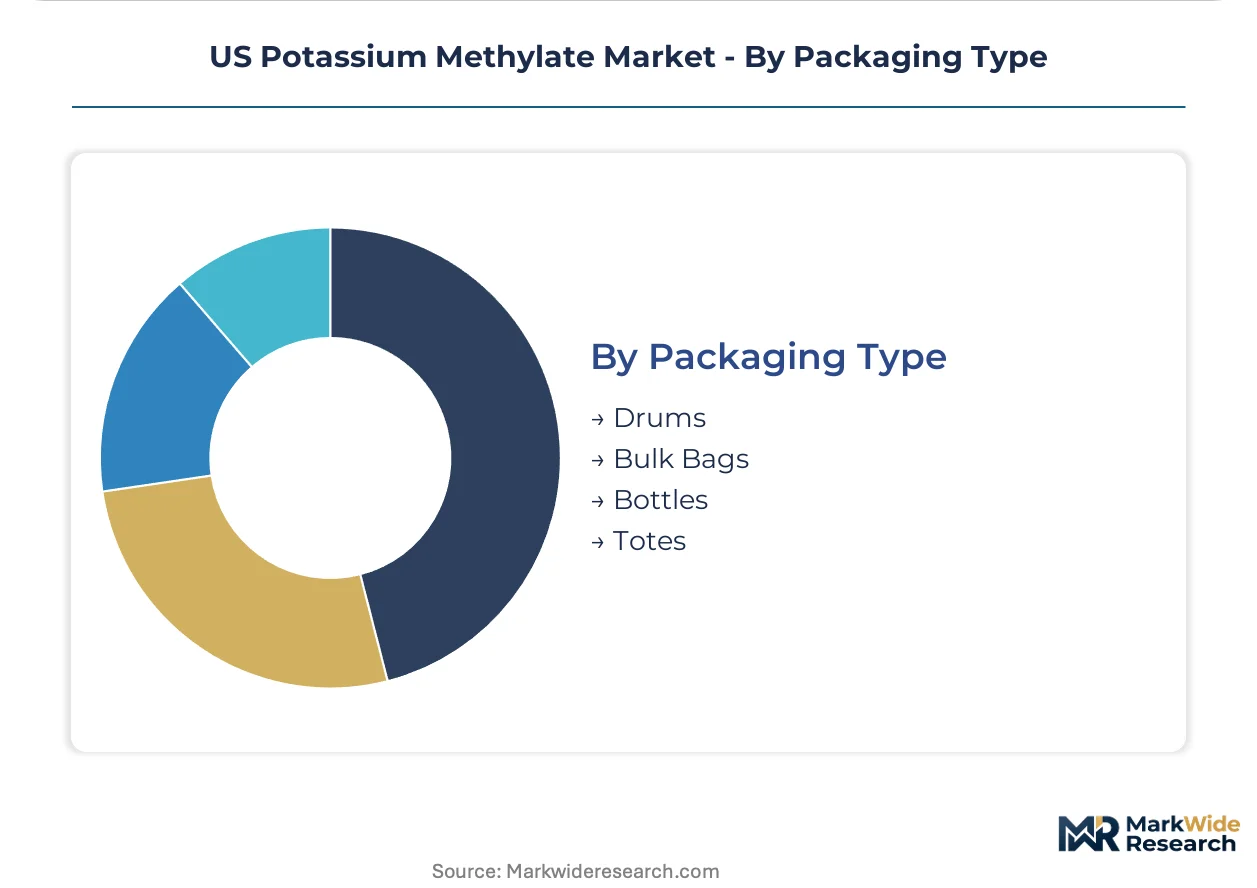
Freight economics and handling automation requirements reshape container preferences as large-volume buyers consolidate toward bulk formats with integrated dosing systems.
- Totes:Intermediate bulk containers capture share from drums among biodiesel refiners seeking reduced per-unit freight costs and compatibility with automated alkoxide injection skids.
- Drums:Steel and fiber containers retain position in chemical synthesis and smaller-scale pharmaceutical applications where lot segregation and manual handling persist.
- Bulk Bags:Flexible intermediate bulk containers serve powder and granule shipments to agricultural chemical manufacturers with pneumatic transfer infrastructure.
- Bottles:Small-format glass and fluoropolymer containers deliver laboratory-scale quantities for pharmaceutical research and development with shelf-life preservation requirements.
Fastest format conversion: Totes. Steady decline: Drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest Renewable Fuel Incentive Zones concentrate demand across Iowa, Illinois, and Minnesota as state-level tax credits and EPA renewable volume obligations pull production capacity toward the Corn Belt. State low-carbon fuel standards in California and Oregon transmit procurement pressure eastward through LCFS credit arbitrage.
Iowa
Biodiesel refineries in Des Moines and Cedar Rapids expand continuous-flow reactor capacity to capture EPA renewable identification numbers. The Iowa Renewable Fuel Infrastructure Program subsidizes storage and blending equipment upgrades. Sioux City processors negotiate long-term potassium methylate offtake contracts with penalty clauses for delivery failure.
Illinois
Chicago-area chemical distributors face margin compression as integrated energy companies shift to direct supplier relationships. The Illinois Renewable Fuel Standard mandates escalating biofuel blends through 2030. Peoria and Decatur production facilities demand chain-of-custody documentation tracing catalysts to specific methanol sources.
Minnesota
Cooperative refineries in Mankato and Albert Lea consolidate vendor bases from multi-supplier rotation to single-source contracts. The Minnesota Biodiesel Content Act requires minimum renewable diesel percentages. Twin Cities logistics hubs underdevelop Nebraska and Kansas distribution infrastructure, creating first-mover gaps.
Louisiana
Gulf Coast methanol corridors supply anhydrous solution grades to Midwest buyers via barge and rail networks. OSHA process safety management requirements govern pyrophoric handling at Baton Rouge transfer terminals. Hurricane exposure concentrates supply risk without geographic diversification alternatives.
California
LCFS credit pricing transmits through arbitrage chains to Iowa and Illinois procurement desks. CARB enforcement mechanisms tighten mass-balance documentation for catalyst origin verification. Los Angeles and San Francisco Bay Area importers qualify renewable identification numbers through supplier-certified methanol sourcing.
US Potassium Methylate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: integrated chemical majors with captive methanol-to-methoxide infrastructure, specialty distributors serving regional synthesis operations, and life sciences suppliers with FDA qualification capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as participants defend positioning against sodium methoxide substitution.
Within the integrated chemical tier, BASF SE and Evonik anchor differentiated supply positions. BASF exemplifies cost-advantaged production through backward control over methanol feedstock and methoxide conversion. Evonik occupies a specialty-grade position aligned with pharmaceutical manufacturing protocols. Among materials science suppliers, American Elements represents high-purity powder specifications for life sciences applications. Thermo Fisher Scientific and Sigma-Aldrich Corporation sit within the laboratory-scale distribution tier serving research and development channels with shelf-life preservation packaging.
| Leading Market Players |
|---|
| GELEST, Inc. |
| Thermo Fisher Scientific, Inc. |
| Sigma-Aldrich Corporation |
| American Elements |
| BASF SE |
| Evonik |
| Brenntag NV |
| SRS International |
| Eastman Chemical Company |
| Others |
Pricing and Supply Chain Analysis
Drum-to-tote packaging consolidation among Iowa and Illinois biodiesel refiners is compressing supplier margins and forcing methanol-to-methoxide producers to absorb freight efficiencies or lose volume commitments.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Minnesota cooperatives demand just-in-time alkoxide delivery to avoid storage degradation risks. Three-tier pricing structure across pharmaceutical-grade powder, technical-grade solution, and economy-grade granules separates FDA-cGMP-certified batches from standard biodiesel catalysts. Cost compression in technical-grade solution is intensifying because sodium methoxide substitution erodes potassium methylate share in non-food-grade applications. Energy producers exhibit highest price sensitivity through consolidated long-term offtake negotiations, while life sciences organizations accept premium positioning for batch traceability.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast methanol corridors where Louisiana production assets concentrate anhydrous solution supply without geographic diversification alternatives. The US Potassium Methylate Market draws from domestic methanol production along Texas and Louisiana chemical corridors, with supplemental technical-grade powder imports from Germany and India. Natural gas price volatility transmits directly to methanol feedstock costs, creating margin squeeze without immediate pass-through mechanisms. Distribution runs through barge and rail networks to Midwest renewable fuel hubs, with Baton Rouge transfer terminals governed by OSHA pyrophoric handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA renewable volume obligation enforcement and sodium methoxide substitution pressure are forcing sub-scale alkoxide suppliers toward exit or acquisition, consolidating viable production capacity among integrated chemical majors.
For Market Incumbents: Deepen backward integration into captive methanol production to insulate margins from natural gas price swings transmitted through Gulf Coast feedstock markets. Expand automated dosing system deployment to capture safety-conscious chemical synthesis buyers seeking OSHA process safety management alignment. Defend against sodium methoxide displacement by emphasizing catalyst recovery economics in food-grade biodiesel applications where potassium methylate retains technical superiority. For New Entrants and Emerging Players: Launch via regional blending and storage facilities in Nebraska and Kansas where underdeveloped logistics infrastructure creates first-mover advantage for Great Plains distribution hubs. Target pharmaceutical-grade powder certification to access FDA cGMP-qualified active pharmaceutical ingredient synthesis demand with pricing premiums independent of commodity cycles. Pursue direct relationships with Minnesota cooperative refineries shifting from multi-supplier rotation to single-source contracts. For Investors and Strategic Acquirers: The window for entry favors specialty chemical houses with existing life sciences infrastructure and FDA qualification capabilities. Long-term viability hinges on securing methanol supply agreements with pricing mechanisms that buffer natural gas volatility. Watch for Iowa and Illinois refinery consolidation announcements as inflection indicators for catalyst procurement volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Production | Captive methanol supply insulates BASF and Evonik from natural gas price transmission. |
| Pharmaceutical-Grade Certification Investment | FDA cGMP qualification opens premium positioning in active pharmaceutical ingredient synthesis. |
| Automated Dosing System Deployment | OSHA-aligned pyrophoric handling protocols capture safety-conscious chemical synthesis buyers. |
| Great Plains Distribution Hub Establishment | Nebraska and Kansas facilities address logistics gaps for biodiesel refiners seeking freight efficiencies. |
| Long-Term Offtake Agreement Structuring | Penalty clauses for delivery failure secure volume commitments from Minnesota cooperative refiners. |
Research Methodology
Independent corroboration across EPA renewable fuel standard documentation, OSHA process safety management filings, and FDA cGMP inspection records underwrites the qualitative findings on compliance-driven procurement patterns. Primary interviews with biodiesel plant managers, specialty chemical procurement leads, pharmaceutical manufacturing directors, and methanol supply specialists were combined with secondary validation from EIA energy data, ACC chemical industry reports, and SEC 10-K disclosures from integrated chemical majors. Bottom-up volume triangulation across Iowa, Illinois, and Minnesota production facilities was cross-checked against top-down market sizing from methanol consumption correlations.
Rate-of-change decomposition across the analysis window separated volume growth from pricing dynamics and mix shifts between solution, powder, pellet, and granule grades. Segmentation dimensions modeled include physical form, end-use application, packaging type, and regional production hub concentration. CAGRs were derived from regression analysis against EPA renewable volume obligation trajectories and state-level low-carbon fuel standard adoption curves. Forecast inputs incorporated methanol feedstock cost sensitivity and sodium methoxide substitution elasticity in non-food-grade biodiesel segments.
Methanol price volatility, hurricane disruption frequency along Gulf Coast corridors, and sodium methoxide technical advancement are the dominant revision risks that could reshape supply security assumptions and catalyst substitution timelines. Forecasts reflect documented assumptions about EPA enforcement continuity and state LCFS program expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Amino Acids Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Soy-Based Chemical Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
L-Citrulline Market