
 Ionomer Resins Market | 2026-2036
Ionomer Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Ionomer Resins Market Intelligence
Specialty polymer chemist availability is reorganizing capacity expansion timelines across the ionomer value chain. Dow leverages backward integration into ethylene-acrylic acid feedstocks to secure cost positions in packaging-grade pellets. DuPont sustains technology leadership in fluorinated ionomer membranes through captive research infrastructure. SK Functional Polymer anchors Asia-Pacific supply with dedicated lines serving automotive and medical device converters.
Ionomer resins comprise thermoplastic polymers containing ionic crosslinks within hydrocarbon backbones, typically manufactured through copolymerization of ethylene with methacrylic or acrylic acid followed by partial neutralization with metal cations. These materials exhibit puncture resistance, optical clarity, and heat-seal performance that enable food packaging, golf ball covers, and battery membrane substrates. Fluorinated ionomer variants command premium positions in proton-exchange membrane applications where chemical stability determines product lifetimes. Packaging applications dominate volume consumption while medical-grade pellets attract margin concentration from sterilization-compatibility requirements and regulatory certification barriers.
REACH compliance in Europe and FDA food-contact regulations in the United States shape formulation chemistries and migration-testing protocols for ionomer film producers. Korea's MFDS medical-device material standards and China's GB food-packaging safety rules add parallel certification burdens for exporters serving multiple jurisdictions. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could recast fluorinated ionomer demand trajectories and redirect R&D investment toward halogen-free alternatives.
Market Dynamics
Fluorinated ionomer membrane demand from proton-exchange membrane energy storage systems is restructuring capacity allocation across specialty polymer producers, while food packaging multinationals tighten sealant-layer specifications that filter back to resin formulation requirements.
Growth Catalysts
- Proton-exchange membrane deployment:Energy storage system manufacturers are specifying fluorinated ionomer grades for fuel cell and electrolyzer applications, pulling capacity toward high-purity production lines.
- REACH compliance acceleration:European formulators are advancing migration-tested film architectures ahead of ECHA evaluation windows, expanding certified supplier pools for medical-device laminates.
- Ethylene-acrylic acid feedstock security:Backward integration into acid copolymer precursors is compressing pellet costs for packaging-grade ionomer producers serving heat-seal film converters.
Market Restraints
- Metal cation supply volatility:Zinc and sodium neutralization agents face price swings tied to mining output fluctuations, squeezing margin predictability for neutralized ethylene-methacrylic acid grades.
- Fluorinated precursor concentration:Perfluorinated monomer supply clusters among limited specialty chemical producers, creating single-source vulnerability for membrane-grade resin manufacturers.
- Polyolefin substitution pressure:Metallocene polyethylene advances in puncture-resistant food packaging are capturing share in non-barrier applications where optical clarity requirements relax.
Strategic Opportunities
- Halogen-free membrane R&D:Per- and polyfluoroalkyl substance restriction proposals are opening formulation space for hydrocarbon-based proton conductors in stationary storage applications.
- Medical device sterilization compatibility:Gamma and electron-beam stable ionomer grades command certification premiums in surgical packaging where FDA master file submissions create incumbent stickiness.
- Automotive lightweighting mandates:Korean and Chinese fuel cell vehicle production targets are accelerating localized membrane substrate qualification programs.
Industry Challenges
- Specialty polymer chemist scarcity:Acid copolymer neutralization expertise concentrates among aging technical workforces, extending pilot-to-production timelines for new grade introductions.
- Multi-jurisdiction certification burdens:Simultaneous FDA food-contact, MFDS medical-device, and GB packaging safety submissions stretch regulatory affairs bandwidth for film exporters.
- Legacy extrusion asset retrofit costs:Converting lines from conventional polyolefin to ionomer-compatible temperature and shear profiles requires capital outlays that mid-tier converters defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ionomer Resins Market |
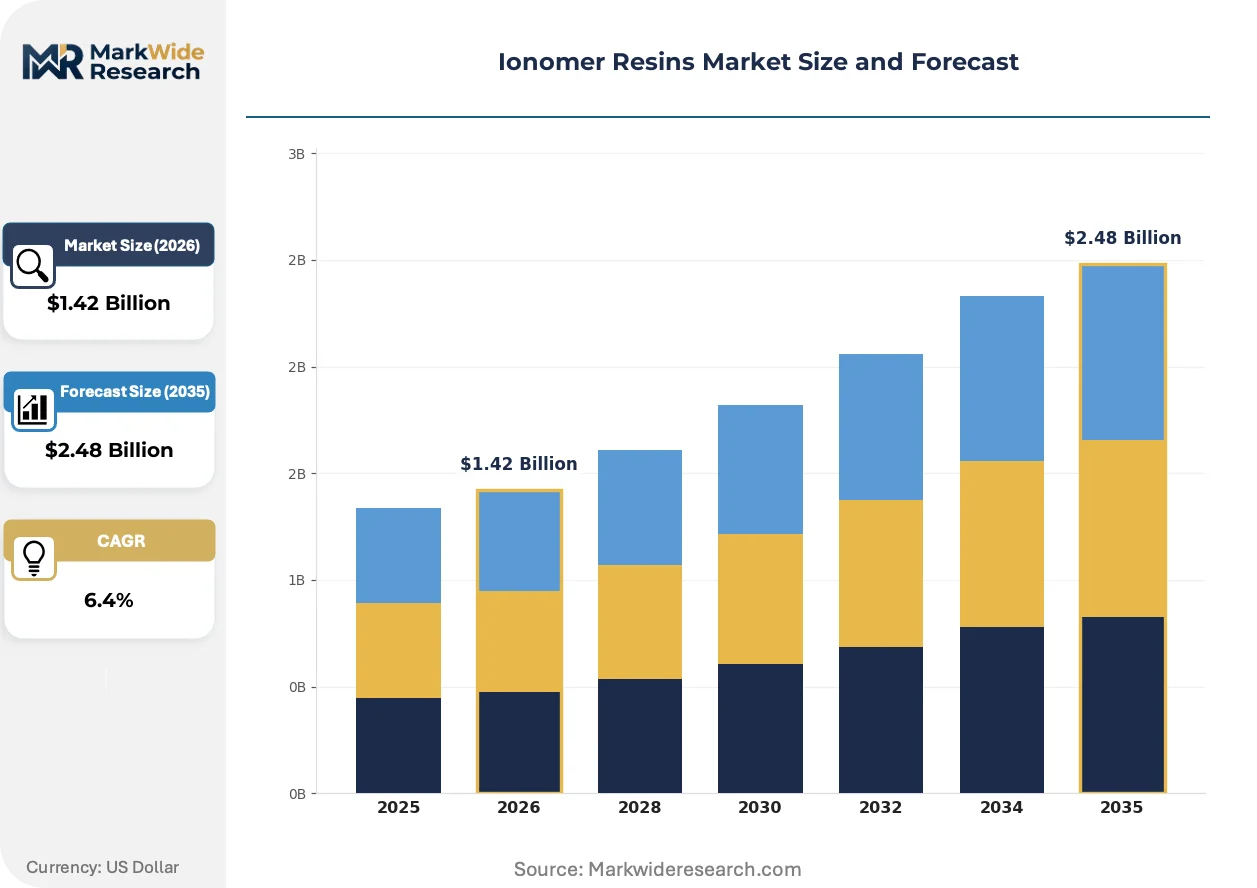
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Density Ionomer, High-Density Ionomer, Fluorinated Ionomer, Others Application: Packaging, Automotive Parts, Medical Devices, Sporting Goods Grade: Food Grade, Industrial Grade, Medical Grade, Pharmaceutical Grade Form: Pellets, Films, Coatings, Sheets |
| Companies Covered | Honeywell International Inc, Solvay, Dow, SK Functional Polymer, Kuraray, DuPont, 3M, AGC Chemicals Americas, Inc., Asahi Kasei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ionomer Resins Market Strategic Shifts & Innovations
Reformulation activity is accelerating across three vectors: membrane chemistry diversification, regulatory compliance automation, and procurement model restructuring that compresses supplier qualification cycles.
Partially fluorinated sulfonic acid ionomers are decomposing the historical trade-off between proton conductivity and mechanical durability in fuel cell membranes. Automotive stack assemblers are qualifying these grades for heavy-duty vehicle applications where lifetime operating hours exceed passenger car benchmarks. The technology is decomposing incumbent perfluorinated membrane positions by offering comparable chemical stability at reduced fluorine content, redirecting R&D budgets toward hydrocarbon backbone modifications.
EU F-Gas Regulation phase-down schedules are forcing membrane manufacturers to inventory fluorinated precursor reserves ahead of quota restrictions. Industrial gas suppliers are restructuring long-term offtake agreements to secure tetrafluoroethylene feedstock allocations for ionomer production through 2030. European electrolyzer OEMs are accelerating qualification of reduced-fluorine alternatives to hedge against import dependency as ECHA evaluates additional per- and polyfluoroalkyl substance restrictions.
Specification-driven procurement is consolidating buyer power among food packaging multinationals that publish unified sealant-layer standards across their global converting networks. Tier-one laminate producers are responding by pre-qualifying ionomer grades against multiple brand owner protocols simultaneously, compressing the traditional 18-month supplier approval cycle. This pattern concentrates order flow toward resin producers with dedicated regulatory affairs teams capable of parallel certification submissions.
Ionomer Resins Market Segmentation
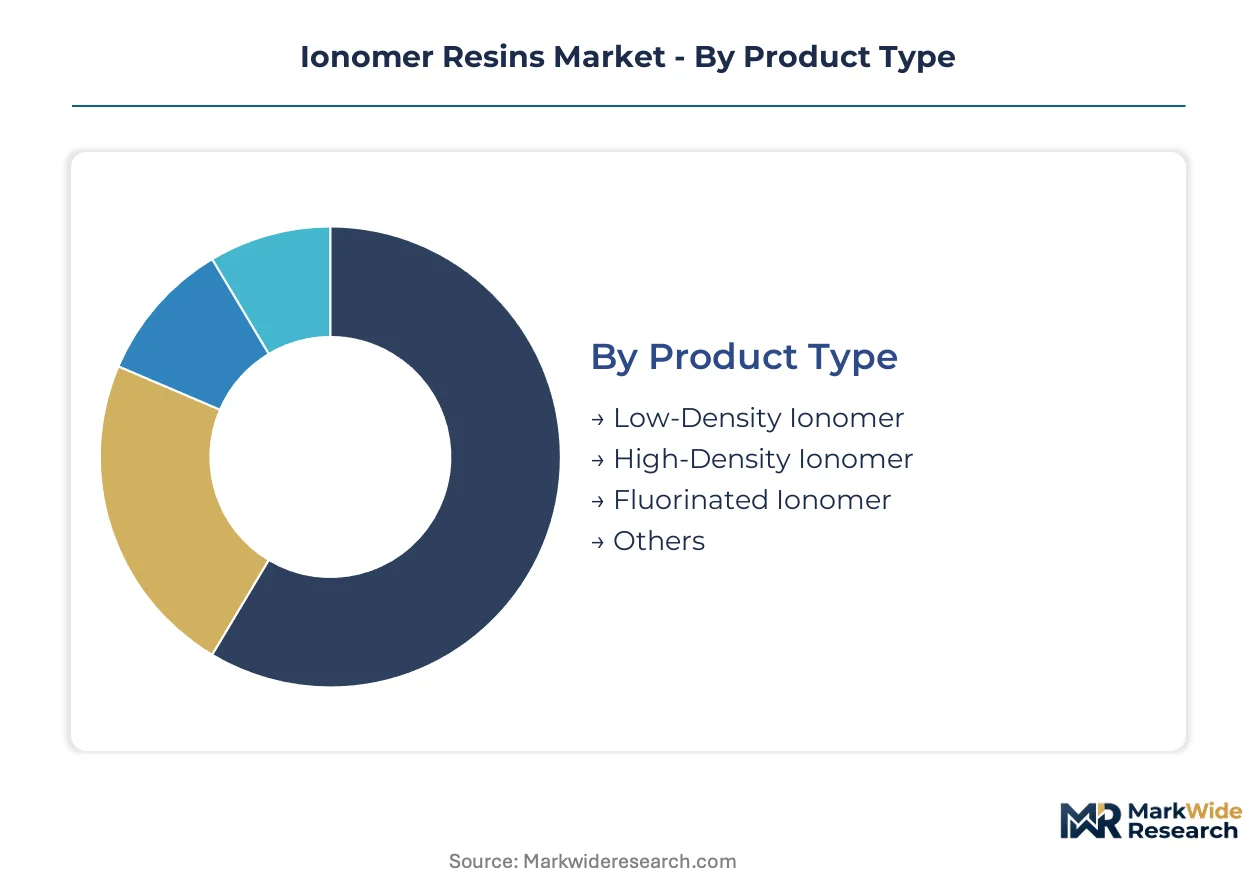
Ionomer resin specifications diverge sharply across end-use certifications, with FDA food-contact, MFDS medical-device, and REACH migration-test requirements dictating formulation chemistry rather than performance alone. Segmentation clarity enables suppliers to align production assets against qualification timelines and margin structures.
Product Type:
REACH and FDA migration thresholds separate commodity grades from certified membrane materials, with fluorine content determining regulatory scrutiny intensity across jurisdictions.
- Low-Density Ionomer:Ethylene-methacrylic acid copolymers with partial zinc or sodium neutralization yield flexible films with puncture resistance and optical clarity. Food packaging converters in South Korea specify these grades for multilayer sealant layers where SK Functional Polymer maintains dedicated production lines.
- Fluorinated Ionomer:Perfluorinated sulfonic acid backbones deliver proton conductivity for fuel cell and electrolyzer membranes. Energy storage system manufacturers in Germany and Japan are qualifying reduced-fluorine variants ahead of EU F-Gas Regulation quota restrictions.
- High-Density Ionomer:Higher acid content and crystallinity suit rigid automotive parts and golf ball cover applications.
- Others:Specialty neutralized grades include lithium and magnesium variants for niche battery separator coatings.
Established volume favors low-density grades; emerging adoption favors fluorinated ionomers.
Application:
Application segmentation tracks capital deployment patterns, with packaging assets dominating installed extrusion capacity while medical and automotive lines command qualification premiums.
- Packaging:Heat-seal films for fresh meat, cheese, and snack applications require migration-tested ionomer layers compliant with FDA food-contact notifications and EFSA evaluations. Dow's backward integration into ethylene-acrylic acid feedstocks secures cost positions for high-volume converters.
- Medical Devices:Gamma and electron-beam sterilizable grades for surgical tray packaging demand FDA master file submissions and MFDS material certifications. DuPont sustains technology leadership through captive research infrastructure for sterilization-stable formulations.
- Automotive Parts:Fuel cell vehicle production targets in Korea and China are accelerating membrane substrate qualification programs.
- Sporting Goods:Golf ball covers utilize ionomer durability and cut resistance in multi-piece construction.
Packaging absorbs the highest volume; medical devices capture the steepest expansion trajectory.
Grade:
Grade stratification reflects certification burden intensity, with pharmaceutical and medical tiers requiring parallel submissions to FDA, MFDS, and EMA that extend commercialization timelines.
- Medical Grade:Biocompatibility testing per ISO 10993 and sterilization validation protocols support surgical packaging and device component applications. Korean laminate producers anchor regional supply chains with dedicated cleanroom compounding lines.
- Food Grade:Migration testing for acid copolymer residues and metal cation extractables satisfies FDA 21 CFR 177.1330 and EFSA food-contact evaluations. European formulators advance certified film architectures ahead of ECHA evaluation windows.
- Industrial Grade:General-purpose neutralized pellets serve automotive interior and tooling applications without migration-test requirements.
- Pharmaceutical Grade:Enhanced purity protocols and extractables documentation support primary drug container applications.
Food grade commands current volume leadership; pharmaceutical grade offers the highest margin concentration.
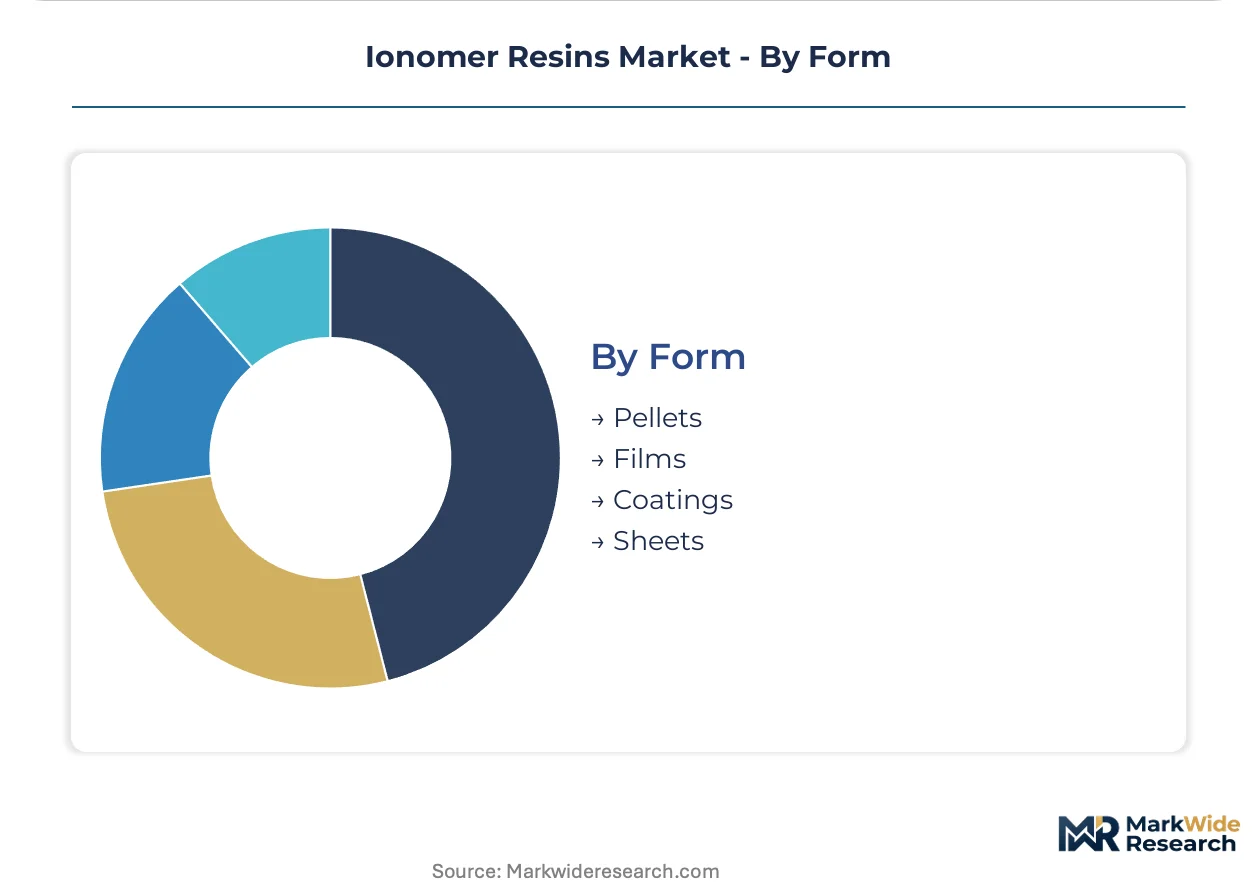
Form:
Form selection determines downstream processing economics, with pellet supply concentrating among compounders while film and sheet production fragments across converter tiers.
- Pellets:Standardized melt-flow grades enable toll compounding and captive extrusion across packaging and automotive supply chains. Backward integration into acid copolymer precursors compresses pellet costs for high-volume producers.
- Films:Coextruded ionomer layers in multilayer structures deliver oxygen barrier and heat-seal functionality for modified atmosphere packaging. Specification-driven procurement by food packaging multinationals consolidates order flow toward pre-qualified suppliers.
- Coatings:Aqueous dispersions and solvent-based systems serve textile and paper substrate treatments.
- Sheets:Thick-gauge thermoforming grades target medical tray and industrial packaging applications.
Pellets dominate upstream supply; films are gaining share fastest in downstream value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes ionomer resins disproportionately for multilayer food packaging sealants, whereas Germany and Japan concentrate demand in fluorinated membrane grades for energy storage systems. The United States splits consumption across medical device sterilization packaging and automotive fuel cell substrates. China is expanding both packaging and membrane applications simultaneously.
South Korea
Food packaging multinationals operating in South Korea specify ionomer sealant layers for modified atmosphere meat and cheese films. MFDS medical-device material standards govern surgical tray laminates exported to regional markets. SK Functional Polymer anchors national supply chains with dedicated production lines serving automotive and medical device converters in the Seoul Capital Area.
Germany
Electrolyzer OEMs in Germany qualify fluorinated ionomer membranes for green hydrogen production systems. EU F-Gas Regulation phase-down schedules force membrane manufacturers to inventory tetrafluoroethylene precursor reserves ahead of quota restrictions. Industrial gas suppliers in North Rhine-Westphalia restructure long-term offtake agreements to secure feedstock allocations through 2030.
United States
FDA food-contact notifications shape ethylene-acrylic acid copolymer formulations for fresh produce packaging films. Gamma and electron-beam sterilizable grades for surgical packaging demand FDA master file submissions that create incumbent stickiness. Dow leverages backward integration into acid copolymer precursors to secure cost positions for high-volume converters in Texas and Louisiana.
Japan
Fuel cell vehicle manufacturers specify proton-exchange membrane substrates with reduced fluorine content ahead of per- and polyfluoroalkyl substance evaluations. METI clean hydrogen roadmaps accelerate qualification timelines for domestic membrane producers. Asahi Kasei occupies a central position in Chubu regional supply chains serving automotive stack assemblers.
China
Dual carbon goals and fuel cell vehicle production targets in China accelerate localized membrane substrate qualification programs. GB food-packaging safety rules add parallel certification burdens for exporters serving multinational brand owners. Yangtze River Delta compounders expand ionomer pellet capacity to serve both domestic packaging converters and electrolyzer OEMs.
Ionomer Resins Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with backward integration into ethylene-acrylic acid feedstocks separating cost leaders from toll compounders. The market structures around three archetypes: diversified chemical conglomerates with captive research infrastructure, regional polymer specialists with dedicated cleanroom compounding lines, and fluorinated materials producers with perfluorinated monomer access. Competitive moves concentrate on capacity expansion in high-purity production lines and parallel certification submissions to compress supplier qualification cycles.
Within the diversified chemical tier, Dow and DuPont exemplify contrasting strategic positions—Dow through upstream control over acid copolymer precursors, DuPont through captive research infrastructure for fluorinated membrane formulations. SK Functional Polymer anchors the Asia-Pacific specialist tier with dedicated production assets in South Korea. Solvay occupies a distinctive position among European fluorinated materials producers navigating EU F-Gas Regulation constraints.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Solvay |
| Dow |
| SK Functional Polymer |
| Kuraray |
| DuPont |
| 3M |
| AGC Chemicals Americas, Inc. |
| Asahi Kasei |
| Others |
Cost & Logistics Intelligence
Metallocene polyethylene substitution in non-barrier food packaging is simultaneously redrawing supply geography toward commodity polyolefin producers and compressing pricing premiums for standard-grade ionomer pellets. This displacement dynamic concentrates margin protection in certified medical and membrane grades where regulatory barriers sustain value capture.
Pricing Analysis
Long-term offtake agreements dominate fluorinated ionomer membrane procurement, with electrolyzer OEMs locking in tetrafluoroethylene feedstock allocations through structured contracts. Three-tier pricing structure across pharmaceutical, medical-device, and industrial grades reflects certification burden intensity, with FDA master file submissions commanding substantial premiums over food-contact tiers. Cost compression in packaging-grade pellets is intensifying because metallocene polyethylene advances capture share in optical-clarity-relaxed applications. Food packaging converters exhibit highest price sensitivity, while energy storage system manufacturers accept premium positioning for proton-exchange membrane substrates.
Supply Chain Analysis
Strategic stockpiling of fluorinated precursors prevails among European membrane manufacturers navigating EU F-Gas Regulation quota restrictions. Supply concentrates in South Korea, the United States, and Germany, with ethylene-acrylic acid feedstock security resting on backward-integrated producers. Zinc and sodium neutralization agents, perfluorinated monomer precursors, and acid copolymer resins constitute critical input dependencies. Single-source vulnerability in perfluorinated monomer supply creates structural risk for membrane-grade manufacturers. Distribution runs through toll compounders serving converter networks, with pre-qualified supplier status determining order flow concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ionomer resin demand is recovering from cyclical lows as fuel cell vehicle production targets and electrolyzer deployment schedules reactivate membrane substrate procurement. Capital expenditure cycles in energy storage systems provide the cyclical driver justifying recovery framing.
For Market Incumbents: Secure captive research infrastructure for halogen-free membrane R&D ahead of per- and polyfluoroalkyl substance restrictions. Defend margin position by accelerating parallel FDA, MFDS, and EMA certification submissions to compress supplier qualification cycles. Backward integration into ethylene-acrylic acid precursors remains essential for cost leadership in packaging-grade volume.
For New Entrants and Emerging Players: Differentiate on gamma and electron-beam sterilization compatibility for surgical packaging applications where incumbent stickiness from FDA master files creates qualification barriers. Target pharmaceutical-grade pellet production where enhanced purity protocols and extractables documentation support primary drug container applications. Pursue joint development agreements with Korean and Chinese fuel cell vehicle stack assemblers to anchor membrane substrate qualification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional compounders possessing dedicated cleanroom production lines but lacking global certification bandwidth. Five-to-ten-year viability hinges on successful navigation of fluorinated material restrictions toward hydrocarbon-based proton conductors. Acquisition candidates should demonstrate established relationships with industrial gas suppliers for tetrafluoroethylene feedstock security. Watch EU ECHA evaluation timelines for per- and polyfluoroalkyl substance restrictions as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Copolymer Feedstocks | Dow's upstream control over ethylene-acrylic acid precursors compresses pellet costs for packaging converters. |
| Halogen-Free Membrane R&D Program | DuPont's hydrocarbon backbone modifications address EU F-Gas Regulation constraints while preserving proton conductivity. |
| Parallel Multi-Jurisdiction Certification | Pre-qualification against FDA, MFDS, and GB standards simultaneously compresses traditional supplier approval cycles. |
| Strategic Precursor Inventory Build | German electrolyzer OEMs stockpile tetrafluoroethylene reserves ahead of EU F-Gas quota restrictions. |
| Regional Cleanroom Compounding Capacity | SK Functional Polymer's dedicated Seoul Capital Area lines anchor Asia-Pacific medical-device supply chains. |
Research Approach
A standing panel of acid copolymer plant managers, medical-device procurement leads at laminate producers, fuel cell stack assemblers, and regulatory affairs directors provided ongoing calibration across the research process. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, customs and trade data, FDA food-contact notification databases, and ECHA substance evaluation records. Bottom-up volume estimates from converter throughput data and top-down cross-checks against resin producer capacity announcements enabled triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, application, grade tier, and form, with additional dimensioning by regional regulatory cluster. CAGRs derived from historical growth rate analysis applied against capacity expansion timelines and end-use demand elasticity. Forecast inputs incorporated fuel cell vehicle production targets, electrolyzer deployment schedules, and EFSA migration-test protocol evolution.
Material uncertainties — per- and polyfluoroalkyl substance regulatory restrictions, metal cation price volatility, and metallocene polyethylene substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and feedstock supply continuity. Revision becomes warranted when EU ECHA evaluation outcomes or Korean fuel cell vehicle production shortfalls cross threshold magnitudes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Smart Polymers Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Europe Polymer Emulsion Market