
 Europe Polyacrylamide Market | 2026-2036
Europe Polyacrylamide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyacrylamide Market Insights
Project finance for municipal water infrastructure is fragmenting the competitive landscape in the Europe polyacrylamide sector, as smaller utilities gain procurement autonomy through leasing-based treatment plant upgrades. SNF leverages its backward integration into acrylamide monomer production to control raw material costs across French and German supply chains. BASF SE anchors its position through R&D intensity in high-molecular-weight cationic grades tailored to paper making and sludge dewatering. Kemira competes by specializing in emulsion-form polyacrylamides that reduce dissolution time for oil recovery operators in the North Sea basin.
Polyacrylamide is a water-soluble synthetic polymer synthesized from acrylamide monomer through free-radical polymerization, with molecular weights ranging from thousands to over 20 million Daltons depending on crosslinking density and ionic functionality. Its primary industrial purpose is to act as a flocculating and viscosifying agent, aggregating suspended particles in aqueous systems across water treatment, oil extraction, and mineral processing operations. Anionic grades dominate municipal and industrial wastewater applications due to superior performance with positively charged suspended solids, while cationic variants command premium positioning in organic sludge dewatering where charge neutralization drives cake dryness. Powder formulations retain the largest volume share across European utilities, though emulsion and liquid forms are gaining ground in oil recovery and mining applications where rapid deployment and reduced dust exposure matter.
REACH registration requirements administered by ECHA mandate comprehensive toxicity and environmental fate data for acrylamide monomer residuals, directly elevating product qualification costs and favoring producers with dedicated analytical capabilities. The EU Green Deal's zero-pollution action plan and F-Gas Regulation's broader chemical stewardship momentum are tightening permissible discharge thresholds for water treatment effluents, reinforcing specification shifts toward lower-toxicity polyacrylamide alternatives. Germany's KBA and France's ANSM have no direct jurisdiction here, but national environmental agencies in both countries enforce stricter local permitting that exceeds baseline EU standards. Stakeholders must monitor the evolving interface between ECHA's polymer registration guidance and national implementation variance, as divergence in enforcement intensity will reshape competitive access across European sub-regions.
Market Dynamics
REACH compliance costs and the EU Green Deal's zero-pollution mandate are compressing supplier margins while accelerating substitution of legacy flocculants across municipal and industrial water treatment networks.
Growth Catalysts
- EU Green Deal discharge thresholds:Tightening effluent standards under the zero-pollution action plan are displacing aluminum-based coagulants with high-performance polyacrylamide flocculants in German and Dutch wastewater facilities.
- Paper industry sludge dewatering:Scandinavian pulp and paper mills are converting to cationic polyacrylamide grades to meet stricter landfill moisture content requirements and reduce disposal volumes.
- North Sea enhanced oil recovery:Emulsion-form polyacrylamides are gaining traction among offshore operators seeking rapid deployment and reduced dissolution time for polymer flooding operations.
Market Restraints
- Acrylamide monomer price volatility:Feedstock costs fluctuate with propylene and ammonia markets, squeezing compounders lacking backward integration into monomer production.
- REACH registration burden:ECHA-mandated toxicity and environmental fate data requirements elevate product qualification costs, favoring producers with dedicated analytical laboratories and regulatory affairs infrastructure.
- Biopolymer substitution threat:Chitosan and starch-based flocculants are capturing niche applications in food-grade water treatment where synthetic polymer residuals face heightened scrutiny.
Strategic Opportunities
- Polish municipal infrastructure:Leasing-based treatment plant upgrades are granting procurement autonomy to smaller utilities in Eastern Europe, fragmenting demand and creating entry points for mid-tier suppliers.
- Mining tailings management:Anionic polyacrylamides are penetrating mineral processing operations in Iberian Peninsula copper and lithium extraction, where water recycling mandates intensify flocculant consumption.
- CSRD-aligned sustainability reporting:Large water utilities face Scope 3 disclosure requirements that favor suppliers offering certified low-toxicity grades with transparent supply chain documentation.
Industry Challenges
- Analytical chemistry talent scarcity:Acrylamide monomer residual testing at parts-per-billion levels requires specialized chromatography expertise that competes with pharmaceutical and food safety sectors for limited European laboratory personnel.
- Legacy dosing system incompatibility:Municipal utilities operating 1980s-era dry polymer make-down equipment struggle to handle modern high-molecular-weight emulsion products without capital-intensive retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyacrylamide Market |
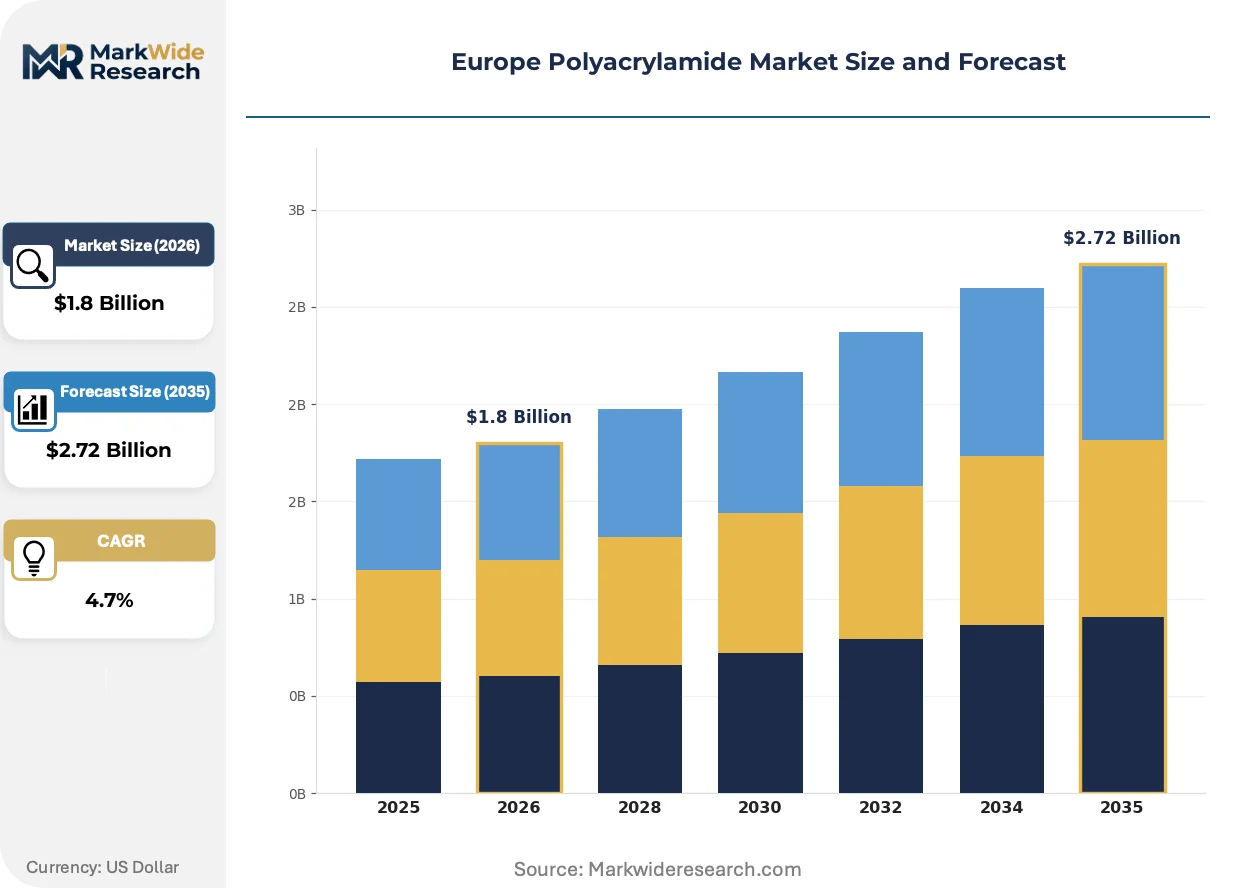
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Ionic, Anionic, Cationic, Amphoteric Application: Water Treatment, Oil Recovery, Paper Making, Mining End User: Agriculture, Construction, Wastewater, Chemical Form: Powder, Emulsion, Gel, Liquid |
| Companies Covered | SNF, BASF SE, Kemira, Solenis, Solvay, Ashland, INEOS, Mitsui Chemicals, Nouryon, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyacrylamide Market Trends and Innovations
Formulation chemistry and regulatory disclosure requirements are converging to reshape product specifications, manufacturing footprints, and buyer-supplier contracting structures across European water treatment markets.
Dual-function polyacrylamide hybrids incorporating both flocculating and scale-inhibition chemistries are hybridizing conventional single-purpose additives. Offshore oil operators in the Norwegian sector are piloting these formulations to reduce chemical inventory complexity on platform facilities. The technology is hybridizing procurement categories that suppliers previously sold as separate product lines, compressing addressable market definitions.
REACH polymer registration guidance revisions under ECHA review are elevating data requirements for imported polyacrylamide grades. Non-EU manufacturers face extended dossier preparation timelines and higher testing expenditures to maintain market access. German and French environmental agencies are enforcing national implementation that exceeds baseline EU standards, creating regulatory friction for suppliers relying on centralized European registration strategies.
Performance-based service contracts are displacing traditional volume-based chemical supply agreements in large municipal utilities. Dutch water authorities in the Randstad conurbation are contracting for guaranteed suspended solids removal outcomes rather than tonnage deliveries. This restructures supplier economics toward technical service intensity and remote monitoring capabilities rather than manufacturing scale alone.
Europe Polyacrylamide Market Segmentation
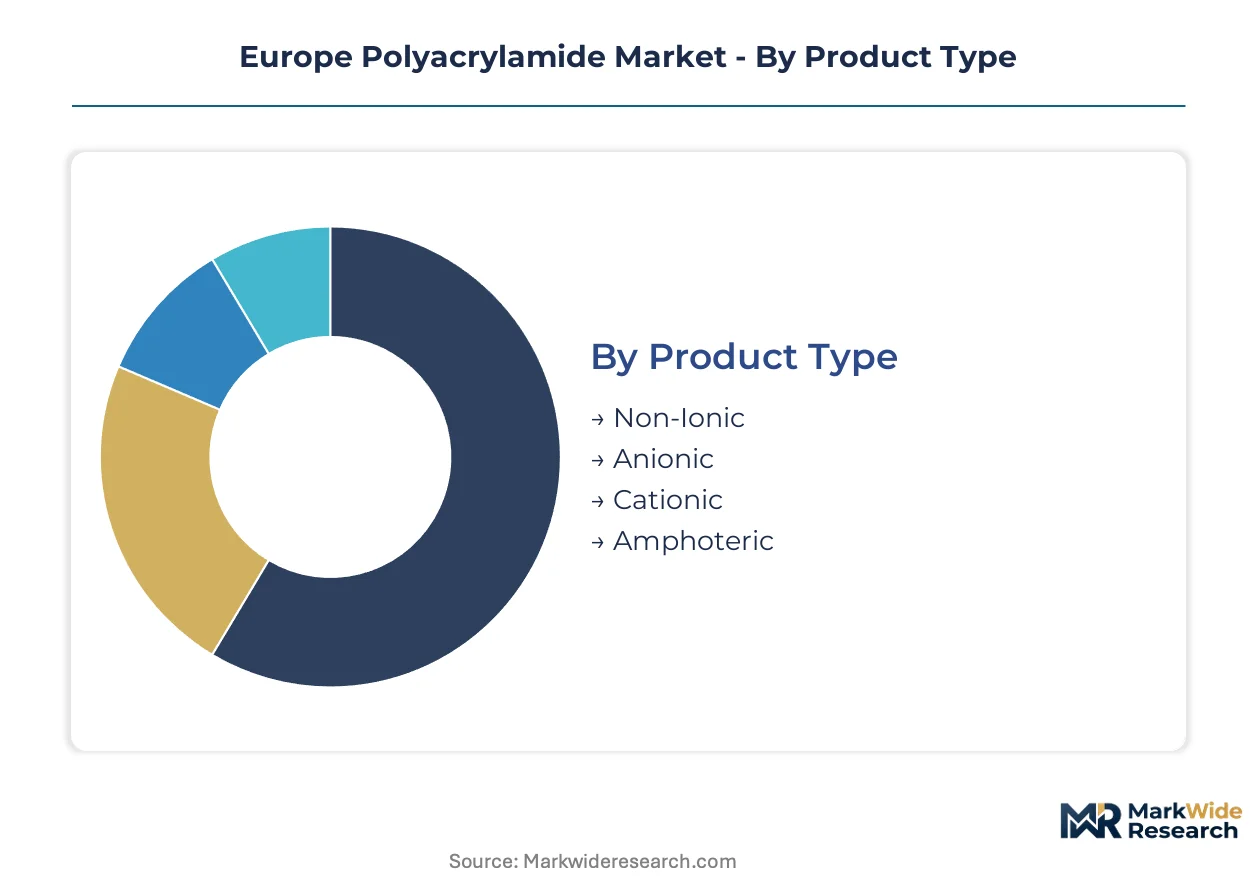
Polyacrylamide specifications diverge sharply across European end-uses, with ionic charge, molecular weight, and physical form determining performance in wastewater clarification, sludge dewatering, and enhanced oil recovery. Procurement patterns in Germany's industrial corridor and Dutch municipal networks reveal how technical segmentation maps onto geographic demand concentration.
Product Type:
Ionic functionality dictates charge density, molecular architecture, and compatibility with target effluent chemistries across European treatment facilities.
- Anionic:Carboxylate-functionalized chains carry negative charge density optimized for inorganic suspended solids and metal-laden industrial effluents. German steelworks and Dutch municipal plants in the Randstad conurbation specify high-molecular-weight anionic grades for rapid settling of positively charged colloidal matter.
- Cationic:Quaternary ammonium groups impart positive charge for organic sludge neutralization, driving superior cake dryness in Scandinavian pulp mill dewatering operations. French wastewater authorities specify cationic variants for biological sludge handling where charge neutralization reduces disposal volumes.
- Non-Ionic:Neutral polyacrylamide chains serve specialized mining applications where ionic interference from dissolved salts would compromise flocculation efficiency.
- Amphoteric:Dual-charge functionality accommodates variable pH effluents in chemical manufacturing clusters along Germany's Rhine corridor.
Anionic grades hold installed capacity across municipal utilities. Cationic variants are rotating up the share rankings in industrial dewatering.
Application:
End-use performance requirements span from parts-per-billion clarity standards to viscosity maintenance under reservoir temperature and salinity stress.
- Water Treatment:Municipal and industrial clarification processes consume powder-form anionic polyacrylamides for coagulant aid and sludge conditioning. REACH-compliant low-toxicity specifications dominate procurement in German and Dutch utilities upgrading to EU Green Deal discharge thresholds.
- Oil Recovery:Polymer flooding operations in the Norwegian North Sea sector deploy emulsion-form products for rapid dissolution and reduced platform inventory. Offshore operators prioritize high-molecular-weight grades that maintain viscosity at reservoir temperatures exceeding 80°C.
- Paper Making:Retention and drainage aids in Scandinavian pulp mills utilize cationic grades to improve fiber recovery and reduce freshwater intake.
- Mining:Tailings flocculation in Iberian copper and lithium extraction relies on anionic variants for water recycling compliance under tightening Spanish and Portuguese environmental permits.
Water treatment holds installed capacity across European utilities. Oil recovery is rotating up the share rankings in North Sea capital programs.
End User:
Customer scale and technical sophistication fragment procurement patterns from standardized municipal tenders to performance-guaranteed industrial contracts.
- Wastewater:Municipal utilities in Germany, France, and the Netherlands specify powder-form anionic grades for primary clarification and sludge thickening. Dutch water authorities are piloting outcome-based service contracts that guarantee suspended solids removal rather than chemical tonnage.
- Chemical:Petrochemical and specialty chemical manufacturers in Germany's industrial corridor demand customized emulsion formulations for process water recycling and effluent compliance.
- Agriculture:Soil conditioning and erosion control applications in Mediterranean regions utilize lower-molecular-weight grades for irrigation efficiency.
- Construction:Tunneling and foundation works specify polyacrylamides for slurry stabilization and dewatering of excavated materials.
Wastewater holds installed capacity across municipal networks. Chemical end-use is rotating up the share rankings in performance-contracting adoption.
Form:
Physical presentation determines dissolution kinetics, dust exposure risk, and compatibility with legacy dosing infrastructure.
- Powder:Dry granular formulations retain volume leadership across European municipal utilities operating established make-down equipment. German waterworks specify powder grades for cost efficiency in large-scale clarification operations where dissolution time is not constrained.
- Emulsion:Oil-continuous dispersions enable rapid deployment in offshore oil platforms and mining remote sites where reduced dissolution time and dust elimination justify premium positioning. Norwegian sector operators favor emulsion forms for polymer flooding logistics.
- Liquid:Pre-hydrated solutions serve small utilities and intermittent applications where capital investment in dissolution equipment is uneconomical.
- Gel:High-concentration aqueous preparations target specialized laboratory and pilot-scale testing applications.
Powder holds installed capacity across legacy municipal infrastructure. Emulsion is rotating up the share rankings in offshore and remote-site deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water utilities and industrial chemical processors concentrate procurement authority across Germany, France, and the Netherlands, with Scandinavian pulp operations and Iberian mining ventures expanding the buyer map.
Germany
Chemical manufacturing clusters along the Rhine corridor and municipal water infrastructure upgrades drive anionic polyacrylamide consumption for sludge dewatering. The Federal Environment Agency enforces discharge thresholds exceeding baseline EU standards under the Water Resources Act. North Rhine-Westphalia's industrial corridor hosts steelworks and petrochemical complexes specifying high-molecular-weight grades for effluent clarification.
France
Wastewater authorities in the Île-de-France region specify cationic variants for biological sludge handling where charge neutralization reduces disposal volumes. ANSM oversight of chemical safety intersects with EU Green Deal zero-pollution implementation through stricter local permitting. The Lyon chemical basin demands amphoteric grades for variable pH effluents in specialty chemical production.
Netherlands
Randstad water authorities pilot outcome-based service contracts guaranteeing suspended solids removal rather than chemical tonnage deliveries. REACH compliance administered by ECHA elevates product qualification costs for imported grades. Rotterdam's port-industrial complex consumes emulsion-form polyacrylamides for rapid deployment in chemical logistics and treatment operations.
Sweden
Scandinavian pulp and paper mills convert to cationic polyacrylamide grades to meet stricter landfill moisture content requirements. The Swedish Environmental Protection Agency enforces EU Green Deal discharge thresholds through national implementation exceeding baseline standards. The Sundsvall timber processing corridor anchors Nordic demand for sludge dewatering specifications.
Spain
Iberian copper and lithium extraction operations deploy anionic variants for tailings flocculation under tightening environmental permits. Spanish environmental authorities enforce water recycling mandates intensifying flocculant consumption in mineral processing. The Extremadura mining belt represents emerging demand concentration for remote-site emulsion deployment.
Europe Polyacrylamide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where backward integration into acrylamide monomer production separates margin leaders from compounders. Three archetypes dominate: integrated petrochemical majors with captive monomer supply, specialty chemical houses with formulation expertise, and regional distributors with technical service capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term municipal utility contracts and offshore oil operator relationships.
Among integrated chemical producers, SNF and BASF SE exemplify the backward-integrated archetype controlling raw material costs across French and German supply chains. Kemira occupies a position representing the formulation-specialist tier with emulsion-form expertise. Solenis and Nouryon sit within the technical service-intensive segment competing on application engineering rather than manufacturing scale alone.
| Leading Market Players |
|---|
| SNF |
| BASF SE |
| Kemira |
| Solenis |
| Solvay |
| Ashland |
| INEOS |
| Mitsui Chemicals |
| Nouryon |
| Others |
Pricing and Supply Chain Analysis
Acrylamide monomer price volatility, tethered to propylene and ammonia feedstock markets, compresses compounder margins while widening the spread between backward-integrated majors and formulation-dependent suppliers across German and French procurement networks.
Pricing Analysis
Cost-plus contracts indexed to propylene and ammonia commodity benchmarks dominate polyacrylamide procurement agreements across European municipal utilities. Pricing stratifies across REACH-certified premium grades, standard industrial specifications, and economy-tier imports lacking ECHA dossier completeness. Cost compression in the economy tier is intensifying because Asian compounders are absorbing tariff exposure to maintain volume. Small Polish and Spanish utilities exhibit the highest price sensitivity, while Dutch Randstad water authorities prioritize performance guarantees over unit economics.
Supply Chain Analysis
Export-control regimes limiting dual-use chemical technology transfers constrain acrylamide monomer production equipment flows into non-EU jurisdictions. Manufacturing gravity centers on France, Germany, and Belgium, with raw material supply drawing from petrochemical complexes in the ARA region and ammonia networks extending into the Netherlands. Single-source vulnerability concentrates in acrylamide monomer supply, where three producers control captive supply for the majority of European derivative output. Distribution runs through integrated chemical distributors with technical service capabilities rather than commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based contracting platforms are reconfiguring buyer-supplier relationships around guaranteed outcomes rather than chemical tonnage, creating interoperability requirements between polymer dosing systems and remote monitoring infrastructure.
For Market Incumbents: Insulate margin structure by deepening backward integration into acrylamide monomer production or securing long-term offtake agreements with ARA-region petrochemical suppliers. Biopolymer substitution in food-grade water treatment and REACH registration cost escalation for imported competitors represent immediate threats requiring analytical laboratory infrastructure investment and regulatory affairs capacity expansion. For New Entrants and Emerging Players: Eastern European municipal infrastructure leasing programs in Poland and the Czech Republic offer procurement autonomy fragmentation that mid-tier suppliers can exploit. Mining tailings management in the Iberian Peninsula and outcome-based service contracting adoption among smaller Dutch utilities represent the most penetrable entry points. Technical service partnerships with regional distributors provide lower-capital go-to-market pathways than greenfield manufacturing. For Investors and Strategic Acquirers: Formulation-specialist targets with emulsion-form expertise and established North Sea oil operator relationships command scarcity premiums in a consolidating supplier landscape. Long-term viability hinges on CSRD-aligned sustainability documentation capabilities and analytical chemistry talent retention. The signal to monitor is ECHA polymer registration guidance divergence between baseline EU standards and national implementation by German and French environmental agencies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer | Captive raw material supply insulates SNF and BASF from propylene volatility in Rhine corridor operations. |
| Emulsion-Form Capacity Expansion | Rapid-deployment formulations address Norwegian North Sea polymer flooding logistics constraints. |
| REACH Dossier Investment | Comprehensive toxicity data submission secures market access as ECHA elevates registration requirements. |
| Performance-Based Service Contracts | Outcome guarantees for suspended solids removal restructure Dutch utility procurement economics. |
| Technical Service Partnerships | Application engineering capabilities differentiate Solenis and Nouryon from manufacturing-scale competitors. |
Research Methodology
Cross-validation between executive interviews and trade data anchors the qualitative findings across the Europe polyacrylamide sector. Primary fieldwork encompassed polymer plant managers, municipal procurement leads at German and Dutch water utilities, distribution channel partners serving Scandinavian pulp operations, and technical R&D directors at formulation houses. Secondary validation drew from ECHA registration databases, Cefic chemical industry reports, customs trade flows for acrylamide monomer, and SEC filings of publicly traded chemical majors. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates.
Calibration against historical capacity utilization rates and announced expansion projects shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed ionic functionality tier, end-use industry concentration, physical form factor, and regional production hub. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and feedstock cost cycle assumptions. Industry-specific inputs included REACH compliance cost trajectories and North Sea capital program timelines for enhanced oil recovery.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Asian compounders or accelerated biopolymer substitution would shift outcomes. Material shifts in ECHA polymer registration guidance or EU Green Deal discharge threshold implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Polyolefin Compound Market