
 Generator Sales Market | 2026-2036
Generator Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Generator Sales Market Intelligence
The ISO 8528 standard for performance and safety is rotating market access towards manufacturers with certified testing capabilities. Caterpillar Inc. leverages its extensive global distribution network to serve heavy industrial and construction clients. Cummins Inc. specializes in high-horsepower diesel and natural gas engines for data center and healthcare applications. Generac Power Systems dominates the residential and light commercial segments with a focus on inverter and solar generator technologies.
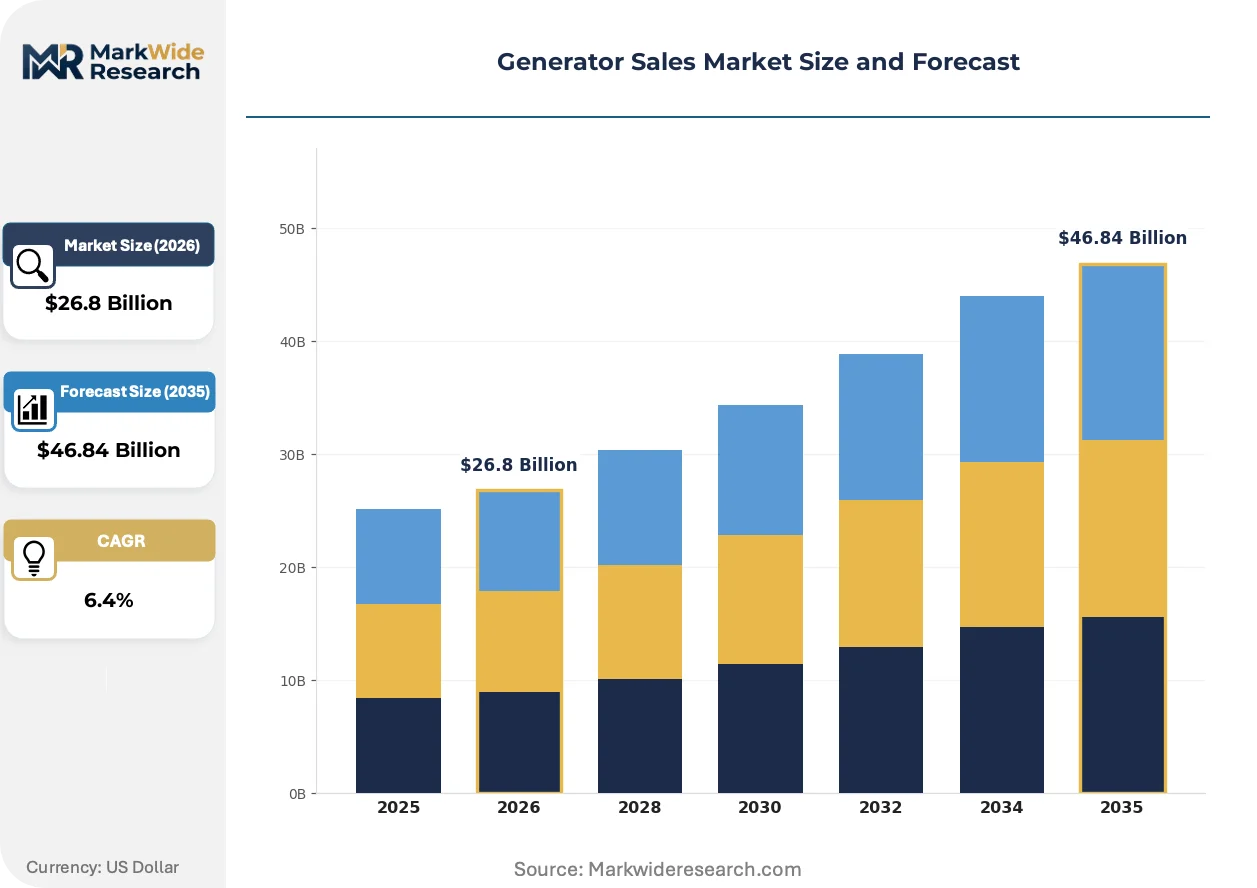
A generator is an apparatus that converts mechanical energy, typically from an internal combustion engine, into electrical power for prime or backup use. These units are specified by their power output rating, measured in kilowatts (kW), and their fuel source. Diesel generators continue to command the high-capacity segment for applications like data centers and construction sites. However, natural gas and solar generator sales are accelerating, driven by demand from residential buildings and commercial establishments seeking lower emissions and operational costs.
Regulatory frameworks, including the EPA's Tier 4 standards in the United States and the EU's Stage V emission rules, dictate engine design and after-treatment requirements. In China, the Ministry of Ecology and Environment (MEE) imposes stringent limits on both emissions and operational noise levels for industrial equipment. Navigating these divergent regional compliance pathways while managing fuel efficiency and total cost of ownership remains the central challenge for manufacturers and end users.
Market Dynamics
Stricter global emissions standards are fundamentally altering generator engine design and fuel choices. This regulatory pressure intersects with escalating power reliability needs from data centers and telecommunications, creating a central market tension between clean operation and absolute dependability.
Growth Catalysts
- Data Center Expansion:The proliferation of cloud computing and AI workloads requires massive investment in data centers, each demanding redundant backup power systems to ensure continuous uptime.
- Grid Modernization:In the United States, aging electrical grids and increased frequency of extreme weather events are driving investment in distributed power generation for grid stability and resilience.
- Cleaner Fuel Mandates:Incentives and regulations promoting natural gas and renewable-hybrid systems accelerate their adoption in residential and light commercial segments seeking lower emissions profiles.
Market Restraints
- High Compliance Costs:Adherence to multi-jurisdictional emission standards like the EPA's Tier 4 and the EU's Stage V requires significant R&D investment in engine after-treatment systems, increasing unit costs.
- Battery Storage Competition:The declining cost of battery energy storage systems (BESS) presents a direct substitution threat, especially for shorter-duration backup power needs in commercial buildings.
- Fuel Infrastructure Dependency:The growth of natural gas generators is constrained by the geographic availability of pipeline infrastructure, limiting their deployment in remote industrial or construction applications.
Strategic Opportunities
- Southeast Asian Industrialization:Rapid industrial development and infrastructure projects in nations like Vietnam and Indonesia, often with less stable power grids, create significant white space for prime and standby power solutions.
- Hybrid Power Systems:Integrating traditional generator sets with solar PV and battery storage offers a pathway to create resilient, low-emission microgrids for commercial and community applications, unlocking new service models.
- Telecommunication 5G Rollout:The deployment of 5G networks necessitates a denser array of cell towers, many in remote locations, creating an opportunity for smaller, efficient, and remotely monitored backup power units.
Industry Challenges
- Divergent Certification Pathways:Manufacturers face complexity and cost in navigating disparate regional standards, such as ISO 8528 for performance, alongside distinct noise and emission rules from China's MEE and Europe's Stage V.
- Shortage of Skilled Technicians:A persistent gap exists for qualified technicians capable of servicing modern generator sets, which feature complex electronic controls, fuel injection systems, and emissions after-treatment technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generator Sales Market |
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $46.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generator, Gasoline Generator, Natural Gas Generator, Solar Generator, Inverter Generator Technology: Automatic Voltage Regulator, Digital Control Panel, Brushless Alternator, Fuel Injection System, Noise Reduction Technology Application: Construction Sites, Data Centers, Telecommunications, Residential Buildings, Emergency Backup Power End User: Manufacturing Plants, Commercial Establishments, Educational Institutions, Government Facilities, Agricultural Operations |
| Companies Covered | Mitsubishi Heavy Industries, Kohler Co., Caterpillar Inc., Briggs & Stratton Corporation, Atlas Copco, Cummins Inc., Rolls-Royce Power Systems, Yanmar Co., Ltd., Generac Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generator Sales Market Strategic Shifts & Innovations
A fundamental shift toward integrated power management and cleaner fuel sources is redefining the generator's role from a standalone emergency asset to a component within a larger energy ecosystem. This evolution prioritizes connectivity, fuel flexibility, and regulatory compliance.
Inverter technology, which produces cleaner and more stable AC power, is increasingly integrated into portable and residential generator models. Adoption is rapid in the light commercial and residential segments, where users require power for sensitive electronics. This technology is fragmenting the traditional market by creating a distinct performance tier, separating basic emergency units from advanced models.
The ISO 8528 standard, which defines generator set performance, safety, and rating classifications, is gaining prominence as a global benchmark for market access. Compliance requires manufacturers to invest in certified testing facilities and rigorous documentation, creating a barrier for non-compliant players. This trend is most pronounced in tenders for critical infrastructure like hospitals and data centers, where adherence is now a mandatory procurement criterion.
A notable shift in buyer behavior moves from capital expenditure on wholly-owned assets toward "Power-as-a-Service" or long-term rental agreements. This model disrupts the traditional distributor-led sales channel, with energy service companies offering packages that include fuel management and uptime guarantees. This is most visible in construction and events, where project-based power needs favor operational-expense models.
Generator Sales Market Segmentation
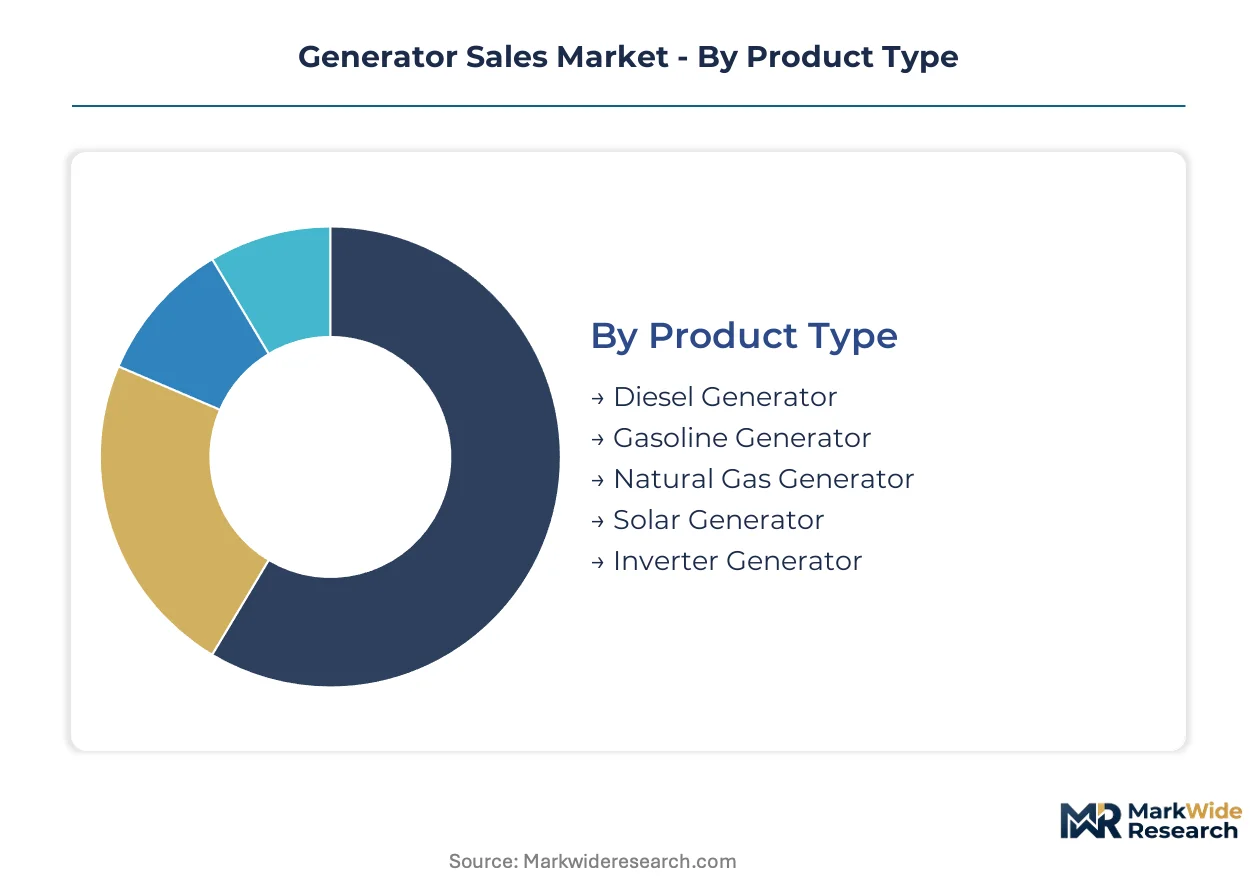
The Generator Sales Market is differentiated across several critical dimensions, reflecting varied end-user requirements and technological advancements. Understanding these distinct segments illuminates where market value concentrates and where innovation is most impactful. This segmentation analysis provides a granular view of the market's structure and its underlying demand patterns.
Product Type:
The product type segment faces significant substitution pressure as cleaner and more efficient alternatives challenge traditional fossil-fuel-based generators. Manufacturers must strategically adapt their portfolios to address evolving regulatory landscapes and end-user preferences for sustainable power solutions.
- Diesel Generator:These units typically feature robust internal combustion engines designed for high power output and extended run times, making them suitable for prime or standby power. Demand concentrates in heavy industrial applications and remote construction sites, driven by their reliability and readily available fuel infrastructure in these settings.
- Natural Gas Generator:Utilizing pipeline natural gas or propane, these generators offer lower emissions and quieter operation compared to diesel counterparts. Their adoption is expanding rapidly in commercial establishments and data centers, primarily due to stringent environmental regulations and the desire for reduced operational costs.
- Gasoline Generator:Smaller, portable units commonly used for residential backup power or light recreational activities.
- Solar Generator:Integrates photovoltaic panels with battery storage to provide emission-free power, gaining traction in off-grid residential and small commercial settings.
- Inverter Generator:Produces clean, stable AC power suitable for sensitive electronics, popular in residential and light commercial segments for quiet operation.
Diesel Generator retains volume leadership; Natural Gas Generator holds the steepest expansion curve.
Technology:
Technological advancements within generators impact both performance and compliance, with specific features enhancing operational efficiency and meeting regulatory benchmarks. The integration of advanced controls and components differentiates products across various application tiers, influencing procurement decisions.
- Digital Control Panel:These advanced interfaces provide real-time monitoring of generator parameters, remote diagnostics, and fault reporting, improving operational efficiency. Data centers and telecommunications infrastructure increasingly demand these panels for precise control and integration into broader network management systems.
- Noise Reduction Technology:Encompasses sound-attenuating enclosures, advanced muffler designs, and anti-vibration mounts to minimize operational noise levels. Urban residential installations and commercial buildings prioritize this technology to comply with local noise ordinances and enhance occupant comfort.
- Automatic Voltage Regulator:Maintains a stable output voltage regardless of load fluctuations, crucial for protecting sensitive electronic equipment.
- Brushless Alternator:Reduces maintenance requirements and improves reliability by eliminating wear-prone carbon brushes.
- Fuel Injection System:Optimizes fuel delivery for improved efficiency and reduced emissions, particularly in diesel and natural gas engines.
Digital Control Panels are increasingly essential for remote management; Noise Reduction Technology addresses critical environmental compliance for urban deployments.
Application:
The demand for generators is heavily influenced by the specific operational requirements and criticality of power supply in various end-use applications. High-stakes environments, such as data centers, drive demand for highly reliable and redundant systems, shaping product development.
- Data Centers:These facilities require uninterrupted power to maintain continuous operation of servers and cooling systems, making robust backup generators indispensable. Investment in data centers across the United States and Southeast Asian nations necessitates high-capacity, ultra-reliable generator sets with advanced monitoring capabilities.
- Emergency Backup Power:This broad category encompasses systems designed to automatically supply electricity during grid outages for essential services. Residential buildings and healthcare facilities prioritize these systems to ensure safety and continuity of critical functions during unforeseen power disruptions.
- Construction Sites:Rely on portable and stationary generators for power tools, lighting, and temporary site offices in locations without grid access.
- Telecommunications:Requires backup power for cell towers and central offices to maintain network connectivity, especially during extreme weather events.
- Residential Buildings:Utilize smaller, often portable or standby generators, to power essential appliances during home power failures.
Data Centers represent a critical, high-value application; Telecommunications deployments show significant expansion potential for smaller units.
End User:
Different end-user segments operate under distinct regulatory environments and possess unique power reliability needs, influencing the type and scale of generator solutions procured. Compliance with emission standards and operational noise limits varies significantly across industrial and commercial users.
- Manufacturing Plants:These facilities demand continuous, stable power for production lines and machinery to prevent costly downtime and ensure product quality. European manufacturing plants increasingly integrate natural gas generators to comply with stringent EU Stage V emission rules while maintaining operational continuity.
- Commercial Establishments:Includes offices, retail stores, and hotels that require backup power for lighting, HVAC, and point-of-sale systems. Businesses in urban centers often seek quieter, more efficient generator solutions to minimize disruption and meet local environmental regulations.
- Educational Institutions:Utilize generators for backup power in dormitories, labs, and administrative buildings to ensure safety and operational continuity.
- Government Facilities:Deploy generators for critical infrastructure like emergency services, administrative buildings, and military bases, prioritizing reliability and security.
- Agricultural Operations:Rely on generators for irrigation systems, livestock facilities, and remote farming equipment where grid power is unreliable or unavailable.
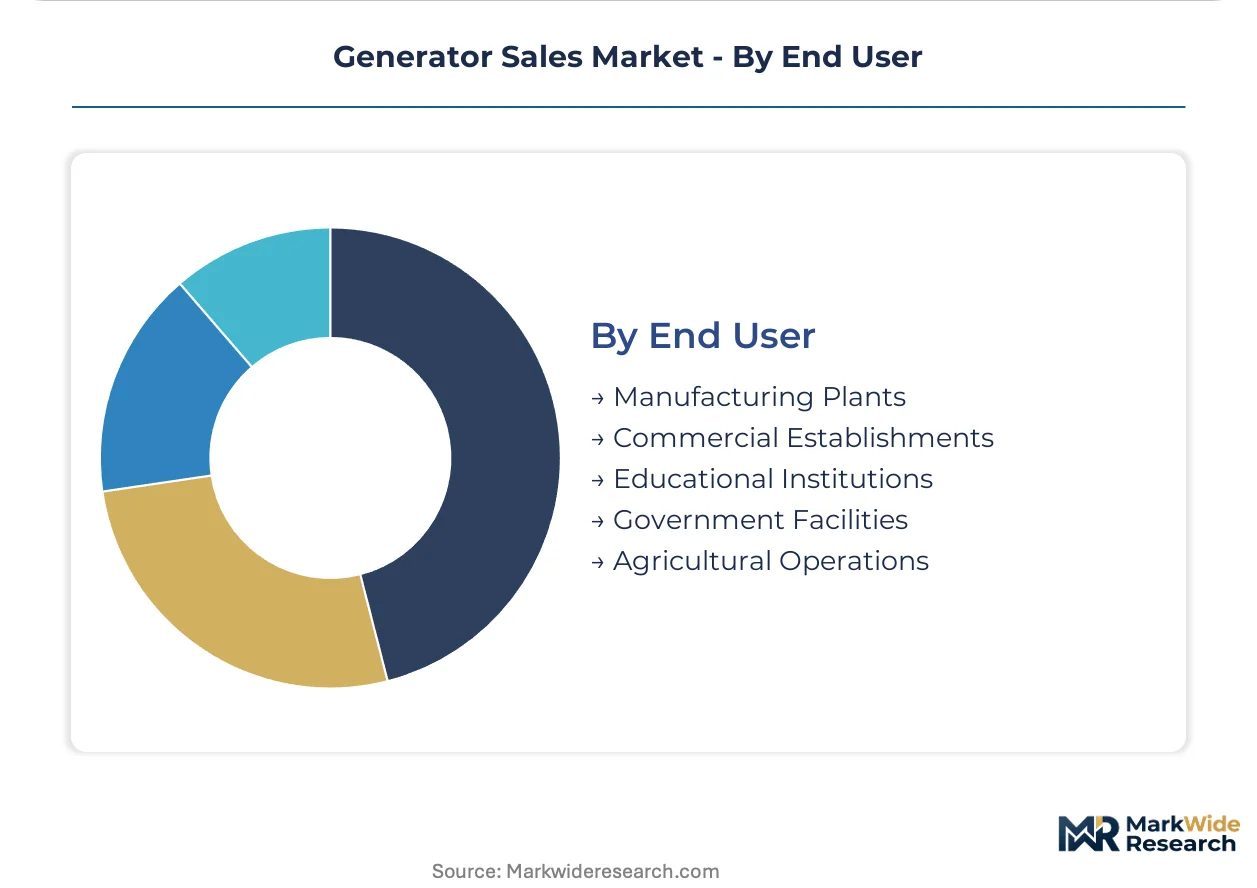
Manufacturing Plants drive consistent demand for high-capacity units; Commercial Establishments show an increasing preference for cleaner, quieter power solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aging grid infrastructure in the United States, coupled with the expansion of data centers, underwrites significant generator demand. Regional markets exhibit distinct drivers shaped by local industrial activity, regulatory frameworks, and grid stability. Manufacturers must tailor product offerings to meet varied compliance needs and application specifics across these diverse geographies.
United States
Grid modernization and the proliferation of cloud computing facilities drive demand for reliable backup power solutions. The EPA's Tier 4 regulations mandate cleaner engine designs, influencing procurement decisions for new installations. Data center clusters in Virginia and Texas require high-capacity, low-emission generator sets to ensure continuous uptime.
Germany
Manufacturing plants and commercial establishments require stable power, often integrating generators for peak shaving and backup. EU's Stage V emission rules heavily influence engine specifications, favoring natural gas and hybrid solutions. The automotive industry in Bavaria and the industrial heartland of North Rhine-Westphalia consistently invest in compliant power generation.
China
Industrial development and telecommunications infrastructure expansion necessitate robust power supply. The Ministry of Ecology and Environment (MEE) imposes stringent limits on emissions and operational noise for industrial equipment. Manufacturing hubs in the Yangtze River Delta and technology parks in Shenzhen drive demand for both prime and standby power.
India
Infrastructure projects and an often-unreliable grid stimulate demand for both prime and backup power solutions. The Central Electricity Authority (CEA) sets standards for power generation, encouraging investment in resilient systems. Industrial zones in Maharashtra and IT parks in Bangalore require consistent power to support rapid economic growth.
Vietnam
Rapid industrialization and infrastructure development, often in areas with less stable power grids, create significant demand for prime and standby power. National energy development plans prioritize reliable power access for new manufacturing facilities. Industrial parks near Ho Chi Minh City and Hanoi are key areas for generator deployment.
Generator Sales Market Key Industry Players
Listed leaders compete with private specialists across the generator sales market, offering a spectrum of solutions from high-capacity industrial units to residential backup systems. The market structure exhibits consolidation at the high-horsepower industrial end, while fragmentation characterizes the residential and light commercial segments. Strategic archetypes include diversified industrial conglomerates, specialized engine manufacturers, and residential power solution providers. Dominant competitive moves involve portfolio diversification into cleaner fuel technologies and geographic expansion into emerging industrial markets.
Within the diversified industrial conglomerate tier, Caterpillar Inc. and Mitsubishi Heavy Industries exemplify global reach and a broad product portfolio, serving heavy industrial and construction clients. Cummins Inc., a specialized engine manufacturer, focuses on high-horsepower diesel and natural gas engines for critical applications like data centers. Generac Power Systems anchors the residential and light commercial segments, with a strong emphasis on inverter and solar generator technologies.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Kohler Co. |
| Caterpillar Inc. |
| Briggs & Stratton Corporation |
| Atlas Copco |
| Cummins Inc. |
| Rolls-Royce Power Systems |
| Yanmar Co., Ltd. |
| Generac Power Systems |
| Others |
Cost & Logistics Intelligence
Manufacturing scale economies in generator production directly influence supply concentration among a few global players and establish competitive price floors across product tiers. This scale advantage shapes pricing power for high-capacity units and impacts component sourcing decisions.
Pricing Analysis
Volume-discount tiering structures characterize generator sales, where larger orders for industrial applications receive more favorable unit pricing. Price differentiation drivers include ISO 8528 certification levels for critical infrastructure and the extent of after-sales service bundles. Pricing pressure stems from the declining cost of battery energy storage systems, especially for shorter-duration backup power needs. Residential buyers demonstrate the most price sensitivity, while data centers exhibit the least due to uptime criticality.
Supply Chain Analysis
Inbound logistics costs, particularly for large engine components, significantly impact the final price of generator sets, with shipping routes from Asian manufacturing hubs facing occasional congestion. Geographic supply concentration for core engine components centers in Germany, Japan, and China. Raw material dependencies include steel for enclosures, copper for alternators, and specialized alloys for engine blocks. Single-source vulnerability for advanced electronic controls presents a structural risk. Distribution runs through a blend of direct sales to large industrial clients and a robust distributor-led channel for commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A persistent shortage of skilled technicians capable of servicing modern generator sets creates a capability gap within the market. This scarcity influences operational efficiency and long-term maintenance costs for end-users.
For Market Incumbents:Consolidate market share in high-value segments by investing in advanced diagnostic tools and training programs for complex after-treatment systems. This counters the threat of specialized service providers and ensures compliance with evolving emission standards like the EU's Stage V. Deepen vertical integration into digital control panel manufacturing to improve supply chain resilience and differentiate product offerings.
For New Entrants and Emerging Players:Certification fast-tracks for hybrid power systems offer a pathway to penetrate the generator market, particularly in residential and light commercial segments. Target underpenetrated rural areas in Southeast Asian nations, where grid instability creates demand for reliable prime power. A go-to-market angle focused on integrated solar-generator-battery solutions with remote monitoring capabilities can capture early adopters seeking sustainable power.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized engine manufacturers with strong R&D in cleaner fuel technologies and advanced digital controls. Focus on companies developing modular, scalable generator solutions for microgrid applications or specialized units for 5G telecommunications infrastructure. A signal to watch is the increasing adoption rate of Power-as-a-Service models, indicating a shift in procurement patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Cleaner Fuels | Manufacturers expand offerings to meet stricter emission standards and evolving buyer preferences. |
| Investment in Digital Control Panel R&D | Enhances remote monitoring capabilities, crucial for data centers and telecommunications infrastructure. |
| Expansion of Technician Training Programs | Addresses the critical shortage of skilled personnel for complex modern generator maintenance. |
| Strategic Partnerships for Hybrid Systems | Integrates traditional generators with renewable energy sources for resilient microgrid solutions. |
| Geographic Expansion into Southeast Asia | Captures demand from rapid industrialization and infrastructure development in emerging markets. |
Research Approach
The analysis maps generator product types, technologies, and applications, each validated through extensive interviews with original equipment manufacturers, distribution channel partners, and large-scale end-users. This comprehensive approach incorporates data from regulatory bodies like the EPA and China's MEE, alongside industry association reports and trade publications. Both bottom-up and top-down triangulation methods ensured data accuracy.
Consistency checks against external benchmarks validated all volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived by projecting demand drivers such as data center expansion and grid modernization, alongside supply-side capacity additions. Key forecast inputs included projected infrastructure spending and regional energy demand trends.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in unforeseen economic downturns or rapid shifts in energy policy. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Silent Generator Market
Generators
Southeast Asia Portable Generator Market
Generators
Construction Portable Generators Market
Generators
China Generator Sets Market
Generators
Electric Generators Market
Generators
Generator Rental Market
Generators
South America Diesel Generator Market
Generators
Marine Gensets Market
Generators
Europe Gas Generator Market
Generators
United States Portable Generator Market
Generators
United States Diesel Generator Market
Generators
Industrial Generator Market
Generators
Saudi Arabia Diesel Generator Market
Generators
India Generator Sets Market
Generators
Hand Crank Power Generator Market
Generators
Construction Generator Sets Market