
 India Portable Generator Market | 2026-2036
India Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
India Portable Generator Market Outlook
BIS certification under IS 4722 is rotating the competitive set by disqualifying unorganized assemblers from institutional tenders. Kohler Power India leverages its captive engine foundry to control cost volatility across the 5-15 kVA range. Honda India Power Products sustains brand premium in the residential inverter segment through silent-operation engineering. Kirloskar Oil Engines dominates the diesel-heavy commercial channel with a service footprint spanning over 400 Indian districts.
A portable generator is a self-contained internal combustion or electrochemical power unit rated typically below 15 kVA, designed for mobility via wheeled chassis or lift frames, producing alternating current through electromagnetic induction or solid-state inversion for off-grid or backup applications. Conventional generators still occupy the majority revenue share due to lower first-cost thresholds among price-sensitive construction buyers, though inverter generators are capturing the fastest growth in residential and telecom tower deployments where harmonic distortion below 3% protects sensitive electronics. Diesel fuel type anchors the installed base across industrial end users, while renewable energy and dual fuel variants are emerging in disaster-response and eco-sensitive commercial zones.
The Central Pollution Control Board enforces CPCB IV+ emission limits on all gensets above 800 kVA equivalent, compelling redesigns of catalytic after-treatment and electronic fuel injection systems. BIS harmonization with ISO 8528 for steady-state frequency tolerance is raising the technical barrier for new entrants seeking OEM partnerships with state electricity boards. Stakeholders must monitor how the Bureau of Energy Efficiency's star-labeling program for portable gensets reshapes procurement criteria in government-backed infrastructure projects.
Market Dynamics
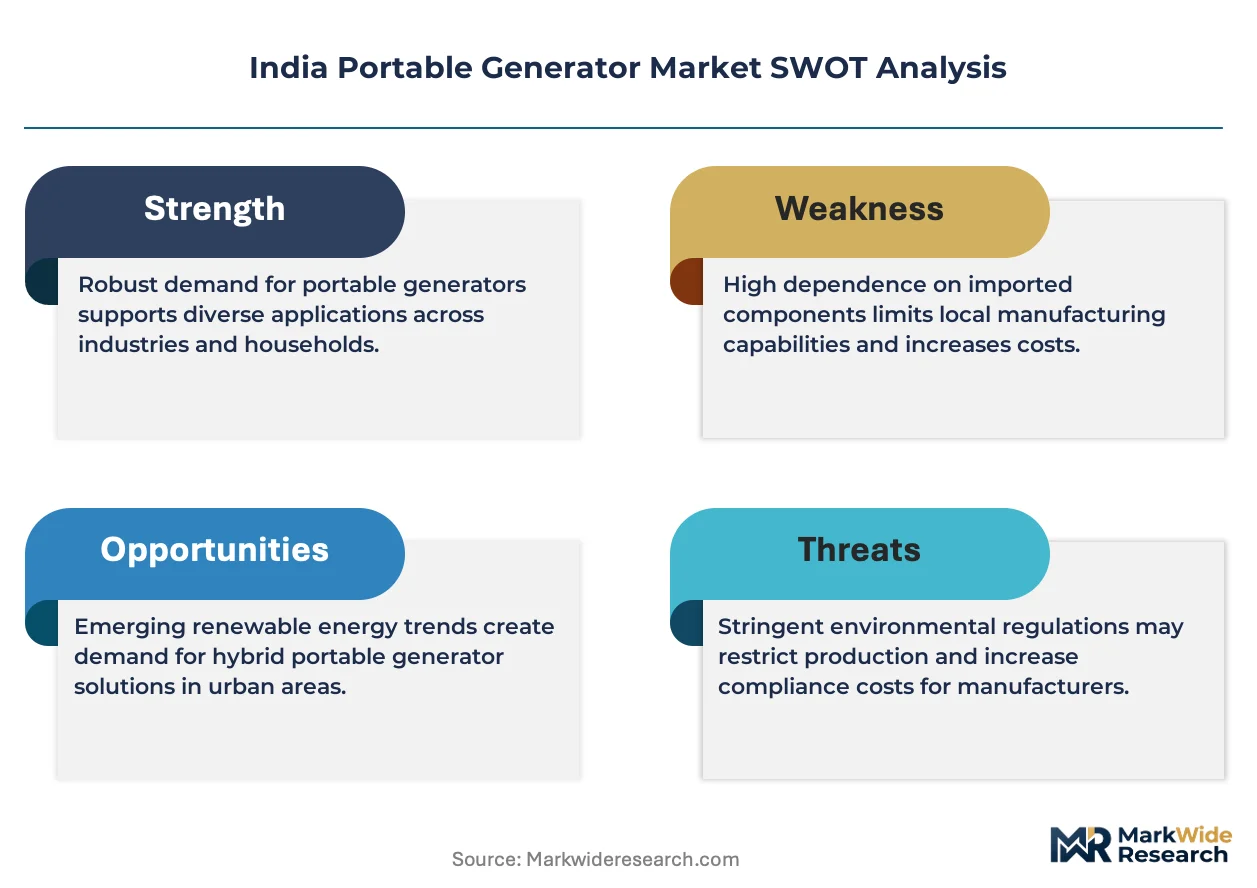
CPCB IV+ emission mandates are forcing a wholesale architecture shift from conventional diesel gensets toward inverter and dual-fuel systems, compressing margins for assemblers lacking catalytic after-treatment capabilities.
Growth Catalysts
- Grid Instability in Manufacturing Corridors:Pune, Coimbatore, and Ahmedabad experience seasonal voltage fluctuations during peak industrial demand, driving diesel generator deployment among small and medium enterprises.
- Telecom Tower Electrification:Tower operators mandate sub-3% total harmonic distortion for sensitive base station electronics, accelerating inverter generator specification in rural network expansion.
- Construction Sector Expansion:Maharashtra and Gujarat infrastructure projects require uninterrupted power for concrete curing and crane operations, sustaining fleet orders across the 5-15 kVA range.
Market Restraints
- Steel and Copper Input Volatility:Stator windings and engine blocks face commodity price swings that erode first-cost competitiveness for domestic manufacturers.
- Foundry Capacity Concentration:Captive engine production remains limited to integrated players, forcing independent assemblers into import-dependent supply chains.
- BIS Certification Barriers:IS 4722 harmonization with ISO 8528 frequency tolerance standards disqualifies unorganized producers from state electricity board tenders.
Strategic Opportunities
- Disaster Response Dual-Fuel Systems:Kerala and Odisha state disaster management authorities seek portable gensets with LPG-diesel flexibility for cyclone-prone coastal zones.
- Bureau of Energy Efficiency Star Labeling:Proposed efficiency grading for portable gensets will reshape procurement criteria in government-backed highway and railway projects.
- Residential Inverter Penetration:Silent-operation engineering opens premium positioning among urban households with home-office power backup requirements.
Industry Challenges
- After-Treatment Integration Complexity:Catalytic converter and electronic fuel injection retrofitting extends product development cycles for legacy diesel platforms.
- Service Network Density Requirements:Pan-India spare parts logistics and technician certification strain working capital for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Portable Generator Market |
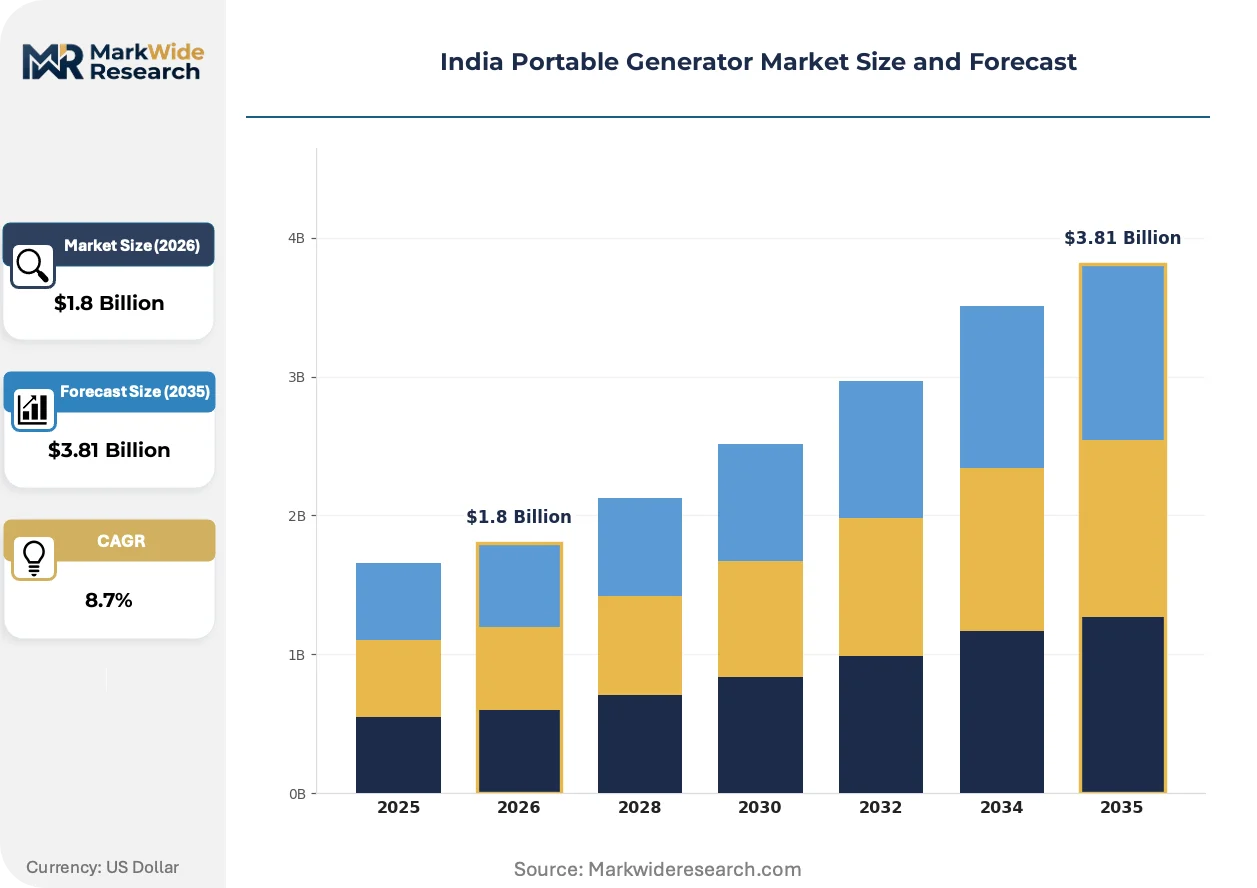
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverter Generator, Conventional Generator, Solar Generator, Dual Fuel Generator Fuel Type: Diesel, Gasoline, Propane, Renewable Energy End User: Residential, Commercial, Construction, Emergency Services Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Kohler Power India Private Limited, Atlas Copco (India) Limited, Honda India Power Products Limited, Sudhir Power, Himalayan Power Machine Manufacturing Company, Kirloskar Oil Engines Limited, Greaves Cotton Limited, Skyline Power Solutions Private Limited, Mahindra & Mahindra Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Portable Generator Market Strategic Shifts
Inverter topology is compressing the traditional gap between portable and stationary power systems, enabling variable-speed engine control that cuts fuel consumption and noise emissions simultaneously.
Silicon carbide power electronics is miniaturizing inverter genset form factors while maintaining sine wave purity. Telecom tower operators in Tamil Nadu and Karnataka are specifying these units for remote site deployment. The technology is miniaturizing the 5-10 kVA class into wheeled enclosures previously reserved for sub-3 kVA residential models.
CPCB IV+ mandates from the Central Pollution Control Board enforce particulate matter and nitrogen oxide limits on all gensets above 800 kVA equivalent. Engine manufacturers must redesign combustion chambers and add selective catalytic reduction systems. Commercial and industrial segments in Delhi-NCR face the steepest compliance costs due to airshed severity classifications.
Equipment-as-a-service arrangements are displacing outright purchase in construction and event management verticals. Rental fleet operators in Mumbai and Bengaluru now bundle fuel, maintenance, and uptime guarantees into monthly contracts. Channel intermediaries in western India report the fastest contract penetration among mid-sized contractors with irregular project pipelines.
India Portable Generator Market Segmentation
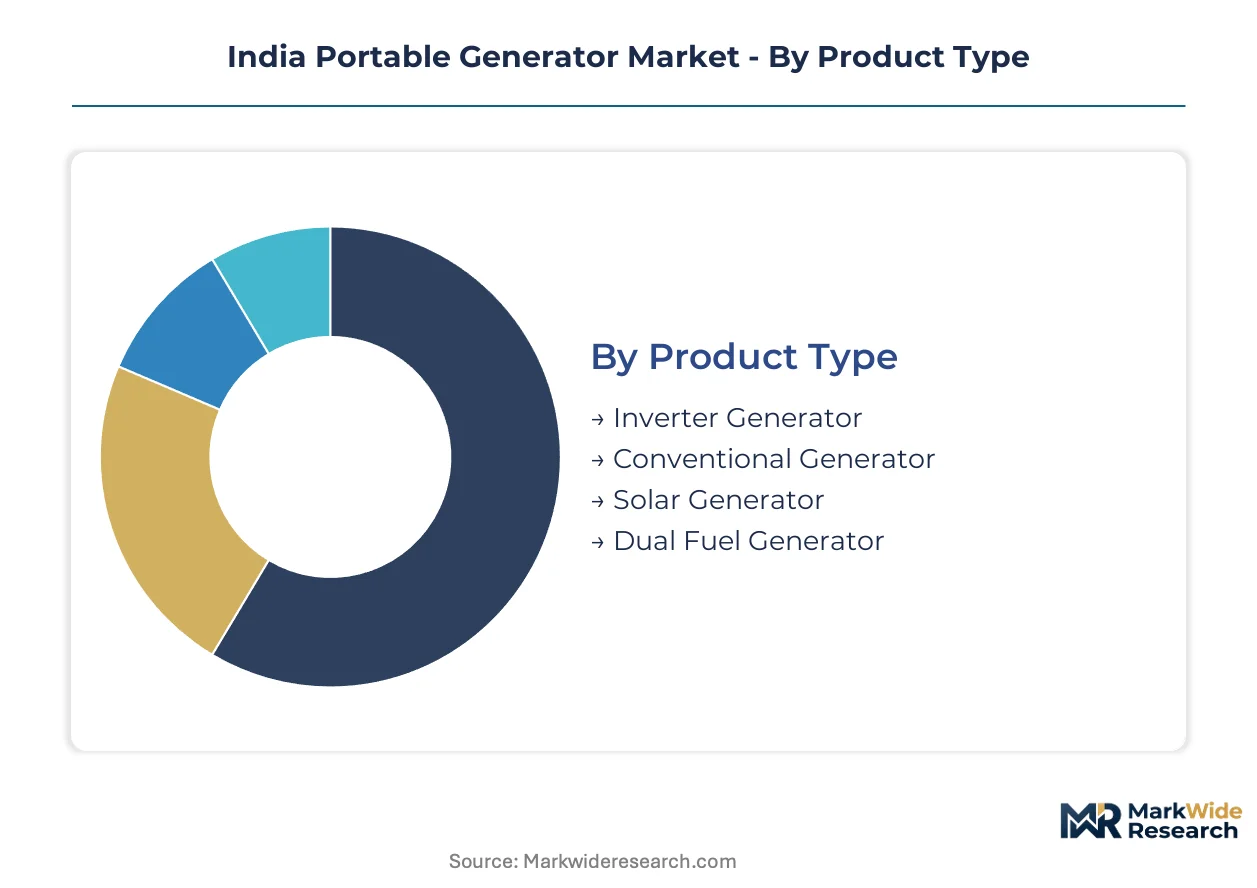
Segmentation in the India portable generator market reveals how regulatory pressure and end-use specialization fragment procurement patterns. Each dimension exposes distinct margin structures and compliance burdens that shape manufacturer positioning across state-level tenders and private fleet orders.
Product Type:
Domestic demand concentrates in conventional and inverter architectures for construction and residential backup, while solar and dual-fuel variants serve export-oriented OEM contracts and disaster-response tenders in coastal states.
- Inverter Generator:Solid-state power electronics deliver sine wave output with total harmonic distortion below 3%, protecting sensitive telecom base station equipment. Tamil Nadu and Karnataka tower operators specify these units for rural network expansion where grid quality degrades. The technology commands premium positioning among urban households with home-office power backup requirements in Bengaluru and Hyderabad.
- Conventional Generator:Electromagnetic induction systems using fixed-speed engines dominate the 5-15 kVA construction fleet segment due to lower first-cost thresholds. Maharashtra and Gujarat contractors favor these units for concrete curing and crane operations where harmonic sensitivity is minimal. Price-sensitive buyers in tier-two industrial corridors prioritize capital efficiency over fuel economy.
- Solar Generator:Photovoltaic-battery hybrid systems serve eco-sensitive commercial zones and Kerala state disaster management specifications for cyclone-prone coastal deployment.
- Dual Fuel Generator:LPG-diesel flexibility meets Odisha and Kerala state disaster authority requirements for fuel security during supply disruptions.
Conventional generators command the established base. The steepest expansion runs through inverter topology as CPCB IV+ emission mandates accelerate architecture shifts.
Fuel Type:
Cost tier stratification separates diesel's industrial dominance from gasoline's residential penetration, with propane and renewable variants occupying emerging niches driven by airshed severity classifications and state-level clean energy procurement.
- Diesel:Compression-ignition engines anchor the installed base across industrial end users due to superior thermal efficiency and torque characteristics for sustained load operation. Delhi-NCR commercial and industrial segments face the steepest CPCB IV+ compliance costs from selective catalytic reduction and particulate matter after-treatment requirements. Foundry-integrated manufacturers control cost volatility through captive engine production.
- Gasoline:Spark-ignition systems dominate the sub-5 kVA residential segment where portability and cold-start reliability outweigh fuel economy considerations. Urban households in Mumbai and Pune prioritize silent-operation engineering for apartment backup applications.
- Propane:LPG variants gain traction in eco-sensitive zones and disaster-response tenders where fuel storage safety and emission profiles outweigh energy density penalties.
- Renewable Energy:Solar-battery hybrids serve government-backed highway and railway projects where Bureau of Energy Efficiency star-labeling criteria reshape procurement evaluation.
Diesel retains volume leadership across institutional tenders. Renewable and dual-fuel alternatives are climbing the fastest as state disaster authorities and green procurement mandates expand addressable demand.
End User:
Customer type determines specification rigor, with construction and emergency services demanding ruggedized chassis and extended runtime while residential buyers prioritize acoustic attenuation and form factor miniaturization.
- Construction:Wheeled chassis gensets rated 5-15 kVA sustain uninterrupted concrete curing and material handling across Maharashtra and Gujarat infrastructure projects. Fleet operators bundle fuel, maintenance, and uptime guarantees into monthly equipment-as-a-service contracts for mid-sized contractors with irregular project pipelines.
- Residential:Silent-operation engineering and compact enclosures drive specification among urban households with home-office power backup requirements. Inverter topology penetration is deepest in Bengaluru and Hyderabad where electronics density in households is highest.
- Commercial:Small and medium enterprises in Pune, Coimbatore, and Ahmedabad deploy diesel backup for seasonal voltage fluctuation protection during peak manufacturing demand.
- Emergency Services:Kerala and Odisha state disaster management authorities specify dual-fuel and solar-battery systems for cyclone-prone coastal zone deployment with fuel flexibility requirements.
Construction anchors fleet revenue concentration. Residential inverter penetration is gaining share fastest as urban electrification quality concerns and home-office normalization persist.
Distribution Channel:
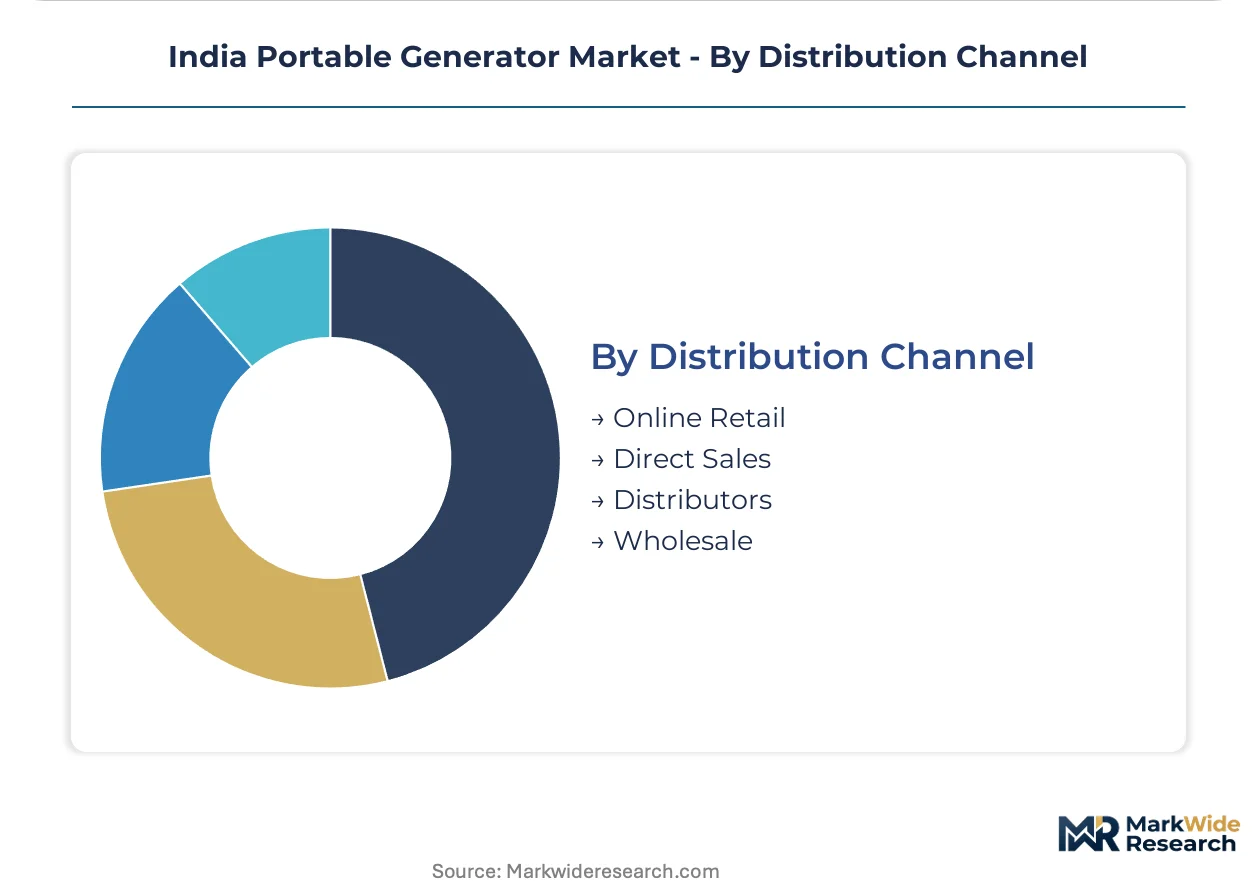
Channel selection reflects buyer sophistication and contract scale, with direct sales and distributor networks dominating institutional procurement while online retail captures residential replacement cycles.
- Distributors:Pan-India spare parts logistics and technician certification capabilities position authorized distributor networks for state electricity board tenders and commercial fleet sales. Kirloskar Oil Engines leverages over 400 district service footprints to maintain diesel-heavy commercial channel dominance.
- Direct Sales:OEM-direct relationships serve large construction contractors and telecom tower operators with customized specification, fuel bundling, and uptime guarantee integration. Mumbai and Bengaluru rental fleet operators report fastest contract penetration through direct channel engagement.
- Online Retail:E-commerce platforms capture residential replacement demand and sub-3 kVA inverter specification among price-comparison shoppers in tier-one cities.
- Wholesale:Bulk procurement aggregators serve unorganized assemblers and price-sensitive buyers in tier-three industrial corridors with limited BIS certification requirements.
Distributor networks command the established institutional base. Direct sales with bundled service contracts are expanding most quickly as equipment-as-a-service arrangements displace outright purchase in construction verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors and small-medium enterprises dominate procurement across India's industrial corridors, with state-level tender specifications and disaster-response mandates fragmenting demand patterns by geography.
Maharashtra
Infrastructure projects in Mumbai and Pune drive fleet orders for 5-15 kVA diesel units to sustain concrete curing and crane operations. The state's pollution control board enforces CPCB IV+ compliance timelines that compress margins for assemblers lacking catalytic after-treatment capabilities. Nagpur and Nashik manufacturing zones concentrate rental fleet operators bundling fuel and maintenance into equipment-as-a-service contracts.
Gujarat
Ahmedabad and Surat industrial belts experience seasonal voltage fluctuations that push SME deployment of backup power systems during peak manufacturing demand. Gujarat Pollution Control Board aligns with central BIS certification requirements under IS 4722, disqualifying unorganized producers from state electricity board tenders. Vadodara chemical processing clusters specify dual-fuel flexibility for operational continuity during fuel supply disruptions.
Karnataka
Bengaluru electronics manufacturing and telecom infrastructure demand inverter topology with sub-3% harmonic distortion for sensitive base station equipment. The state's energy department integrates Bureau of Energy Efficiency star-labeling criteria into procurement evaluation for government-backed highway projects. Mysuru and Hubli-Dharwad industrial areas show deepening penetration of silent-operation residential units among home-office households.
Tamil Nadu
Coimbatore textile and engineering clusters anchor diesel generator deployment for grid reliability during monsoon-season voltage instability. Tamil Nadu Pollution Control Board mandates adherence to CPCB IV+ particulate matter limits that force redesigns of combustion chambers and selective catalytic reduction integration. Chennai telecom tower operators specify silicon carbide power electronics for remote rural network expansion.
Kerala
State disaster management authorities in Kochi and Thiruvananthapuram procure LPG-diesel dual-fuel and solar-battery hybrid systems for cyclone-prone coastal zone deployment. Kerala State Electricity Board tenders prioritize fuel flexibility and emission profiles over energy density in emergency response specifications. Alappuzha and Kozhikode commercial zones show emerging specification of eco-sensitive variants for tourism-related infrastructure.
India Portable Generator Market Competitive Environment
Player mix skews toward foundry-integrated manufacturers and engine specialists with captive production capabilities, creating a tiered structure where service network density separates institutional tender winners from price-driven assemblers. Strategic archetypes include diesel-heavy commercial channel operators, residential inverter premium-positioned brands, and rental fleet aggregators with bundled uptime guarantees. Competitive moves center on backward integration into engine production and geographic expansion of authorized distributor footprints.
Among foundry-integrated specialists, Kirloskar Oil Engines Limited and Greaves Cotton Limited occupy positions shaped by captive manufacturing capabilities and pan-India service infrastructure. Honda India Power Products Limited represents the premium residential inverter archetype, with positioning driven by silent-operation engineering differentiation. Kohler Power India Private Limited anchors the institutional and commercial tender segment through integrated engine foundry control over cost volatility in the mid-range power band.
| Leading Market Players |
|---|
| Kohler Power India Private Limited |
| Atlas Copco (India) Limited |
| Honda India Power Products Limited |
| Sudhir Power |
| Himalayan Power Machine Manufacturing Company |
| Kirloskar Oil Engines Limited |
| Greaves Cotton Limited |
| Skyline Power Solutions Private Limited |
| Mahindra & Mahindra Limited |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day engine block lead times concentrate pricing power with foundry-integrated manufacturers while compressing margins for import-dependent assemblers across Maharashtra and Gujarat procurement corridors. This inventory banding shapes tiered cost structures where captive production capabilities anchor price stability against commodity volatility.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate fleet procurement between construction contractors and rental operators in Mumbai and Pune. Pricing stratifies across BIS-certified premium tiers, unorganized economy assemblers, and mid-tier distributors with service bundling. Cost compression in the 5-15 kVA diesel segment intensifies because CPCB IV+ after-treatment redesigns extend product development cycles. Small and medium enterprises in tier-two industrial corridors exhibit highest price sensitivity, while telecom tower operators prioritize harmonic distortion specifications over capital efficiency.
Supply Chain Analysis
Strategic stockpiling of stator windings and catalytic converter substrates prevails over just-in-time approaches as commodity volatility and BIS certification timelines stretch procurement horizons. Engine block supply concentrates in India, China, and Japan, with domestic foundry capacity limited to integrated players like Kirloskar and Greaves Cotton. The chain draws from copper winding imports, silicon carbide power electronics, and selective catalytic reduction systems. Single-source vulnerability runs through Japanese fuel injection component suppliers. Distribution runs through authorized distributor networks with pan-India spare parts logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on equipment-as-a-service bundling where rental fleet operators in Mumbai and Bengaluru integrate fuel, maintenance, and uptime guarantees into single-contract procurement. Interoperability between genset monitoring systems and state electricity board grid management platforms is reshaping competitive positioning.
For Market Incumbents: Fortify backward integration into captive engine foundries to insulate margin structures from steel and copper volatility. Deepen certification investment under BIS IS 4722 harmonization with ISO 8528 to disqualify unorganized assemblers from state tenders. Expand authorized distributor footprints into Kerala and Odisha disaster-response corridors where dual-fuel specifications are concentrating demand. For New Entrants and Emerging Players: Differentiate on silicon carbide inverter topology for telecom tower operators in Tamil Nadu and Karnataka seeking sub-3% harmonic distortion. Target residential silent-operation segments in Bengaluru and Hyderabad where home-office backup requirements outstrip supply. Pursue direct sales with bundled service contracts to bypass entrenched distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because emission mandates are accelerating architecture shifts toward inverter and dual-fuel systems. Acquisition target archetype: mid-scale manufacturers with BIS certification progress but incomplete service network density. Watch Bureau of Energy Efficiency star-labeling implementation as the inflection signal reshaping government procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic After-Treatment Integration | CPCB IV+ compliance redesigns combustion chambers and selective catalytic reduction systems for Delhi-NCR airshed severity. |
| Dual-Fuel Architecture Development | LPG-diesel flexibility meets Kerala and Odisha state disaster authority specifications for cyclone-prone coastal zones. |
| Silicon Carbide Power Electronics Adoption | Miniaturized inverter gensets with sine wave purity serve Tamil Nadu telecom tower rural network expansion. |
| Equipment-as-a-Service Contract Expansion | Mumbai and Bengaluru rental operators bundle fuel, maintenance, and uptime guarantees for mid-sized contractors. |
| Pan-India Service Network Extension | Technician certification and spare parts logistics capture state electricity board tenders beyond current 400-district footprints. |
Study Parameters
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings on CPCB IV+ implementation timelines and BIS certification barriers. Conversations with plant engineers at Pune and Coimbatore manufacturing facilities, procurement leads at Maharashtra construction contractors, aftermarket service heads at distributor networks, and regulatory affairs specialists at engine manufacturers combined with Central Pollution Control Board notifications, Bureau of Indian Standards harmonization documents, Bureau of Energy Efficiency draft star-labeling criteria, and state pollution control board enforcement calendars. Bottom-up triangulation across end-user demand segments and top-down validation against production capacity disclosures ensure consistency.
Sensitivity analysis around steel and copper price bands, CPCB IV+ compliance cost scenarios, and BIS certification timeline variations shapes the analytical framework. Segmentation dimensions modeled include product type topology, fuel type architecture, end-user application, and distribution channel structure across the projection horizon. CAGRs derive from installed base replacement cycles, fleet expansion rates in construction verticals, and inverter penetration curves in residential and telecom segments. Industry-specific inputs incorporate monsoon-season grid reliability patterns and state-level disaster management procurement schedules.
Decision-makers should treat outputs as directional under assumptions of steady CPCB IV+ enforcement progression and continued steel-copper commodity volatility; material deviation in regulatory timelines or input cost trajectories would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Industrial Generator Market
Generators
Tri Fuel Generators Market
Generators
Middle-East and Africa Diesel Generator Market
Generators
South America Portable Generator Market
Generators
Wind Power Generators Market
Generators
Home Standby Gensets Market
Generators
Asia-Pacific Portable Generator Market
Generators
Construction Generator Sets Market
Generators
North America Portable Generators Market
Generators
Multi Fuel Generators Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
South America Gas Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Asia-Pacific Gas Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
Generator Rental Market