
 Asia-Pacific Nuclear Reactor Construction Market | 2026-2036
Asia-Pacific Nuclear Reactor Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nuclear Reactor Construction Market Outlook
ASME Section III certification is reorganizing the vendor landscape for nuclear-grade pressure vessels and reactor coolant systems. China National Nuclear Corporation leverages captive forging capacity for domestic Generation III deployments. Mitsubishi Heavy Industries anchors Japan's supply chain through its role in pressurized water reactor component fabrication. Larsen & Toubro Limited sustains heavy engineering capabilities for containment structures across Indian project sites.
Asia-Pacific nuclear reactor construction encompasses the engineering, procurement, and erection of fission-based power generation facilities requiring containment vessels rated for pressures exceeding 17 MPa and neutron flux environments exceeding 10^15 n/cm²s. Pressurized Water Reactors dominate current order books due to operational familiarity among regional utilities and established supply chains for zirconium alloy fuel cladding. Small Modular Reactors represent the fastest-expanding technology segment as Indonesia and the Philippines evaluate sub-300 MWe units for island grid applications. Utility Companies constitute the primary end-user category, with procurement decisions increasingly favoring vendors offering integrated fuel-cycle services alongside reactor delivery.
China's MEE enforces environmental impact assessments for all coastal nuclear installations, while India's Atomic Energy Regulatory Board mandates site-specific seismic qualification beyond standard IAEA benchmarks. Japan's Nuclear Regulation Authority requires filtered containment venting systems as a condition for reactor restart authorization, adding retrofit scope to existing construction programs. Stakeholders must monitor how divergent national safety requirements affect component standardization and cross-border vendor qualification timelines.
Market Dynamics
China's MEE coastal siting approvals and Japan's METI restart protocols are compressing vendor qualification timelines while fragmenting component standardization across national regulatory boundaries.
Growth Catalysts
- Dual carbon targets:China's binding emissions commitments under its dual carbon goals mandate baseload nuclear expansion, forcing provincial grid operators to accelerate procurement timelines for Generation III units.
- PHWR indigenous programs:India's Department of Atomic Energy ten-unit domestic pressurized heavy water reactor buildout creates sustained demand for heavy engineering and containment fabrication capacity.
- Island grid applications:Utility procurement for sub-300 MWe Small Modular Reactors is accelerating across Indonesia and the Philippines as archipelago geographies render large baseload plants uneconomical.
Market Restraints
- Forging capacity concentration:Ultra-heavy reactor pressure vessel forging is captive to three integrated mill-forge complexes in China and Japan, creating single-source vulnerability for Asia-Pacific new builds.
- Seismic qualification divergence:India's Atomic Energy Regulatory Board mandates site-specific seismic benchmarks exceeding IAEA standards, extending design certification cycles by 18-24 months for imported reactor designs.
- Natural gas substitution:Floating LNG regasification terminals are capturing mid-merit capacity additions in Vietnam and Bangladesh, displacing planned nuclear baseload slots in national power development plans.
Strategic Opportunities
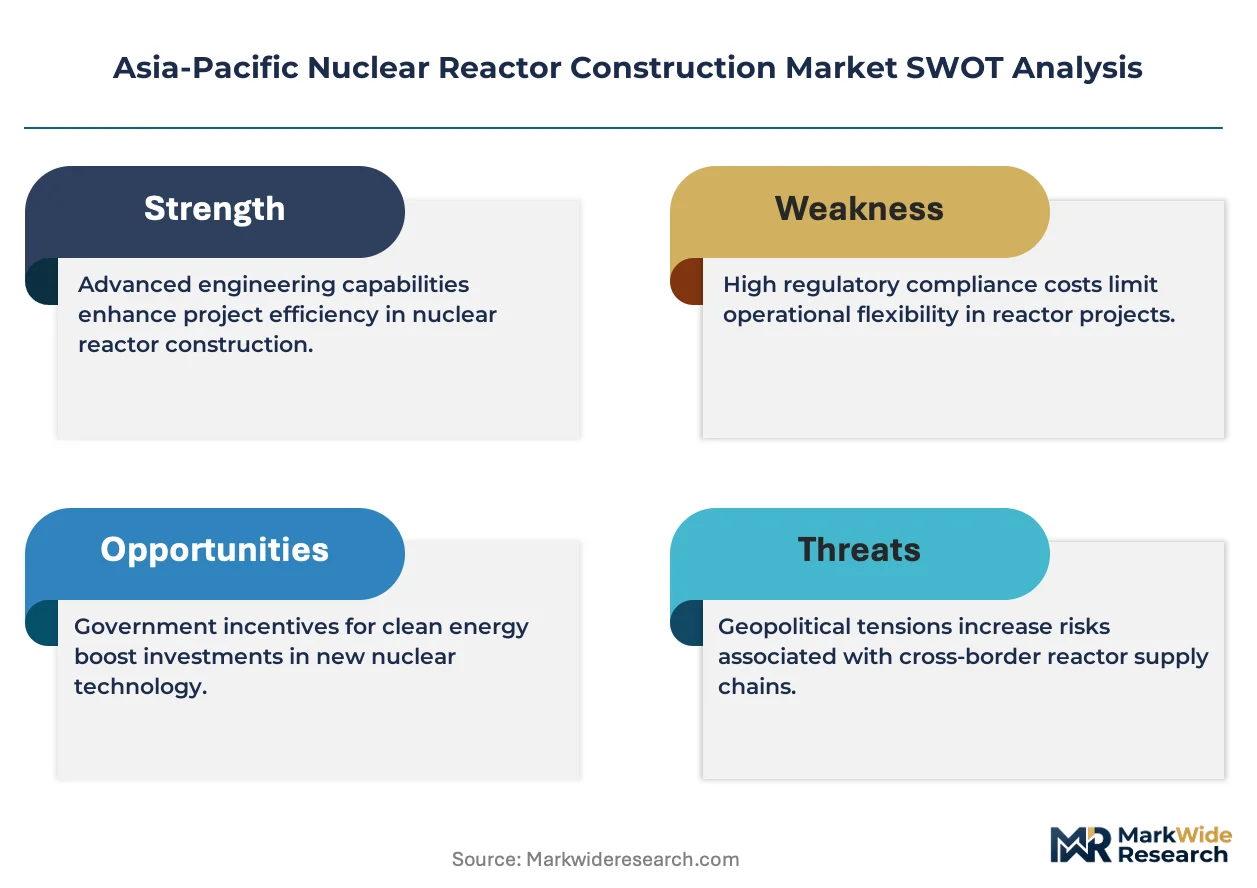
- SMR export corridors:Australia's emerging nuclear prohibition repeal debate opens potential first-mover positioning for vendor fuel-cycle bundling in previously closed Asia-Pacific markets.
- Containment venting retrofits:Japan's Nuclear Regulation Authority filtered containment venting mandate creates aftermarket scope for existing construction programs and restart authorizations.
- Zirconium alloy localization:Fuel cladding supply chain gaps in India and Southeast Asia present backward integration opportunities for reactor vendors seeking captive fuel fabrication.
Industry Challenges
- Welding certification bottlenecks:ASME Section III qualified welder scarcity extends erection timelines for reactor coolant system piping, particularly at Indian and Vietnamese greenfield sites.
- Cross-border component acceptance:Divergent national interpretations of IAEA safety standards prevent seamless redeployment of certified pressure vessels between China, Japan, and Indian project sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nuclear Reactor Construction Market |
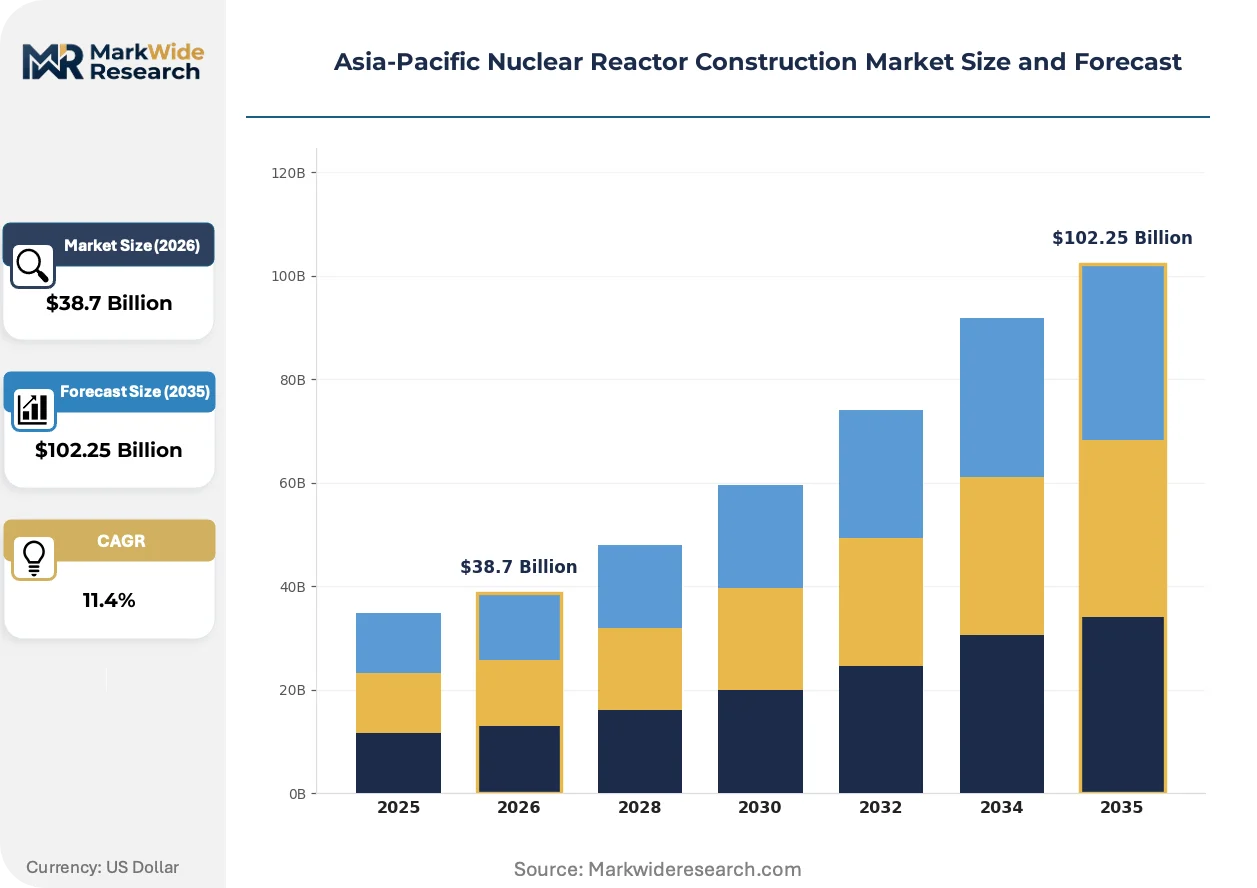
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressurized Water Reactors, Boiling Water Reactors, Heavy Water Reactors, Fast Neutron Reactors End User: Utility Companies, Government Agencies, Research Institutions, Industrial Users Technology: Advanced Passive Technology, Generation III, Generation IV, Small Modular Reactors Installation: Onshore, Offshore, Near Shore, Underground |
| Companies Covered | China National Nuclear Corporation, China General Nuclear Power Group, Rosatom State Nuclear Energy Corporation, Westinghouse Electric Company LLC, Mitsubishi Heavy Industries Ltd, Larsen & Toubro Limited, KEPCO Engineering & Construction, Shanghai Electric Group Company Limited, GE-Hitachi Nuclear Energy Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nuclear Reactor Construction Market Strategic Shifts
Reactor technology trajectories are splitting between large-scale Generation III deployments and standardized Small Modular Reactor platforms, with regulatory frameworks struggling to synchronize certification pace.
Generation III+ large light water reactor designs are bifurcating procurement strategies across Asia-Pacific utilities. State-owned grid operators in China favor domestically licensed Hualong One variants with captive forging supply. Private and mixed-ownership utilities in Southeast Asia pursue vendor-financed EPC contracts with fuel-cycle service bundling. This technology split is compressing mid-scale reactor vendor margins while elevating SMR licensing fee structures.
METI's reactor restart protocols are mandating filtered containment venting and severe accident management hardware retrofits as conditions for operational license renewal. Japanese utilities must integrate these systems into existing construction schedules or face stranded asset risk. Vessel suppliers and containment fabricators are reconfiguring shop layouts to accommodate simultaneous new-build and retrofit production streams.
Utility procurement departments are unbundling long-term fuel supply from reactor delivery contracts, reversing decades of integrated vendor offerings. State electricity boards in India and Thailand now solicit separate bids for uranium enrichment, fuel fabrication, and spent fuel management. This purchasing pattern shift is most visible in Indian PHWR tenders where the Department of Atomic Energy mandates indigenous fuel sourcing decoupled from reactor vendor selection.
Asia-Pacific Nuclear Reactor Construction Market Segmentation
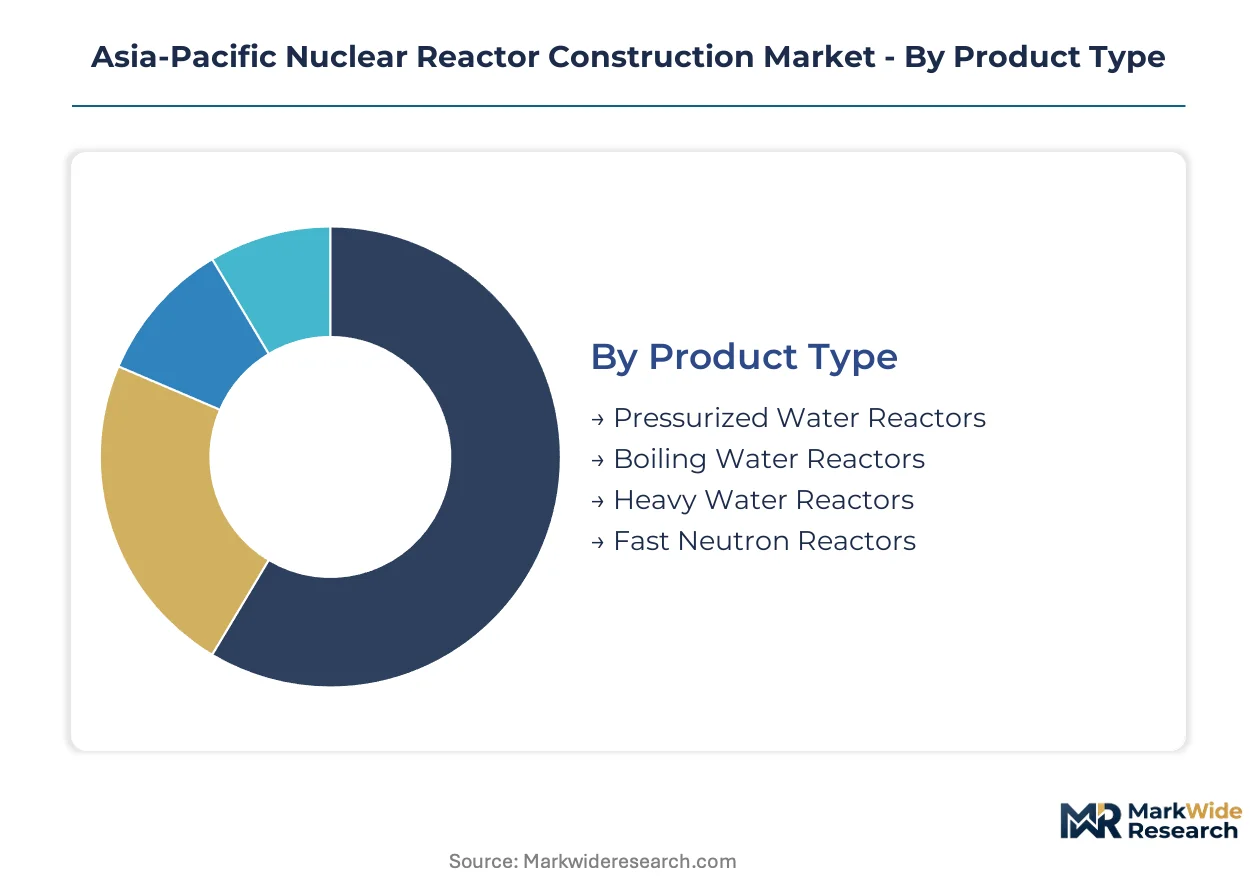
Segmentation in nuclear reactor construction reveals how regulatory frameworks, technology maturity, and siting constraints fragment procurement patterns across Asia-Pacific utilities. Each dimension carries distinct certification requirements and supply chain implications that reshape vendor qualification timelines.
Product Type:
China's MEE coastal siting rules and India's AERB seismic mandates are bifurcating reactor selection between imported light water designs and indigenous heavy water platforms.
- Pressurized Water Reactors:These systems operate at primary loop pressures exceeding 15.5 MPa with zirconium alloy fuel cladding. Demand concentrates in China's coastal provinces where State Grid procurement favors domestically licensed Generation III variants under dual carbon compliance deadlines.
- Heavy Water Reactors:PHWR designs utilize natural uranium fuel and heavy water moderator, enabling indigenous fuel cycles. India's Department of Atomic Energy ten-unit buildout anchors regional demand as New Delhi mandates technology transfer and local fabrication capacity.
- Boiling Water Reactors:Japan's METI restart protocols favor BWR retrofits for existing sites.
- Fast Neutron Reactors:Sodium-cooled designs remain experimental with limited commercial procurement.
Pressurized Water Reactors handle the majority of throughput; Heavy Water Reactors are gaining share fastest on indigenous program scale.
End User:
Procurement authority is splintering between state-owned grid operators and mixed-ownership utilities, each with divergent risk appetites for long-term capital commitments.
- Utility Companies:State electricity boards and independent power producers dominate order books. Procurement in Indonesia and the Philippines is accelerating for sub-300 MWe units as archipelago geographies render large baseload plants uneconomical.
- Government Agencies:Direct state procurement channels in China and India bypass competitive bidding for strategic energy security projects.
- Research Institutions:Limited construction scope focused on test reactors and materials qualification facilities.
- Industrial Users:Captive power applications for heavy industry remain marginal in Asia-Pacific markets.
Utility Companies absorb the dominant construction volume; Government Agencies are expanding most quickly on security-driven procurement.
Technology:
Certification pace is diverging between mature Generation III platforms and unproven Generation IV designs, with Small Modular Reactors occupying a contested middle ground.
- Generation III:Large light water reactors with passive safety systems and 60-year design life. China's Hualong One deployments and Japan's restart authorizations anchor regional demand as vendors compress construction schedules to 52 months.
- Small Modular Reactors:Standardized sub-300 MWe units with factory fabrication and transportable modules. Indonesia's PLN and the Philippines' NGCP are evaluating island grid applications where transmission infrastructure cannot support gigawatt-scale baseload.
- Advanced Passive Technology:AP1000 and EPR variants with simplified safety architecture.
- Generation IV:Sodium-cooled fast reactors and high-temperature gas designs remain pre-commercial.
Generation III commands the installed base; Small Modular Reactors show the steepest expansion trajectory on archipelago utility interest.
Installation:
Siting economics and seismic risk are pushing deployment toward hardened configurations that elevate civil works cost but reduce licensing uncertainty.
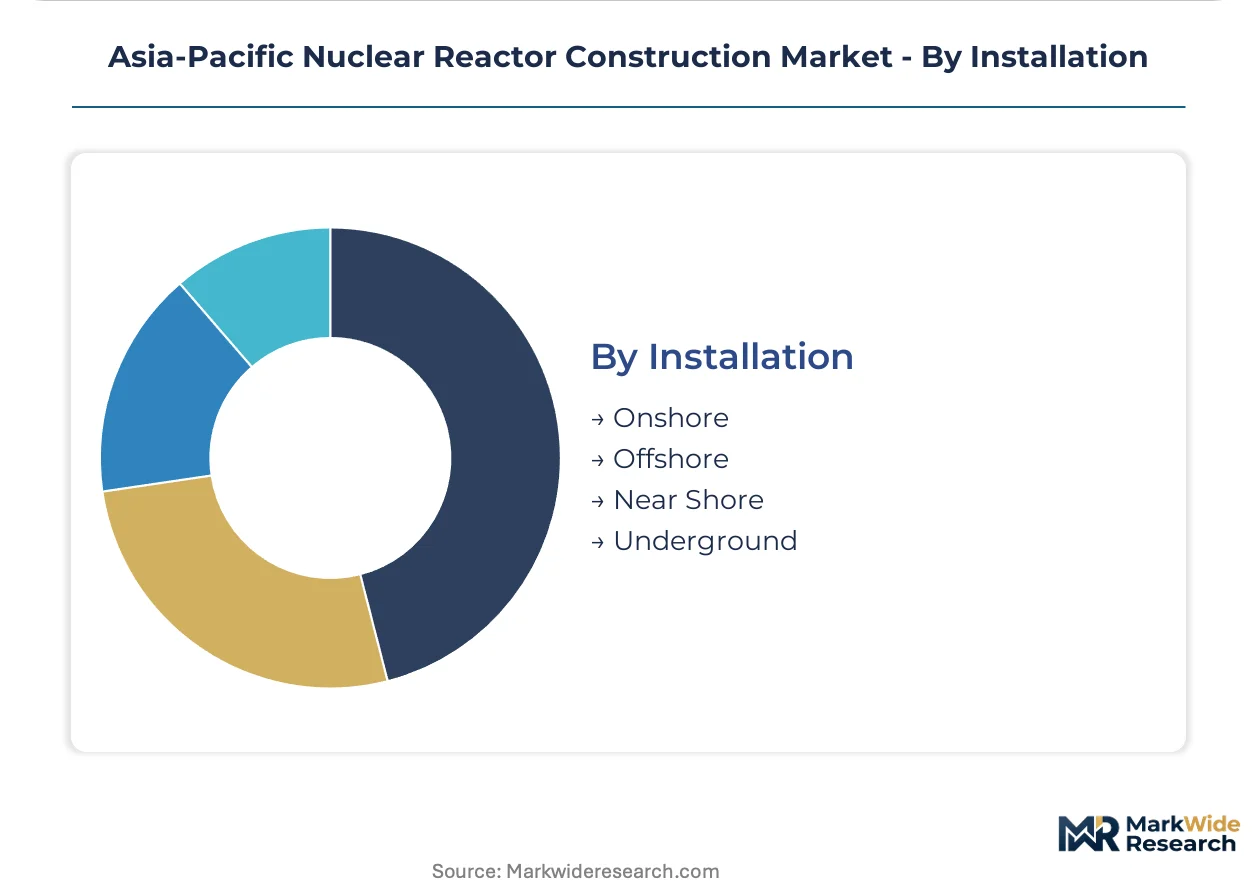
- Onshore:Conventional coastal installations with cooling tower or once-through seawater systems. China's MEE environmental impact assessments and Japan's NRA filtered venting mandates dominate regulatory scope for greenfield coastal sites.
- Underground:Rock-embedded containment structures with enhanced seismic isolation. India's AERB site-specific qualification requirements are driving consideration of hardened configurations in Himalayan foreland basins.
- Near Shore:Floating or barge-mounted units for rapid deployment.
- Offshore:Platform-based installations remain conceptual with no Asia-Pacific procurement active.
Onshore retains the construction volume lead; Underground is climbing fastest on seismic qualification stringency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and Japan's METI reactor restart protocols are compressing vendor qualification timelines across the region. India's indigenous PHWR buildout and Southeast Asia's island grid SMR evaluations are fragmenting procurement patterns. Utility procurement now spans coastal Generation III deployments, seismic-hardened Himalayan configurations, and archipelago-optimized sub-300 MWe units.
China
State Grid procurement favors domestically licensed Hualong One variants for coastal provinces under MEE environmental impact assessment rules. The dual carbon mandate forces provincial operators to accelerate Generation III timelines. Shanghai Electric Group anchors component fabrication in the Yangtze River Delta, with forging capacity concentrated at captive mill-forge complexes serving domestic deployment schedules.
Japan
METI restart protocols mandate filtered containment venting retrofits for BWR license renewals, extending construction scope at existing sites. The Nuclear Regulation Authority's severe accident management hardware requirements are reconfiguring vendor shop layouts. Mitsubishi Heavy Industries sustains pressurized water reactor component fabrication in the Chubu region, balancing new-build and retrofit production streams.
India
The Department of Atomic Energy's ten-unit indigenous PHWR program creates sustained demand for heavy engineering and containment fabrication. AERB site-specific seismic qualification exceeds IAEA benchmarks, extending design certification cycles for imported designs. Larsen & Toubro Limited sustains containment structure capabilities across project sites in Gujarat and Tamil Nadu, with localization mandates driving domestic fabrication.
South Korea
KEPCO Engineering & Construction leverages APR1400 design maturity for regional export positioning, though domestic new-build momentum has slowed. The country's nuclear regulator maintains stringent containment performance standards that vendors reference for third-market qualification. Heavy component forging clusters in the southeast industrial belt support reactor pressure vessel supply for overseas contracts.
Indonesia
PLN evaluation of sub-300 MWe SMR units for island grid applications is accelerating procurement timelines for archipelago-optimized designs. The country's national energy regulator is developing site-specific licensing frameworks for non-coastal nuclear installations. Utility procurement teams in Java and Sumatra are assessing vendor fuel-cycle bundling options alongside reactor delivery contracts.
Asia-Pacific Nuclear Reactor Construction Market Competitive Environment
Player mix skews toward state-owned integrated energy corporations with captive forging and heavy engineering capabilities. The vendor base concentrates around three strategic archetypes: domestic champions with licensed Generation III designs, global reactor vendors with fuel-cycle service portfolios, and heavy engineering specialists with ASME Section III certification. Competitive positioning hinges on technology licensing partnerships and backward integration into zirconium alloy fuel cladding supply.
Among Asia-Pacific state-owned enterprises, China National Nuclear Corporation and China General Nuclear Power Group exemplify the domestic champion archetype with captive supply chain control. Mitsubishi Heavy Industries occupies a position within the heavy engineering specialist tier, while Westinghouse Electric Company LLC represents global vendor positioning with integrated fuel-cycle offerings. These three anchors illustrate how regulatory alignment with national nuclear programs determines competitive viability across divergent certification regimes.
| Leading Market Players |
|---|
| China National Nuclear Corporation |
| China General Nuclear Power Group |
| Rosatom State Nuclear Energy Corporation |
| Westinghouse Electric Company LLC |
| Mitsubishi Heavy Industries Ltd |
| Larsen & Toubro Limited |
| KEPCO Engineering & Construction |
| Shanghai Electric Group Company Limited |
| GE-Hitachi Nuclear Energy Inc. |
| Others |
Value Chain & Pricing Dynamics
Reactor pressure vessel lead times stretching beyond 36 months for non-captive buyers concentrate pricing power with integrated mill-forge complexes in China and Japan, while procurement officers at Southeast Asian utilities face compressed vendor qualification timelines that erode negotiation leverage on Generation III EPC contracts.
Pricing Analysis
ASME Section III certification grade creates the primary spread between premium and standard vendor tiers. Project-based EPC contracting dominates, with price differentiation resting on captive forging capacity and fuel-cycle service bundling. Cost compression in containment fabrication is intensifying because India's AERB mandates site-specific seismic qualification beyond IAEA benchmarks. State-owned grid operators in China exhibit lowest price sensitivity; private utilities in Indonesia and the Philippines face acute budget constraints on island grid SMR deployments.
Supply Chain Analysis
Strategic stockpiling of zirconium alloy ingots and heavy forgings prevails over just-in-time approaches given single-source vulnerability at three integrated mill-forge complexes in China, Japan, and South Korea. Raw material dependencies center on high-purity steel ingots, zirconium sponge, and boron carbide absorbers. Tariff exposure on specialty alloy imports from Japan disrupts cross-border component acceptance. Distribution runs through state-owned EPC contractors with captive heavy engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating LNG regasification terminals are capturing mid-merit capacity additions across Vietnam and Bangladesh, forcing nuclear reactor vendors to defend baseload positioning through integrated fuel-cycle bundling and accelerated SMR certification timelines.
For Market Incumbents: Compound forging capacity advantages by securing long-term offtake agreements with India's Department of Atomic Energy PHWR program before indigenous heavy engineering scale-up matures. Lock in containment venting retrofit scope at Japanese BWR sites under METI restart protocols to offset margin pressure from vendor-financed EPC structures in Southeast Asia. For New Entrants and Emerging Players: ASME Section III certification fast-tracks for SMR pressure vessel modules open white-space positioning in Indonesia's archipelago utility procurement, where PLN evaluation timelines favor vendors with pre-qualified transportable reactor designs. Target Philippine NGCP island grid applications with sub-300 MWe units bundled with spent fuel management services. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Generation III+ deployments as seismic qualification stringency extends design certification cycles. Acquisition targets should exhibit captive zirconium alloy fabrication or backward integration into heavy forging supply. Watch for AERB approval velocity on imported light water designs as inflection indicator for Indian market accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel-Cycle Service Bundling | Integrated uranium enrichment and spent fuel management contracts differentiate vendor offerings for Southeast Asian utilities. |
| SMR Certification Investment | Pre-licensed sub-300 MWe designs accelerate PLN procurement timelines for Indonesian island grid applications. |
| Containment Venting Retrofit | Filtered venting system integration captures aftermarket scope under Japan's NRA restart authorization requirements. |
| Seismic Qualification Investment | Site-specific engineering capabilities enable AERB compliance for Himalayan foreland basin deployments in India. |
| Heavy Forging Capacity Expansion | Captive mill-forge complexes at China National Nuclear Corporation reduce single-source vulnerability for Asia-Pacific new builds. |
Study Parameters
The analysis maps Generation III deployments, Small Modular Reactor platforms, PHWR indigenous programs, and containment venting retrofits, each validated through utility procurement officers, EPC project directors, nuclear regulatory affairs leads, and heavy engineering fabrication managers. Primary interview findings triangulate against IAEA safety standards documentation, national regulatory filings with China's MEE and India's AERB, reactor technology licensing databases, and utility capital expenditure disclosures. Bottom-up project pipeline aggregation reconciles with top-down national energy plan targets.
Consistency checks validate volume and value outputs against external benchmarks including IEA nuclear capacity projections and national power development plan revisions. The analytical framework segments by reactor technology type, end-user procurement authority, installation configuration, and regulatory jurisdiction across the projection horizon. CAGRs derive from unit-level construction cost trajectories and deployment schedule probability weighting. Forecast inputs incorporate forging capacity utilization rates and seismic qualification timeline distributions.
Decision-makers should treat outputs as directional under base assumptions of sustained dual carbon policy enforcement in China and METI restart protocol continuity; material deviation in national nuclear phase-out decisions would warrant model refresh. Revision becomes warranted when floating LNG terminal deployment crosses thresholds that displace planned nuclear baseload slots in Vietnam or Bangladesh national power development plans.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Nuclear Fuels Market