
 Europe Gas Generator Market | 2026-2036
Europe Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gas Generator Market Foresight
The EU Green Deal is recalibrating the cost-of-entry calculus for gas generator manufacturers serving Europe. MTU Onsite Energy Corp leverages its captive engine manufacturing to sustain margin control across the 1-5 kW to above 20 kW range. Caterpillar Inc anchors its position through deep channel density in German and French industrial corridors. INNIO Jenbacher GmbH & Co OG specializes in biogas-adapted architectures, differentiating where landfill and agricultural methane recovery expands.
A gas generator converts chemical energy from gaseous fuels into electrical output through internal combustion or turbine-driven alternator sets, typically achieving 25-45% thermal efficiency in distributed applications and serving as prime or emergency power for facilities requiring uninterrupted electricity. Standby generators occupy the largest revenue pool across Europe given mandatory backup requirements for hospitals, data centers, and financial infrastructure, while biogas generators represent the fastest-expanding fuel category as anaerobic digestion capacity scales in Denmark and the Netherlands. Industrial generators above 20 kW concentrate margin where combined heat and power integration raises utilization rates above 4,000 annual operating hours.
EMA guidelines on stationary engine emissions, REACH compliance for lubricants and coolants, and the EU F-Gas Regulation on fluorinated greenhouse gases collectively shape product design cycles and aftermarket service obligations across European member states. ECHA substance restrictions limit certain catalyst coatings, forcing reformulation of exhaust aftertreatment systems. Stakeholders must monitor how the EU AI Act and evolving grid interconnection standards redefine remote monitoring and predictive maintenance architectures for distributed generation assets.
Market Dynamics
The EU F-Gas Regulation is compressing product design cycles as manufacturers reformulate exhaust aftertreatment systems ahead of 2027 phase-down mandates for fluorinated greenhouse gases used in catalyst coatings and cooling circuits.
Growth Catalysts
- Data center construction:Hyperscale facilities in Frankfurt and Amsterdam are mandating on-site gas-fired backup capacity exceeding 20 MW per site to satisfy grid interconnection reliability clauses.
- REACH compliance innovation:Reformed lubricant formulations are extending service intervals for biogas-adapted engines, reducing total cost of ownership for agricultural methane recovery installations.
- EMA emission benchmarks:Tightening nitrogen oxide limits for stationary engines are accelerating replacement demand in German industrial clusters where legacy diesel units face operational restrictions.
Market Restraints
- Natural gas price volatility:Input cost swings linked to LNG import dependence are compressing project IRRs for combined heat and power investments in Poland and Italy.
- Catalyst supply concentration:Rare earth processing for exhaust aftertreatment systems concentrates in a limited supplier base, creating procurement bottlenecks for European engine assemblers.
- Battery substitution:Lithium-ion storage paired with renewable generation is displacing peaking gas capacity in shorter-duration backup applications below four-hour runtime requirements.
Strategic Opportunities
- Hydrogen blending readiness:Engine architectures capable of 25% hydrogen co-firing are capturing early-mover premiums from Dutch chemical plants preparing for grid-connected green hydrogen supply.
- Biogas feedstock expansion:Anaerobic digestion capacity buildouts in Denmark offer captive fuel supply chains for distributed generation assets serving agricultural processing cooperatives.
- EU Green Deal financing:Recovery and Resilience Facility disbursements are subsidizing CHP retrofits in Spanish and Portuguese food manufacturing facilities seeking carbon intensity reductions.
Industry Challenges
- Aftertreatment calibration expertise:Scarce technician pools familiar with selective catalytic reduction tuning are extending commissioning timelines for hospital and healthcare installations.
- Legacy control system integration:Proprietary SCADA protocols in existing building management systems demand costly middleware development for remote monitoring compliance under evolving grid codes.
- ECHA substance notification:Extended REACH registration timelines for reformulated coolant chemistries are delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gas Generator Market |
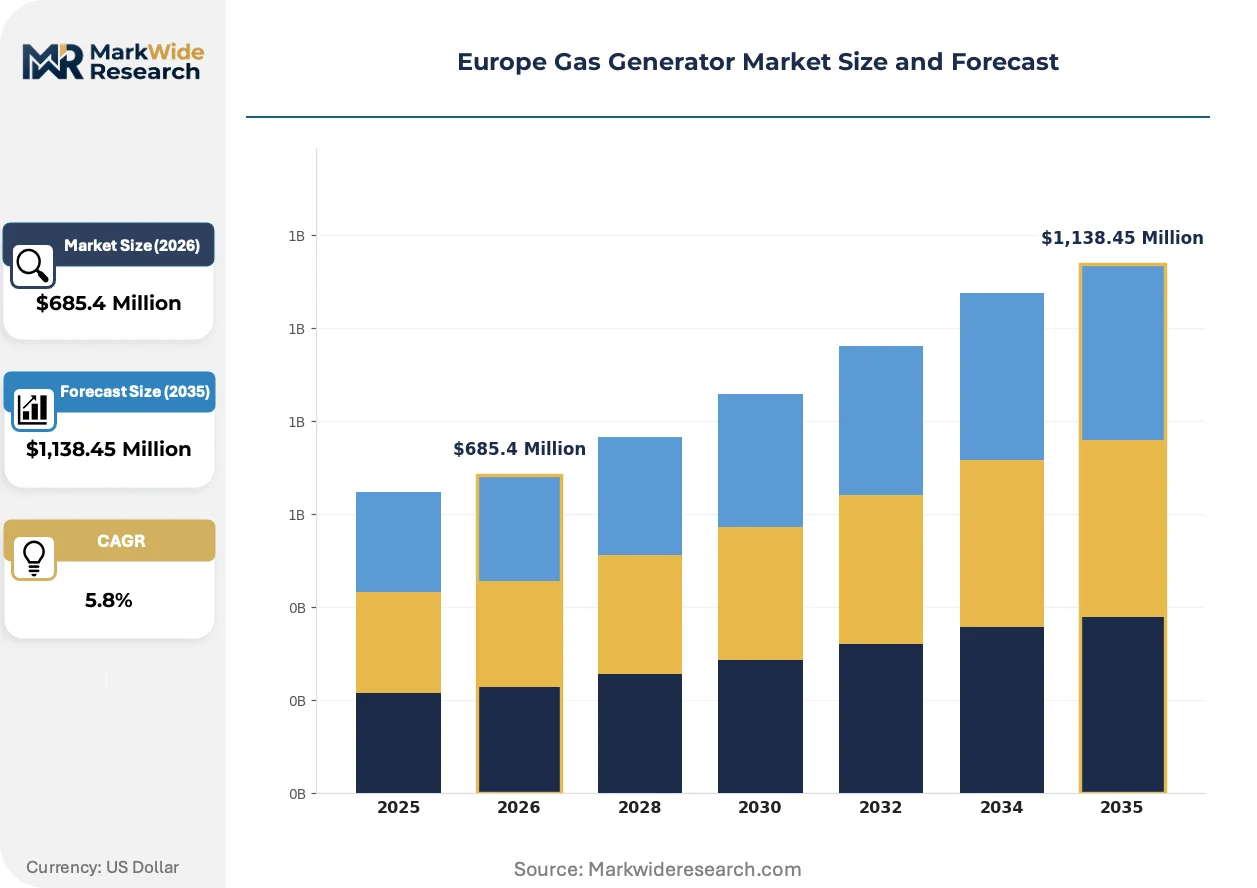
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Inverter Generators, Industrial Generators Power Rating: 1-5 kW, 6-10 kW, 11-20 kW, Above 20 kW Fuel Type: Natural Gas, Propane, Biogas, Others End User: Residential, Commercial, Industrial, Emergency Services |
| Companies Covered | MTU Onsite Energy Corp, FG Wilson Power Equipment Co Ltd, Caterpillar Inc, Genesal Energy, Aggreko plc, Cummins Inc, Himoinsa SL, INNIO Jenbacher GmbH & Co OG, Generac Holdings Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gas Generator Market Shifts & Advancements
Digital twin architectures and synthetic fuel compatibility are redefining generator system value propositions as asset operators prioritize predictive uptime over rated capacity specifications.
Modular containerized generator sets with integrated heat recovery are electrifying deployment economics for district heating networks in Scandinavian municipalities. Finnish and Swedish energy utilities are specifying these configurations for 4,000+ annual operating hour regimes. The technology is compressing payback periods for urban CHP investments below six years in high heat-density zones.
The EU AI Act's risk classification framework for critical infrastructure is mandating algorithmic audit trails for predictive maintenance software deployed on hospital backup systems. Engine OEMs must now document training data provenance and decision transparency for remote diagnostic tools. German healthcare procurement boards are requiring CE-marked AI compliance documentation prior to contract award.
Power purchase agreement structures are displacing traditional equipment ownership models for industrial cogeneration assets. Dutch greenhouse operators and Belgian brewing facilities are contracting energy-as-a-service providers who retain generator ownership and assume fuel price risk. This shift concentrates balance sheet exposure with specialized fleet operators while transferring operational complexity away from agricultural and food processing end-users.
Europe Gas Generator Market Segmentation
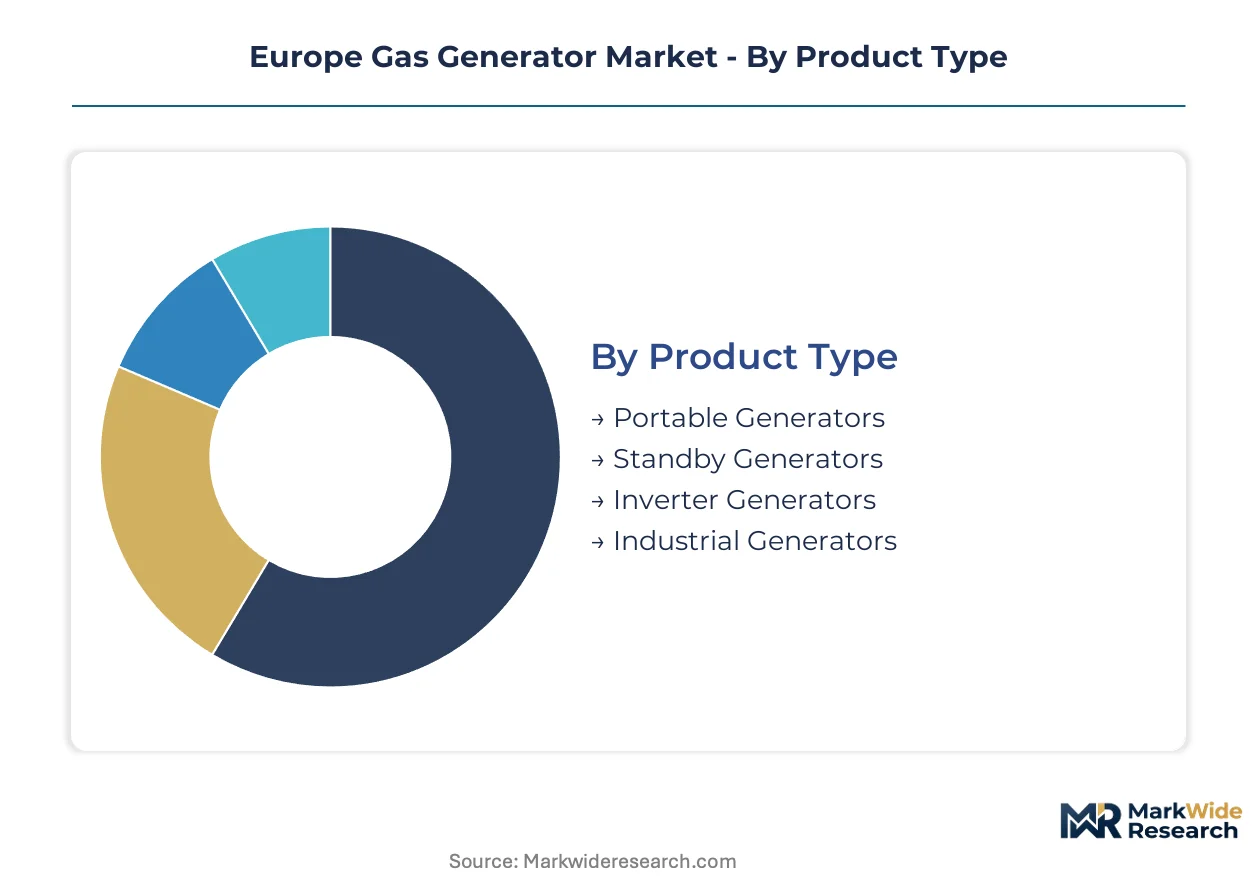
Segmentation in the Europe Gas Generator Market reveals how supply chain concentration, regulatory pressure, and end-use specialization create distinct competitive arenas. Manufacturers configure product portfolios around power rating thresholds and fuel adaptability to capture margin pools in German industrial corridors and Dutch biogas zones.
Product Type:
Supply concentration for engine blocks and alternator sets tilts competitive advantage toward manufacturers with captive manufacturing or deep component sourcing partnerships.
- Portable Generators:Compact units below 10 kW serve construction sites and outdoor events across Spain and Italy. Rental fleet operators in France prioritize weight reduction and rapid deployment features for seasonal demand spikes.
- Standby Generators:Automatic transfer switch integration defines this segment, with hospitals in Germany and data centers in the Netherlands mandating sub-10-second startup compliance. EMA emission benchmarks and EU F-Gas Regulation compliance add certification complexity that favors established suppliers with dedicated regulatory teams.
- Inverter Generators:Power electronics integration enables variable-speed operation for sensitive equipment in research laboratories and broadcasting facilities. Danish and Swedish buyers specify harmonic distortion below 3% for precision manufacturing environments.
- Industrial Generators:Heavy-frame units above 500 kW dominate combined heat and power installations in Polish and Czech manufacturing clusters. Extended service contracts and predictive maintenance integration separate premium suppliers from commodity assemblers.
Standby generators absorb the bulk of installed capacity; inverter generators are expanding most quickly.
Power Rating:
Cost tier stratification aligns with application criticality, where higher ratings command proportionally greater service revenue attachment.
- 1-5 kW:Single-phase output suits residential backup and small retail premises in rural France and northern Italy. Noise enclosure requirements under municipal ordinances in German suburbs drive specification premiums.
- 6-10 kW:Three-phase capability enters at this threshold, serving small commercial kitchens and veterinary clinics across Belgium and Austria. Grid interconnection standards in the Netherlands mandate specific synchronization protection for export-rated units.
- 11-20 kW:Mid-scale commercial applications including boutique hotels and regional bank branches concentrate demand in Portuguese and Greek tourist corridors. Fuel flexibility between natural gas and propane addresses infrastructure gaps in island territories.
- Above 20 kW:Industrial prime power and large standby installations in Frankfurt data centers and Rotterdam port facilities define this segment. Combined heat and power integration raises annual operating hours above 4,000, compressing payback periods for efficiency-optimized configurations.
Above 20 kW systems capture the greatest service revenue intensity; 6-10 kW units are climbing the fastest as commercial backup mandates broaden.
Fuel Type:
Application suitability and infrastructure availability determine fuel selection, with regulatory preference increasingly favoring renewable-derived alternatives.
- Natural Gas:Pipeline distribution density in Germany, the Netherlands, and the UK underpins dominant market presence. Grid reliability concerns at Frankfurt and Amsterdam data centers sustain procurement of multi-megawatt gas-fired backup capacity.
- Propane:Tank-stored fuel serves off-grid commercial and agricultural operations across Spain, Italy, and rural France where pipeline extension is uneconomical. Seasonal heating load correlation in Alpine regions creates demand concentration for dual-fuel capable units.
- Biogas:Anaerobic digestion infrastructure in Denmark and the Netherlands supplies captive fuel for agricultural processing and district heating applications. REACH-compliant lubricant formulations extend service intervals, improving total cost of ownership for methane recovery installations.
- Others:Hydrogen blending trials and synthetic methane pilots in Dutch chemical corridors represent emerging demand. Engine architectures capable of 25% hydrogen co-firing capture early-mover premiums from facilities preparing for grid-connected green hydrogen supply.
Natural gas retains the largest installed base; biogas is gaining share fastest on EU Green Deal financing and agricultural methane recovery expansion.
End User:
Customer type segmentation exposes diverging procurement sophistication, from price-sensitive residential buyers to industrial purchasers prioritizing lifecycle cost and regulatory compliance.
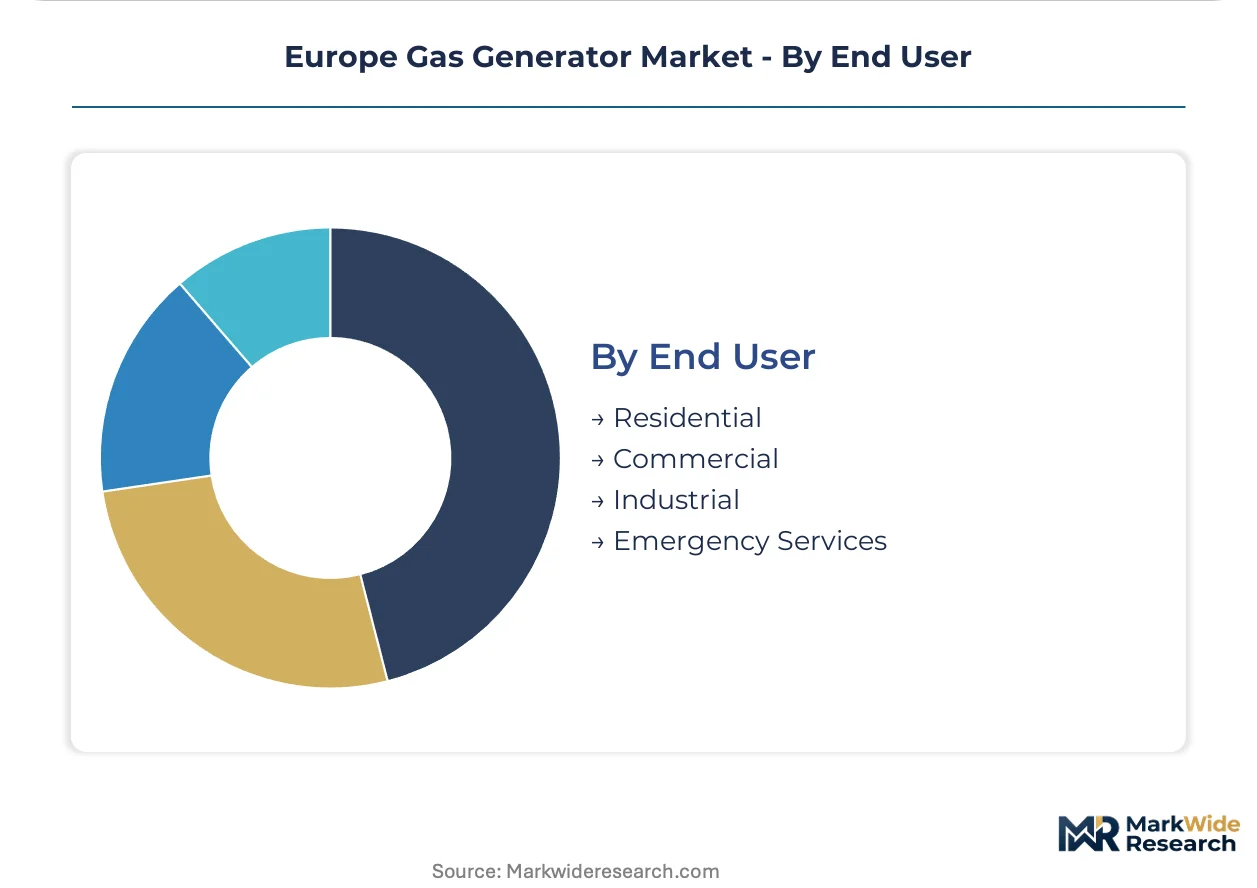
- Residential:Single-family homes and small multi-unit buildings in storm-prone coastal zones of France and Italy drive standby installation. Grid instability in rural eastern Germany has accelerated generator adoption alongside solar-battery hybrid systems.
- Commercial:Retail chains, hospitality groups, and office landlords across the UK and Benelux specify automatic backup for revenue protection. Insurance underwriters increasingly mandate on-site generation for business continuity certification.
- Industrial:Continuous process manufacturers in German chemical clusters and food processing cooperatives in Denmark deploy prime power and CHP configurations. Power purchase agreement structures are displacing equipment ownership, concentrating balance sheet exposure with specialized fleet operators.
- Emergency Services:Hospitals, fire stations, and telecommunications hubs face mandatory backup requirements under national safety codes. The EU AI Act's risk classification framework mandates algorithmic audit trails for predictive maintenance software deployed on hospital backup systems.
Industrial end users command the highest average transaction values; emergency services are expanding most quickly on healthcare infrastructure investment and regulatory mandate tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Rhine-Main's data center tax incentives concentrate multi-megawatt gas generator procurement in German industrial corridors. The EU Green Deal's Recovery and Resilience Facility channels capital toward combined heat and power retrofits across member states with high manufacturing density.
Germany
Chemical clusters in North Rhine-Westphalia and automotive manufacturing in Bavaria sustain demand for above-500 kW prime power installations. The Federal Immission Control Act tightens nitrogen oxide thresholds for stationary engines, accelerating replacement cycles for legacy diesel units. Frankfurt's hyperscale data centers mandate on-site gas-fired backup exceeding 20 MW per facility under grid interconnection reliability clauses.
Netherlands
Rotterdam port logistics and Amsterdam data center construction drive procurement of containerized CHP systems. The National Climate Agreement subsidizes biogas generator deployment for agricultural methane recovery. Greenhouse operators in Westland cluster contract energy-as-a-service providers who assume generator ownership and fuel price risk.
Denmark
Anaerobic digestion infrastructure expansion supplies captive biogas fuel for agricultural processing cooperatives. The Danish Energy Agency mandates renewable gas integration targets for district heating networks. Aarhus and Odense municipalities specify modular containerized sets with integrated heat recovery for 4,000+ annual operating hour regimes.
France
Nuclear grid intermittency concerns accelerate hospital and healthcare backup procurement in Île-de-France and Provence-Alpes-Côte d'Azur. The French Environment Code transposes EU F-Gas Regulation phase-down mandates for fluorinated greenhouse gases in cooling circuits. Lyon and Marseille industrial zones deploy hydrogen-blending-ready architectures for chemical process heat applications.
United Kingdom
London financial infrastructure and Scottish distillery operations require sub-10-second automatic transfer switch compliance. The Environment Agency enforces Medium Combustion Plant Directive emission limits for stationary gas engines. Manchester and Birmingham manufacturing corridors favor power purchase agreement structures over equipment ownership for cogeneration assets.
Europe Gas Generator Market Competitive Landscape
German producers anchor one tier; Austrian and British specialists hold differentiated positions in biogas-adapted and rental fleet segments. The market exhibits moderate consolidation with three to five integrated engine manufacturers commanding premium pricing on above-20 kW industrial configurations. Strategic archetypes include captive engine manufacturers with in-house block production, rental fleet operators with rapid-deployment logistics, and biogas specialists with anaerobic digestion integration expertise. Competitive moves concentrate on hydrogen blending certification and predictive maintenance software compliance with EU AI Act risk classification frameworks.
Within the captive manufacturing tier, MTU Onsite Energy Corp and INNIO Jenbacher GmbH & Co OG represent vertically integrated engine producers with margin control across power rating ranges. Caterpillar Inc anchors channel density positions in German and French industrial corridors through established distribution partnerships. These three companies exemplify how regulatory compliance capabilities and service network reach determine contract award outcomes in hospital and data center procurement processes.
| Leading Market Players |
|---|
| MTU Onsite Energy Corp |
| FG Wilson Power Equipment Co Ltd |
| Caterpillar Inc |
| Genesal Energy |
| Aggreko plc |
| Cummins Inc |
| Himoinsa SL |
| INNIO Jenbacher GmbH & Co OG |
| Generac Holdings Inc |
| Others |
Supply & Pricing Matrix
Scarce selective catalytic reduction calibration expertise in German industrial corridors widens pricing-tier spreads between premium service-bundled installations and commodity hardware-only transactions. Labor-cost differentials between certified technician pools in Bavaria and emerging service centers in Eastern Europe compress margins on mid-tier configurations while sustaining premiums for EMA-compliant turnkey packages.
Pricing Analysis
Short lead-time premiums of 15-25% apply to standby generator configurations for Frankfurt data centers facing grid interconnection deadlines, while spot inventory of containerized CHP units trades at discounts in Scandinavian municipal procurement. Three-tier pricing structure across premium, standard, and economy levels separates EMA-certified hospital installations from commercial backup units and portable construction-site rentals. Cost compression in the 6-10 kW commercial segment intensifies because battery substitution erodes four-hour backup applications. Industrial buyers above 500 kW exhibit lowest price sensitivity due to lifecycle cost focus, whereas residential and small commercial purchasers prioritize upfront capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg orchestrate hub-and-spoke patterns for engine block and alternator set logistics across German, Dutch, and French industrial corridors. Manufacturing concentrates in Germany, Austria, and the United Kingdom for precision engine components, while rare earth processing for exhaust aftertreatment catalysts draws from concentrated supplier bases outside Europe. Single-source vulnerability around selective catalytic reduction substrates creates procurement bottlenecks during EMA compliance transition periods. Distribution runs through authorized dealer networks with captive service capabilities rather than pure equipment wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance costs are forcing consolidation as smaller assemblers lack capital to reformulate exhaust aftertreatment systems ahead of 2027 mandates.
For Market Incumbents: To counter battery substitution in sub-four-hour backup applications, deepen backward integration into power electronics and thermal management subsystems. Capture margin expansion through predictive maintenance software architectures that satisfy EU AI Act algorithmic audit requirements for hospital infrastructure contracts. For New Entrants and Emerging Players: Enter via biogas-adapted engine configurations for Danish agricultural cooperatives and Dutch greenhouse clusters where captive fuel supply chains reduce customer switching costs. Target anaerobic digestion integration partnerships as the most penetrable white-space, leveraging energy-as-a-service contract structures to assume balance sheet exposure from food processing end-users. For Investors and Strategic Acquirers: Re-rating potential sits with hydrogen-blending-ready engine specialists given Dutch chemical corridor demand for 25% co-firing architectures. Long-term viability over the next decade favors manufacturers with in-house block production and established EMA certification pathways. Monitor green hydrogen grid connection timelines as the critical inflection signal for stranded asset risk in pure natural gas configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Blending Certification | Dutch chemical plants demand 25% co-firing readiness for grid-connected green hydrogen supply. |
| Predictive Maintenance Software Development | EU AI Act mandates algorithmic audit trails for hospital backup system diagnostics. |
| Biogas Engine Architecture Specialization | Denmark's anaerobic digestion expansion creates captive fuel supply for agricultural cooperatives. |
| Energy-as-a-Service Model Deployment | Dutch greenhouse operators transfer operational complexity to specialized fleet operators. |
| EMA Emission Compliance Investment | German Federal Immission Control Act accelerates replacement cycles for legacy diesel units. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Gas Generator Market analysis. Primary interviews with plant engineers at German chemical clusters, aftermarket service heads at Dutch data center operators, EPC contractors specializing in CHP installations, and procurement leads at Scandinavian district heating utilities combined with ECHA substance restriction databases, EMA emission benchmark documentation, and EU Recovery and Resilience Facility disbursement records. Bottom-up unit economics triangulated against top-down sector expenditure estimates.
Granularity-level modeling addressed power rating tiers, fuel type adaptability, end-user procurement sophistication, and national regulatory framework variations across the projection horizon. CAGRs derived from segment-level volume build-ups and value-per-unit trajectories. Forecast inputs incorporated anaerobic digestion capacity buildout schedules, hydrogen grid injection timelines, and data center construction permitting velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas price volatility and rare earth supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Power Generator for Military Market
Generators
South America Portable Generator Market
Generators
Construction Portable Generators Market
Generators
Electric Generators Market
Generators
Kuwait Diesel Gensets Market
Generators
Power Generator Rental Market
Generators
South America and Africa Diesel Generator Market
Generators
Multi Fuel Generators Market
Generators
Europe Gas Turbine Market
Generators
Nuclear Turbine Generators Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Europe Portable Generator Market
Generators
Gasoline Generator Market
Generators
China Generator Sets Market
Generators
Onboard Marine Gensets Market
Generators
Containerized Solar Generators Market