
 Industrial Generator Market | 2026-2036
Industrial Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Generator Market Analysis
Modular power blocks paired with containerized enclosures is restructuring how industrial buyers evaluate total cost of ownership against fixed installations. Caterpillar leverages its integrated controls architecture to anchor large-scale mining and utility contracts across multiple continents. Cummins sustains engineering intensity in dual-fuel platforms that compete in markets with volatile diesel pricing. Wärtsilä differentiates through flexible gas engine configurations that dominate distributed generation deployments in Europe and Asia.
An industrial generator is a stationary or mobile engine-alternator set rated typically from 10 kW to multiple megawatts, converting mechanical energy into electrical power through electromagnetic induction for continuous, prime, or emergency industrial supply. Diesel generators retain the largest installed base due to fuel energy density and established service networks, though gas generators are gaining share where pipeline infrastructure exists and emissions restrictions harden. Smart grid technology represents the fastest-expanding segment as remote monitoring and automated load management reduce downtime costs for manufacturing and events end users.
EPA stationary engine standards in the United States, EU F-Gas Regulation for fluorinated greenhouse gases, and India's CEA grid connectivity norms collectively shape product certification requirements and fuel technology roadmaps across major supply regions. Compliance timelines in Europe and North America are forcing accelerated R&D spending on exhaust aftertreatment and alternative fuel compatibility. Stakeholders must weigh captive power economics against evolving carbon pricing mechanisms when sizing fleet investments for the next decade.
Market Dynamics
Containerized modular power blocks are compressing project timelines and redefing how mining operators and data center developers evaluate fixed versus mobile generation assets against total lifecycle cost.
Growth Catalysts
- EPA Stationary Engine Standards:Tightening emissions limits for diesel engines above 560 kW are accelerating replacement cycles across US manufacturing facilities and emergency backup fleets.
- Grid Instability in India:Voltage fluctuations and scheduled rolling blackouts in Maharashtra and Gujarat are compelling automotive and textile manufacturers to install captive gas and diesel generation capacity.
- Dual-Fuel Engine Platforms:The ability to switch between diesel and natural gas without load interruption is reducing fuel cost exposure for operators in markets with volatile energy pricing.
Market Restraints
- Platinum Group Metal Costs:Exhaust aftertreatment systems for Tier 4 Final and Stage V compliance rely on palladium and rhodium catalysts, creating margin pressure when commodity prices spike.
- Engine Block Casting Concentration:Foundry capacity for heavy-duty engine components concentrates in China and India, exposing lead times to regional logistics constraints.
- Pipeline Infrastructure Gaps:Natural gas generator deployment faces hard limits in Sub-Saharan Africa and parts of Southeast Asia where distribution networks remain underdeveloped.
Strategic Opportunities
- Hydrogen-Ready Engine Retrofits:Wärtsilä and MAN Energy Solutions are certifying gas engine platforms for hydrogen blends, positioning for EU Green Deal hydrogen corridor investments.
- Remote Monitoring as Service Revenue:Predictive maintenance platforms using vibration analysis and oil degradation sensors are creating recurring revenue streams independent of equipment sales.
- Data Center Hyperscaler Contracts:Microsoft, Amazon, and Google are procuring multi-hundred-megawatt backup power through 10-15 year power purchase agreements with guaranteed uptime clauses.
Industry Challenges
- Emissions Calibration Complexity:Field tuning of selective catalytic reduction systems for varying load profiles requires specialized technicians that OEM service networks struggle to recruit.
- Interconnection Queue Delays:Utility approval timelines for grid-parallel generator installations in California and Texas are extending project completions by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Generator Market |
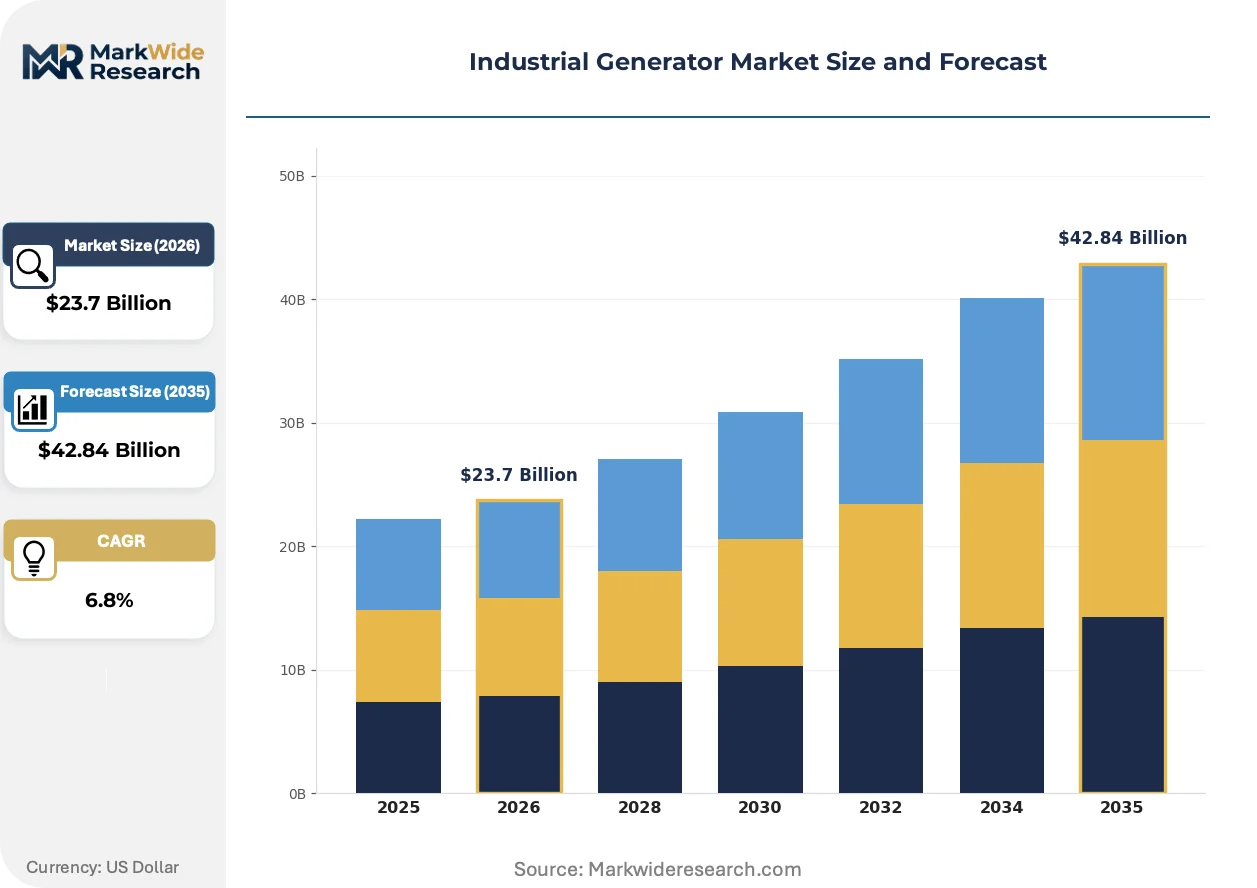
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Hybrid Generators, Portable Generators End User: Construction, Mining, Manufacturing, Events Technology: Conventional, Renewable, Smart Grid, Standby Application: Power Generation, Backup Power, Prime Power, Distributed Generation |
| Companies Covered | Caterpillar, Cummins, Generac Power Systems, Rolls-Royce, Kohler, Mitsubishi Heavy Industries, Wärtsilä, Kirloskar Electric Company, Multiquip, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Generator Market Emerging Trajectories
Digital twins and physics-based simulation are compressing engine development cycles while remote diagnostics platforms are shifting maintenance from scheduled intervals to condition-based interventions.
Advanced exhaust aftertreatment is integrating diesel particulate filters with selective catalytic reduction and ammonia slip catalysts into single compact modules. Mining operators in Western Australia and Chile are specifying these integrated systems to meet site-specific air quality permits. This convergence is integrating emissions hardware with engine control units through proprietary CAN bus architectures that lock in OEM service relationships.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in generator set cooling systems and switchgear insulation. Engine manufacturers are redesigning thermal management circuits to accommodate CO2-based cooling and dry air insulation. Data center deployments in Germany and the Netherlands are experiencing the earliest compliance pressure, with operators demanding factory-certified F-Gas-free configurations.
Power-as-a-service contracting is displacing traditional capital purchase models for distributed generation. Industrial facilities in Texas and Pennsylvania are signing 7-10 year agreements where the OEM retains asset ownership and guarantees availability. This model concentrates with oil and gas midstream operators seeking to remove generation assets from their balance sheets.
Industrial Generator Market Segmentation
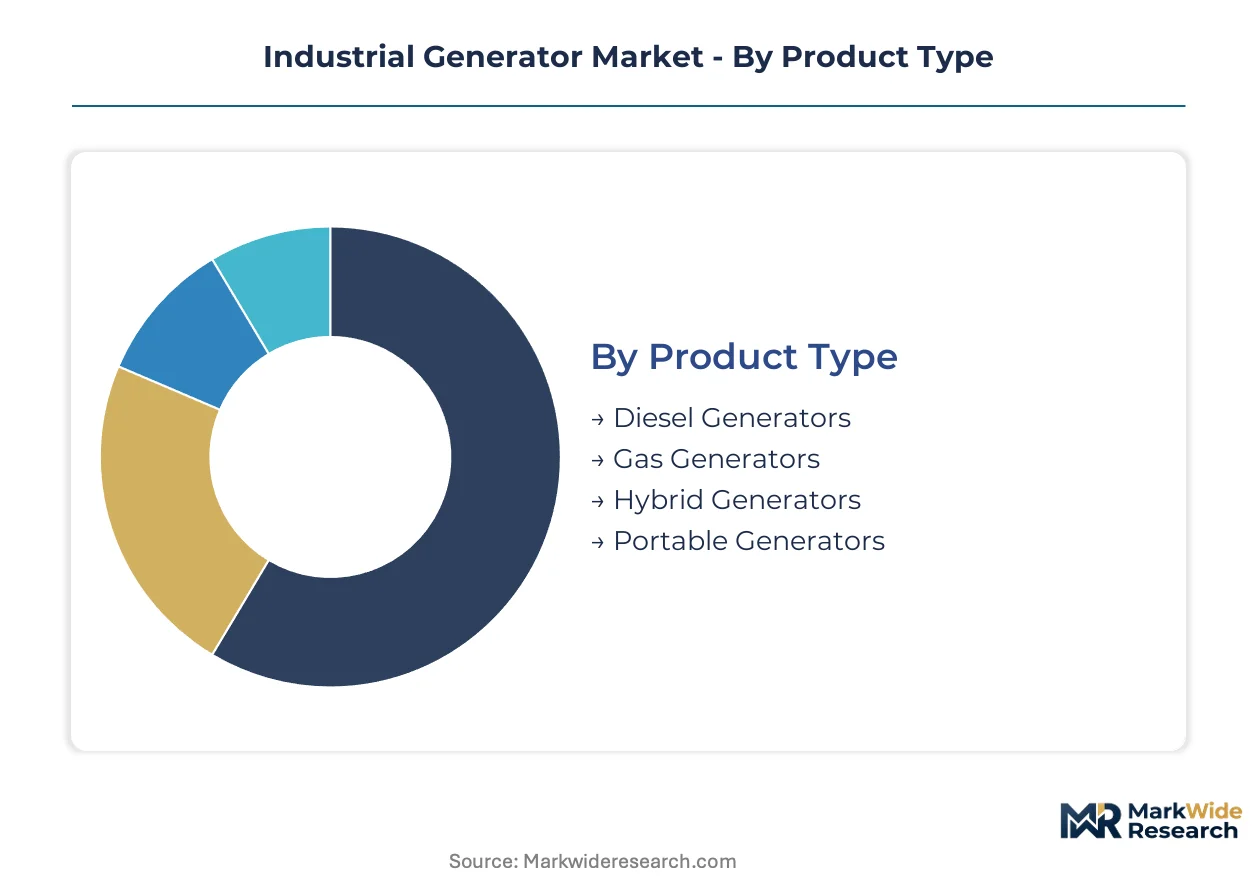
Industrial generator procurement varies sharply by operational intensity and fuel infrastructure availability. Buyers segment choices around runtime economics, emissions compliance burdens, and integration complexity with existing plant systems.
Product Type:
Diesel and gas platforms demand the heaviest capital deployment, while portable units minimize upfront outlay through rental channels.
- Diesel Generators:Compression-ignition engines deliver the highest energy density per liter, making them indispensable for remote mining camps in Western Australia and Chile where fuel logistics dominate operating cost. Caterpillar and Cummins anchor their service networks on these units, locking in multi-year parts contracts.
- Gas Generators:Spark-ignited engines burning pipeline natural gas or field gas achieve lower particulate emissions and reduced fuel cost volatility where distribution infrastructure exists. Data center operators in Texas and Pennsylvania specify these for continuous runtime behind-the-meter applications.
- Hybrid Generators:Diesel-battery or gas-battery combinations modulate engine loading to improve fuel efficiency and extend maintenance intervals.
- Portable Generators:Trailer-mounted or skid-mounted units below 500 kW serve construction sites and temporary events through rental fleet deployment.
Most installed capacity flows through diesel generators. Expansion is steepest in hybrid configurations.
End User:
Manufacturing and mining represent the highest absolute spend, while events and construction drive rental fleet turnover.
- Manufacturing:Automotive and textile plants in Maharashtra and Gujarat install captive gas and diesel capacity to buffer against grid instability and voltage fluctuations that ruin production batches.
- Mining:Open-pit copper and iron ore operations in Western Australia and Chile specify containerized modular blocks for camp power and process crushing circuits, with emissions hardware tailored to site-specific air quality permits.
- Construction:Commercial building projects and infrastructure sites rely on rental portable units for temporary power during grid connection delays.
- Events:Music festivals and sporting venues deploy mobile generator fleets for short-duration, high-reliability power with rapid deployment requirements.
Manufacturing commands the largest share of new orders. Events show the most rapid fleet refresh cycles.
Technology:
Smart grid and renewable integration platforms carry premium pricing but reduce lifecycle cost through predictive maintenance and fuel optimization.
- Smart Grid:Remote monitoring platforms using vibration analysis and oil degradation sensors shift maintenance from scheduled intervals to condition-based interventions, creating recurring service revenue streams for OEMs.
- Conventional:Basic engine-alternator sets without integrated controls dominate price-sensitive procurement in developing markets where technician scarcity limits advanced system adoption.
- Renewable:Solar-diesel or wind-diesel hybrid controllers manage battery charging and load dispatch to minimize engine runtime.
- Standby:Automatic transfer switch integration for emergency backup applications prioritizes start reliability over fuel efficiency.
Conventional systems retain the largest installed base. Smart grid platforms are climbing the fastest as data center operators mandate uptime guarantees.
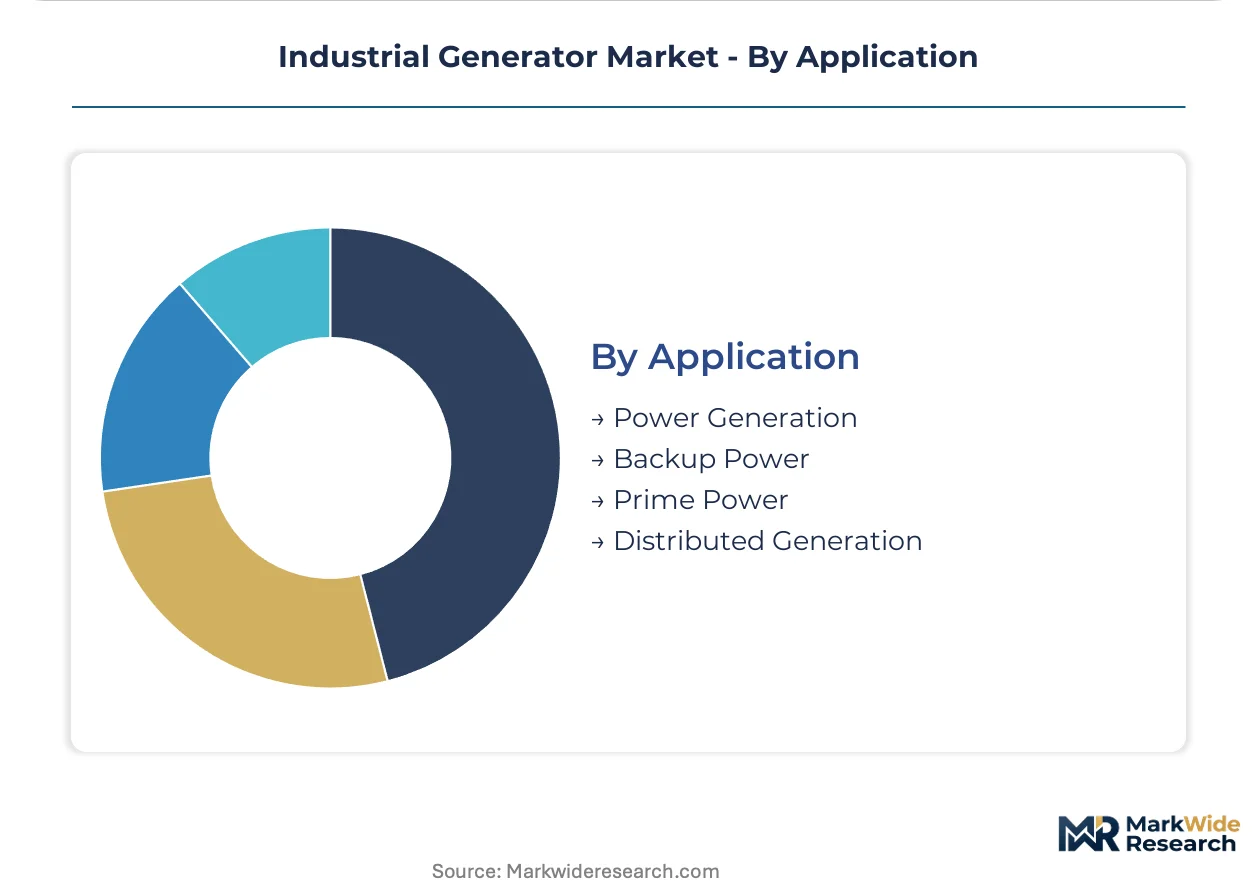
Application:
Prime power and distributed generation require the most sophisticated control architectures, while backup power emphasizes start reliability and regulatory compliance documentation.
- Prime Power:Continuous operation applications in oil and gas midstream and remote mining demand heavy-duty engine blocks with extended overhaul intervals and integrated heat recovery systems.
- Backup Power:Emergency standby systems for hospitals, data centers, and financial services facilities must demonstrate EPA Tier 4 Final or equivalent emissions compliance and automatic load transfer within ten seconds.
- Power Generation:Grid-parallel installations in Texas and California face interconnection queue delays of 8-14 months, extending project timelines and capital lockup.
- Distributed Generation:Behind-the-meter installations at industrial campuses and commercial complexes reduce exposure to utility tariff volatility and demand charges.
Backup power represents the largest addressable market. Distributed generation is expanding most quickly as commercial and industrial ratepayers seek tariff arbitrage opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial generator industry traces its modern scaling to post-war American manufacturing and European reconstruction, with Caterpillar and Cummins establishing the integrated service-network model that now defines competitive positioning worldwide.
United States
Data center hyperscalers in Virginia and Texas are procuring multi-hundred-megawatt backup capacity through decade-long power purchase agreements. EPA Tier 4 Final standards for engines above 560 kW are accelerating replacement cycles across manufacturing facilities. The Permian Basin oilfield cluster drives demand for mobile prime power units with dual-fuel flexibility.
China
Foundry capacity for heavy-duty engine blocks concentrates in Jiangsu and Shandong provinces, exposing lead times to regional logistics constraints. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions compliance for stationary engines. Manufacturing plants in the Yangtze River Delta install captive diesel and gas capacity to buffer against grid instability during peak demand seasons.
Germany
Industrial facilities in North Rhine-Westphalia and Bavaria demand factory-certified F-Gas-free generator configurations ahead of EU regulation deadlines. The EU Green Deal hydrogen corridor investments are prompting engine OEMs to certify gas platforms for hydrogen blends. Chemical parks along the Rhine corridor specify flexible gas engines for distributed generation behind-the-meter applications.
India
Automotive and textile manufacturers in Maharashtra and Gujarat install captive generation to protect production batches from voltage fluctuations and scheduled rolling blackouts. The Central Electricity Authority grid connectivity norms shape product certification requirements for parallel operation. The Delhi-NCR industrial belt faces acute pressure from air quality regulations that favor gas over diesel installations.
Australia
Open-pit iron ore and lithium operations in Western Australia specify containerized modular power blocks for camp power and process crushing circuits. State-level air quality permits in Queensland and New South Wales mandate integrated exhaust aftertreatment systems. Mining operators in the Pilbara region prioritize total lifecycle cost evaluation over upfront capital expenditure.
Industrial Generator Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive engine technology and continental service networks. The vendor base spans three tiers: integrated power systems houses with full controls architecture, engine specialists licensing alternator technology, and regional assemblers sourcing blocks from foundry partners. Strategic moves concentrate on exhaust aftertreatment integration and predictive maintenance platform deployment.
Among the integrated power systems houses, Caterpillar, Cummins, and Wärtsilä occupy positions that exemplify distinct competitive archetypes. Caterpillar represents the mining and heavy infrastructure anchor with embedded controls lock-in. Cummins exemplifies dual-fuel engineering intensity targeting volatile fuel markets. Wärtsilä anchors the flexible gas engine segment for distributed generation in pipeline-rich European and Asian markets.
| Leading Market Players |
|---|
| Caterpillar |
| Cummins |
| Generac Power Systems |
| Rolls-Royce |
| Kohler |
| Mitsubishi Heavy Industries |
| Wärtsilä |
| Kirloskar Electric Company |
| Multiquip |
| Others |
Supply Flow & Price Mechanics
Family-owned foundry operators in Jiangsu and Shandong provinces anchor heavy-duty engine block casting, creating supply discipline that resists price erosion even when palladium and rhodium catalyst costs spike. Their captive financing relationships with regional diesel component assemblers transmit alloy commodity volatility directly into Tier 4 Final compliance premiums for North American buyers.
Pricing Analysis
Project-based contracting with availability guarantees dominates hyperscaler data center procurement, while rental fleet operators price portable units on utilization-adjusted hourly rates. Three-tier pricing structure across EPA-certified, EU Stage V-compliant, and economy-grade configurations reflects aftertreatment hardware differentiation. Cost compression in the economy tier is intensifying because Indian and Southeast Asian buyers prioritize upfront capital minimization over lifecycle fuel efficiency. Manufacturing facilities in Maharashtra exhibit the sharpest price sensitivity, whereas mining operators in Western Australia accept premium positioning for modular containerized blocks with integrated heat recovery.
Supply Chain Analysis
Regional distribution centers in Texas, North Rhine-Westphalia, and Gujarat operate hub-and-spoke patterns that position alternator and control module inventory within 48-hour reach of major deployment clusters. Foundry capacity for engine blocks concentrates in China, India, and Germany, drawing from iron ore feedstocks in Western Australia and coking coal from Mongolia. Single-source vulnerability in platinum group metal catalyst supply from South Africa and Russia exposes aftertreatment system costs to geopolitical disruption. Distribution runs through OEM-owned service networks that lock in multi-year parts contracts, compressing third-party aftermarket access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial generator market functions as a regulatory compounder, with EPA Tier 4 Final and EU Stage V emissions milestones forcing replacement cycles that override pure economic optimization for installed base owners.
For Market Incumbents: Cement controls architecture lock-in by embedding proprietary CAN bus protocols that tie emissions hardware to engine management systems, raising switching costs for mining and data center operators. Deepen backward integration into exhaust aftertreatment catalyst recycling to buffer margin pressure from palladium and rhodium price spikes. Prioritize technician certification programs that address the scarcity of field-calibration specialists for selective catalytic reduction systems. For New Entrants and Emerging Players: Hydrogen-ready gas engine retrofits offer a technology-first wedge into EU Green Deal hydrogen corridor investments, where Wärtsilä and MAN Energy Solutions have established early positioning. Target distributed generation deployments in German chemical parks and Dutch data centers seeking F-Gas-free configurations ahead of regulatory deadlines. Pursue power-as-a-service contracting models that remove capital expenditure barriers for oil and gas midstream operators in Texas and Pennsylvania. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers sourcing engine blocks from Jiangsu foundries, where logistics constraints and emissions compliance investments have compressed multiples. Long-term viability hinges on captive power economics remaining favorable against utility tariff structures and carbon pricing mechanisms. Watch interconnection queue timelines in California and Texas as the signal for distributed generation project velocity and capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Exhaust Aftertreatment Integration | Single-module DPF-SCR-ASC systems lock in OEM service relationships for Tier 4 Final compliance. |
| Predictive Maintenance Platform Deployment | Vibration analysis and oil degradation sensors create recurring revenue independent of equipment sales. |
| Hydrogen-Ready Engine Certification | Gas platform modifications position OEMs for EU Green Deal hydrogen corridor investments. |
| Power-as-a-Service Contracting | Availability guarantees transfer balance sheet risk from oil and gas midstream operators to OEMs. |
| Containerized Modular Power Block Expansion | Compressed project timelines attract data center developers evaluating fixed versus mobile assets. |
Methodological Framework
Multiple input streams — primary interviews with plant engineers and aftermarket service heads, secondary validation through EIA capacity data and EPA certification records, and customs trade flows for engine block imports — were reconciled to construct bottom-up and top-down estimates. Conversations with maintenance directors at automotive facilities in Maharashtra, procurement leads at Western Australian mining operations, and EPC contractors specializing in data center power infrastructure informed operational assumptions. SEC filings from Caterpillar and Cummins, EU ETS carbon price series, and FERC interconnection queue databases provided secondary anchors.
Data-stream reconciliation across product type, fuel technology, end-use intensity, and regional regulatory framework dimensions produced volume and value trajectories over the projection horizon. CAGRs were derived from segment-level growth rate distributions weighted by installed base turnover and replacement cycle acceleration from emissions standards. Forecast inputs incorporated EPA stationary engine rulemaking timelines, India CEA grid connectivity enforcement patterns, and EU F-Gas Regulation phase-down schedules for cooling system refrigerants.
The model holds under stable regulatory enforcement and commodity price bands; deviation in platinum group metal supply disruption or interconnection approval delays would shift replacement cycle timing and project completion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Asia-Pacific Gas Generator Market
Generators
Tri Fuel Generators Market
Generators
Portable Inverter Generators Market
Generators
Gasoline Gensets Market
Generators
Containerized Solar Generators Market
Generators
North America Generator Sets Market
Generators
China Diesel Generator Market
Generators
Onboard Marine Gensets Market
Generators
Hand Crank Power Generator Market
Generators
South America Gas Generator Market
Generators
Construction Prime Power Generators Market
Generators
South America Generator Sets Market
Generators
Silent Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
North West Europe Diesel Generator Market
Generators
Reciprocating Power Generating Engine Market