
 South America Diesel Generator Market | 2026-2036
South America Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
South America Diesel Generator Market Analytics
Multi-source procurement among large energy users is shifting toward consolidated supplier relationships with regional service capabilities. Caterpillar Inc anchors its position through an extensive dealer network across Brazil and Argentina. WEG S.A. leverages domestic manufacturing in Jaraguá do Sul to compete on lead times and aftermarket proximity. Cummins Inc differentiates through integrated power system design spanning generator sets and switchgear.
A diesel generator converts mechanical energy from compression-ignition engines into electrical output, typically operating at 50 Hz or 60 Hz with power ratings from one kilowatt to multiple megawatts; these units serve as primary, standby, or emergency power sources for facilities where grid supply proves unreliable or unavailable. Standby and prime product types capture the dominant share of revenue as commercial and industrial end users prioritize operational continuity over fuel efficiency in volatile grid environments. The above 30 kW power rating segment leads volume in mining and heavy manufacturing applications, while the 16-30 kW bracket expands fastest among healthcare facilities requiring NFPA 110-compliant emergency power systems.
Brazil's ANEEL and CONAMA frameworks govern grid interconnection standards and emission thresholds for stationary engines, compelling manufacturers to invest in exhaust after-treatment technologies. Argentina's Secretariat of Energy and Chile's SEC certification requirements further fragment compliance obligations across national boundaries. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and unilateral national standards that complicate cross-border product certification strategies.
Market Dynamics
Grid instability across Brazil's southeastern industrial corridor and Chile's mining belt is forcing facility operators to treat diesel backup as operational infrastructure rather than insurance, compressing replacement cycles and expanding specification requirements.
Growth Catalysts
- CONAMA Resolution 491/2018:Brazil's tightening particulate emission thresholds for stationary engines are accelerating fleet turnover toward Tier 3 and Tier 4 interim compliant units in São Paulo and Minas Gerais manufacturing zones.
- Underground mining electrification gaps:Chilean and Peruvian copper operations below 3,000 meters elevation rely on diesel prime power where grid extension remains economically unviable for at least another decade.
- Healthcare infrastructure expansion:Brazilian hospital construction under the country's universal health system mandates NFPA 110-compliant emergency power, creating specification pull for 16-30 kW synchronized sets.
Market Restraints
- Import dependency for electronic governing systems:Brazil lacks domestic production of variable speed controllers and digital voltage regulators, exposing assemblers to lead time volatility from European and Asian component suppliers.
- Diesel price linkage to international benchmarks:Argentina's fuel pricing volatility tied to peso-dollar exchange rate swings creates total cost of ownership uncertainty that delays capital approval cycles.
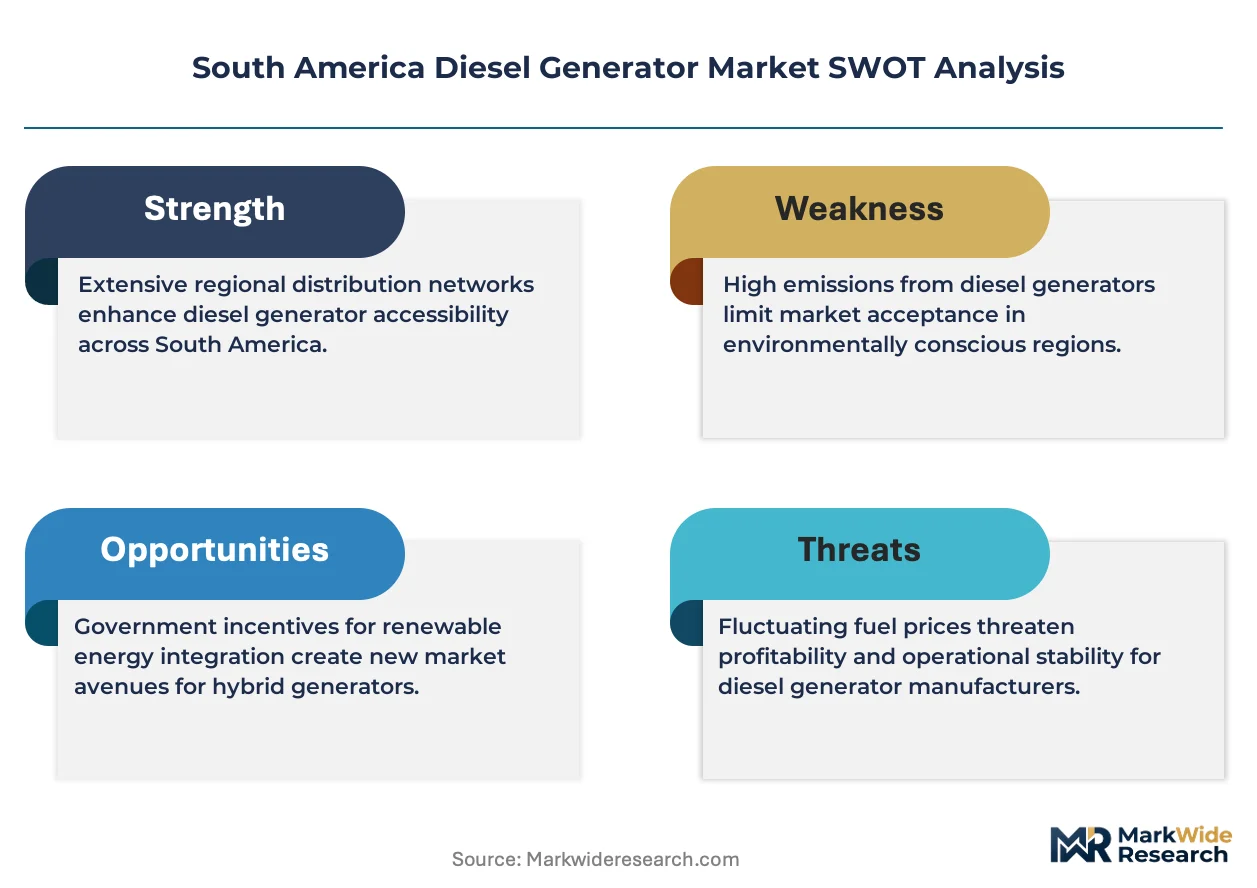
- Lithium-ion microgrid substitution:Declining battery storage costs in Chile's solar-rich northern regions are displacing diesel prime applications in remote telecommunications and small-scale mining camps.
Strategic Opportunities
- Colombia's underserved Pacific coast:Buenaventura port expansion and Chocó mining projects lack established generator service networks, creating first-mover advantage for regional dealers with mobile technician capabilities.
- Hybrid diesel-solar integration:Convergence of photovoltaic arrays with intelligent load management controllers enables fuel consumption reductions of 30-40 percent in off-grid Brazilian agroindustrial operations.
- Argentina's renewable energy auction delays:Grid connection backlogs for wind and solar projects under the RenovAr program extend temporary power requirements, stretching rental fleet utilization rates.
Industry Challenges
- Certification timeline fragmentation:Brazil's INMETRO conformity assessment and Chile's SEC electrical safety approvals operate on non-harmonized testing protocols, forcing manufacturers to duplicate validation expenditure for cross-border sales.
- Skilled technician scarcity:Compression-ignition engine diagnostics and exhaust after-treatment system maintenance require training pipelines that Brazilian vocational institutions have not scaled to match equipment deployment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Diesel Generator Market |
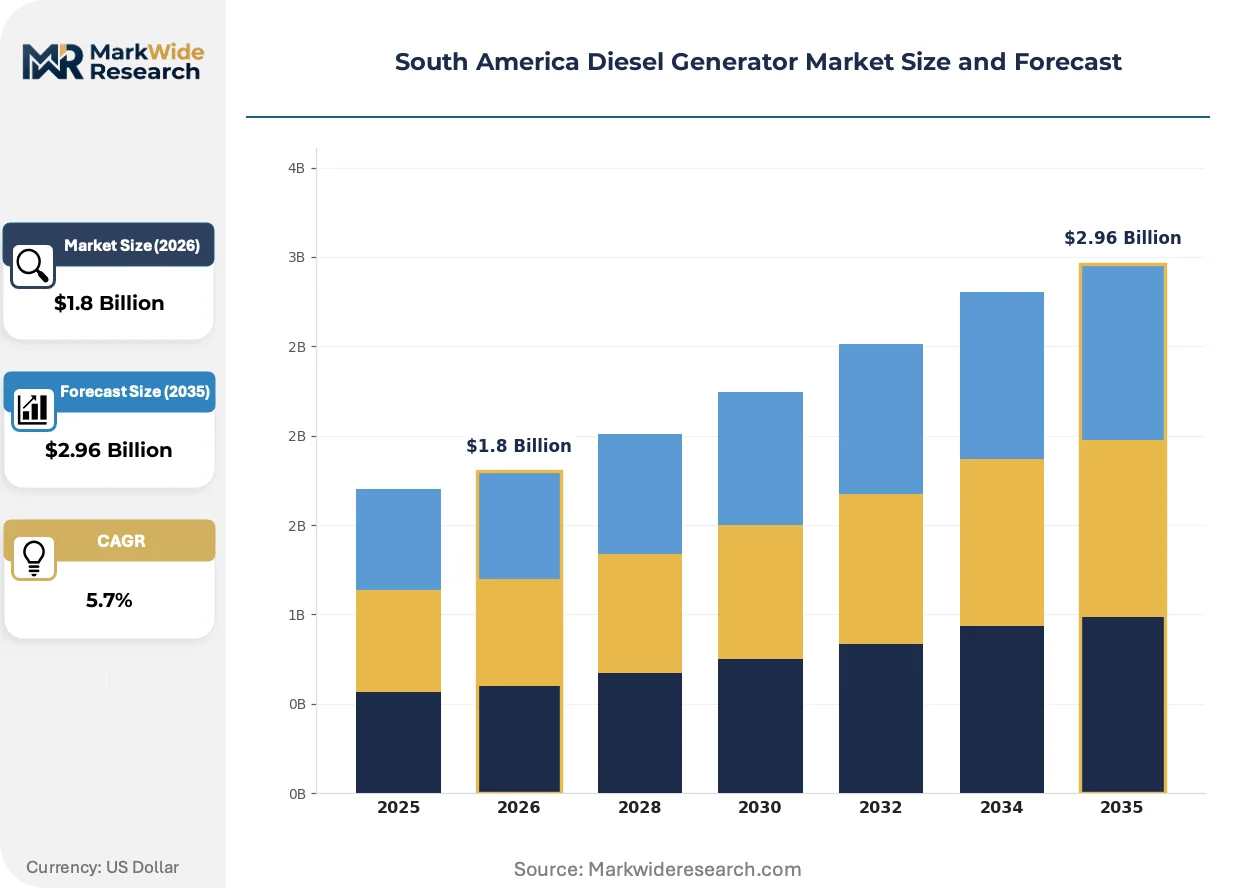
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Prime, Continuous End User: Residential, Commercial, Industrial, Healthcare Power Rating: 1-5 kW, 6-15 kW, 16-30 kW, Above 30 kW Fuel Type: Diesel, Biofuel, Natural Gas, Others |
| Companies Covered | MTU Onsite Energy Corp, Atlas Copco AB, Caterpillar Inc, Yanmar Holdings Co Ltd, J C Bamford Excavators Ltd, Cummins Inc, Kohler Co, WEG S.A., Generac Holdings Inc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Diesel Generator Market Evolving Landscape
Power system architecture is fragmenting from monolithic installations toward configurable sub-assemblies, while emission compliance technology and procurement contracting models undergo parallel reinvention across the continent's industrial base.
Containerized and skid-mounted generator packages are displacing traditional open-set installations in Brazilian data center and pharmaceutical manufacturing applications. Mining operators in Chile's Atacama region specify these units for rapid site relocation as extraction fronts advance. The technology is modularizing power infrastructure deployment, compressing civil engineering requirements from weeks to days and enabling leasing models previously impractical for permanent installations.
Brazil's ANEEL Resolution 1,000/2021 establishes distributed generation interconnection standards that complicate standby system synchronization with grid-tied renewable assets. Industrial facilities in São Paulo state must now engineer islanding capabilities and anti-islanding protections that earlier specifications omitted. The above-30 kW segment faces the steepest engineering adaptation costs as owners retrofit existing fleets rather than full replacement.
Long-term rental and power-as-a-service contracts are displacing capital purchase in Argentine manufacturing where currency volatility distorts equipment financing. Caterpillar dealers and independent rental houses in Córdoba and Rosario industrial corridors now structure five-year agreements bundling maintenance, fuel management, and eventual upgrade paths. Brazilian mining contractors are piloting similar arrangements for remote camp power, transferring operational risk to suppliers with balance sheet capacity to absorb fuel price exposure.
South America Diesel Generator Market Segmentation
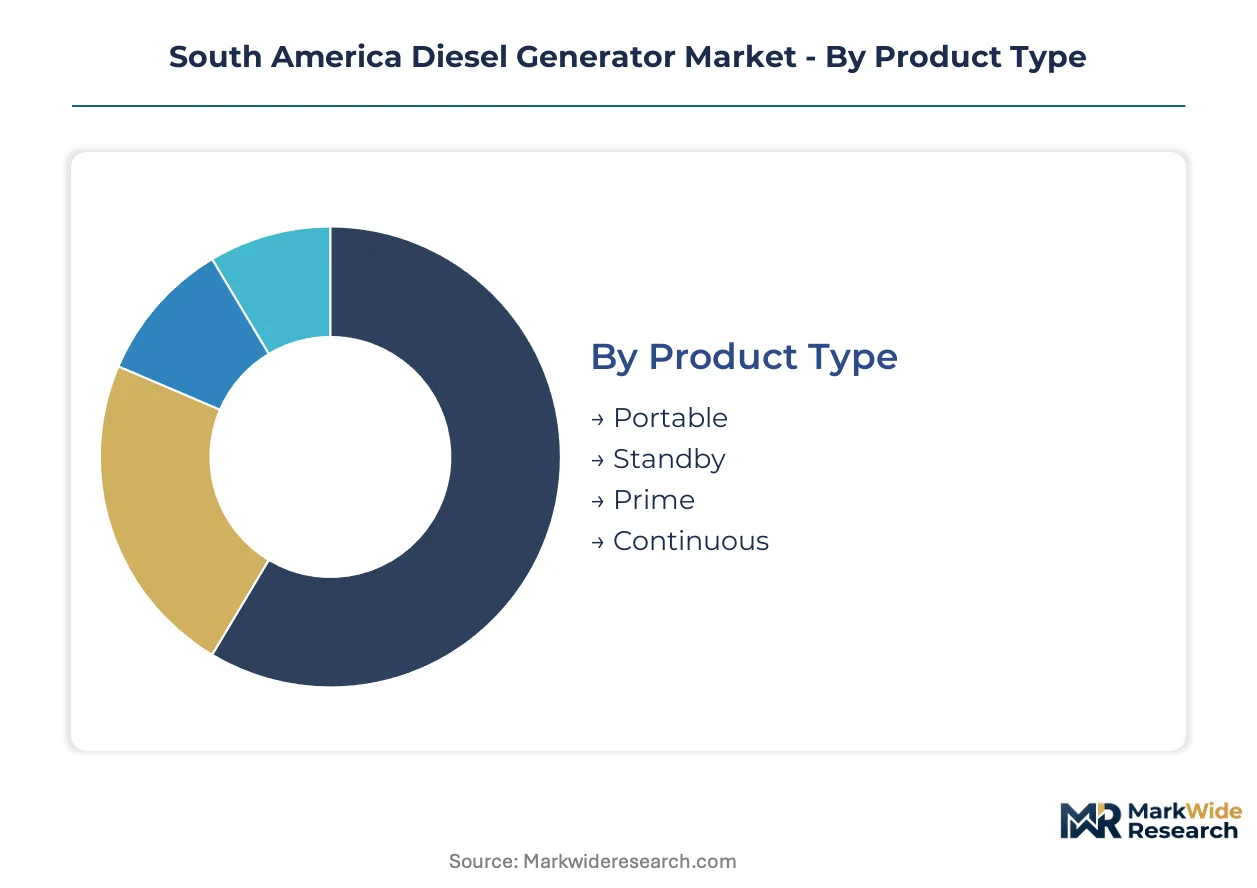
Diesel generator procurement across South America fragments across operational duty cycles, facility scale, and fuel compliance regimes. Buyers in Brazil's industrial corridor and Chile's mining belt prioritize different specification bundles based on grid reliability profiles and emission enforcement intensity.
Product Type:
Standby and prime configurations demand the heaviest capital outlay due to automatic transfer switches, exhaust after-treatment systems, and extended-duty cooling packages. Portable units carry lower upfront costs but require frequent replacement in continuous-use environments.
- Standby:These units activate automatically upon grid failure and must achieve rated output within ten seconds to comply with NFPA 110 for healthcare and data center applications. Brazilian hospital construction under the universal health system specification pull concentrates demand in São Paulo and Minas Gerais states where ANEEL interconnection standards enforce synchronization capabilities. Chilean copper concentrators specify standby sets for process safety systems where unplanned outages trigger multi-million dollar recovery costs.
- Prime:Designed for unlimited hours of variable load operation, these generators serve as primary power where grid extension remains uneconomical. Underground mining operations below 3,000 meters elevation in Chile and Peru rely on prime diesel sets for at least another decade. The segment requires heavy-duty engine blocks and enhanced filtration systems that lift capital costs 40-60 percent above standby equivalents.
- Portable:Trailer-mounted or wheeled units serve construction sites, emergency response, and temporary events. Argentine infrastructure contractors favor rental fleets of portable sets given currency volatility that distorts purchase financing.
- Continuous:Built for constant base load operation at steady output, these units support remote telecommunications towers and off-grid agroindustrial processing. Colombian Pacific coast projects lack established service networks, stretching lead times for continuous-duty maintenance parts.
Standby configurations absorb the bulk of installed capacity across Brazilian healthcare and manufacturing; prime power applications are expanding most quickly in Chilean and Peruvian mining frontiers.
End User:
Industrial facilities generate the highest per-site revenue through multi-megawatt installations and comprehensive service contracts. Residential demand concentrates in backup power for affluent households in grid-unstable zones rather than primary electrification.
- Industrial:Mining, manufacturing, and heavy processing operations require 24/7 power continuity where grid fluctuations threaten production economics. Brazil's southeastern industrial corridor spanning São Paulo and Minas Gerais states accounts for concentrated specification activity. CONAMA Resolution 491/2018 emission thresholds are accelerating fleet turnover toward Tier 3 and Tier 4 interim compliant units.
- Healthcare:Hospitals, clinics, and diagnostic centers mandate NFPA 110-compliant emergency power systems with automatic start and load transfer. Brazilian hospital construction creates specification pull for 16-30 kW synchronized sets. The segment demands rigorous maintenance documentation and fuel testing protocols that lift operational compliance costs.
- Commercial:Retail, hospitality, and office facilities prioritize cost-minimized standby coverage for revenue protection rather than life safety. Argentine commercial buyers favor long-term rental contracts bundling maintenance and fuel management to transfer currency exposure.
- Residential:Single-family and multi-unit housing applications concentrate in affluent Brazilian neighborhoods where grid instability justifies backup investment. The segment favors 6-15 kW units sized for essential circuits rather than whole-home coverage.
Industrial end users command the largest aggregate capacity deployment; healthcare infrastructure is climbing the fastest on Brazilian universal health system expansion.
Power Rating:
Above-30 kW systems require substantial civil engineering, fuel storage, and exhaust infrastructure that multiplies total installed cost beyond equipment price alone. Sub-5 kW units deploy with minimal site preparation.
- Above 30 kW:Mining haulage, concentrator operations, and large manufacturing plants require megawatt-scale generation with paralleling switchgear. Chilean copper operations specify these units for rapid site relocation as extraction fronts advance. ANEEL Resolution 1,000/2021 distributed generation standards complicate standby synchronization, forcing engineering adaptation for grid-tied facilities.
- 16-30 kW:Mid-size healthcare facilities, commercial buildings, and small industrial plants favor this bracket for balance of capital efficiency and load coverage. Brazilian hospital construction mandates NFPA 110 compliance, creating specification pull for synchronized sets in this range. The segment benefits from standardized skid packages that compress installation timelines.
- 6-15 kW:Small commercial facilities, residential estates, and remote telecommunications sites deploy these units for essential circuit coverage. Argentine rental fleets concentrate in this bracket for manufacturing corridor temporary power.
- 1-5 kW:Portable and recreational applications dominate this entry-level segment. Brazilian residential buyers in grid-unstable neighborhoods favor these units for selective appliance backup.
Above-30 kW systems carry the heaviest installed base in mining and heavy manufacturing; 16-30 kW configurations are gaining share fastest on healthcare infrastructure mandates.
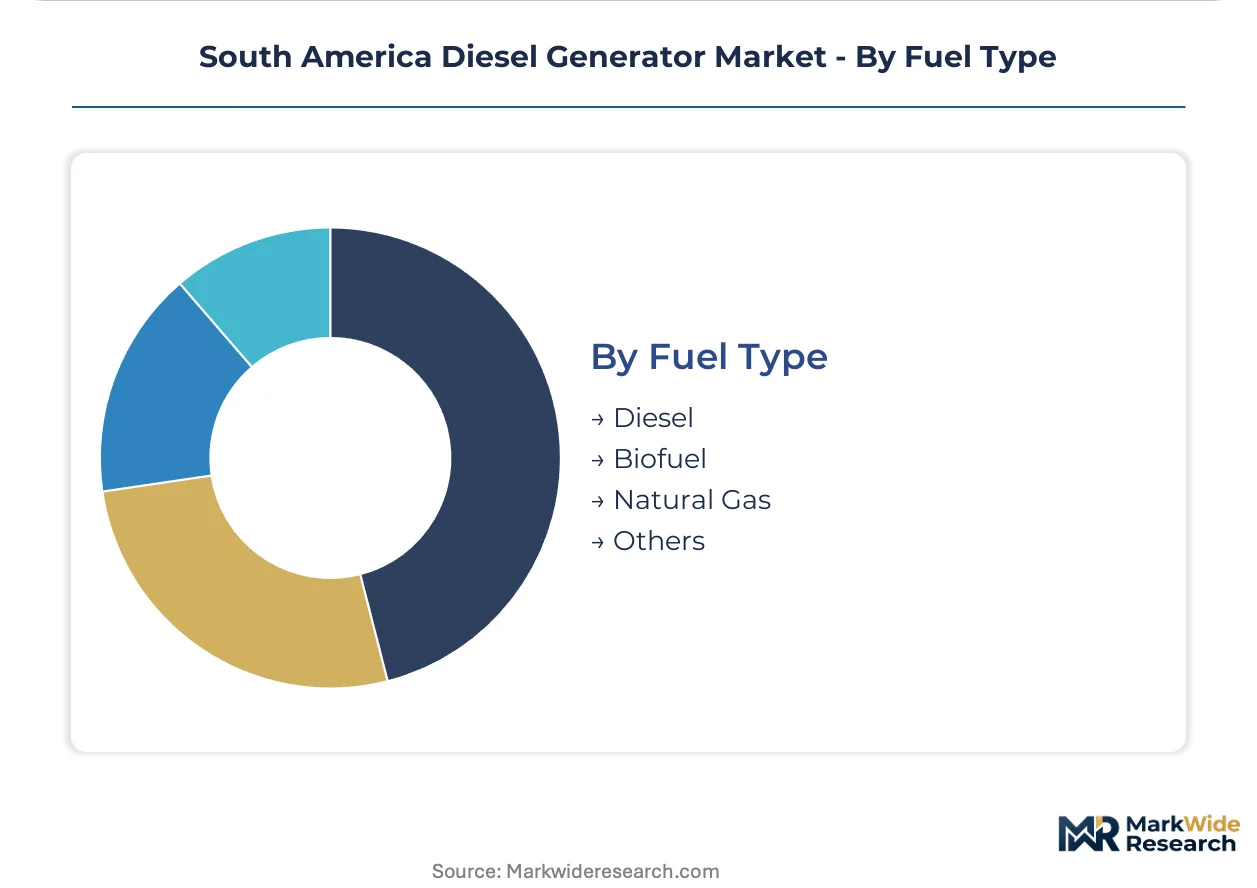
Fuel Type:
Diesel retains capital cost advantages in prime power and large standby applications despite emission compliance investments. Biofuel and natural gas alternatives require fuel supply infrastructure that lifts total project economics.
- Diesel:Compression-ignition engines dominate mining, healthcare, and industrial standby applications for energy density and load response. Brazil's ANEEL and CONAMA frameworks govern grid interconnection and emission thresholds, compelling exhaust after-treatment investment. Argentina's fuel pricing volatility tied to peso-dollar exchange rates creates total cost of ownership uncertainty.
- Biofuel:Biodiesel blends and renewable diesel variants serve environmental compliance objectives in Brazilian agroindustrial operations. The segment requires fuel quality verification and modified injection system maintenance.
- Natural Gas:Spark-ignited gas engines compete in grid-connected standby where pipeline infrastructure exists. Brazilian industrial corridors with established gas distribution specify these units for reduced emission profiles.
- Others:Dual-fuel and emerging synthetic fuel configurations occupy niche pilot applications. Chilean solar-rich northern regions are testing hybrid diesel-solar integration with intelligent load management.
Diesel retains dominant share across South American installed capacity; biofuel blends are expanding most quickly on Brazilian agroindustrial sustainability targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper deposits in Chile's Atacama Desert and iron ore formations in Brazil's Carajás Basin anchor diesel generator demand across South American mining corridors. Grid reliability deficits in southeastern Brazil and currency volatility in Argentina reshape procurement patterns for standby power infrastructure. National regulatory frameworks fragment compliance requirements across Mercosur boundaries.
Brazil
Iron ore mining in Pará state and soybean processing in Mato Grosso drive prime power installations where grid extension remains uneconomical. ANEEL Resolution 1,000/2021 mandates distributed generation interconnection standards that complicate standby synchronization for industrial facilities. São Paulo and Minas Gerais states concentrate manufacturing demand as CONAMA emission thresholds accelerate fleet turnover toward Tier 3 and Tier 4 interim compliant units.
Chile
Underground copper extraction below 3,000 meters elevation in the Atacama Desert relies on diesel prime power for haulage and ventilation systems. SEC certification requirements govern electrical safety approvals for stationary engines, operating on non-harmonized testing protocols with Brazilian INMETRO standards. Antofagasta Region mining camps specify containerized generator packages for rapid site relocation as extraction fronts advance.
Argentina
Shale oil developments in Vaca Muerta and agricultural processing in Córdoba province sustain demand for continuous-duty generation. Peso-dollar exchange rate volatility creates total cost of ownership uncertainty that delays capital approval cycles and extends temporary power rental arrangements. Rosario industrial corridor manufacturers favor five-year service contracts bundling maintenance and fuel management to transfer currency exposure.
Peru
Gold and copper operations in the Andean Cordillera deploy prime power sets at elevations where grid infrastructure cannot penetrate mountain terrain. The country's national mining regulator enforces environmental compliance protocols that shape exhaust after-treatment specifications for remote camp power. Arequipa Region concentrator plants require synchronized standby systems to prevent multi-million dollar recovery costs from unplanned outages.
Colombia
Pacific coast port expansion at Buenaventura and Chocó department mining projects lack established generator service networks, stretching lead times for maintenance parts. The national environmental licensing authority imposes emission thresholds that diverge from Brazilian CONAMA standards, complicating cross-border product certification strategies. Antioquia department agroindustrial processors pilot hybrid diesel-solar integration with intelligent load management controllers.
South America Diesel Generator Market Competitive Landscape
Global majors compete with regional champions across distribution reach and aftermarket service density. The vendor base organizes into three tiers: integrated power system designers with switchgear capabilities, domestic assemblers leveraging manufacturing proximity, and rental fleet operators absorbing operational risk. Consolidation pressures concentrate among mid-scale fabricators lacking certified service networks. Dominant competitive moves include geographic expansion through dealer appointments and portfolio diversification into hybrid energy systems.
Among global power equipment manufacturers, Caterpillar Inc and Cummins Inc exemplify integrated system architects with extensive regional dealer infrastructure. WEG S.A. occupies a position as the dominant domestic manufacturer with captive production in Jaraguá do Sul. These three anchors represent divergent strategic postures: foreign-owned full-liners competing on specification breadth, versus a Brazilian champion optimizing lead times and aftermarket proximity through vertical manufacturing control.
| Leading Market Players |
|---|
| MTU Onsite Energy Corp |
| Atlas Copco AB |
| Caterpillar Inc |
| Yanmar Holdings Co Ltd |
| J C Bamford Excavators Ltd |
| Cummins Inc |
| Kohler Co |
| WEG S.A. |
| Generac Holdings Inc |
| Others |
Value Network & Pricing Analysis
Global diesel price benchmarks cascade through South American generator markets, compressing margins for assemblers lacking captive fuel hedging while elevating total cost of ownership sensitivity among Argentine and Brazilian industrial buyers. Tiered pricing structures stratify across premium, standard, and economy levels based on emission certification grade and aftermarket service bundling intensity.
Pricing Analysis
Warranty and preventive maintenance bundling separate premium-tier offerings from unbundled equipment-only transactions in Brazilian mining corridors. Three-tier pricing structure across premium, standard, and economy levels reflects CONAMA Tier 4 interim certification status, paralleling switchgear inclusion, and regional service network density. Cost compression in the standard tier is intensifying as WEG S.A. and domestic assemblers exploit manufacturing proximity to undercut landed costs of fully-imported systems. Healthcare facilities and data center operators exhibit lowest price sensitivity due to NFPA 110 compliance mandates and downtime cost exposure, while Argentine commercial buyers facing peso volatility demonstrate highest elasticity.
Supply Chain Analysis
INMETRO and SEC certification requirements gate component sourcing for Brazil and Chile respectively, forcing parallel validation tracks on electronic governing systems and exhaust after-treatment modules. Manufacturing concentration centers on Brazil for domestic assembly, China for engine blocks and alternators, and Germany for precision fuel injection and emission control technologies. Critical input dependencies include high-pressure common rail systems, digital voltage regulators, and diesel oxidation catalyst substrates. Single-source vulnerability in variable speed controllers from European suppliers exposes Brazilian assemblers to lead time volatility. Distribution runs through authorized dealer networks with captive service capabilities rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around service-capable integrated power system providers as CONAMA emission deadlines and ANEEL interconnection complexity eliminate pure equipment traders. Certification timeline fragmentation and skilled technician scarcity are forcing weaker fabricators toward exit or acquisition.
For Market Incumbents: Anticipate lithium-ion microgrid substitution in Chilean solar-rich regions by accelerating hybrid diesel-solar pilot deployments with intelligent load management controllers. Deepen backward integration into exhaust after-treatment assembly within Brazil to compress Tier 4 compliance costs and defend margin position against WEG S.A.'s manufacturing proximity advantage. Prioritize captive technician training pipelines to address scarcity compression in Brazilian vocational institutions. For New Entrants and Emerging Players: Launch via mobile service fleet partnerships targeting Colombia's Pacific coast where Buenaventura port expansion and Chocó mining projects lack established generator service networks. Focus initial penetration on continuous-duty applications in remote telecommunications and agroindustrial processing where incumbent coverage gaps are widest. Exploit Argentina's rental market preference for power-as-a-service contracts to transfer currency exposure while building installed base. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Brazilian fabricators with INMETRO certification but incomplete service networks in São Paulo and Minas Gerais states. Long-term viability hinges on regulatory compliance capabilities across Mercosur harmonization efforts and unilateral national standards. Watch Argentina's RenovAr renewable auction grid connection backlogs as inflection indicator for temporary power rental fleet utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Exhaust After-Treatment Technology Licensing | Enables Tier 4 interim compliance without captive R&D investment in CONAMA-regulated zones. |
| Hybrid Diesel-Solar Integration Partnership | Captures 30-40% fuel consumption reduction demand from Brazilian agroindustrial off-grid operators. |
| Regional Service Network Acquisition | Addresses technician scarcity compression and consolidates aftermarket revenue in Chilean mining belts. |
| Containerized Generator Platform Standardization | Supports rapid site relocation requirements in Atacama extraction fronts and reduces civil engineering timelines. |
| Power-as-a-Service Contract Portfolio Buildout | Transfers fuel price and currency exposure to balance sheet-capable suppliers in Argentine manufacturing corridors. |
Research Methodology
Document review covered ANEEL regulatory filings, CONAMA resolution texts, SEC certification protocols, and mining operator procurement disclosures, complemented by interviews with maintenance directors at Brazilian manufacturing plants, aftermarket service heads at regional Caterpillar dealers, procurement leads at Chilean copper concentrators, and biomedical engineers specifying NFPA 110 systems for hospital construction. Secondary validation drew from customs trade data, INMETRO conformity assessment records, and distributed generation interconnection statistics. Bottom-up equipment deployment estimates were triangulated against top-down industrial electricity consumption patterns.
Historical shipment data was cross-referenced against panel input from generator set assemblers and component distributors to construct the analytical framework across the projection horizon. Segmentation modeling incorporated power rating tiers, operational duty cycles, end-use industry verticals, and national regulatory framework clusters. CAGRs were derived from equipment replacement cycle compression analysis and fleet turnover acceleration under emission thresholds. Industry-specific inputs included mining extraction front advance rates and Brazilian universal health system hospital construction pipelines.
Regulatory enforcement variance, commodity price volatility, and renewable substitution acceleration are the dominant revision risks to installed base forecasts. Model outputs reflect documented assumptions regarding grid reliability degradation trajectories and emission compliance timeline adherence. A model refresh is warranted upon material change in ANEEL distributed generation interconnection standards or CONAMA resolution implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
India Generator Sets Market
Generators
South America Gas Generator Market
Generators
Southeast Asia Portable Generator Market
Generators
Industrial Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Nuclear Turbine Generators Market
Generators
Wind Power Generators Market
Generators
Construction Generator Sets Market
Generators
Diesel Generator Market
Generators
South America Portable Generator Market
Generators
Global Portable Generator Market
Generators
Construction Portable Generators Market
Generators
United States Portable Generator Market
Generators
Asia-Pacific Gas Generator Market
Generators
Generator [Up to 100 Kva] Market
Generators
Europe Turbo Generator Market