
 United States Diesel Generator Market | 2026-2036
United States Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
United States Diesel Generator Market Analytics
The United States diesel generator market is restructuring around a sharp split between low-emission premium units for regulated environments and cost-optimized commodity sets for price-sensitive buyers. Caterpillar Inc leverages its integrated engine-alternator architecture to dominate the above-500 kVA industrial tier. Cummins Inc sustains broad channel coverage across stationary and trailer-mounted configurations through its dealer network density.
A diesel generator converts mechanical energy from compression-ignition engines into electrical output, typically operating at 1800 RPM for 60 Hz North American grids with fuel consumption curves measured in gallons per hour at defined load banks. Backup power applications command the largest revenue pool across healthcare and data center end users, while containerized deployments represent the fastest-growing deployment format due to modular scalability and reduced site preparation. The 251-500 kVA power rating band captures concentrated margin as mid-scale commercial and light industrial buyers prioritize footprint efficiency over sub-100 kVA portability.
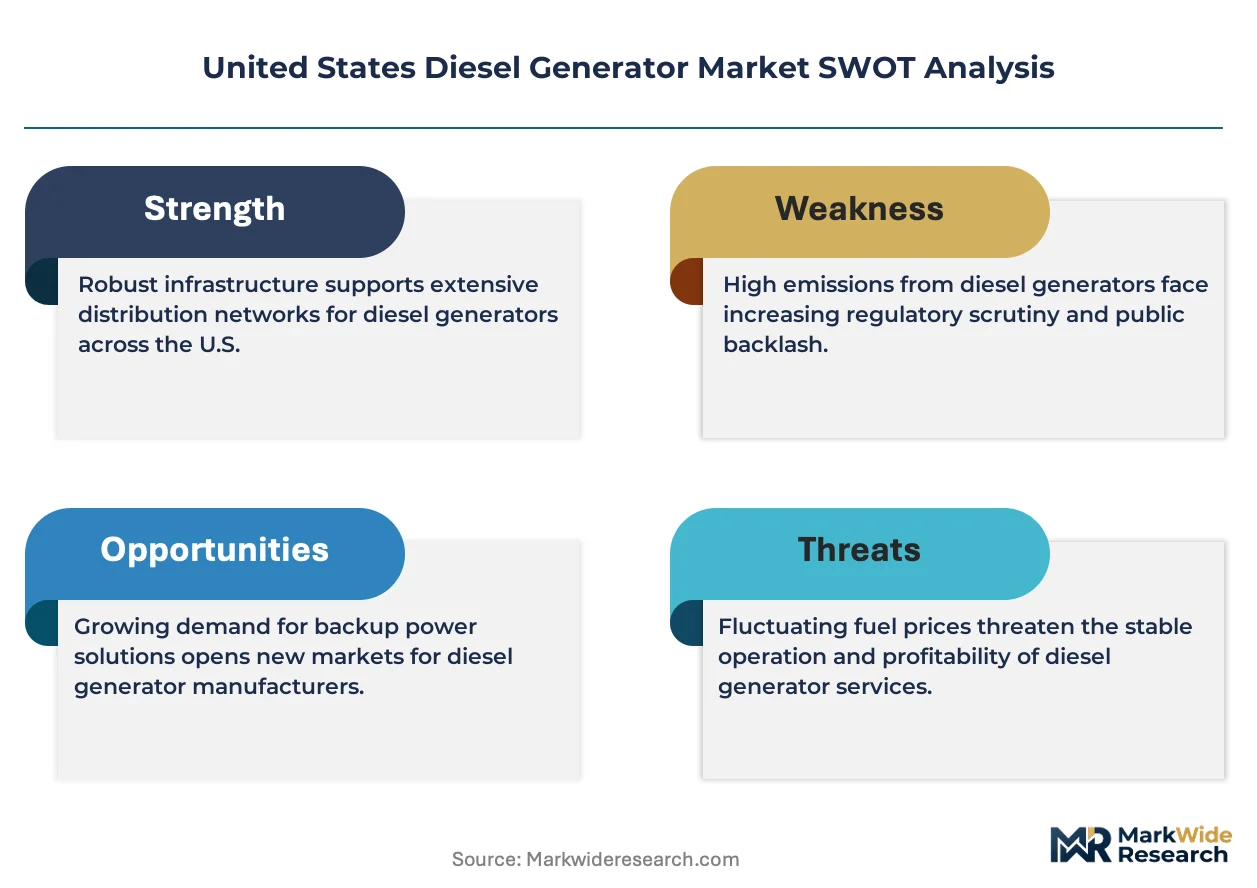
EPA Tier 4 Final emissions standards and OSHA workplace noise regulations jointly determine product certification requirements and manufacturing cost structures for equipment sold in the United States. The Federal Energy Regulatory Commission oversees interconnection standards that influence standby generator sizing for facilities participating in demand response programs. Stakeholders must monitor state-level renewable portfolio standards and accompanying grid stability mandates that could either extend diesel generator relevance or accelerate hybrid substitution depending on implementation timelines.
Market Dynamics
The United States diesel generator market is bifurcating around EPA Tier 4 Final compliance deadlines, forcing operators to choose between premium low-emission architectures for regulated environments and cost-optimized units for price-sensitive backup applications.
Growth Catalysts
- Data Center Cluster Expansion:Virginia's Loudoun County and Texas's Dallas-Fort Worth corridor are adding multi-megawatt backup fleets ahead of utility interconnection delays. Hyperscale operators are pre-positioning redundant capacity.
- EPA Tier 4 Final Enforcement:The Environmental Protection Agency's emissions deadlines are accelerating replacement cycles in healthcare and municipal segments. Non-compliant legacy units face operational restrictions in ozone non-attainment zones.
- Grid Instability in Industrial Midwest:Ohio, Michigan, and Indiana manufacturers are procuring prime power diesel systems as baseload alternatives. Aging transmission infrastructure and storm-related outages are driving on-site generation decisions.
Market Restraints
- Aftertreatment Cost Inflation:Selective catalytic reduction and diesel particulate filter systems have added substantial material cost to Tier 4 Final-compliant units. Engine block pricing now carries a permanent emissions premium.
- Domestic Engine Supply Concentration:Heavy-duty compression-ignition engine production concentrates among a handful of Midwest manufacturing facilities. Single-source dependencies create vulnerability to component shortages.
- Battery Storage Substitution:Lithium-ion battery energy storage systems are capturing short-duration backup applications under four hours. Data center operators are evaluating hybrid diesel-battery architectures for load smoothing.
Strategic Opportunities
- Containerized Modular Deployments:Pre-integrated skid-mounted and containerized generator packages are reducing site preparation timelines. Texas and Arizona utilities are standardizing on plug-and-play formats for rapid deployment.
- Demand Response Program Participation:The Federal Energy Regulatory Commission's Order 2222 is enabling aggregated generator fleets to bid into wholesale markets. Facility operators in PJM and ERCOT territories are retrofitting units for grid services.
- Hybrid Diesel-Renewable Integration:Synchronization controllers are blending diesel generation with solar and battery assets. Remote mining and telecom tower operators in the Mountain West are adopting microgrid architectures.
Industry Challenges
- Emissions Technician Shortage:Aftertreatment system diagnostics and urea infrastructure maintenance require specialized training. Dealer networks are competing for scarce EPA-certified service personnel.
- Site Permitting Complexity:Local air quality districts in California and Northeast states impose additional permitting layers beyond federal requirements. Project timelines extend by quarters for environmental impact assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Diesel Generator Market |
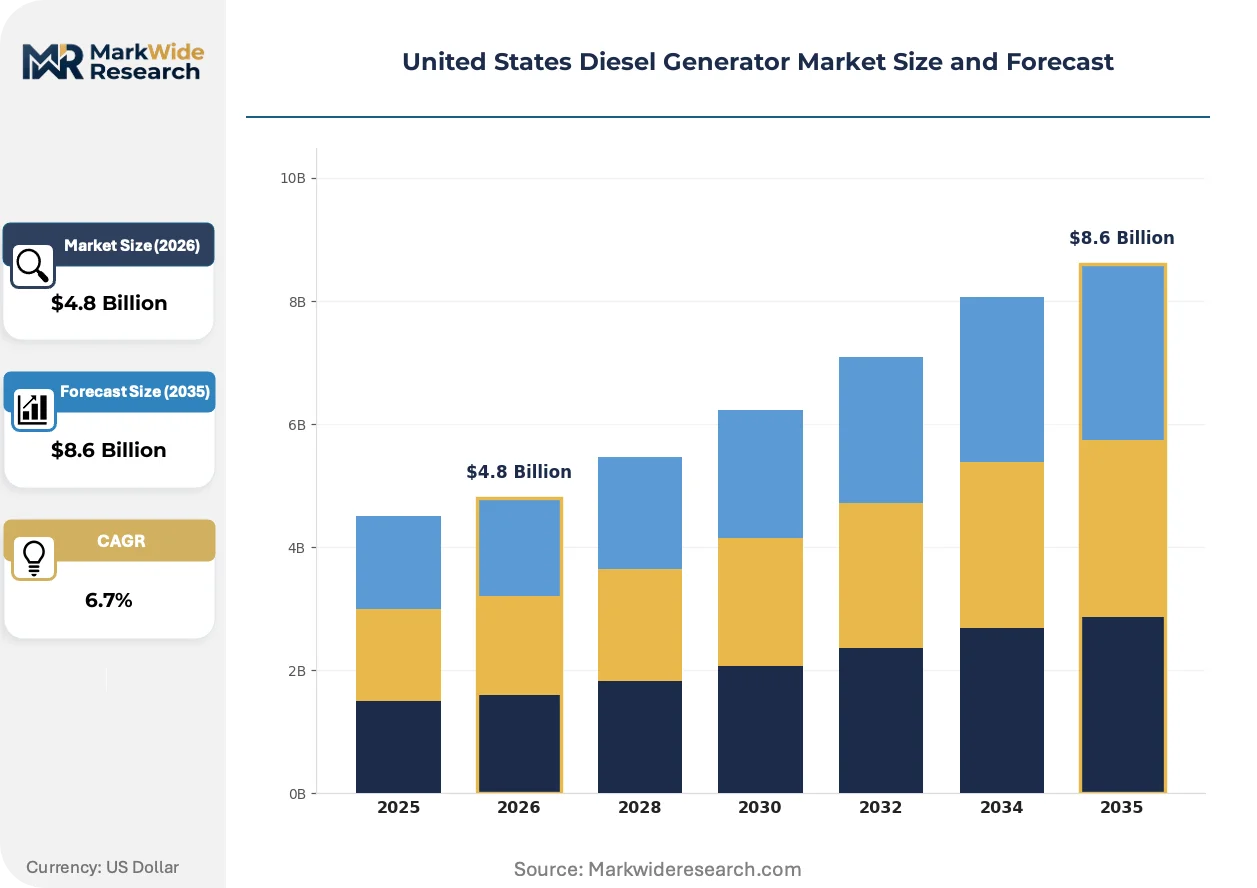
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Backup Power, Continuous Power, Prime Power, Off-Grid Power Power Rating: Below 100 kVA, 100-250 kVA, 251-500 kVA, Above 500 kVA End User: Residential, Commercial, Industrial, Healthcare Deployment: Portable, Stationary, Trailer-Mounted, Containerized |
| Companies Covered | Kohler Co, Briggs & Stratton Corporation, Caterpillar Inc, Doosan Corporation, MTU Onsite Energy, Cummins Inc, Atlas Copco AB, Mitsubishi Heavy Industries, Generac Holdings Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Diesel Generator Market Evolving Landscape
Digitalization of generator control systems is compressing commissioning timelines and enabling predictive maintenance models that reshape service revenue structures across the dealer network.
Advanced paralleling controllers and cloud-connected engine management systems are absorbing traditional switchgear functions into integrated power modules. Data center operators in Northern Virginia are specifying these architectures to reduce electrical room footprints. The technology is absorbing market share from conventional manual synchronization panels.
The Environmental Protection Agency's enforcement of Tier 4 Final standards for non-road engines is mandating selective catalytic reduction across the 75-750 horsepower range. Engine manufacturers have retooled production lines to accommodate aftertreatment packaging. The industrial prime power segment is absorbing the steepest cost increases as continuous-duty applications face the most stringent verification protocols.
Buying committees at healthcare and colocation facilities are consolidating vendor relationships around full-lifecycle service contracts. Traditional equipment-only transactions are ceding ground to bundled offerings that include fuel management, remote monitoring, and predictive parts replacement. This pattern is most pronounced in Texas and Florida markets where hurricane exposure elevates uptime requirements.
United States Diesel Generator Market Segmentation
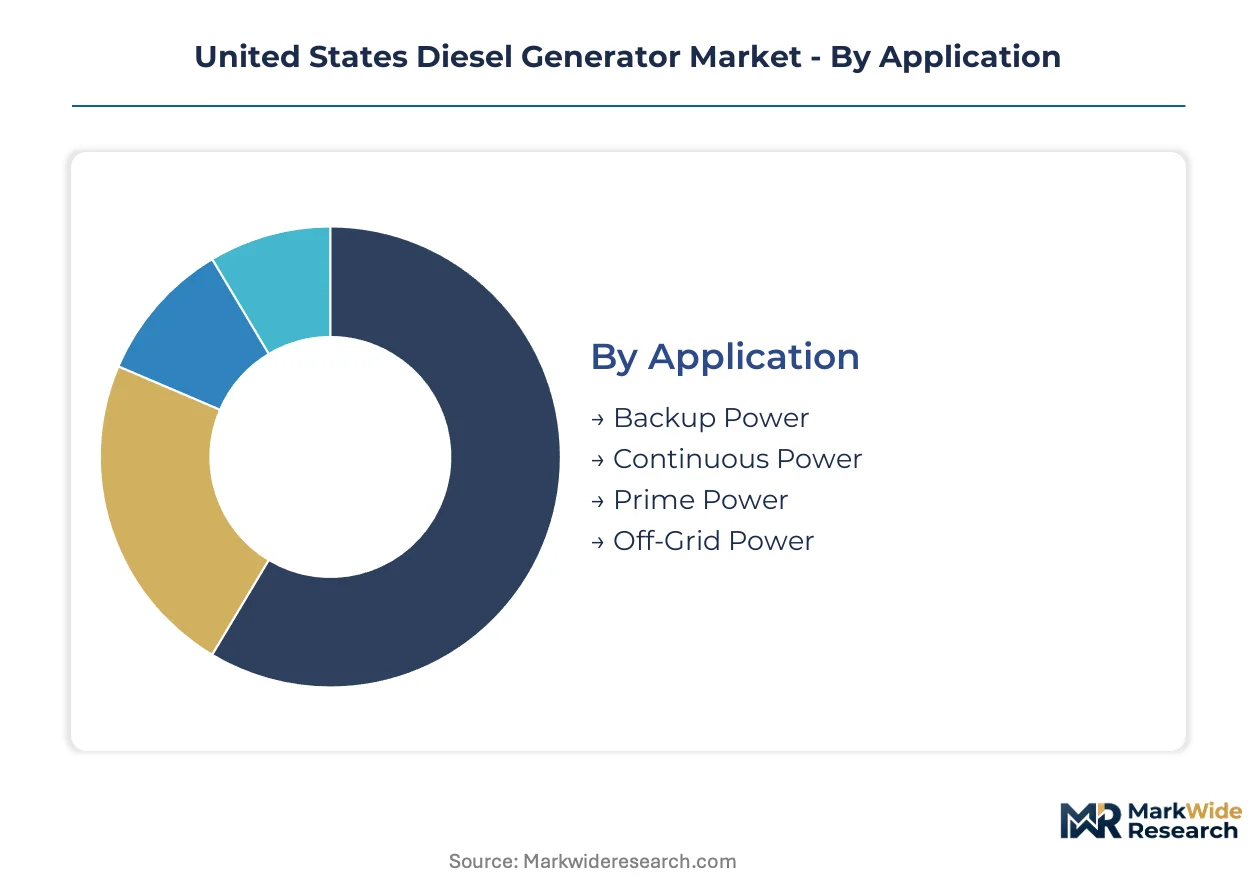
Segmentation in the United States diesel generator market reveals distinct procurement patterns across application intensity, power scale, and installation permanence. Buyers optimize specifications against EPA Tier 4 Final compliance costs, grid reliability exposure, and site preparation constraints.
Application:
Customization intensity varies sharply across this category, from highly specified continuous-duty architectures to standardized emergency backup units.
- Backup Power:Units designed for intermittent operation during grid failure, typically exercising weekly at partial load. Healthcare facilities in Texas and Virginia are expanding redundant backup fleets ahead of interconnection delays.
- Prime Power:Compression-ignition systems configured for unlimited annual operating hours as primary electricity source. Ohio and Indiana manufacturers are deploying these units where aging transmission infrastructure creates reliability gaps.
- Continuous Power:Baseload-rated generators engineered for constant operation with derated output for longevity. Remote mining operations in Nevada and Arizona specify these for off-grid extraction sites.
- Off-Grid Power:Standalone systems serving isolated loads without utility interconnection. Telecom tower operators across the Mountain West favor these for remote relay stations beyond distribution lines.
Leading the category by volume: Backup Power. Expanding most quickly: Prime Power.
Power Rating:
Cost tiers cluster around footprint efficiency tradeoffs, with mid-range bands capturing margin from buyers balancing portability against electrical room constraints.
- 251-500 kVA:Mid-scale architectures optimized for commercial buildings and light industrial plants where space efficiency outweighs sub-100 kVA mobility. Colocation facilities in Northern Virginia standardize on this band for floorplate optimization.
- Above 500 kVA:Heavy-duty industrial units requiring engineered foundations and dedicated fuel farms. Hyperscale data centers in Dallas-Fort Worth are pre-positioning multi-megawatt blocks of this capacity.
- Below 100 kVA:Compact single-phase or small three-phase sets for residential and small commercial standby. Hurricane-exposed Florida homeowners drive replacement demand for these units.
- 100-250 kVA:Transitional range serving retail chains and municipal buildings with moderate load profiles. Regional hospital networks in the Midwest specify these for departmental redundancy.
Capturing concentrated margin: 251-500 kVA. Gaining share fastest: Above 500 kVA.
End User:
Customer type determines service bundling intensity, with industrial and healthcare buyers demanding full-lifecycle contracts versus transactional equipment-only sales.
- Healthcare:Mission-critical installations requiring NFPA 110 Level 1 compliance and 10-second automatic transfer. Hospital systems in California and the Northeast face the steepest EPA Tier 4 Final replacement cycles.
- Industrial:Manufacturing and processing plants procuring prime or continuous power for production protection. Automotive suppliers across Michigan are adding on-site generation as grid stability concerns mount.
- Commercial:Office buildings, retail centers, and hospitality properties specifying backup for revenue protection. Texas grocery chains are retrofitting stores with extended-runtime fuel systems post-winter storm disruptions.
- Residential:Single-family and small multi-family installations, predominantly below 100 kVA. Standby generator penetration remains concentrated in hurricane and tornado corridors.
Dominating service contract bundling: Healthcare. Steepest procurement acceleration: Industrial.
Deployment:
Supply concentration favors pre-integrated formats that compress site preparation timelines versus field-erected traditional installations.
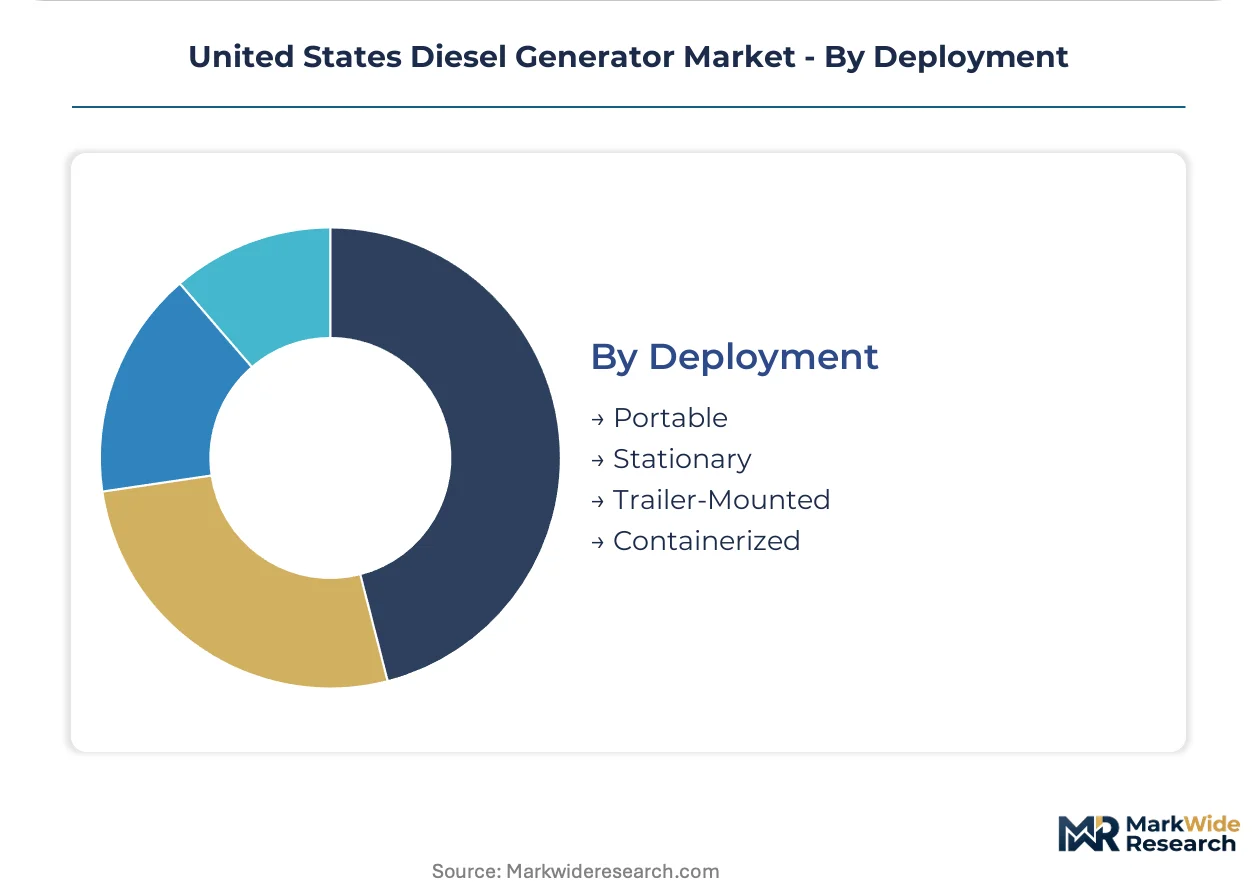
- Containerized:Pre-integrated power modules housed in ISO-standard enclosures with built-in fuel tanks and ventilation. Arizona and Texas utilities are standardizing on these for rapid emergency deployment.
- Stationary:Permanent installations on poured concrete pads with fixed electrical connections. Large industrial facilities in the Midwest continue specifying these for decades-long asset lifecycles.
- Trailer-Mounted:Mobile units on highway-legal chassis for construction, events, and emergency response. Rental fleets across the Southeast maintain high utilization of this format.
- Portable:Small wheeled or skid units for temporary power at job sites and outdoor events. Contractor demand in the Sun Belt drives seasonal volume spikes.
Compressing installation timelines most aggressively: Containerized. Maintaining largest installed base: Stationary.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Loudoun County, Virginia anchors the nation's diesel generator procurement surge, with hyperscale data center operators pre-positioning multi-megawatt backup fleets ahead of utility interconnection bottlenecks. EPA Tier 4 Final enforcement timelines and state-level grid reliability mandates are reshaping regional deployment patterns across the United States.
Texas
Data center construction in the Dallas-Fort Worth corridor is accelerating backup power procurement as ERCOT grid instability persists. The Texas Commission on Environmental Quality enforces state implementation plans for ozone non-attainment zones that affect generator permitting timelines. Houston industrial facilities are retrofitting prime power systems following winter storm Uri disruptions to baseload reliability.
Virginia
Northern Virginia's data center alley commands the densest concentration of above-500 kVA generator deployments in North America. The Virginia Department of Environmental Quality administers air quality permits that Tier 4 Final compliance deadlines have complicated. Loudoun and Prince William counties are experiencing 18-month lead times for large-scale generator installations due to electrical infrastructure backlogs.
Ohio-Michigan-Indiana Corridor
Automotive suppliers and heavy manufacturers across this industrial Midwest region are procuring prime power diesel systems as grid reliability concerns mount. The Ohio Environmental Protection Agency enforces state-specific permitting requirements beyond federal EPA standards. Detroit-area stamping plants and Cleveland steel processors are specifying continuous-duty architectures for production protection.
California
Healthcare and municipal buyers face the steepest Tier 4 Final replacement cycles due to the state's stringent air quality district layering. The California Air Resources Board imposes additional emissions verification protocols beyond federal requirements. Sacramento and Fresno hospital systems are consolidating vendor relationships around full-lifecycle service contracts to manage compliance complexity.
Florida
Hurricane exposure is driving residential and commercial standby generator penetration across the peninsula. The Florida Department of Environmental Protection coordinates with county air quality districts on generator permitting post-disaster deployments. Miami-Dade grocery chains and Tampa healthcare networks are installing extended-runtime fuel systems following recent storm season disruptions.
United States Diesel Generator Market Competitive Landscape
Capital-heavy integrated manufacturers compete with asset-light assembly specialists across the United States diesel generator market. The vendor base concentrates around engine-alternator integration capabilities, with above-500 kVA industrial tiers favoring in-house engine production while sub-250 kVA segments accommodate outsourced powertrain sourcing. Three strategic archetypes dominate: integrated engine-generator builders, alternator-assembly specialists, and rental fleet operators with captive service networks. Competitive positioning hardens through Tier 4 Final certification depth and dealer service territory density rather than manufacturing scale alone.
Within the integrated manufacturing tier, Caterpillar Inc and Cummins Inc anchor competitive positioning through captive engine production and extensive dealer infrastructure. Kohler Co represents the premium stationary backup segment with concentrated presence in healthcare and residential applications. These three companies exemplify divergent strategic postures: Caterpillar through industrial-scale prime power dominance, Cummins through broad channel coverage across stationary and mobile configurations, and Kohler through specification intensity in mission-critical installations.
| Leading Market Players |
|---|
| Kohler Co |
| Briggs & Stratton Corporation |
| Caterpillar Inc |
| Doosan Corporation |
| MTU Onsite Energy |
| Cummins Inc |
| Atlas Copco AB |
| Mitsubishi Heavy Industries |
| Generac Holdings Inc |
| Others |
Value Network & Pricing Analysis
Captive engine production at Caterpillar and Cummins anchors both supply security and pricing power across the United States diesel generator market, with in-house manufacturing of heavy-duty compression-ignition engines insulating integrated builders from component volatility while commanding premium positioning in above-500 kVA tiers.
Pricing Analysis
Uptime guarantees and lifecycle cost predictability anchor value-based pricing for Tier 4 Final-compliant units, with EPA certification grade and after-sales service bundling driving price differentiation between premium integrated manufacturers and assembly specialists. Cost compression in sub-250 kVA commodity tiers is intensifying because outsourced powertrain sourcing erodes margin protection. Healthcare and data center buyers show lowest price sensitivity due to mission-critical uptime requirements, while residential and small commercial segments prioritize capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers across Texas, Ohio, and Virginia maintain hub-and-spoke patterns that compress delivery timelines for containerized generator packages. Engine block casting and machining concentrates in the United States, Mexico, and Germany, while alternator windings and control electronics source from China and South Korea. Single-source vulnerability in selective catalytic reduction substrate supply creates exposure to emissions component shortages. Distribution runs through authorized dealer networks with captive service territories rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States diesel generator market reads as supply-constrained, with EPA-certified emissions technician scarcity propping pricing power for incumbent service networks and extending lead times for Tier 4 Final-compliant installations.
For Market Incumbents: Acquire regional service dealerships with EPA-certified technician rosters to consolidate aftermarket control against battery storage substitution threats. Expand captive urea distribution infrastructure in Texas and Virginia data center corridors. Backward integration into aftertreatment component sourcing reduces exposure to single-source SCR substrate vulnerability. For New Entrants and Emerging Players: EPA Tier 4 Final enforcement in California and Northeast ozone non-attainment zones opens a window for specialized compliance retrofit services targeting legacy healthcare and municipal fleets. Target trailer-mounted rental fleets in hurricane-exposed Southeast markets where asset-light models bypass capital intensity of stationary installations. Pursue demand response aggregation partnerships with ERCOT-registered facility operators as a grid-services entry angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated engine manufacturers seeking alternator-assembly capabilities. The five-to-ten year viability window hinges on hybrid diesel-battery architecture adoption curves. Acquisition target archetype: regional dealers with dense EPA-certified technician networks and long-term healthcare service contracts. Monitor lithium-ion battery cost trajectories as the inflection signal for backup power substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Tier 4 Final Certification Investment | Unlocks access to regulated California and Northeast healthcare markets under CARB and state air quality district mandates. |
| Demand Response Grid Services Integration | Enables FERC Order 2222 participation for aggregated generator fleets bidding into PJM and ERCOT wholesale markets. |
| Containerized Modular Platform Development | Compresses Arizona and Texas utility deployment timelines through pre-integrated ISO-standard power modules. |
| Hybrid Diesel-Battery Architecture Launch | Captures data center load-smoothing applications where lithium-ion substitution threatens pure diesel backup. |
| Regional Service Network Acquisition | Consolidates scarce EPA-certified technician capacity against emissions diagnostic skill shortages. |
Research Methodology
Trade association filings, EPA emissions certification databases, and FERC interconnection records formed the secondary backbone, supplemented by primary interviews with data center facility managers, healthcare engineering directors, industrial plant maintenance heads, and authorized generator dealer principals. Bottom-up and top-down triangulation validated installation volume estimates against engine production disclosures and regional air quality permit filings.
Bottom-up modeling of unit shipments across power rating bands and application categories was cross-checked against top-down market value reconstruction. Segmentation dimensions included deployment format, end-user vertical, and EPA compliance tier across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles and regulatory enforcement timelines, with grid reliability indices and data center construction permits serving as demand-side forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for lithium-ion battery cost reduction would alter the outlook for diesel generator substitution rates. Forecasts reflect documented assumptions regarding EPA enforcement consistency and ERCOT grid stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
East Africa Diesel Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Europe Generator Sets Market
Generators
Digital Inverter Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
China Gas Generator Market
Generators
Middle-East and Africa Diesel Generator Market
Generators
South America Generator Sets Market
Generators
Asia-Pacific Gas Generator Market
Generators
Gasoline Generator Market
Generators
Commercial Standby Generator Sets Market
Generators
Containerized Solar Generators Market
Generators
Electric Generators Market
Generators
Africa Portable Generator Market
Generators
Nuclear Turbine Generators Market
Generators
Southeast Asia Portable Generator Market