
 India Generator Sets Market | 2026-2036
India Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
India Generator Sets Market Foresight
Tier-4 emission-compliant generator sets is rotating the India generator sets market toward higher-specification equipment. Cummins India leverages its integrated manufacturing footprint in Pune to dominate the high-capacity industrial segment. Kirloskar Oil Engines Limited anchors the domestic mid-range diesel category through its extensive dealer network across tier-2 and tier-3 cities. Mahindra Powerol differentiates with compact gas-powered units designed for urban commercial installations where noise and emission restrictions tighten.
Generator sets are electromechanical devices that convert fuel energy into electrical power through internal combustion engines coupled with alternators, typically rated by output capacity in kVA and governed by emission standards for particulate matter and NOx. Diesel generators continue to occupy the largest installed base across Indian industrial corridors, though gas generators are gaining share in metropolitan areas where PNG infrastructure expands. The above 20 kVA capacity band captures the dominant share of revenue as data centers, cement plants, and textile mills require continuous heavy-load backup power.
BIS certification mandates and CEA grid-interconnection standards shape product design and market access for generator set manufacturers operating in India. The country's national environmental regulator enforces progressive emission norms that phase out older diesel engine platforms and elevate compliance costs for smaller fabricators. Stakeholders must monitor state-level renewable integration mandates that could redefine the economics of hybrid generator configurations against pure fossil-fuel alternatives.
Market Dynamics
BIS emission norms for diesel engines are compressing the addressable market for conventional generator sets while elevating compliance costs across the supply base. Manufacturers must now engineer dual-fuel and hybrid architectures to retain product-market fit as regulatory thresholds tighten progressively.
Growth Catalysts
- Data Center Expansion:Hyperscale operators in Maharashtra and Karnataka are commissioning captive power installations exceeding 50 MW per campus. Grid reliability fluctuations make diesel and gas backup capacity non-negotiable for SLA compliance.
- CEA Grid-Interconnection Standards:Mandates for synchronized backup systems in critical infrastructure are forcing facility managers to upgrade legacy generator sets. Compliance deadlines accelerate replacement cycles across hospitals, airports, and telecom exchanges.
- PNG Infrastructure Rollout:Piped natural gas networks in Delhi-NCR, Mumbai, and Bengaluru enable gas generator deployment where diesel restrictions bite hardest. Urban commercial complexes are switching fuel types to secure municipal operating permits.
Market Restraints
- Engine Platform Obsolescence:BIS Stage-V emission deadlines render older diesel engine designs economically unviable for continued production. Smaller fabricators lack R&D capital to certify new powertrain architectures.
- Import Dependency for Electronic Fuel Injection:Precision injection systems and after-treatment components concentrate among European and Japanese suppliers. Rupee volatility elevates landed costs for Tier-4 compliant subsystems.
- Gas Generator Fuel Security:PNG supply interruptions during peak winter months undermine reliability claims for gas-only installations. Dual-fuel capability adds capital cost without guaranteed fuel availability.
Strategic Opportunities
- Hybrid Solar-Diesel Configurations:Rajasthan and Gujarat solar parks paired with generator sets offer round-the-clock power for agro-processing units. PLI scheme incentives for renewable manufacturing extend to integrated hybrid systems.
- Tier-2 City Dealer Networks:Uttar Pradesh and Madhya Pradesh industrial corridors remain underserved for service-capable distribution. Local assembly partnerships can compress lead times and capture replacement demand.
- Biogas Generator Adaptation:Food processing and dairy clusters in Punjab and Haryana generate feedstock for on-site biogas production. Engine modifications for variable methane content open captive fuel economics.
Industry Challenges
- Emission Certification Timeline Compression:BIS testing protocols for new engine families extend 18-24 months. Product launch schedules misalign with construction season demand windows.
- After-Sales Technician Scarcity:Electronic engine management and exhaust after-treatment systems require diagnostic capabilities absent from traditional mechanic training. Field service quality gaps erode brand equity in remote installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Generator Sets Market |
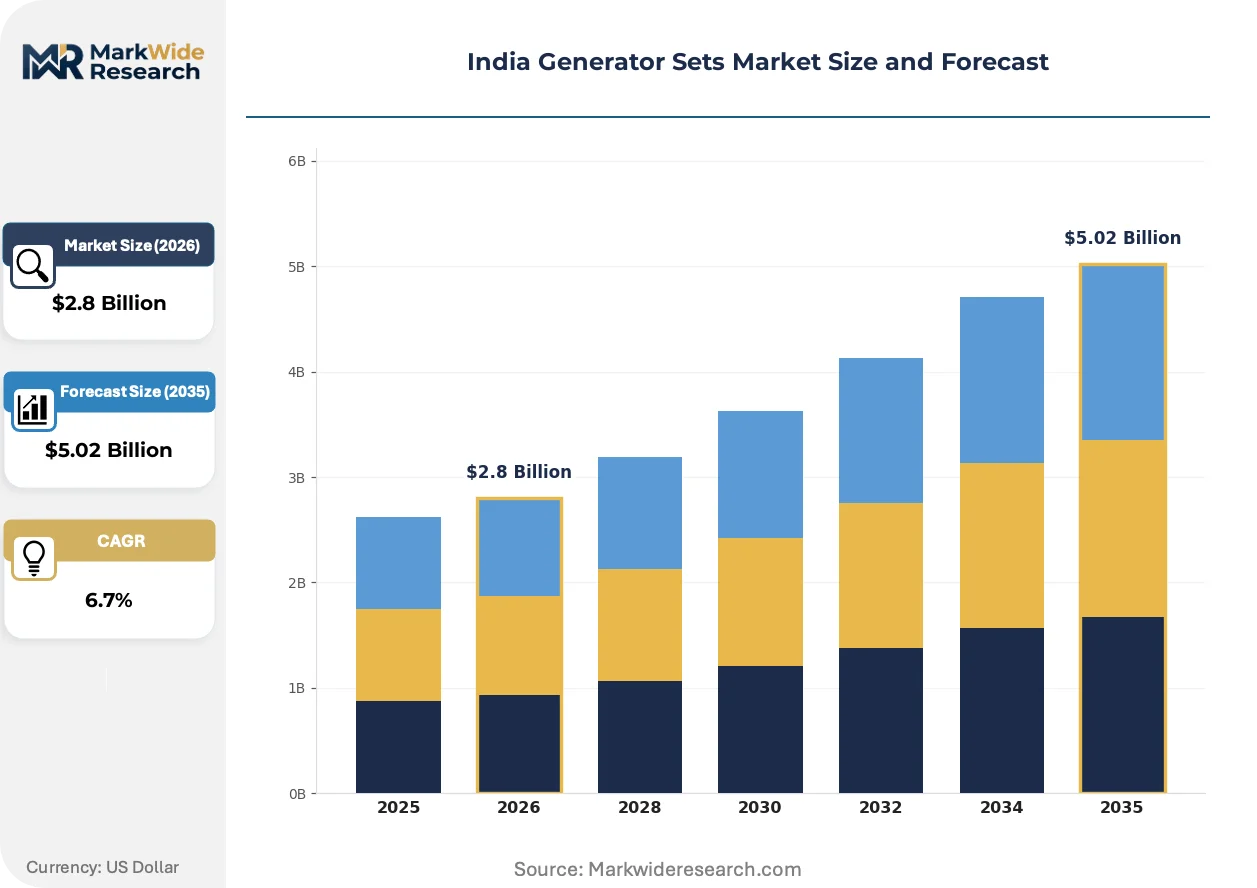
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Hybrid Generators, Portable Generators Application: Residential, Commercial, Industrial, Agricultural End User: OEMs, Construction Firms, Data Centers, Retail Capacity: 1-5 kVA, 5-10 kVA, 10-20 kVA, Above 20 kVA |
| Companies Covered | Cummins India, Kirloskar Oil Engines Limited, Mahindra Powerol, Ashok Leyland, Greaves Cotton Limited, Caterpillar Inc., MTU Onsite Energy, Perkins Engines Company Limited, Honda Siel Power Products Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Generator Sets Market Shifts & Advancements
Diesel-gas hybrid architectures and intelligent load management systems are redefining generator set value propositions. Equipment buyers now prioritize total cost of ownership over upfront capital expenditure, forcing manufacturers to embed predictive maintenance and remote monitoring as standard features.
Modular containerized generator sets is fragmenting the market for fixed-installation equipment. Data center operators in Hyderabad and Chennai are deploying skid-mounted, factory-tested power modules that slash on-site commissioning from weeks to days. This standardization is compressing margins for traditional engineering-procurement-construction contractors who previously captured integration value.
BIS Stage-V emission norms are eliminating mechanically governed diesel engines from the certified product list. Engine manufacturers must integrate electronic control units and selective catalytic reduction hardware that elevates bill-of-material costs substantially. The above-20 kVA industrial segment bears the heaviest compliance burden as particulate matter limits tighten fastest for high-displacement powertrains.
Telecom tower operators are unbundling generator ownership from maintenance contracts, shifting toward power-as-a-service arrangements. Infrastructure leasing firms in western India now procure generator sets directly while outsourcing operations to specialized fleet managers. This separation of asset and service accountability is visible across Maharashtra and Gujarat where tower densification strains traditional dealer-service models.
India Generator Sets Market Segmentation
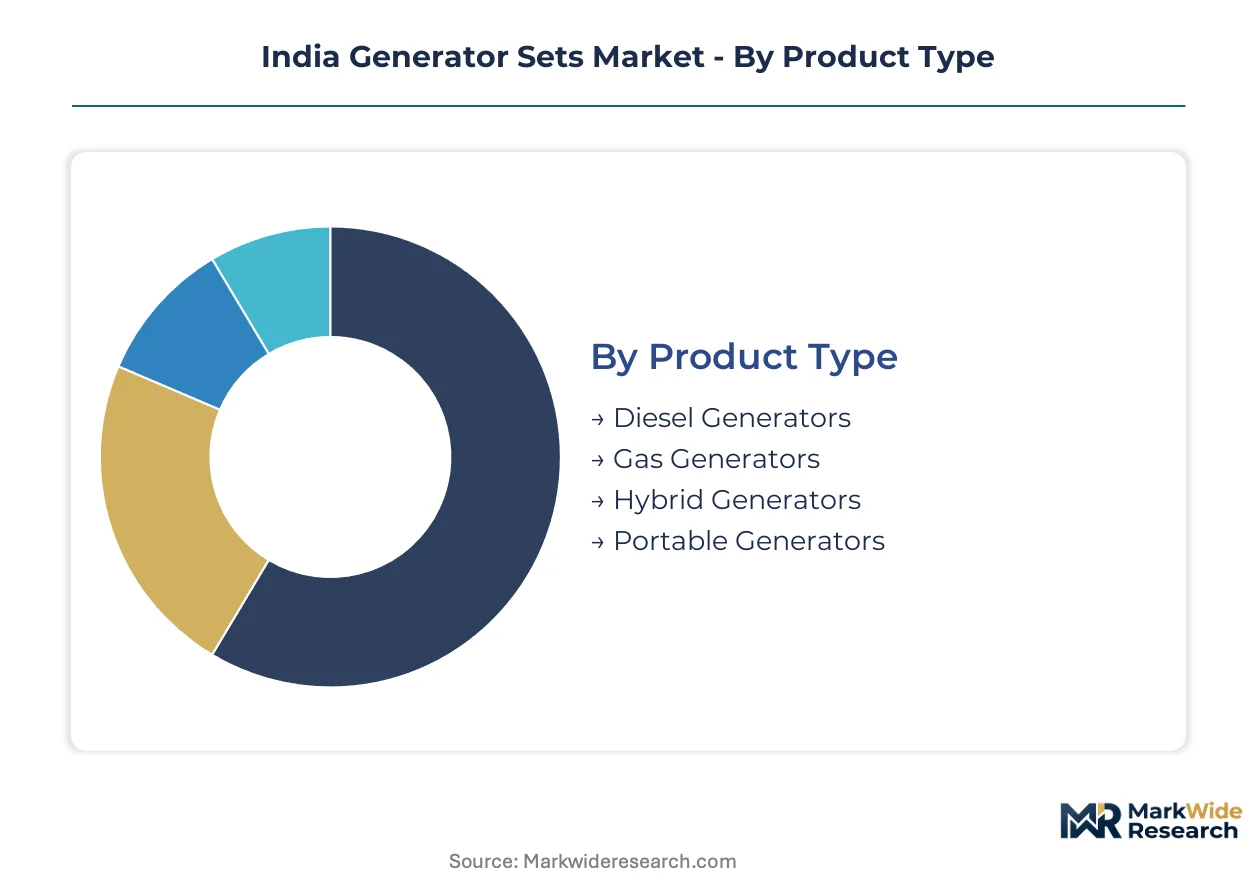
Segmentation in the India generator sets market reveals how BIS emission norms and PNG infrastructure expansion are fragmenting demand across fuel types and capacity bands. Manufacturers must align product portfolios with state-level regulatory deadlines and end-use reliability requirements.
Product Type:
Margin pools concentrate in gas and hybrid configurations where BIS Stage-V compliance costs elevate pricing power for certified suppliers.
- Diesel Generators:Internal combustion engines running on high-speed diesel, governed by mechanical or electronic fuel injection systems rated by kVA output. Cement plants and textile mills across Maharashtra and Gujarat maintain diesel captive power for grid-failure scenarios where PNG pipelines remain absent. BIS Stage-V particulate matter limits are compressing the addressable market for mechanically governed units.
- Gas Generators:Spark-ignition engines optimized for piped natural gas or compressed natural gas, featuring lean-burn combustion architectures. Data centers in Bengaluru and Mumbai deploy gas sets where municipal permits restrict diesel runtime hours. PNG infrastructure rollout in Delhi-NCR is accelerating replacement demand from diesel baseline.
- Hybrid Generators:Integrated diesel-solar or gas-solar systems with battery buffering and intelligent load management. Rajasthan agro-processing units pair solar parks with generator backup for round-the-clock operations.
- Portable Generators:Compact single-phase units below 5 kVA, typically air-cooled and pull-start operated. Construction contractors in tier-2 cities procure portable sets for site electrification where grid extension lags.
Diesel generators hold installed capacity across industrial corridors. Gas generators are rotating up the share rankings in metropolitan areas with reliable PNG networks.
Application:
Volume concentration tilts toward industrial installations where continuous-duty ratings and synchronized grid-interconnection justify premium equipment specifications.
- Industrial:Heavy-duty three-phase generator sets rated for prime power or standby duty in manufacturing facilities. Cement plants in Madhya Pradesh and steel rolling mills in Jharkhand require above-20 kVA units with automatic mains failure panels. CEA grid-interconnection standards mandate synchronized backup for critical process loads.
- Commercial:Mid-range units serving hotels, hospitals, and retail complexes where noise restrictions and emission limits tighten fastest. Mumbai commercial complexes face municipal operating permit conditions favoring gas over diesel.
- Residential:Small-capacity single-phase sets for apartment backup and villa installations. Pune and Hyderabad gated communities deploy 5-10 kVA units for elevator and common-area backup.
- Agricultural:Irrigation pump sets and cold-chain equipment in Punjab and Haryana dairy clusters. Biogas adaptation is gaining traction where feedstock economics support captive fuel production.
Industrial applications dominate revenue. Commercial installations are climbing the fastest as urban emission restrictions displace legacy diesel capacity.
End User:
Procurement authority is fragmenting as telecom tower operators unbundle asset ownership from operations contracts.
- Data Centers:Hyperscale operators in Maharashtra and Karnataka commissioning captive power exceeding 50 MW per campus. SLA compliance mandates N+1 redundancy with synchronized generator sets.
- Construction Firms:Project-based procurement of portable and skid-mounted units for site electrification. Highway and metro contractors in Uttar Pradesh rotate equipment across multiple sites.
- OEMs:Generator set manufacturers integrating engines and alternators for branded product lines. Pune-based assemblers source powertrains from domestic and import suppliers.
- Retail:Mall operators and supermarket chains procuring backup power for refrigeration and POS continuity. Tier-2 city retail expansion is stretching service network coverage.
Data centers anchor premium capacity demand. Construction firms are expanding most quickly as infrastructure investment accelerates across central Indian states.
Capacity:
Cost tier stratification separates premium electronic-governance units in high-kVA bands from mechanically governed economy equipment below 10 kVA.
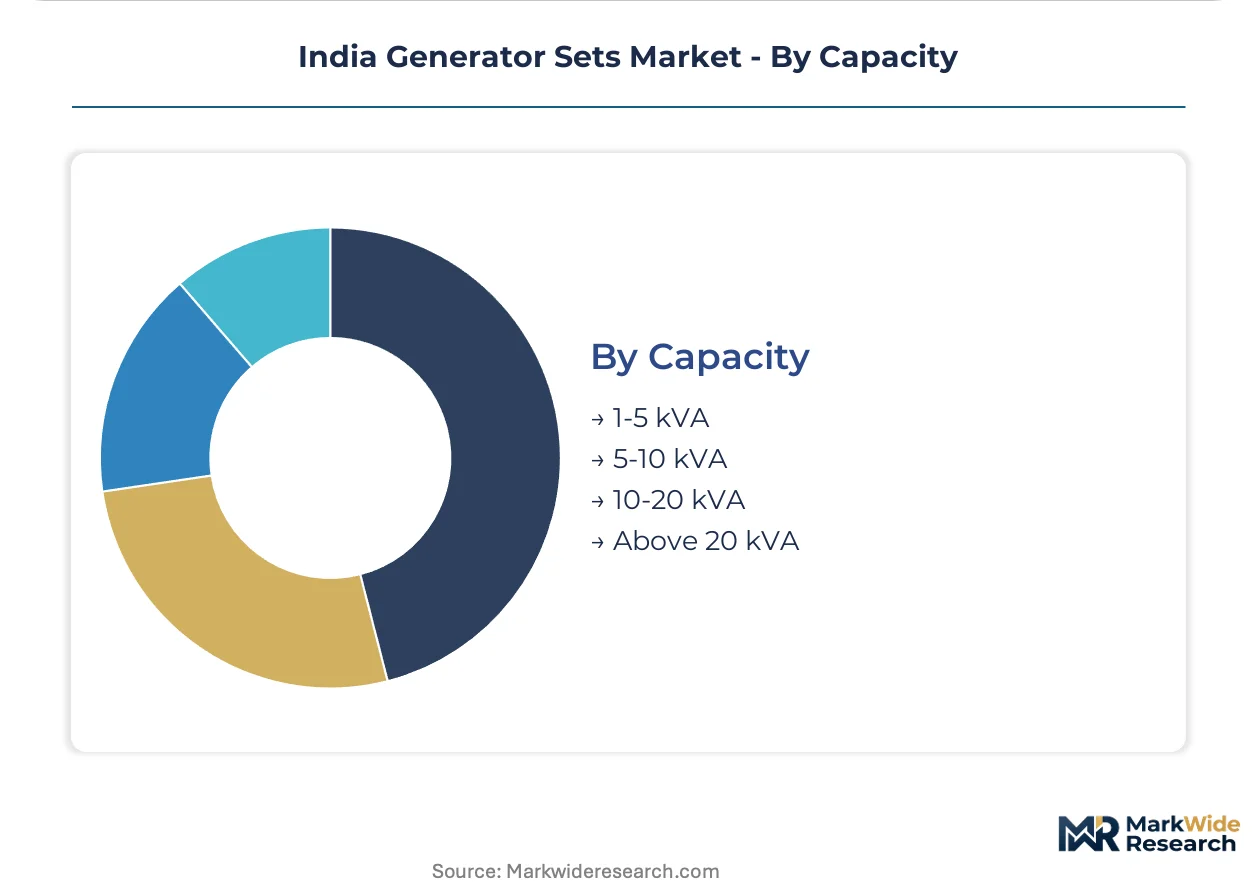
- Above 20 kVA:Industrial-grade three-phase sets with electronic engine management and exhaust after-treatment. Textile mills and pharmaceutical plants in Gujarat and Tamil Nadu require continuous-duty ratings. BIS Stage-V compliance costs hit hardest in this displacement range.
- 10-20 kVA:Commercial and light-industrial applications with manual or automatic transfer switching. Hospitals and mid-size hotels in tier-2 cities standardize on this band for cost-optimized redundancy.
- 5-10 kVA:Residential complexes and small commercial installations with single-phase or three-phase output options. Dealer network availability determines brand selection in remote districts.
- 1-5 kVA:Portable and stationary units for household backup and small shop operations. Price sensitivity is highest; unbranded fabricators compete on upfront capital cost.
Above 20 kVA holds installed capacity. 10-20 kVA is rotating up the share rankings as commercial construction outpaces heavy industrial greenfield investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's generator sets trade flows reveal a structural deficit in high-specification electronic fuel injection systems and exhaust after-treatment components, with domestic manufacturers importing precision subsystems from European and Japanese suppliers to meet BIS Stage-V compliance deadlines.
Maharashtra
Data center operators in Mumbai and Pune are commissioning captive power installations exceeding 50 MW per campus as grid reliability fluctuates during monsoon seasons. CEA grid-interconnection standards mandate synchronized backup systems for critical infrastructure, accelerating replacement cycles across hospitals and telecom exchanges. The Mumbai-Pune industrial corridor anchors premium above-20 kVA demand from cement plants and pharmaceutical facilities.
Gujarat
Textile mills and chemical processing plants in Ahmedabad and Vadodara require continuous-duty diesel backup where PNG pipeline networks remain underdeveloped. BIS emission norms are compressing the addressable market for mechanically governed units, pushing fabricators toward electronic engine management architectures. The Dahej Special Economic Zone concentrates heavy industrial load requirements that justify synchronized generator configurations.
Karnataka
Hyperscale data center campuses in Bengaluru are driving gas generator adoption where municipal permits restrict diesel runtime hours. PNG infrastructure expansion in the Bengaluru metropolitan region enables fuel-switching for commercial complexes seeking operating licenses. The Electronics City and Whitefield IT corridors generate concentrated demand for N+1 redundant backup power systems.
Tamil Nadu
Automotive component manufacturers in Chennai and Coimbatore maintain diesel captive power for grid-failure scenarios despite tightening emission restrictions. The state's renewable integration mandates are redefining hybrid generator economics against pure fossil-fuel alternatives for textile processing clusters. Sriperumbudur and Oragadam industrial belts require automatic mains failure panels for continuous manufacturing operations.
Delhi-NCR
Commercial complexes and retail malls across Gurugram and Noida are switching from diesel to gas generators to secure municipal operating permits under air quality regulations. PNG network reliability concerns during peak winter months sustain demand for dual-fuel capability despite elevated capital costs. The region's construction boom stretches service network coverage for mid-range 10-20 kVA installations.
India Generator Sets Market Competitive Landscape
Concentration sits with integrated engine-alternator assemblers who control certification timelines and captive component sourcing. The vendor base stratifies across three tiers: multinational powertrain specialists with domestic manufacturing footprints, domestic engine houses with extensive dealer networks, and regional fabricators serving price-sensitive portable segments. Strategic moves center on dual-fuel architecture development and Tier-2 city distribution partnerships.
Among multinational assemblers, Cummins India anchors the high-capacity industrial segment through its Pune manufacturing footprint. Kirloskar Oil Engines Limited exemplifies the domestic mid-range diesel category with dealer penetration across tier-2 and tier-3 cities. Mahindra Powerol occupies a position in compact gas-powered configurations designed for urban commercial installations where noise and emission restrictions tighten.
| Leading Market Players |
|---|
| Cummins India |
| Kirloskar Oil Engines Limited |
| Mahindra Powerol |
| Ashok Leyland |
| Greaves Cotton Limited |
| Caterpillar Inc. |
| MTU Onsite Energy |
| Perkins Engines Company Limited |
| Honda Siel Power Products Limited |
| Others |
Supply & Pricing Matrix
Eighteen-month certification timelines for BIS Stage-V compliant engine families compress pricing power for manufacturers while elevating inventory carrying costs for electronic fuel injection subsystems sourced from European and Japanese suppliers. This lead-time rigidity concentrates margin pressure on domestic fabricators lacking captive component production.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the India generator sets market. Price differentiation rests on BIS certification grade and after-sales service bundling, with Tier-4 compliant electronic-governance units commanding substantial premiums over mechanically governed economy alternatives. Cost compression in the below-10 kVA portable segment is intensifying because unbranded fabricators compete aggressively on upfront capital cost. Construction contractors exhibit highest price sensitivity, while data center operators prioritize total cost of ownership and SLA compliance over acquisition expenditure.
Supply Chain Analysis
Inventory carrying costs for precision fuel injection systems and selective catalytic reduction hardware extend lead times and elevate working capital requirements for domestic assemblers. Manufacturing concentration centers on India, Germany, and Japan for engine management systems, while alternator wound components draw from China and South Korea. Single-source vulnerability persists for electronic control units where European suppliers dominate certified product lines. Distribution runs through authorized dealer networks for industrial installations and direct procurement by infrastructure leasing firms for telecom tower deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate battery energy storage systems and grid-scale solar-plus-storage configurations that threaten standby generator economics in commercial segments. Substitution risk from declining lithium-ion costs demands defensive positioning around hybrid architectures and service bundling.
For Market Incumbents: Fortify dealer network control in tier-2 industrial corridors of Uttar Pradesh and Madhya Pradesh where service capability gaps erode competitor positioning. Deepen backward integration into alternator manufacturing to offset rupee volatility on imported wound components. Invest in dual-fuel certification pipelines ahead of BIS Stage-V deadlines to defend margin position against gas-only specialists.
For New Entrants and Emerging Players: Anchor in biogas generator adaptation for Punjab and Haryana dairy clusters where captive feedstock economics bypass PNG infrastructure constraints. Target agro-processing units in Rajasthan seeking solar-hybrid configurations under PLI scheme incentives. Pursue power-as-a-service contracting models that separate asset ownership from operations for telecom tower operators in western India.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because emission certification barriers and R&D capital requirements are eliminating smaller fabricators unable to fund Stage-V compliance. Acquisition candidates with established BIS certification pipelines and tier-2 distribution footprints offer defensive positioning. Monitor PNG network reliability metrics in Delhi-NCR and Mumbai as inflection indicator for gas generator replacement velocity against diesel baseline.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Architecture Development | Enables compliance with BIS Stage-V norms while preserving diesel backup option where PNG supply interrupts. |
| Tier-2 City Distribution Partnership | Compresses lead times for replacement demand in Uttar Pradesh and Madhya Pradesh industrial corridors. |
| Hybrid Solar-Diesel System Integration | Captures PLI scheme incentives for renewable manufacturing while serving Rajasthan agro-processing round-the-clock power needs. |
| Predictive Maintenance Platform Deployment | Addresses after-sales technician scarcity through remote diagnostics for electronic engine management systems. |
| Biogas Engine Certification Investment | Opens captive fuel economics for Punjab and Haryana dairy clusters with variable methane content feedstock. |
Research Methodology
Desk research of BIS certification databases, CEA grid-interconnection standards, and PNG infrastructure rollout reports preceded structured interviews with generator set manufacturing executives, aftermarket service heads, data center facility managers, and tier-2 city distribution partners. Secondary validation drew from customs trade data, engine manufacturer technical bulletins, and state-level renewable integration policy documents. Bottom-up capacity installation estimates triangulated against top-down industrial power demand projections.
Variance decomposition across fuel type, capacity band, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling against BIS compliance deadline phasing and PNG network expansion trajectories. Forecast inputs incorporated data center capex pipelines, cement plant captive power replacement cycles, and telecom tower densification rates.
Material uncertainties — BIS testing protocol delays, rupee volatility on electronic component imports, and state-level renewable mandate acceleration — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Halogenerator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Kuwait Diesel Gensets Market
Generators
Generator Sets Market
Generators
Generator Rental Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Gas Generator Market
Generators
Power Generator Rental Market
Generators
Construction Portable Generators Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Portable Inverter Generators Market
Generators
East Africa Diesel Generator Market
Generators
United States Diesel Generator Market
Generators
Tanzania Diesel Generator Market
Generators
China Gas Generator Market
Generators
Generator [Up to 100 Kva] Market