
 Construction Portable Generators Market | 2026-2036
Construction Portable Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Portable Generators Market Insights
Chinese engine manufacturing clusters is recalibrating export volumes as domestic construction activity absorbs more portable power units. Generac Holdings leverages its residential-to-commercial product pipeline to serve mid-size contractors. Caterpillar sustains premium positioning through integrated telematics and extended service networks. Honda Motor differentiates via inverter technology leadership for noise-sensitive urban job sites.
Construction portable generators are self-contained internal combustion or electrochemical power units rated typically from 1 kW to 250 kW, designed for temporary deployment without grid connection to energize tools, lighting, and machinery at building sites. Diesel generators dominate heavy civil applications where load duration exceeds eight hours and fuel logistics favor energy density. Inverter generators capture share among residential construction contractors prioritizing compact footprint and harmonic distortion below 3% for sensitive electronics. Battery-powered generators are the fastest-expanding technology segment, though margin pools remain concentrated in conventional reciprocating engine systems above 50 kW.
EPA Tier 4 Final and CARB standards enforce particulate matter and NOx limits that add after-treatment cost and weight to gasoline and diesel units sold in the United States. The EU F-Gas Regulation and CE machinery directives shape import eligibility and noise emission thresholds for equipment entering European job sites. Stakeholders must monitor battery energy density improvements and fast-charging infrastructure density to assess when electrochemical systems displace combustion units on cost-per-kWh at medium-duty construction applications.
Market Dynamics
EPA Tier 4 Final emissions compliance is compressing diesel generator margins while forcing manufacturers to absorb after-treatment costs that add weight and complexity to portable units destined for US construction sites.
Growth Catalysts
- Rural Electrification Gaps:India's highway construction expansion sustains rental fleet deployment of diesel generators at remote worksites where grid connection remains unavailable.
- Battery Energy Density Gains:Lithium-ion cell improvements are extending runtime for electrochemical power units in medium-duty residential construction applications.
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating manufacturer investment in alternative cooling architectures for generator enclosures.
Market Restraints
- After-Treatment Cost Burden:Diesel particulate filters and selective catalytic reduction systems add material cost and service complexity to units above 75 kW.
- Steel and Copper Volatility:Stator winding and enclosure raw material price swings compress fabrication margins for engine-generator set assemblers.
- Substitution by Grid Extension:Utility electrification of peri-urban construction zones in China reduces temporary power rental duration.
Strategic Opportunities
- Telematics Integration:Remote monitoring and predictive maintenance platforms create recurring revenue streams from rental fleet operators.
- Hybrid Architectures:Battery-diesel parallel systems capture load-following applications where runtime variability penalizes pure combustion efficiency.
- India PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing reduce import dependency for domestic generator OEMs.
Industry Challenges
- Emissions Calibration Talent Scarcity:Engine control module programming for Tier 4 Final compliance requires specialized software engineering expertise concentrated at tier-one suppliers.
- Multi-Jurisdiction Certification Timelines:CARB, EPA, and CE machinery directive testing protocols extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Portable Generators Market |
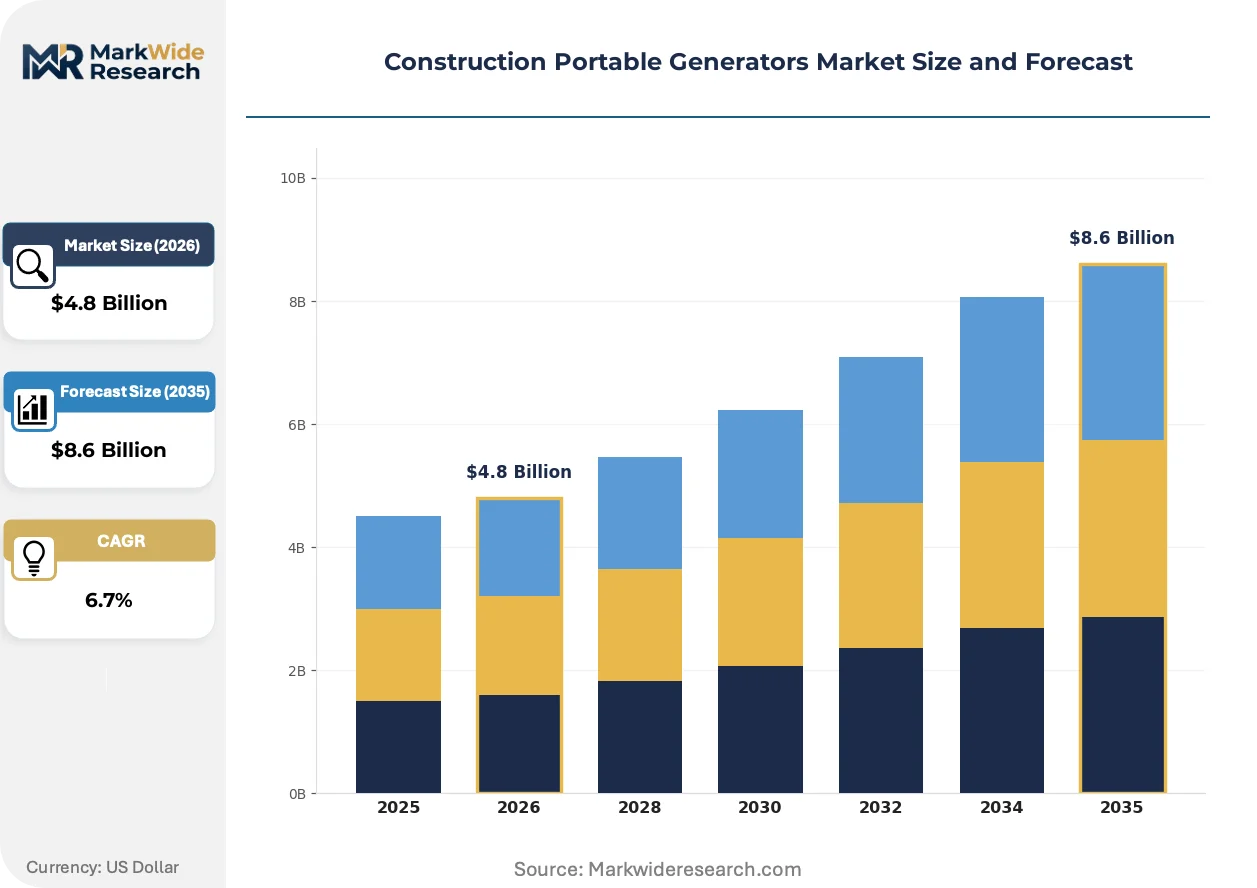
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gasoline Generators, Propane Generators, Solar Generators, Battery-Powered Generators Technology: Inverter Generators, Conventional Generators, Digital Control Generators, Automatic Voltage Regulators Application: Residential Construction Sites, Commercial Building Projects, Infrastructure Development, Emergency Power Supply End User: Construction Contractors, Equipment Rental Companies, Municipal Authorities, Independent Power Providers |
| Companies Covered | Generac Holdings, Caterpillar, Honda Motor, Briggs & Stratton, Atlas Copco, Cummins, Kohler, Yamaha Motor, Yanmar Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Portable Generators Market Trends and Innovations
Inverter generator architectures are compressing the performance gap with conventional synchronous machines while opening new deployment contexts. Three distinct trajectories are reshaping competitive positioning.
Silicon carbide power electronics is consolidating inverter generator efficiency gains above 94% at partial load conditions. Residential contractors in noise-restricted urban zones are specifying these units for harmonic-sensitive tool power. The technology is consolidating premium pricing power away from conventional open-frame gasoline sets.
EPA Tier 4 Final and CARB small off-road engine regulations are forcing gasoline generator redesigns for evaporative emissions containment. Manufacturers serving California and Northeast corridor markets face distinct testing burdens versus 49-state product lines. The regulatory divergence is fragmenting SKU portfolios and concentrating compliance investment at larger production volumes.
Rental fleet operators are unbundling after-sales service from equipment procurement contracts. Mid-size contractors in Texas and Florida are subscribing to hourly maintenance plans rather than bearing overhaul risk. This consumption-pattern shift is reallocating margin from unit sales to parts and labor revenue pools.
Construction Portable Generators Market Segmentation
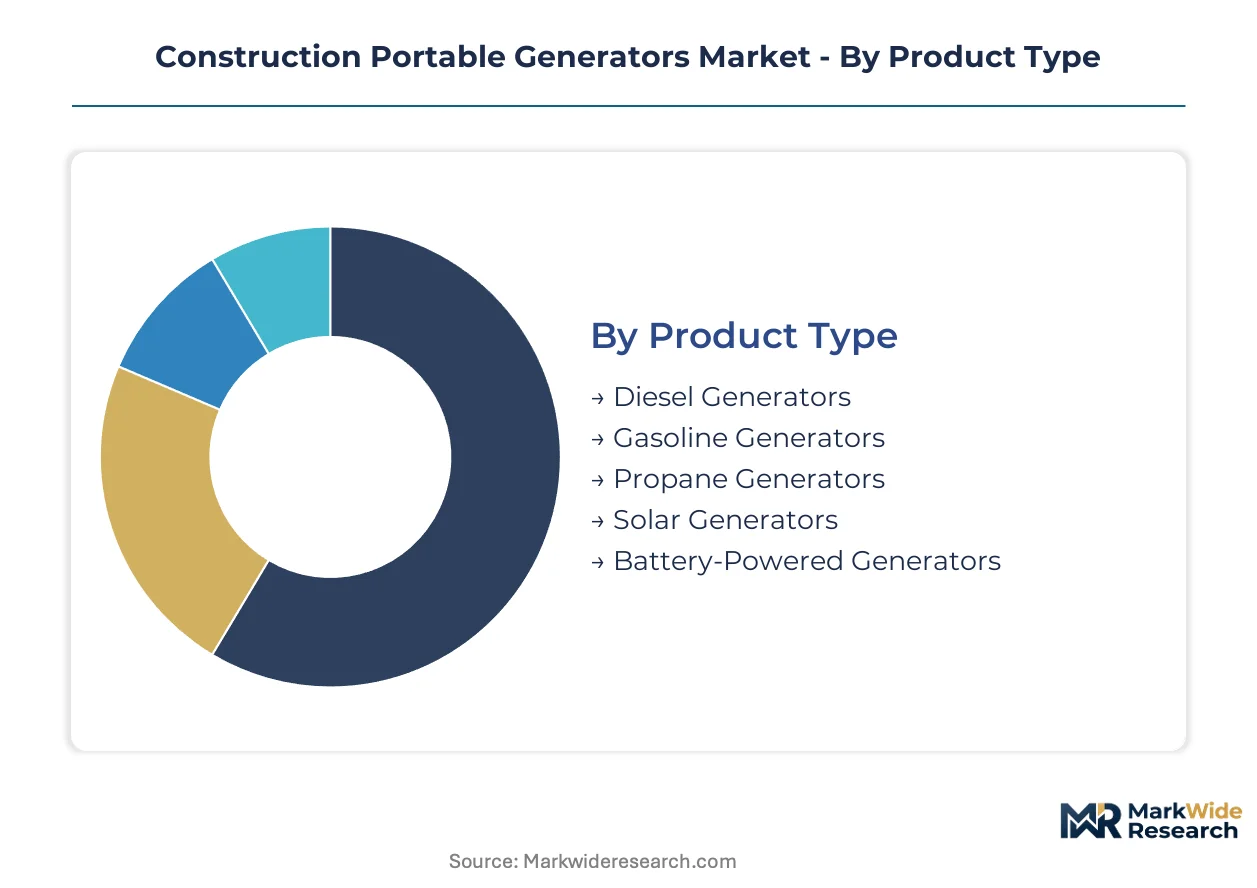
Segmentation in construction portable generators reveals distinct upgrade cycles across power technologies. Replacement decisions hinge on emissions compliance deadlines, runtime economics, and site-specific noise constraints rather than uniform depreciation schedules.
Product Type:
Upgrade cycles vary sharply by fuel architecture, with diesel units requiring Tier 4 Final retrofits while battery systems face cell degradation thresholds.
- Diesel Generators:Compression-ignition engines rated 50-250 kW dominate heavy civil works where load duration exceeds eight hours. Demand concentrates in India's highway construction corridors where grid extension lags behind earthmoving schedules and rental fleets absorb EPA after-treatment costs.
- Gasoline Generators:Spark-ignition units below 10 kW serve residential framing crews prioritizing capital cost over fuel efficiency. North American homebuilders specify these for short-cycle concrete pours where runtime rarely exceeds four hours.
- Propane Generators:LPG-fueled systems reduce evaporative emissions compliance burden for California contractors under CARB small off-road engine rules.
- Solar Generators:Photovoltaic-battery hybrids address remote site lighting with zero fuel logistics; adoption clusters in Australian mining camp construction.
- Battery-Powered Generators:Lithium-ion electrochemical units below 5 kW eliminate noise restrictions for urban infill projects; steepest expansion trajectory among all product types as energy density improvements extend runtime.
Volume placements concentrate in diesel generators; the faster expansion belongs to battery-powered generators.
Technology:
Technology selection tracks application sensitivity to power quality and operator control requirements.
- Inverter Generators:Variable-speed engines coupled with high-frequency alternators and rectifier-inverter stages deliver total harmonic distortion below 3%. Japanese residential contractors specify Honda and Yamaha units for sensitive electronics at smart home pre-wiring sites.
- Conventional Generators:Direct-coupled synchronous alternators maintain cost leadership for non-sensitive loads; dominance persists in emerging market infrastructure where waveform purity commands no premium.
- Digital Control Generators:Microprocessor-governed voltage regulation enables remote monitoring integration; rental fleets in Texas deploy these for predictive maintenance contracts.
- Automatic Voltage Regulators:Brushless excitation systems stabilize output for motor-starting loads; specification priority at commercial concrete batching operations.
Conventional generators retain the largest installed base; inverter architectures are gaining share fastest in noise-restricted urban zones.
Application:
Application segmentation aligns with project duration, load predictability, and grid proximity.
- Residential Construction Sites:Single-family and multi-family building projects require 3-15 kW units for circular saws, compressors, and temporary lighting. California's SB 100 building electrification mandates accelerate battery generator specification for indoor finishing work.
- Commercial Building Projects:Mid-rise steel and concrete structures demand 20-75 kW systems for tower cranes and welding equipment. India's commercial real estate expansion in Bangalore and Hyderabad sustains diesel rental demand.
- Infrastructure Development:Highway, bridge, and tunnel construction requires 100-250 kW prime power for continuous earthmoving operations.
- Emergency Power Supply:Standby deployment for grid outage continuity; municipal procurement in Florida and Texas prioritizes rapid-deployment trailer-mounted sets.
Commercial building projects generate the highest rental revenue density; residential sites are expanding most quickly as battery economics improve.
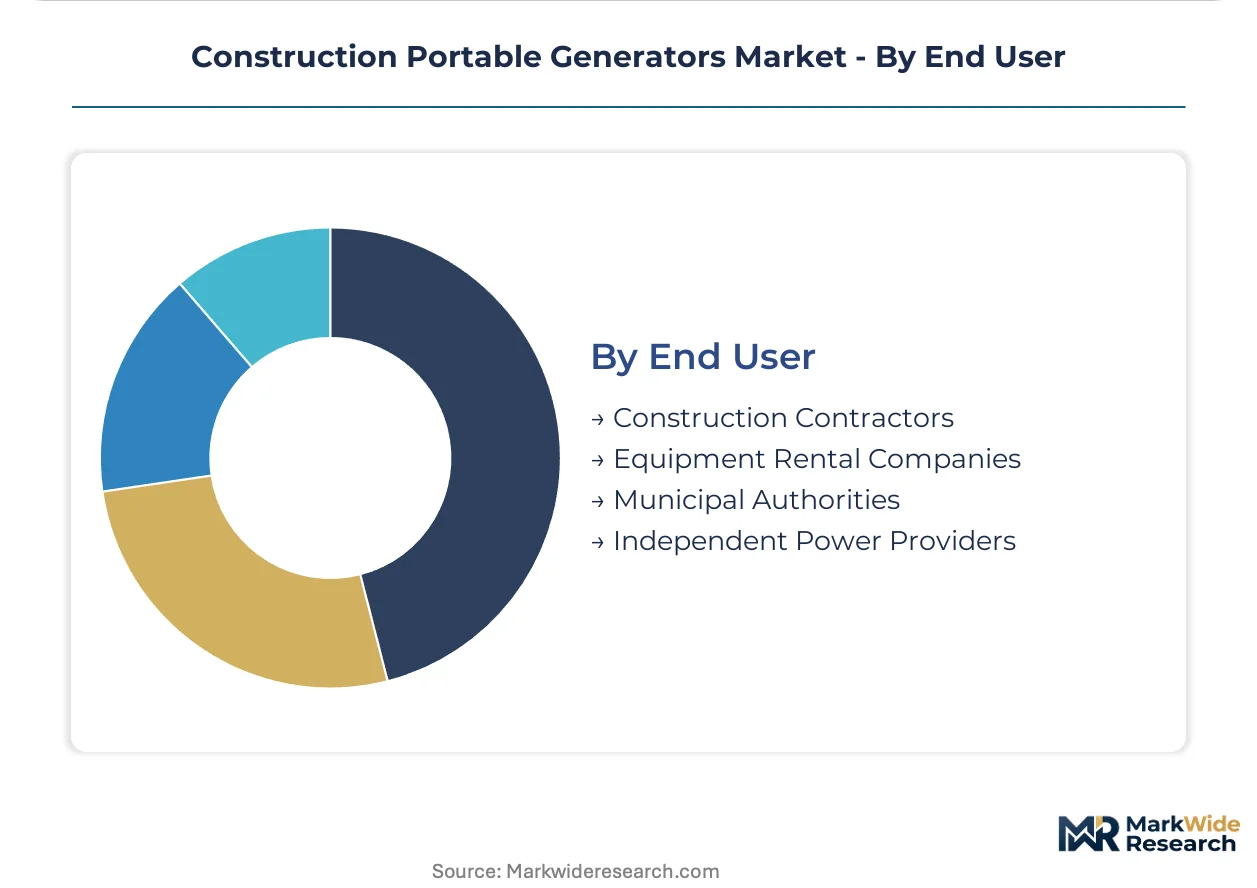
End User:
End user categories reflect procurement sophistication and maintenance capability dispersion.
- Construction Contractors:Direct ownership dominates among national builders with captive maintenance shops; Tier 4 Final calibration expertise concentrates at Caterpillar and Generac dealer networks.
- Equipment Rental Companies:United Rentals and Sunbelt Rentals aggregate fleet purchasing power; telematics integration creates recurring service revenue streams.
- Municipal Authorities:Public works departments specify low-emission units for compliance with state procurement guidelines; California Air Resources Board certification is mandatory.
- Independent Power Providers:Mobile power specialists serve event and film production adjacent to construction; margin pools favor short-duration premium pricing over long-term rental contracts.
Equipment rental companies command the largest procurement volumes; independent power providers are climbing the fastest as project-based contracting expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and copper sourcing corridors in China's Jiangsu and Shandong provinces anchor component supply for portable generator manufacturing clusters serving construction demand worldwide.
United States
Highway construction expansion across Texas and Florida sustains diesel generator rental demand for earthmoving fleets. EPA Tier 4 Final enforcement tightens particulate matter limits for units above 75 kW. Houston-based rental operators absorb after-treatment costs through telematics-enabled maintenance contracts.
India
Rural electrification gaps and Bangalore-Hyderabad commercial real estate corridors drive diesel generator deployment at remote worksites. The PLI scheme for advanced chemistry cell manufacturing reduces import dependency for domestic OEMs. Maharashtra's Pune-Nashik industrial belt hosts fabrication clusters for 50-250 kW prime power units.
China
Domestic construction absorption limits export volumes from Zhejiang and Jiangsu engine manufacturing clusters. MIIT emissions standards for non-road mobile machinery compress margins on diesel units. Chongqing's machinery hub recalibrates production toward battery-hybrid architectures for urban job sites.
Germany
Commercial building renovation mandates under the EU Green Deal sustain demand for low-emission power at urban construction zones. CE machinery directives and F-Gas Regulation phase-down schedules shape import eligibility for enclosure cooling systems. Bavaria's Munich-Stuttgart corridor concentrates inverter generator R&D for noise-sensitive applications.
Brazil
Infrastructure concessions for highway and port construction sustain rental fleet growth in São Paulo and Rio de Janeiro states. ANVISA and environmental agency oversight of diesel emissions lags EPA and EU stringency. Minas Gerais mining camp construction drives adoption of solar-battery hybrid generators for remote site lighting.
Construction Portable Generators Market Competitive Landscape
Global majors compete with regional champions across distribution networks and service infrastructure. The market structures around three tiers: integrated power systems conglomerates with captive engine technology, specialized generator fabricators focusing on rental fleet partnerships, and emerging battery-electric specialists exploiting energy density improvements. Consolidation pressure concentrates among mid-scale diesel generator assemblers facing Tier 4 Final compliance costs. Dominant competitive moves include telematics platform integration and hybrid architecture development.
Among US-based power systems conglomerates, Generac Holdings and Caterpillar occupy positions spanning residential-to-commercial product pipelines. Japanese precision manufacturers Honda Motor and Yamaha Motor exemplify inverter technology leadership for harmonic-sensitive applications. These named entities anchor archetype differentiation rather than exhaust competitive positioning across the full vendor landscape.
| Leading Market Players |
|---|
| Generac Holdings |
| Caterpillar |
| Honda Motor |
| Briggs & Stratton |
| Atlas Copco |
| Cummins |
| Kohler |
| Yamaha Motor |
| Yanmar Holdings |
| Others |
Pricing and Supply Chain Analysis
EPA Tier 4 Final compliance mandates from US contractors are forcing diesel generator OEMs to absorb after-treatment costs that compress fabrication margins and recalibrate procurement toward certified component suppliers with proven emissions calibration capabilities.
Pricing Analysis
Warranty and service bundling now separates premium rental fleet contracts from transactional unit sales, with Texas-based operators subscribing to hourly maintenance plans while independent contractors bear overhaul risk directly. Pricing stratifies across Tier 4 Final-certified premium tiers, standard 49-state gasoline configurations, and economy open-frame sets for emerging market infrastructure. Cost compression in diesel units above 75 kW is intensifying because selective catalytic reduction systems add material weight and service complexity. Equipment rental companies exhibit lowest price sensitivity due to telematics-enabled recurring revenue streams; residential framing crews remain most price-conscious.
Supply Chain Analysis
Regional distribution centers in Houston, Mumbai, and Rotterdam anchor hub-and-spoke patterns that position finished generator sets within 48-hour delivery windows of major construction corridors. Engine block casting and alternator stator winding concentrate in China's Jiangsu and Shandong provinces, India's Pune-Nashik belt, and Germany's Bavaria cluster. Copper magnet wire, silicon steel laminations, and diesel after-treatment ceramics constitute critical input dependencies. Single-source vulnerability in EPA-certified engine control module programming concentrates at tier-one suppliers. Distribution runs through authorized dealer networks for warranty-backed units and gray-market channels for uncertified emerging market demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around emissions-compliant players as Tier 4 Final calibration costs and multi-jurisdiction certification timelines force mid-scale assemblers toward acquisition or exit.
For Market Incumbents: Extend telematics platform penetration to capture recurring service revenue from rental fleet operators and lock in switching costs. Deepen backward integration into battery cell supply through India's PLI scheme partnerships to hedge diesel substitution risk. Prioritize hybrid architecture R&D for load-following applications where runtime variability penalizes pure combustion efficiency.
For New Entrants and Emerging Players: Capture battery-powered generator share in California's SB 100-mandated residential construction zones where noise restrictions and indoor electrification requirements create specification pull. Target Australian mining camp construction for solar-battery hybrid lighting systems with zero fuel logistics. Pursue direct OEM partnerships with electric tool manufacturers to bundle electrochemical power units as integrated jobsite solutions.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated power systems conglomerates with captive engine technology and established dealer service infrastructure. Long-term viability hinges on hybrid architecture portfolios spanning combustion and electrochemical platforms. Monitor battery energy density improvements above 300 Wh/kg and fast-charging infrastructure density as inflection indicators for medium-duty construction displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables predictive maintenance contracts that shift margin from unit sales to recurring service revenue pools. |
| Hybrid Architecture Development | Captures load-following applications where battery-diesel parallel systems optimize runtime-variable efficiency. |
| Emissions Certification Investment | Secures EPA Tier 4 Final and CARB eligibility for California and Northeast corridor market access. |
| Battery Supply Agreement | Reduces import dependency through India's PLI scheme for advanced chemistry cell manufacturing partnerships. |
| Rental Fleet Partnership | Aggregates procurement volume through United Rentals and Sunbelt Rentals channel relationships. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-validated through primary interviews with rental fleet procurement directors, OEM product managers, aftermarket service heads, and emissions calibration engineers. EPA certification databases, CARB executive orders, EU CE machinery directive harmonized standards, and India BIS product registrations supplied compliance tracking. Bottom-up unit shipment estimates by power rating and fuel type were triangulated against top-down construction spending correlations.
Granularity-level modeling distinguished diesel, gasoline, propane, and battery-powered architectures across 1-250 kW power bands, with separate treatment of inverter versus conventional alternator technologies. CAGRs were derived from regression-weighted scenario outputs across the projection horizon. Forecast inputs incorporated highway construction spending pipelines, rural electrification gap closure timelines, and lithium-ion cell cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery energy density breakthroughs and grid extension rates in peri-urban construction zones. Forecasts reflect documented assumptions about emissions regulation enforcement consistency and raw material price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Middle-East and Africa Portable Generator Market
Generators
Gasoline Gensets Market
Generators
US Generator Sales Market
Generators
Military Generator Market
Generators
Portugal Gas Generator Market
Generators
Power Generator for Military Market
Generators
Kuwait Diesel Gensets Market
Generators
Construction Prime Power Generators Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
Commercial Generator Market
Generators
Emergency Power Generators Sales Market
Generators
India Portable Generator Market
Generators
Power Generator Rental Market
Generators
Mobile Generators Market
Generators
Reciprocating Power Generating Engine Market
Generators
North America Gasoline Gensets Market