
 Construction Generator Sets Market | 2026-2036
Construction Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Generator Sets Market Insights
India's industrial corridor expansion is reshaping competitive dynamics for construction generator sets across South Asia. Caterpillar leverages its integrated engine-manufacturing footprint to dominate heavy-duty prime power deployments at Indian megaproject sites. Cummins sustains technology leadership through in-house alternator production and emissions calibration for high-altitude Himalayan roadworks. HIMOINSA anchors its position in Mediterranean markets with specialized gas generator architectures for urban building sites facing strict noise ordinances.
Construction generator sets are self-contained engine-alternator assemblies rated from 10 kVA to over 3,000 kVA, designed to deliver electrical power at fixed or variable load profiles where grid connection is unavailable or unreliable; their primary purpose is ensuring continuous operations at remote building sites, mining pits, and temporary outdoor installations. Diesel generators still occupy the largest revenue share due to fuel availability and torque response under fluctuating construction loads, though hybrid generators are capturing the fastest growth as contractors face escalating runtime cost pressures and emissions compliance thresholds. Portable technology leads unit shipments for short-duration roadworks and municipal maintenance contracts, while continuous power configurations command premium pricing in mining operations where downtime penalties exceed equipment capital costs.
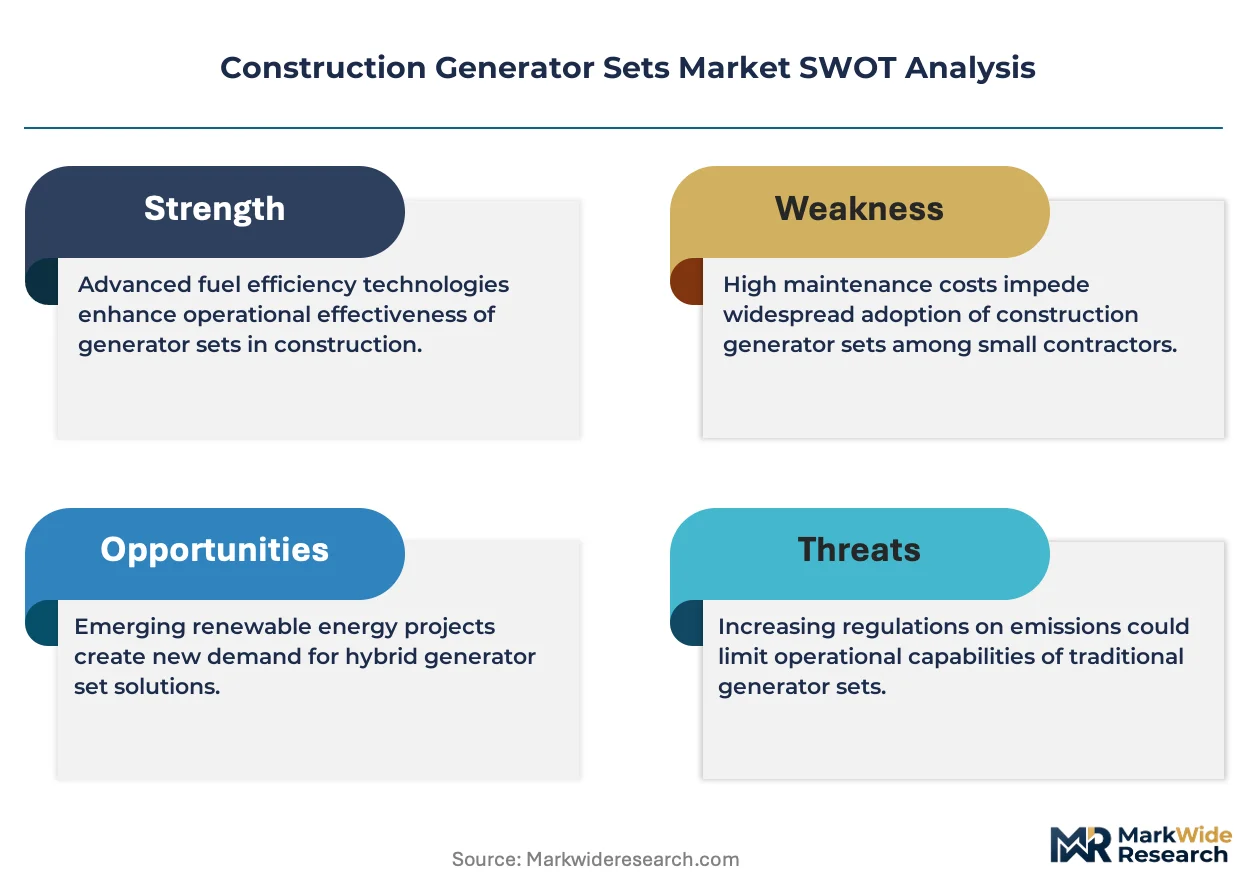
EPA Tier 4 Final standards in the United States and EU Stage V regulations through the European Commission are forcing diesel engine redesigns with selective catalytic reduction and diesel particulate filter integration, raising unit costs but creating barriers for non-compliant imports. India's CEA grid interconnection mandates and BIS fuel efficiency labeling for stationary engines are redirecting contractor procurement toward certified equipment vendors with established service networks. Stakeholders must monitor how carbon border adjustment mechanisms and evolving mine-site electrification timelines reshape the economic calculus between conventional diesel backup and battery-hybrid alternatives.
Market Dynamics
Hybrid generator configurations are compressing the economic calculus between conventional diesel backup and battery-integrated alternatives, as runtime cost pressures and emissions compliance thresholds force contractors to reevaluate prime power architectures at remote construction sites.
Growth Catalysts
- EPA Tier 4 Final standards:Diesel engine redesigns with selective catalytic reduction and diesel particulate filter integration are raising technical barriers for non-compliant imports, favoring established vendors with certified equipment portfolios.
- Mining operations:Australian pit sites are accelerating adoption of hybrid configurations to meet diesel emission limits under the country's national environmental regulator.
- CEA grid interconnection mandates:India's central electricity authority is redirecting contractor procurement toward certified equipment vendors with established service networks.
Market Restraints
- Platinum group metals:Selective catalytic reduction systems depend on palladium and rhodium catalysts, exposing unit costs to volatile precious metal markets.
- Engine manufacturing concentration:Heavy-duty prime power generator sets rely on a concentrated supplier base for compliant diesel engines above 750 kVA.
- Battery-hybrid substitution:Mine-site electrification timelines are accelerating investment in fixed battery storage, threatening mobile generator deployment schedules.
Strategic Opportunities
- Western Indian states:Highway and bridge projects funded by central infrastructure programs are concentrating procurement demand for portable diesel units.
- Gas generator architectures:Specialized natural gas configurations for urban building sites facing strict noise ordinances are opening Mediterranean market penetration.
- Carbon border adjustment mechanisms:Emerging EU trade instruments are creating first-mover advantages for manufacturers with lifecycle emissions documentation.
Industry Challenges
- Emissions calibration expertise:High-altitude Himalayan roadworks require specialized altitude compensation programming that strains field service technician availability.
- Dual certification timelines:Simultaneous EPA Tier 4 Final and EU Stage V homologation processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Generator Sets Market |
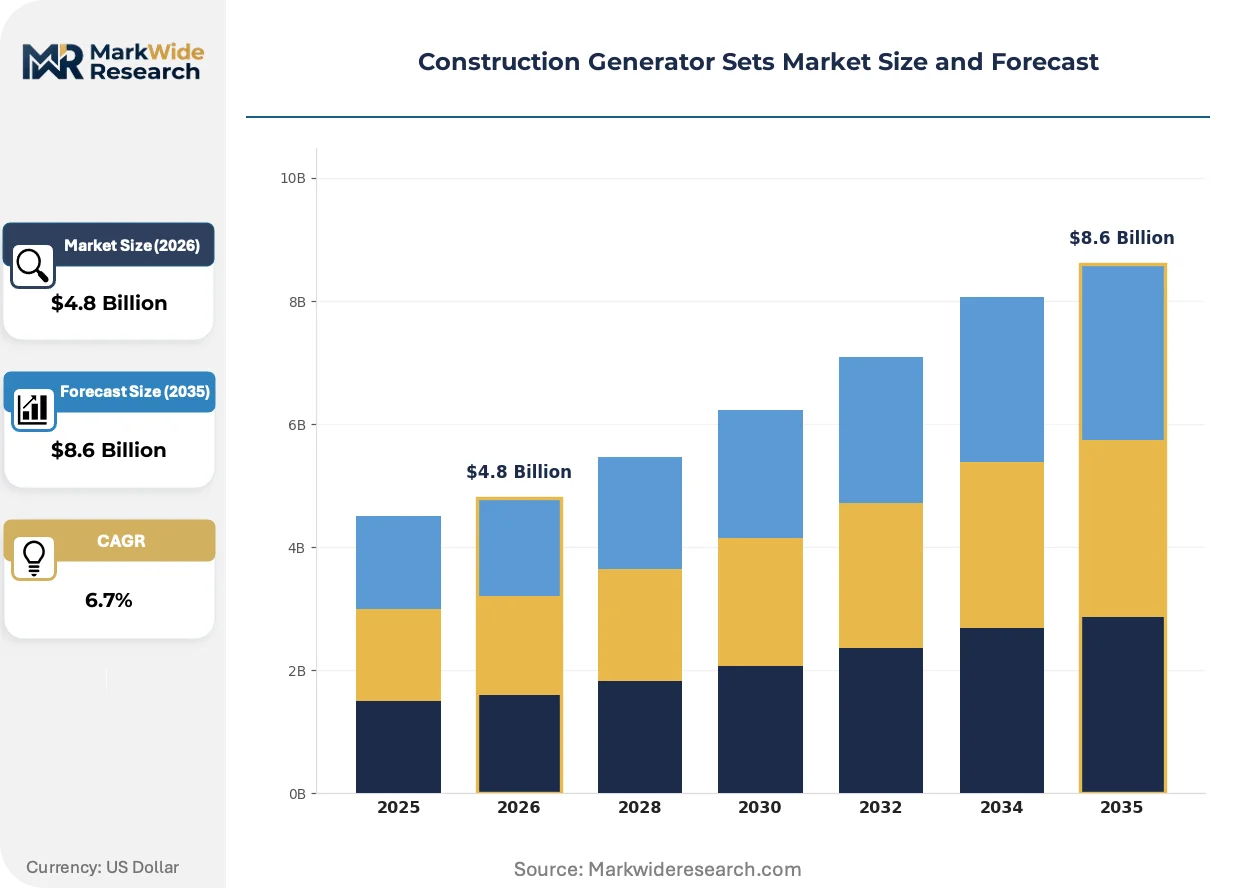
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generator, Gas Generator, Hybrid Generator, Solar Generator Technology: Portable, Standby, Prime Power, Continuous Power Application: Building Sites, Roadworks, Mining Operations, Outdoor Events End User: Contractors, Equipment Rentals, Municipal Authorities, Telecommunications |
| Companies Covered | Cummins, Caterpillar, Generac Power Systems, Atlas Copco, Rehlko, Kohler, Doosan Portable Power, HIMOINSA, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Generator Sets Market Trends and Innovations
Diesel-electric hybrid architectures are redefining power generation economics at construction sites, compressing fuel consumption while extending maintenance intervals. Three interconnected developments are reshaping equipment specifications and vendor competitive positioning.
Power management software is virtualizing generator dispatch decisions at hybrid-equipped sites. Tier 1 contractors on Australian mining leases are deploying predictive load algorithms that cycle diesel engines based on battery state-of-charge and forecasted demand spikes. This capability is virtualizing the traditional role of onsite operators, reducing headcount requirements while optimizing runtime hours across mixed-asset fleets.
EU Stage V regulations through the European Commission are forcing particulate matter and nitrogen oxide reductions below 0.015 g/kWh and 0.4 g/kWh respectively. Engine manufacturers are responding with dual-stage aftertreatment systems that add 12-18% to powerpack weight and volume. Urban building contractors in Germany and France are absorbing these penalties to maintain site access, while remote infrastructure projects in Eastern Europe face equipment availability constraints.
Rental channel consolidation is compressing procurement decision cycles for short-duration roadworks. Municipal maintenance contractors are bypassing traditional equipment distributors to contract directly with national rental fleets offering telematics-enabled uptime guarantees. This pattern is most visible across India's state highway departments, where tender specifications now prioritize real-time fuel monitoring over capital purchase options.
Construction Generator Sets Market Segmentation
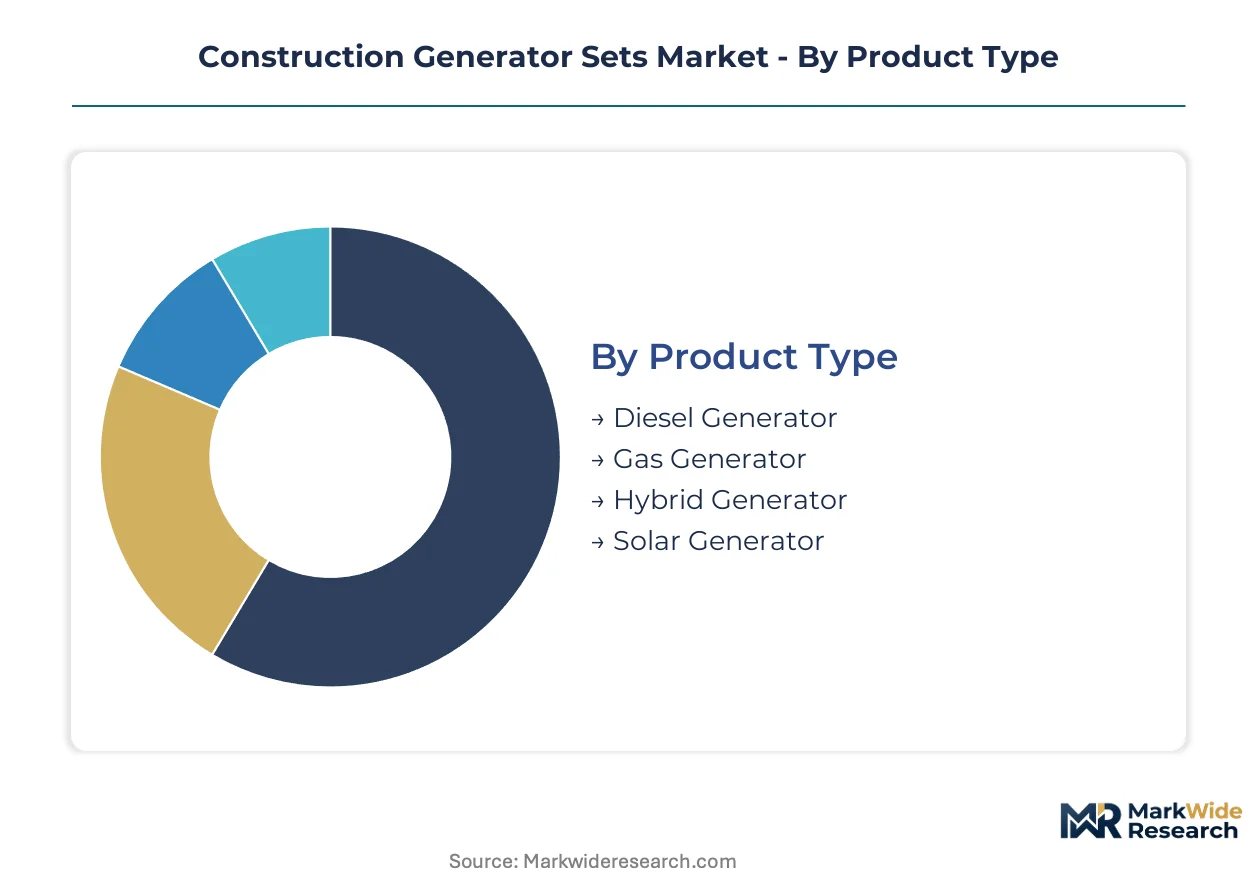
Construction generator sets fragment across four distinct dimensions that dictate procurement velocity, margin structure, and vendor competitive intensity. Equipment turnover cycles vary dramatically: portable units for municipal roadworks rotate every 18-24 months while continuous power configurations for mining operations stretch replacement timelines beyond eight years.
Product Type:
Diesel and gas configurations dominate replacement cycles with predictable obsolescence patterns, whereas hybrid and solar architectures compress technology refresh timelines as battery energy density improves.
- Diesel Generator:Compression-ignition engine-alternator assemblies rated 10-3,000+ kVA deliver torque response under fluctuating construction loads. Australian mining contractors specify these for pit-site prime power despite Tier 4 Final aftertreatment cost premiums, as fuel availability outweighs capital expenditure penalties in remote locations.
- Hybrid Generator:Battery-integrated architectures combine diesel prime movers with lithium-ion storage to optimize load-following and reduce runtime hours. Indian highway contractors in Maharashtra and Gujarat are accelerating procurement of these units for central infrastructure programs where fuel monitoring and emissions compliance tighten bid evaluation criteria.
- Gas Generator:Spark-ignition natural gas configurations leverage pipeline or compressed fuel delivery for reduced particulate emissions. Mediterranean urban building sites facing strict municipal noise ordinances specify these for after-hours concrete curing and crane operations.
- Solar Generator:Photovoltaic-battery hybrids with limited diesel backup serve short-duration outdoor events and remote survey camps. German festival operators deploy these for stage lighting and vendor power where grid extension proves uneconomical.
Diesel configurations anchor the volume base while hybrid architectures gain share at the steepest rate.
Technology:
Cost tiers separate mobile rental fleet specifications from premium continuous-duty installations where downtime penalties exceed equipment capital costs.
- Portable:Skid-mounted or trailer-towed units below 150 kVA deploy for municipal maintenance and emergency response. India's state highway departments now mandate telematics-enabled fuel monitoring in tender specifications, compressing procurement decision cycles toward rental channel consolidation.
- Continuous Power:Heavy-duty configurations engineered for unlimited annual operating hours at constant load. Australian iron ore and coal operations specify these for pit dewatering and processing plant backup where production interruption costs run into millions per day.
- Standby:Automatic-start units rated for limited annual runtime provide grid-failure protection at fixed building sites. French commercial construction contractors install these for tower crane safety systems and site office climate control.
- Prime Power:Variable-load architectures designed as primary electricity source for off-grid operations. Himalayan roadwork contractors in Himachal Pradesh and Uttarakhand deploy these for tunnel boring and batch plant operations where altitude compensation programming strains field service technician availability.
Portable technology commands the highest unit velocity while continuous power configurations capture the steepest expansion trajectory.
Application:
Geographic concentration of infrastructure investment determines segment scale, with mining corridors and highway corridors driving divergent equipment specifications.
- Mining Operations:Pit-site power demands span excavation, haulage, processing, and camp facilities with 24/7 reliability requirements. Western Australia's Pilbara region and Queensland's Bowen Basin are accelerating hybrid adoption under the national environmental regulator's diesel emission limits.
- Roadworks:Linear infrastructure projects require mobile power for asphalt paving, compaction, and lighting. India's western states concentrate procurement for NHAI-funded expressway construction where contractor mobilization schedules favor rental fleet flexibility.
- Building Sites:Urban vertical construction needs tower crane power, concrete pumping, and worker welfare facilities. German and French contractors absorb EU Stage V aftertreatment weight penalties to maintain site access in dense municipal jurisdictions.
- Outdoor Events:Temporary power for festivals, exhibitions, and sporting fixtures demands rapid deployment and silent operation. UK event operators specify gas configurations for central London venues with strict noise curfews.
Roadworks applications rotate equipment fastest while mining operations concentrate revenue at the premium tier.
End User:
Customer type dictates procurement channel structure, with rental intermediaries capturing municipal and contractor demand while direct sales dominate mining accounts.
- Contractors:Tier 1 construction firms with mixed-asset fleets deploy predictive load algorithms that virtualize generator dispatch decisions. Australian mining lease operators cycle diesel engines based on battery state-of-charge, reducing headcount requirements.
- Equipment Rentals:National rental fleets offering telematics-enabled uptime guarantees are bypassing traditional distributors. Indian state highway departments now contract directly with these providers for real-time fuel monitoring over capital purchase options.
- Municipal Authorities:City and state agencies specify portable units for emergency response, road maintenance, and public works. US municipal procurement faces EPA Tier 4 Final compliance barriers that favor established vendors with certified equipment portfolios.
- Telecommunications:Tower companies require standby and prime power for base stations in grid-unreliable regions. Rural Indian telecom infrastructure depends on diesel-gas hybrid configurations under CEA grid interconnection mandates.
Equipment rentals anchor the volume base while contractors expand most quickly through fleet digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine manufacturing for construction generator sets concentrates in industrial clusters across Germany, the United States, Japan, India, and Australia. These five markets anchor both supply capacity and demand intensity for prime power equipment.
United States
Highway reconstruction programs and data center construction are accelerating diesel generator procurement. EPA Tier 4 Final standards force selective catalytic reduction integration, raising barriers for import-dependent contractors. Texas and California industrial corridors dominate heavy-duty prime power deployments.
Germany
Urban building contractors absorb EU Stage V aftertreatment weight penalties to maintain site access in dense municipal jurisdictions. The country's national environmental regulator enforces particulate matter limits below 0.015 g/kWh. Bavaria and North Rhine-Westphalia anchor gas generator adoption for noise-restricted after-hours operations.
India
Western state highway authorities concentrate procurement on portable diesel units for NHAI-funded expressway construction. CEA grid interconnection mandates redirect contractor selection toward certified vendors with established service networks. Maharashtra and Gujarat construction clusters favor rental fleet flexibility over capital purchases.
Australia
Pilbara iron ore and Queensland coal operations accelerate hybrid configuration adoption under the national environmental regulator's diesel emission limits. Mine-site electrification timelines threaten mobile generator deployment schedules. Western Australia mining corridors command premium pricing for continuous power reliability.
Japan
Disaster resilience infrastructure and tunnel construction sustain standby generator demand. METI efficiency standards shape procurement specifications for urban building sites. Kanto and Kansai industrial regions specify compact gas configurations for seismic-sensitive installations.
Construction Generator Sets Market Competitive Landscape
Integrated engine manufacturers and specialized power system assemblers split the market between captive component control and flexible sourcing strategies. The vendor base organizes around three archetypes: full-stack engine-alternator producers, rental fleet operators with captive maintenance networks, and regional fabricators serving price-sensitive municipal procurement. Dominant competitive moves include backward integration into alternator manufacturing and telematics-enabled service contract expansion.
Among North American integrated producers, Caterpillar and Cummins anchor the premium-tier vector for heavy-duty mining and infrastructure applications. HIMOINSA occupies a position within the specialized gas generator segment for Mediterranean urban building sites. These three exemplify how geographic manufacturing footprint and emissions calibration expertise stratify competitive positioning across regulatory jurisdictions.
| Leading Market Players |
|---|
| Cummins |
| Caterpillar |
| Generac Power Systems |
| Atlas Copco |
| Rehlko |
| Kohler |
| Doosan Portable Power |
| HIMOINSA |
| Mitsubishi Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
Platinum group metal volatility in selective catalytic reduction systems determines both the premium tier spreads for EPA Tier 4 Final compliant units and the geographic consolidation of engine manufacturing toward suppliers with captive catalyst hedging capabilities.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the construction generator sets landscape. Three-tier pricing structure across premium, standard, and economy levels separates certified heavy-duty mining configurations from portable rental fleet specifications and uncertified grey-market imports. Price differentiation rests on emissions certification grade and geographic delivery cost to remote Australian pit sites or Himalayan roadworks. Pricing pressure stems from palladium and rhodium cost spikes in aftertreatment systems, compressing margins on mid-range diesel units. Municipal procurement authorities in India exhibit highest price sensitivity, while Australian mining operators prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Export-control restrictions on high-pressure common-rail fuel injection technology limit component flows from Germany and Japan to non-aligned manufacturing jurisdictions. Engine block casting and precision machining concentrate in Germany, the United States, and India. Raw material dependencies include crankshaft-grade steel, copper winding stock for alternators, and platinum group metals for catalytic converters. Single-source vulnerability sits with European suppliers of electronic engine control modules certified for dual EPA-EU homologation. Distribution runs through captive OEM service networks for mining accounts and consolidated national rental fleets for municipal roadworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-hybrid substitution threatens conventional diesel generator incumbents as mine-site electrification accelerates investment in fixed storage infrastructure.
For Market Incumbents: Harden emissions calibration expertise for high-altitude Himalayan deployments where altitude compensation programming strains technician availability. Deepen backward integration into alternator manufacturing to capture margin from hybrid system battery integration. Battery-hybrid substitution represents the core threat requiring defensive R&D allocation toward predictive load algorithms. For New Entrants and Emerging Players: Mid-market gas generator configurations for Mediterranean urban building sites facing strict municipal noise ordinances represent the most penetrable entry point. Western Indian state highway authorities contracting directly with telematics-enabled rental fleets offer a channel bypass opportunity. Target service network partnerships over manufacturing scale to compete with established vendor footprints. For Investors and Strategic Acquirers: Specialized power system assemblers with captive alternator production and established EPA-EU dual certification timelines offer the strongest acquisition target profile. Long-term viability hinges on hybrid technology transition execution over the next decade. Mine-site electrification timeline acceleration serves as the critical inflection indicator requiring portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternator Manufacturing | Captive alternator production secures margin capture from hybrid system battery integration demands. |
| Dual Certification Investment | Simultaneous EPA Tier 4 Final and EU Stage V homologation opens access to premium mining and infrastructure contracts. |
| Predictive Load Algorithm Development | Power management software virtualizes generator dispatch decisions, reducing operator headcount requirements at Australian mining leases. |
| Telematics-Enabled Service Contract Expansion | Real-time fuel monitoring capabilities align with Indian state highway department tender specifications favoring rental over purchase. |
| Gas Generator Architecture Specialization | Natural gas configurations penetrate Mediterranean urban markets where strict noise ordinances restrict diesel runtime. |
Research Methodology
A spread of perspectives from maintenance directors at Australian mining operations, OEM procurement teams at Caterpillar and Cummins, aftermarket service heads in India, and plant engineers at German engine manufacturing facilities converged on the working assumptions. Primary interview insights combined with secondary validation from EPA certification databases, EU Stage V homologation registries, Indian CEA grid interconnection filings, and Australian national environmental regulator emission compliance records. Bottom-up unit shipment estimates and top-down revenue triangulation anchored the analytical framework.
Demand-supply balance modeling across the projection horizon integrated power rating segmentation, fuel type architecture, technology tier classification, and application intensity dimensions. CAGRs derived from regression analysis against infrastructure investment flows and mining capital expenditure cycles. Industry-specific forecast inputs included mine-site electrification timeline assumptions and central infrastructure program disbursement schedules in India.
Practitioners should monitor platinum group metal price spikes, battery energy density improvement curves, and carbon border adjustment mechanism implementation timing for early signals. Forecasts reflect documented assumptions on hybrid adoption rates and regulatory enforcement intensity. Material shifts in mine-site electrification investment or EPA Tier 5 precursor discussions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Multi Fuel Generators Market
Generators
Gasoline Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
Tri Fuel Generators Market
Generators
Halogenerator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Kuwait Diesel Gensets Market
Generators
North West Europe Diesel Generator Market
Generators
China Gas Generator Market
Generators
Power Generator for Military Market
Generators
Europe Turbo Generator Market
Generators
India Diesel Generator Market
Generators
Dual-Fuel Generator Market
Generators
Generator [Up to 100 Kva] Market
Generators
Wind Turbine Alternator Market
Generators
North America Portable Generators Market