
 Generator Rental Market | 2026-2036
Generator Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Generator Rental Market Intelligence
Equipment dealership networks is reconfiguring how generator rental fleets reach end users across fragmented construction zones. United Rentals leverages its branch density to sustain same-day deployment capabilities in metropolitan corridors. Aggreko competes through specialized mobile power modules engineered for remote oilfield operations. Sunbelt Rentals anchors Gulf Coast positioning with hurricane-season surge capacity held in Florida and Texas yards.
Generator rental involves temporary procurement of engine-driven alternator sets rated from 20 kW to 2,000 kW, typically mounted on skid bases or road-legal trailers for transport to sites lacking grid connectivity or requiring backup redundancy. Diesel generator sets dominate fleet composition due to fuel availability and torque response under variable load, though hybrid units incorporating battery storage gain traction where noise restrictions or emissions limits apply. Construction end users account for the largest revenue pool, while emergency rental services command premium rate structures during grid failure events. Short-term rental terms generate higher per-day yields, whereas long-term contracts stabilize fleet utilization across seasonal demand troughs.
EPA Tier 4 Final standards for non-road diesel engines mandate selective catalytic reduction and diesel particulate filters on new rental units, elevating capital costs and reshaping fleet replacement cycles. OSHA temporary power regulations govern grounding and connection protocols at construction sites, creating compliance-driven demand for certified installation services bundled with rental agreements. Stakeholders must monitor state-level zero-emission equipment mandates in California and New York, as these jurisdictions test regulatory boundaries that could propagate to broader regional markets.
Market Dynamics
EPA Tier 4 Final compliance costs are compressing fleet replacement cycles and forcing rental operators to reconfigure capital deployment toward hybrid-electric architectures. Equipment lessors now balance diesel unit longevity against battery-augmented systems that command premium day rates in noise-restricted jurisdictions.
Growth Catalysts
- Grid resilience mandates:State-level reliability standards in California and Texas require backup power redundancy for critical infrastructure, expanding rental contract durations for healthcare and data center operators.
- Construction electrification:Battery-genset hybrid units address torque demands in urban high-rise projects where diesel-only operation faces municipal curfews.
- Hurricane season intensity:Sustained Atlantic storm activity creates surge demand patterns that justify dedicated inventory positioning along Florida and Gulf Coast corridors.
Market Restraints
- Aftertreatment cost inflation:Selective catalytic reduction and diesel particulate filter hardware adds capital burden per kilowatt of rated capacity.
- Skilled technician scarcity:EPA-certified service personnel concentrate in metropolitan rental hubs, limiting remote deployment responsiveness.
- Grid interconnection improvements:Utility hardening programs in hurricane-prone zones reduce outage frequency and duration, compressing emergency rental windows.
Strategic Opportunities
- Remote oilfield electrification:Permian Basin operators seek mobile power for drilling pads lacking transmission infrastructure, favoring rental over ownership for well-to-well mobility.
- California zero-emission mandates:CARB off-road diesel regulations accelerate demand for battery-dominant rental units in Los Angeles and San Francisco construction corridors.
- Microgrid-as-a-service bundling:Rental providers integrate generation, storage, and control hardware into turnkey temporary power systems for event and film production clients.
Industry Challenges
- Fleet utilization volatility:Seasonal construction troughs and unpredictable storm seasons create revenue concentration risk that demands sophisticated demand forecasting.
- Cross-state compliance complexity:Operators serving multi-jurisdictional projects must maintain variant inventory configurations to satisfy divergent emissions and noise ordinances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generator Rental Market |
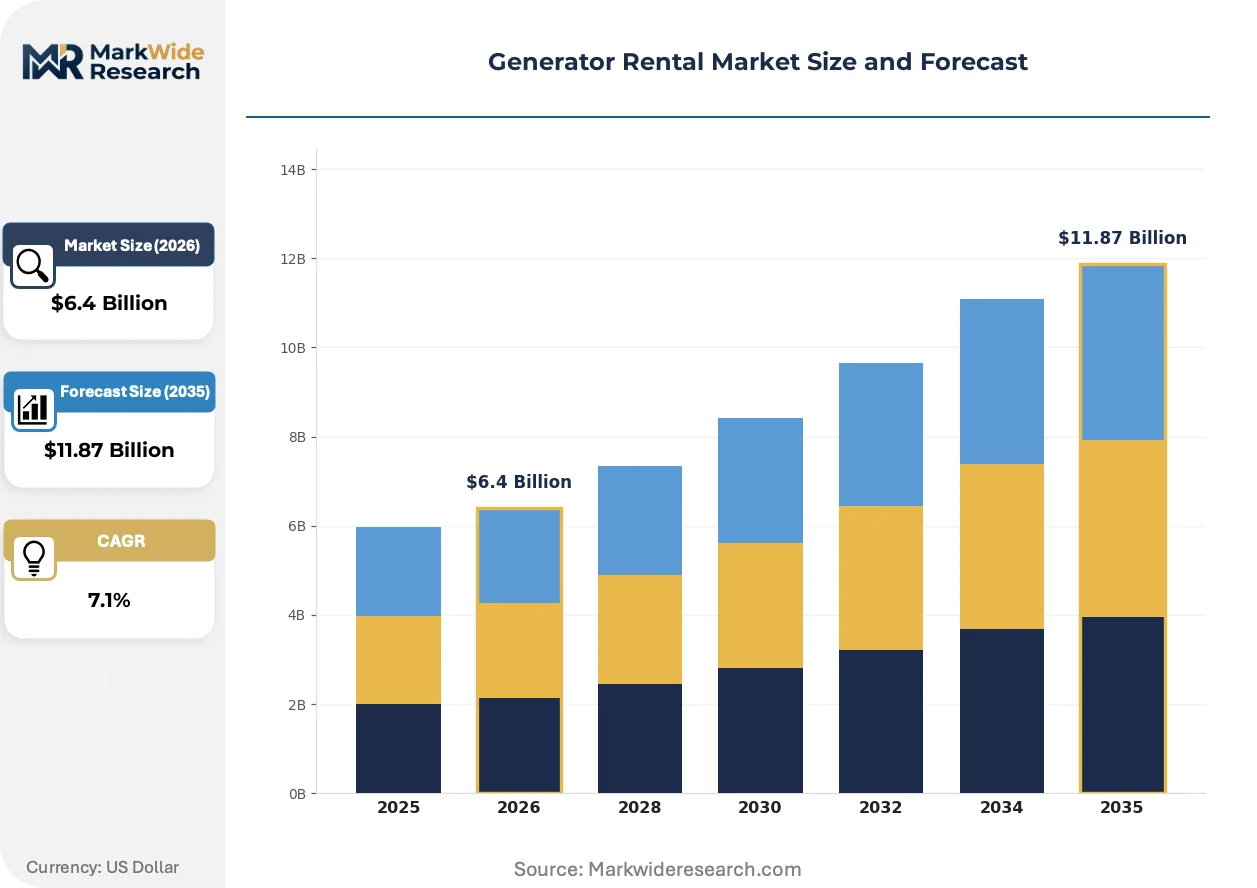
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.87 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Hybrid Generators, Portable Generators End User: Construction, Events, Industrial, Residential Deployment: On-Site, Off-Site, Mobile, Static Service Type: Short-Term Rental, Long-Term Rental, Emergency Rental, Maintenance Service |
| Companies Covered | Herc Rentals, Sunbelt Rentals, United Rentals, Caterpillar, Cummins, Aggreko, Atlas Copco, H&E Equipment Services, Ashtead Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generator Rental Market Strategic Shifts & Innovations
Generator rental technology is bifurcating between legacy diesel platforms and integrated battery-hybrid architectures. This transition redefines fleet economics and service bundling strategies across construction and emergency response verticals.
Hybrid power systems incorporating lithium-ion storage and smart load management are migrating from niche film production applications into mainstream commercial construction. Metropolitan general contractors in Los Angeles and New York now specify these units for overnight concrete curing operations where noise restrictions previously mandated grid tie-in or work stoppage. The technology is migrating from premium event rental into standard construction fleet composition, compressing payback periods for capital-intensive battery hardware.
EPA enforcement of Tier 4 Final standards for non-road diesel engines is tightening compliance timelines for rental fleet operators. The regulation mandates documented maintenance records and emissions testing protocols that elevate operational overhead. California and Texas rental yards face the steepest adaptation curves due to fleet scale and inspection frequency requirements.
Project owners now specify fuel consumption guarantees and uptime service level agreements within rental contracts, displacing simple equipment-hire arrangements. Construction managers in Florida and Gulf Coast markets negotiate bundled offerings covering delivery, installation, and 24-hour technical response. This pattern concentrates procurement authority with national account teams at the expense of regional broker networks.
Generator Rental Market Segmentation
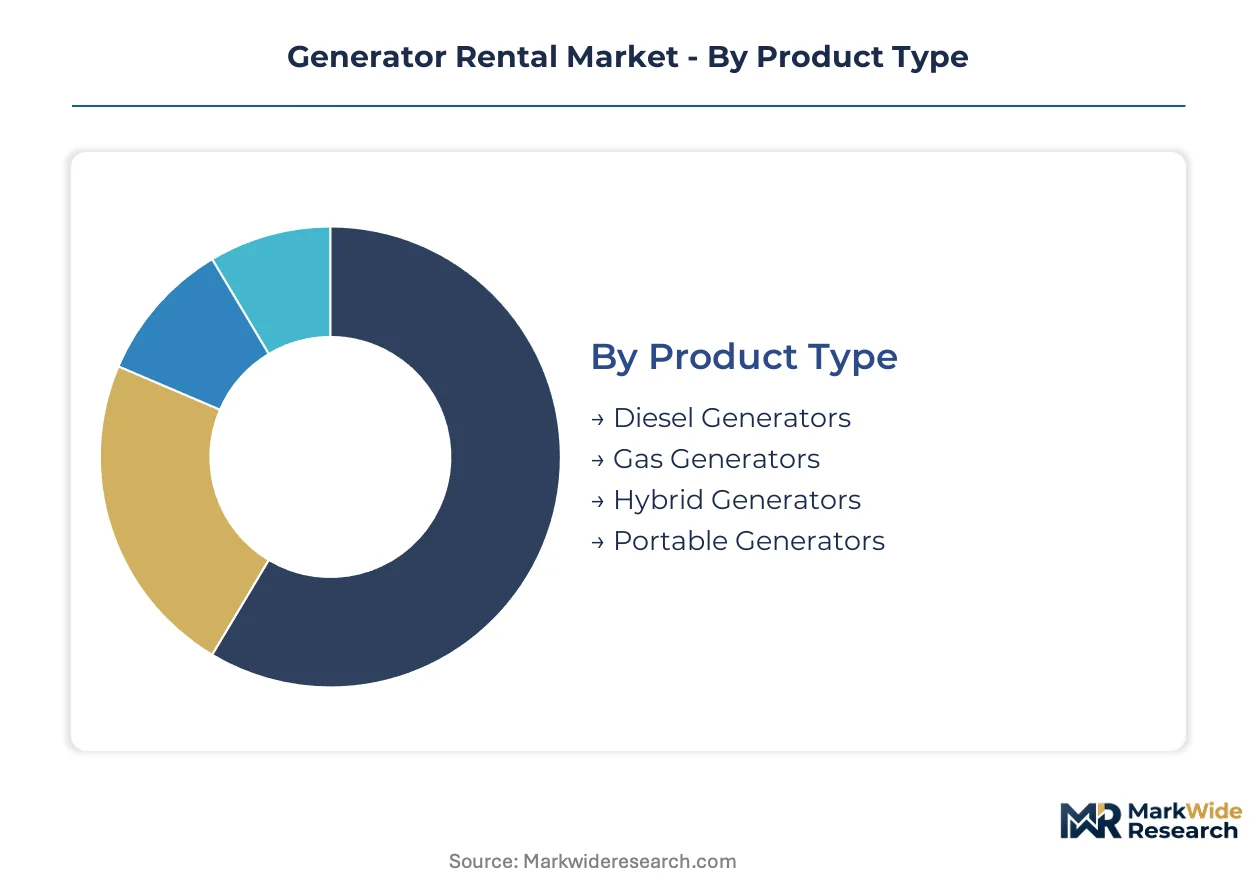
Generator rental segmentation reveals distinct capital intensity patterns across equipment categories. Diesel and hybrid units command longer depreciation schedules than portable gas alternatives, while emergency service contracts generate disproportionate margin concentration relative to standard rental terms.
Product Type:
Diesel and hybrid platforms anchor multi-year fleet cycles, whereas portable gas units turn over fastest due to lighter construction and lower replacement thresholds.
- Diesel Generators:Engine-driven alternator sets rated 20 kW to 2,000 kW with skid or trailer mounting dominate rental fleet composition. Construction firms across Texas and Florida specify these units for sustained load support where fuel availability and torque response outweigh emissions constraints.
- Hybrid Generators:Integrated lithium-ion storage with smart load management enables overnight operations under municipal noise curfews. Los Angeles and New York general contractors now specify these for concrete curing sequences, compressing payback periods for battery-augmented capital.
- Gas Generators:Spark-ignition units serve lower-load event applications with reduced particulate output.
- Portable Generators:Compact sub-20 kW units address residential backup and small-scale commercial needs.
Diesel generators dominate installed base. Hybrid generators are where expansion concentrates.
End User:
Industrial and construction segments absorb the highest equipment throughput, while residential and event verticals concentrate margin in premium short-term deployments.
- Construction:General contractors and specialty trades account for the largest revenue pool, with battery-genset hybrids gaining share in urban high-rise corridors. EPA Tier 4 Final compliance costs are reshaping procurement toward longer-term bundled agreements covering installation and certified grounding services.
- Industrial:Manufacturing and processing facilities require backup redundancy for production continuity. Data center operators in California negotiate extended contracts under state grid resilience mandates, stabilizing fleet utilization across seasonal troughs.
- Events:Film production and outdoor entertainment drive demand for silent-operation hybrid units.
- Residential:Hurricane-driven emergency volumes in Florida sustain dedicated inventory positioning.
Construction anchors fleet deployment. Industrial contracts are climbing the fastest.
Deployment:
Mobile configurations enable rapid asset redeployment between sites, while static installations lock capital into single-location long-term agreements.
- Mobile:Road-legal trailer mounting supports well-to-well mobility for Permian Basin oilfield operators. Aggreko and United Rentals compete through specialized mobile power modules engineered for remote drilling pads lacking transmission infrastructure.
- On-Site:Skid-mounted permanent positioning serves construction projects with multi-year timelines. OSHA temporary power regulations govern grounding protocols, creating compliance-driven demand for certified installation services.
- Off-Site:Yard-staged reserve capacity supports hurricane-season surge requirements.
- Static:Fixed industrial backup systems anchor long-term rental agreements.
Mobile deployment dominates revenue velocity. On-Site positioning is where contract duration extends.
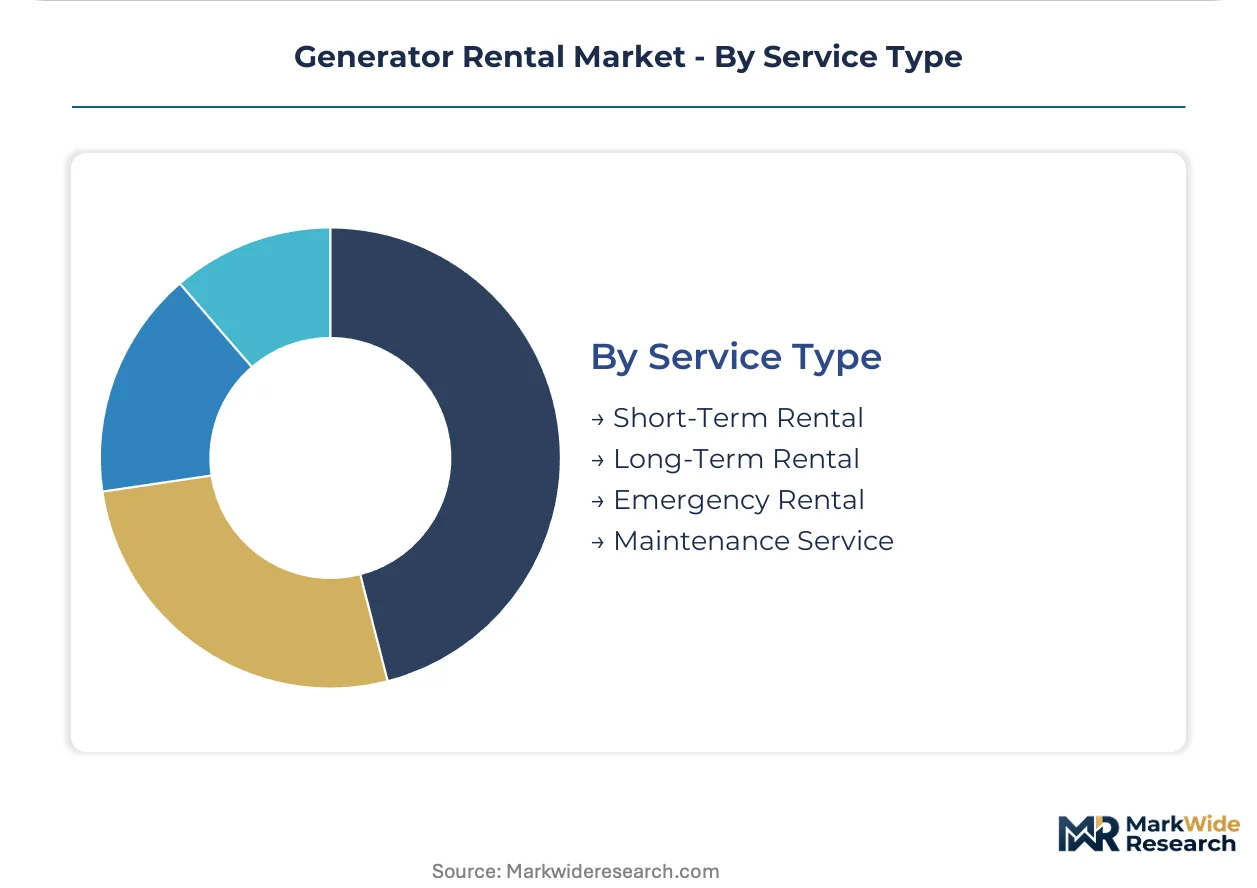
Service Type:
Emergency and short-term rentals command premium rate structures, while long-term agreements sacrifice per-day yield for utilization stability.
- Emergency Rental:Grid failure events trigger surge pricing with 24-hour technical response requirements. Florida and Gulf Coast markets justify dedicated hurricane-season inventory held in Texas yards.
- Long-Term Rental:Multi-year contracts stabilize fleet utilization and amortize EPA Tier 4 Final compliance investments across extended depreciation schedules. Project owners now specify fuel consumption guarantees and uptime service level agreements.
- Short-Term Rental:Higher per-day yields concentrate in event and seasonal construction peaks.
- Maintenance Service:Bundled technical support addresses skilled technician scarcity in remote deployment zones.
Long-Term Rental dominates capital deployment. Emergency Rental is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast pipeline network and Atlantic seaboard grid interconnects position the United States as the dominant geography for mobile power deployment, with hurricane corridors driving emergency rental infrastructure investment.
United States
Construction electrification and data center expansion fuel diesel and hybrid generator demand across Texas, California, and Florida. EPA Tier 4 Final enforcement tightens compliance timelines for rental fleet operators, elevating operational overhead. Houston and Miami metropolitan corridors concentrate hurricane-season surge capacity in dedicated rental yards.
Germany
Industrial manufacturing continuity requirements and renewable energy intermittency drive backup power procurement. The country's national environmental regulator enforces strict emissions standards for non-road mobile machinery, accelerating hybrid fleet adoption. The Rhine-Ruhr industrial belt anchors long-term rental contracts for manufacturing facility redundancy.
China
Infrastructure construction and manufacturing base electrification absorb substantial mobile power capacity. The Ministry of Ecology and Environment implements dual carbon goals that reshape fleet composition toward lower-emission alternatives. The Yangtze River Delta construction corridor generates concentrated demand for portable generator deployment.
India
Grid reliability gaps and construction sector expansion sustain diesel generator rental growth. The Central Electricity Authority mandates backup power standards for critical infrastructure, expanding contract scopes. Maharashtra and Gujarat industrial clusters drive multi-year rental agreements for manufacturing continuity.
Brazil
Mining operations and agricultural processing require remote power solutions beyond grid reach. The national environmental regulator enforces emissions protocols for non-road equipment, elevating compliance costs for rental operators. São Paulo state construction activity concentrates demand for mobile generator deployment.
Generator Rental Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying engine and alternator hardware. The vendor base organizes around three strategic archetypes: national rental networks with branch density advantages, specialized mobile power providers serving remote industrial zones, and equipment manufacturers operating captive rental divisions. Consolidation pressures intensify as EPA compliance costs favor scale economies, while geographic expansion and portfolio diversification emerge as dominant competitive vectors.
Within the national rental network tier, United Rentals and Sunbelt Rentals exemplify branch-density strategies that enable same-day metropolitan deployment. Aggreko occupies a position among specialized mobile power providers engineered for remote oilfield and industrial applications. These three anchors represent divergent capital deployment philosophies: density-driven coverage, surge-capacity positioning, and remote-site specialization.
| Leading Market Players |
|---|
| Herc Rentals |
| Sunbelt Rentals |
| United Rentals |
| Caterpillar |
| Cummins |
| Aggreko |
| Atlas Copco |
| H&E Equipment Services |
| Ashtead Group |
| Others |
Cost & Logistics Intelligence
Engine and alternator manufacturing concentrates in the United States, Germany, and Japan, anchoring margin capture at the component tier while rental operators downstream absorb Tier 4 Final compliance cost inflation through extended contract structures. This upstream concentration limits price-setting autonomy for fleet operators negotiating with construction and industrial end users.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by EPA certification grade and service bundling intensity. Premium tiers command rate premiums for hybrid-battery units with guaranteed uptime SLAs, while standard diesel-only rentals compete on day-rate transparency. Cost compression in the economy tier is intensifying because portable gas unit oversupply in hurricane corridors compresses spot pricing during off-peak seasons. Residential backup buyers exhibit highest price sensitivity, whereas data center operators prioritize reliability guarantees over rate negotiation.
Supply Chain Analysis
Diesel engine castings and alternator windings draw from foundry capacity in the United States, Germany, and China, with lithium-ion battery packs sourcing from South Korean and Japanese cell manufacturers. Selective catalytic reduction hardware and diesel particulate filters introduce single-source vulnerability for Tier 4 Final compliant units. Distribution runs through equipment dealership networks and direct rental yard procurement, with national account teams increasingly disintermediating regional broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
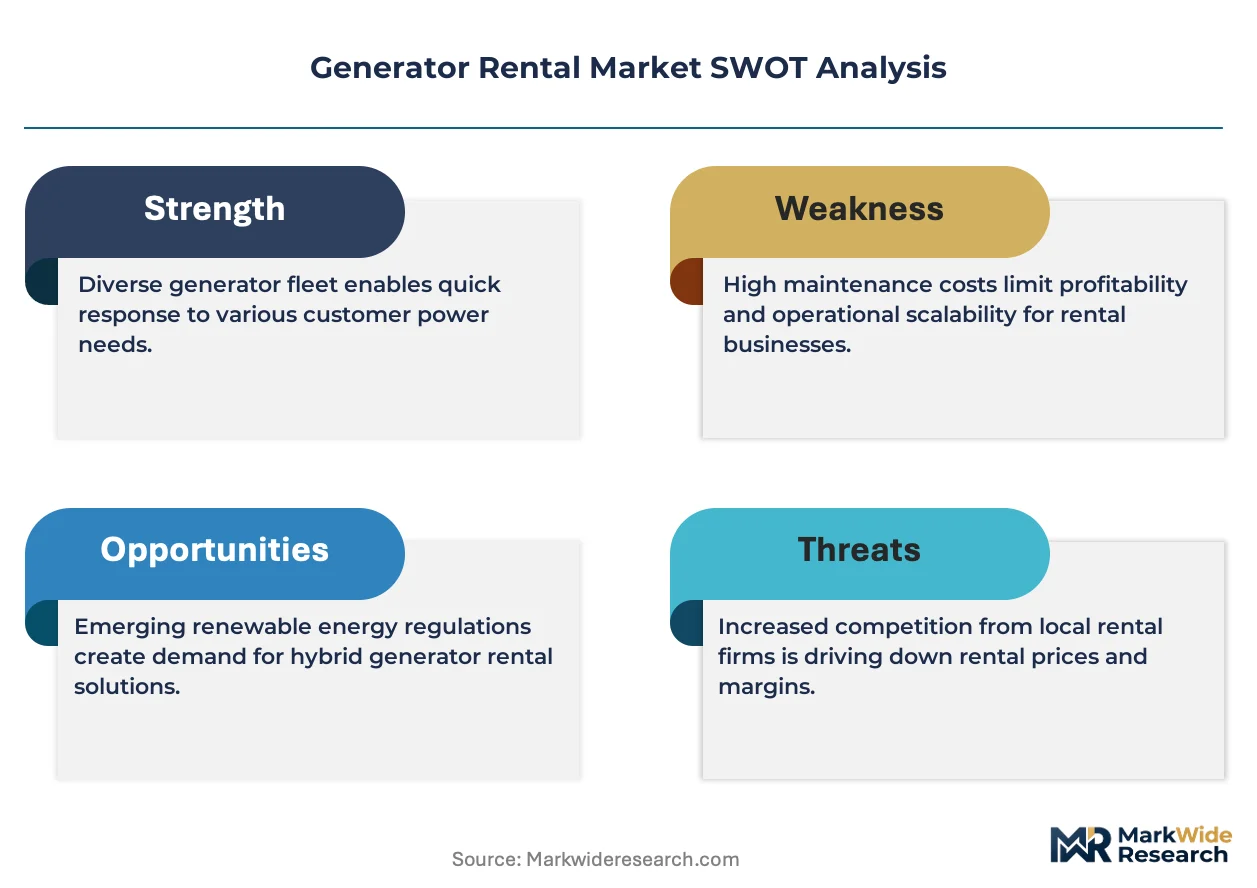
This market is positioned for cyclical recovery as Atlantic hurricane intensity sustains emergency rental demand surges that justify dedicated inventory positioning. Construction electrification mandates in California and New York accelerate hybrid fleet replacement cycles, creating capital deployment windows for prepared operators.
For Market Incumbents: Build regulatory compliance moats through EPA-certified service technician training programs that address skilled labor scarcity in remote deployment zones. Aggreko and United Rentals should deepen backward integration into hybrid power module assembly to capture battery hardware margins currently flowing to third-party integrators. Fleet operators must lock in long-term service agreements with Permian Basin oilfield developers before drilling activity peaks strain mobile power availability.
For New Entrants and Emerging Players: Establish a beachhead in microgrid-as-a-service bundling for film production and outdoor entertainment verticals, where silent-operation hybrid specifications create defensible niche positioning. California zero-emission construction corridors offer the most penetrable geography given CARB enforcement timelines that disadvantage legacy diesel-only incumbents. New entrants should pursue certified installation partnerships with general contractors rather than competing on equipment-only rental rates.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional rental networks in Florida and Texas that lack capital scale for Tier 4 Final fleet turnover. Long-term viability across the analysis window hinges on hybrid-electric technology transition execution and hurricane-season inventory utilization rates. Investors should monitor state-level zero-emission equipment mandate propagation as the signal indicating accelerated capital redeployment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Fleet Conversion | CARB and EPA Tier 4 Final compliance positions operators for California and New York construction contracts. |
| Hurricane Surge Capacity Expansion | Dedicated Texas and Florida yard inventory captures premium emergency rental pricing during grid failure events. |
| Microgrid-as-a-Service Bundling | Integrated generation-storage-control systems address film production and data center backup requirements. |
| Certified Technician Training Programs | OSHA-compliant installation services differentiate rental offerings amid skilled labor scarcity. |
| Permian Basin Mobile Power Positioning | Well-to-well mobility specifications align with oilfield electrification trends in remote drilling pads. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA enforcement documentation, EIA grid reliability data, and construction spending databases. The analysis incorporates structured interviews with fleet operations directors, construction procurement managers, oilfield power engineers, and EPA compliance officers. Secondary validation draws from FERC outage reports, state public utility commission filings, and equipment manufacturer technical specifications. Bottom-up rental yard capacity modeling triangulates against top-down construction and industrial power demand projections.
Forecast inputs span diesel and hybrid generator deployment by end-use vertical, service contract duration tier, and regional regulatory cluster across the projection horizon. The analytical framework segments by product type, end user industry, deployment configuration, and service arrangement. CAGRs derive from equipment replacement cycle analysis, emissions compliance cost trajectories, and grid resilience investment patterns. Hurricane frequency modeling and state-level zero-emission mandate adoption curves inform regional demand distribution.
Sensitivities concentrate around EPA enforcement intensity, battery cell supply constraints, and utility grid hardening investment pace that could compress emergency rental windows. Cross-checking against National Oceanic and Atmospheric Administration storm activity forecasts and state renewable portfolio standard implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Residential Gas Generator Market
Generators
Turbo Generator Market
Generators
Generator Belt Market
Generators
Generator [Up to 100 Kva] Market
Generators
India Generator Sets Market
Generators
Marine Gensets Market
Generators
Tri Fuel Generators Market
Generators
Europe Portable Generator Market
Generators
Global Portable Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Mobile Generators Market
Generators
Asia-Pacific Gas Generator Market
Generators
Containerized Solar Generators Market
Generators
Generator Sets Market
Generators
Wind Turbine Alternator Market