
 Middle East Distribution Transformer Market | 2026-2036
Middle East Distribution Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Distribution Transformer Market Analysis
Project finance tied to sovereign wealth infrastructure programs is narrowing the competitive field for distribution transformer suppliers. Siemens Energy leverages its regional manufacturing footprint to anchor long-term service contracts across GCC utility networks. Alfanar Group competes on localized coil winding and core assembly capacity that reduces import dependency for Saudi projects. Emirates Transformers & Switchgears Factory LLC dominates aftermarket retrofit demand through its Dubai-based technical service infrastructure.
Distribution transformers are electromagnetic devices that step down medium-voltage grid power to utilization voltages through oil-immersed or dry-type insulation systems, typically operating at frequencies of 50 Hz across Middle East grids. These units serve as the final voltage conversion stage before electricity reaches industrial motors, commercial HVAC systems, and residential clusters. Three-phase oil-immersed units lead the product mix due to thermal performance advantages in Gulf climates, while dry-type installations are gaining share in indoor commercial and high-rise residential settings where fire safety codes restrict liquid insulation. Pad-mounted configurations occupy the fastest-growing installation category as Saudi Arabia's NEOM and Red Sea Project developments prioritize aesthetic integration and reduced land use.
Saudi Standards, Metrology and Quality Organization (SASO) efficiency mandates and UAE's Emirates Authority for Standardization and Metrology (ESMA) registration requirements are reshaping import eligibility and local testing obligations for transformer suppliers. Gulf Standardization Organization (GSO) harmonization efforts are pushing manufacturers toward unified efficiency labeling across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and UAE. Stakeholders must monitor how Saudi Arabia's domestic content regulations and UAE's In-Country Value programs redirect procurement toward joint-venture or wholly-owned local production facilities.
Market Dynamics
Sovereign wealth infrastructure programs are compressing procurement timelines while tightening local content requirements across Saudi Arabia and UAE utility networks. Grid operators now bundle long-term service contracts with initial equipment awards, favoring manufacturers with regional coil winding and core assembly capabilities.
Growth Catalysts
- NEOM and Red Sea Project developments:Saudi Arabia's giga-projects are generating concentrated demand for pad-mounted distribution transformers with aesthetic integration requirements and reduced land use footprints.
- SASO efficiency mandates:Saudi Standards, Metrology and Quality Organization regulations are phasing out lower-efficiency transformer tiers and accelerating replacement cycles across existing distribution networks.
- Smart city expansions:UAE's urban developments are specifying digitally monitored transformer assets with integrated condition monitoring for predictive maintenance protocols.
Market Restraints
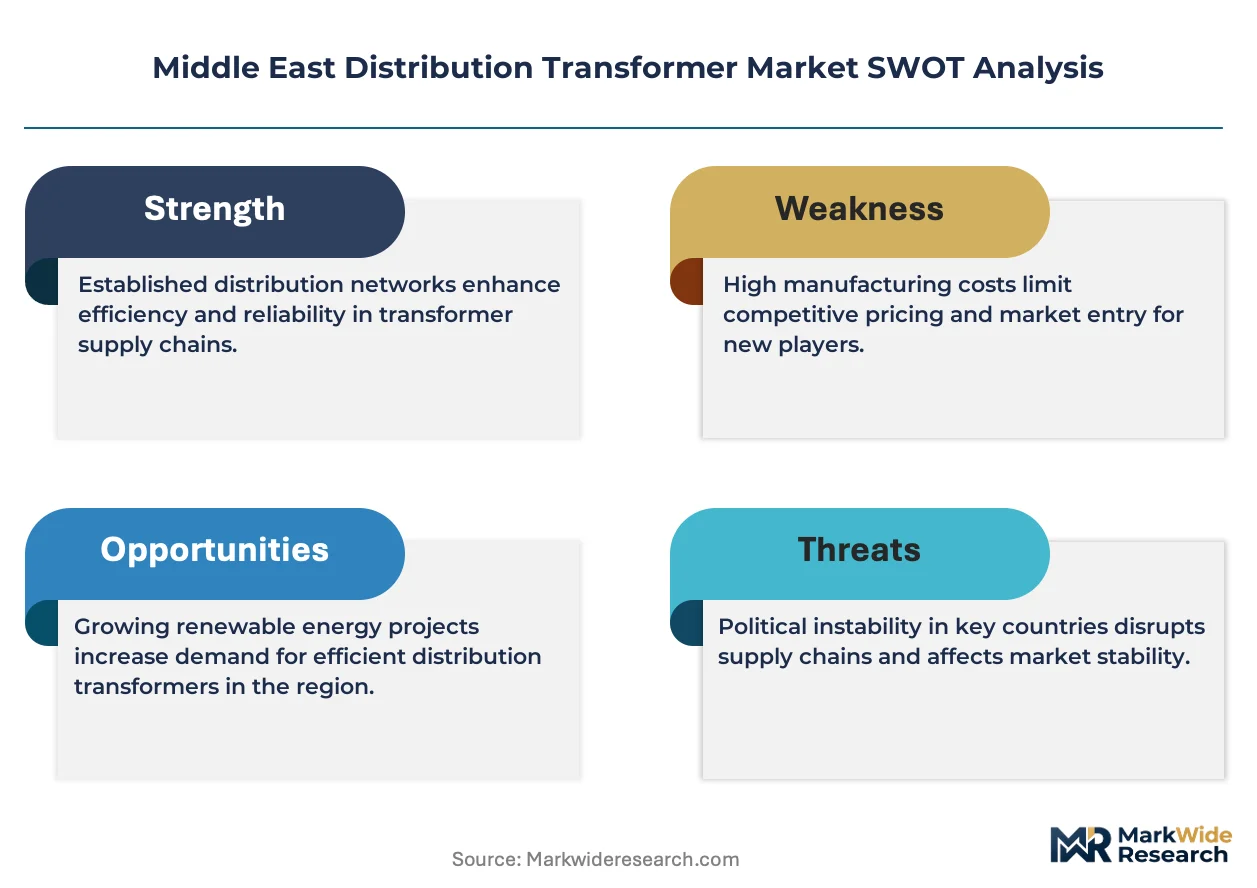
- Grain-oriented electrical steel concentration:Core material supply concentrates among a limited set of Asian and European metallurgical producers, exposing regional transformer manufacturers to input cost volatility and extended lead times.
- Gulf Standardization Organization harmonization delays:Unified efficiency labeling timelines remain unresolved across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and UAE, fragmenting certification requirements.
- Dry-type thermal limitations:Air-cooled transformer designs face capacity ceilings in Gulf summer ambient temperatures, restricting deployment in heavy industrial loads despite fire safety advantages.
Strategic Opportunities
- Oman and Kuwait grid modernization:Underpenetrated utility sectors in these markets present first-mover advantages for suppliers with established GCC manufacturing footprints and GSO certification pathways.
- Renewable integration clusters:Utility-scale solar and wind developments require specialized transformer specifications for variable load profiles and bidirectional power flow management.
- In-Country Value programs:UAE's procurement incentives reward joint-venture structures and local production facilities, creating structural advantages for manufacturers with Dubai or Abu Dhabi assembly presence.
Industry Challenges
- Specialized winding technician scarcity:Regional vocational pipelines produce insufficient numbers of coil winding specialists capable of meeting SASO and ESMA precision tolerances for medium-voltage transformer manufacturing.
- Multi-standard certification complexity:Manufacturers must simultaneously satisfy IEC 60076 efficiency tiers, GSO harmonization drafts, and country-specific testing protocols, extending product qualification timelines.
- Legacy oil-immersed asset integration:Grid operators face technical friction retrofitting condition monitoring sensors onto installed transformer fleets with aged bushing and terminal configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Distribution Transformer Market |
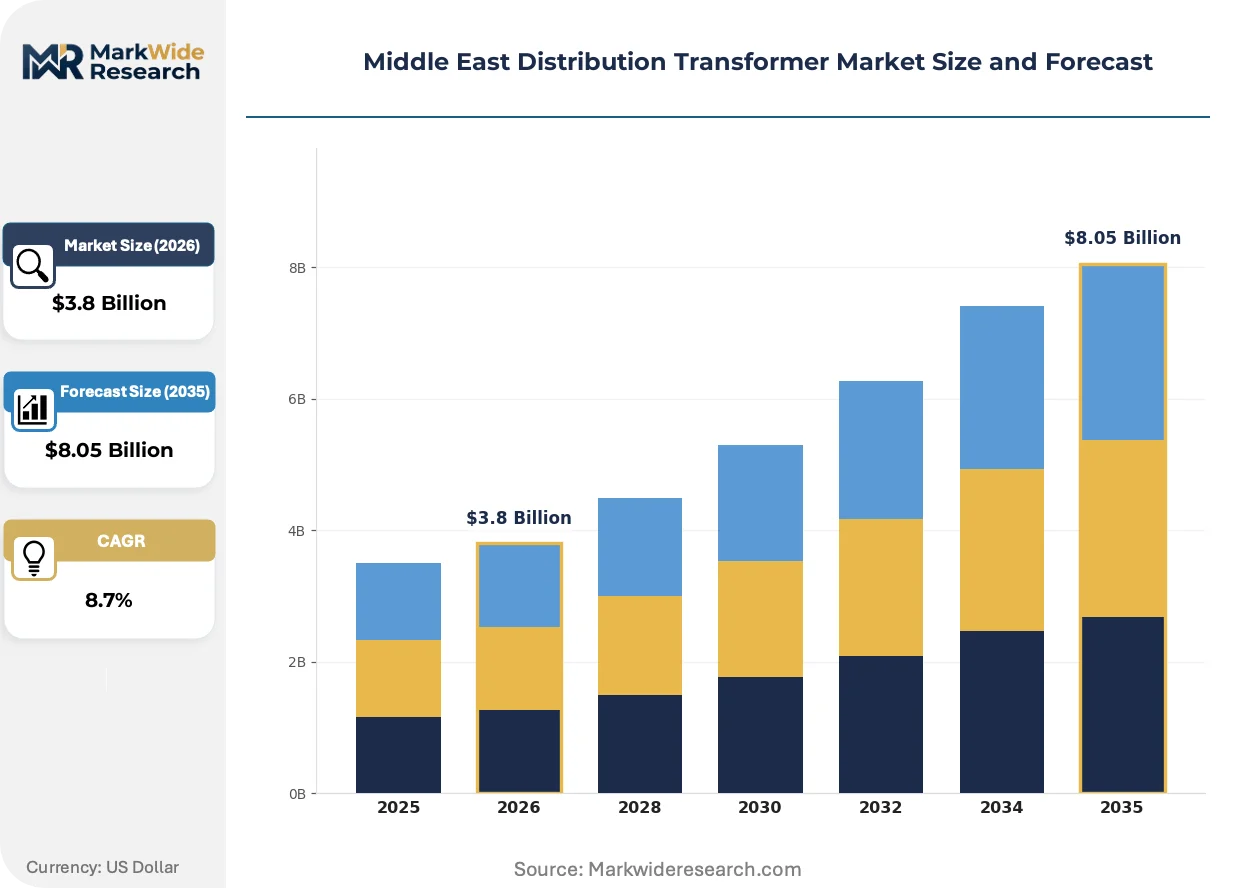
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Oil-Immersed, Dry-Type End User: Residential, Commercial, Industrial, Utility Installation: Indoor, Outdoor, Pole-Mounted, Pad-Mounted Power Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | Saudi Transformers Company Ltd., ABB Ltd., Siemens Energy, CG Power and Industrial Solutions Limited, Emirates Transformers & Switchgears Factory LLC, GE Vernova, Alfanar Group, Voltamp Transformers Limited, Schneider Electric, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Distribution Transformer Market Emerging Trajectories
Transformer technology trajectories across the Middle East center on thermal performance optimization, digital monitoring integration, and procurement model restructuring. These developments respond simultaneously to Gulf climate constraints and sovereign wealth program requirements.
Amorphous metal core technology is migrating from niche commercial applications toward utility-scale deployment in Saudi Arabia's renewable integration zones. Distribution network operators in NEOM and Red Sea Project developments specify these cores for reduced no-load losses despite higher initial capital outlay. The technology is compressing total cost-of-ownership calculations across 25-year asset lifecycles.
Gulf Standardization Organization efficiency harmonization is consolidating previously fragmented national standards across six member states. Unified labeling requirements eliminate redundant testing protocols for manufacturers supplying multiple GCC markets. Saudi Arabia and UAE grid operators are accelerating procurement alignment with draft GSO tiers ahead of formal implementation.
Performance-based service contracting is displacing traditional equipment-only procurement across UAE utility networks. Abu Dhabi and Dubai distribution companies unbundle transformer assets from long-term maintenance obligations, awarding integrated availability contracts to manufacturers with regional technical service infrastructure. This restructuring concentrates aftermarket revenue among suppliers with established Dubai-based spare parts and field engineering capabilities.
Middle East Distribution Transformer Market Segmentation
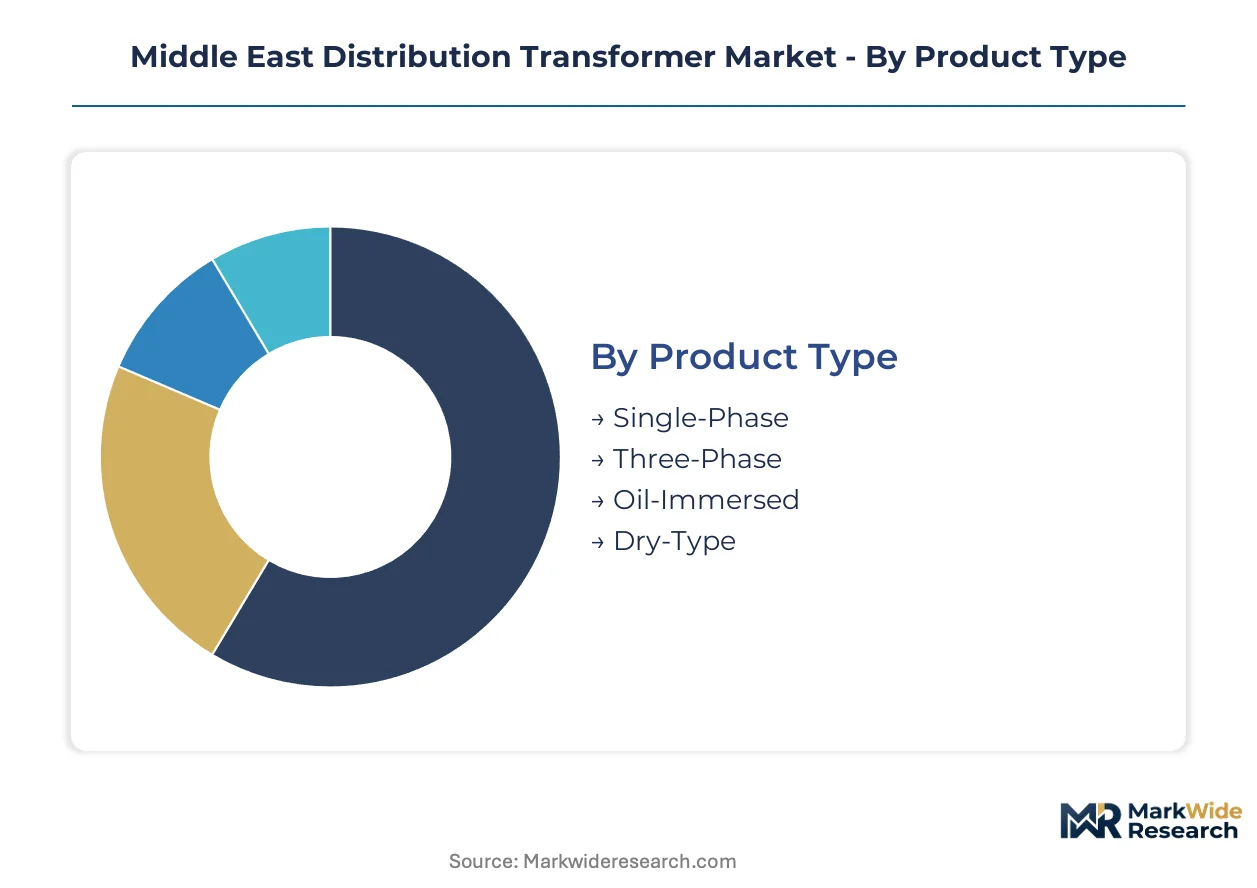
Segmentation in the Middle East distribution transformer market reveals distinct procurement cycles, replacement timelines, and technology preferences across product configurations and end-use applications. Understanding these patterns enables suppliers to align manufacturing capacity with the region's infrastructure buildout priorities.
Product Type:
Replacement cycles vary dramatically across product categories, with oil-immersed units turning over fastest due to Gulf climate stress while dry-type assets enjoy extended service intervals in controlled indoor environments.
- Three-Phase:These units dominate utility-scale deployments across Saudi Arabia's NEOM and Red Sea Project developments, where centralized power distribution demands higher capacity ratings. Procurement concentrates in pad-mounted configurations with aesthetic integration requirements for giga-project master plans.
- Oil-Immersed:Liquid insulation systems deliver superior thermal performance in ambient temperatures exceeding 50°C across UAE and Qatar summer peaks. Demand clusters in outdoor industrial installations where fire safety codes permit hydrocarbon-based cooling.
- Single-Phase:Rural electrification programs in Oman and rural Saudi Arabia deploy these units for isolated residential clusters with modest load profiles.
- Dry-Type:Air-cooled designs gain traction in Dubai high-rise commercial towers and UAE smart city districts where building codes prohibit oil-filled equipment indoors.
Three-Phase oil-immersed configurations anchor the volume base while Dry-Type resin-cast units gain share at the steepest rate in premium commercial developments.
End User:
Customer-type segmentation exposes divergent procurement sophistication, with utility buyers bundling long-term service contracts while industrial purchasers prioritize thermal performance specifications.
- Utility:Saudi Electricity Company and Dubai Electricity & Water Authority dominate procurement volumes, specifying IEC 60076 efficiency tiers with integrated condition monitoring for predictive maintenance protocols.
- Industrial:Petrochemical complexes in Jubail and aluminum smelters in Bahrain demand heavy-duty ratings with bidirectional power flow capabilities for captive renewable integration.
- Commercial:UAE mall developers and Saudi hospitality projects prioritize compact footprints and reduced noise emissions for urban deployment.
- Residential:Master-planned communities across Riyadh and Abu Dhabi specify standardized ratings for repetitive procurement efficiency.
Utility procurement commands the largest contract values while Industrial specifications are expanding most quickly amid manufacturing diversification initiatives.
Installation:
Physical deployment modes reflect land-use constraints and aesthetic priorities across the region's divergent urban planning philosophies.
- Pad-Mounted:Compartmentalized steel enclosures integrate seamlessly into NEOM's underground utility corridors and Red Sea Project landscape-sensitive master plans. These configurations eliminate visual clutter while enabling faster installation cycles.
- Outdoor:Conventional substation-grade installations persist across legacy Saudi and Kuwaiti distribution networks with available land buffers.
- Pole-Mounted:Overhead distribution remains prevalent in Bahrain and Oman secondary networks with established line infrastructure.
- Indoor:Basement and dedicated electrical room placements concentrate in Dubai Marina towers and Riyadh financial district high-rises.
Outdoor installations maintain the installed base while Pad-Mounted configurations climb the fastest as giga-projects advance.
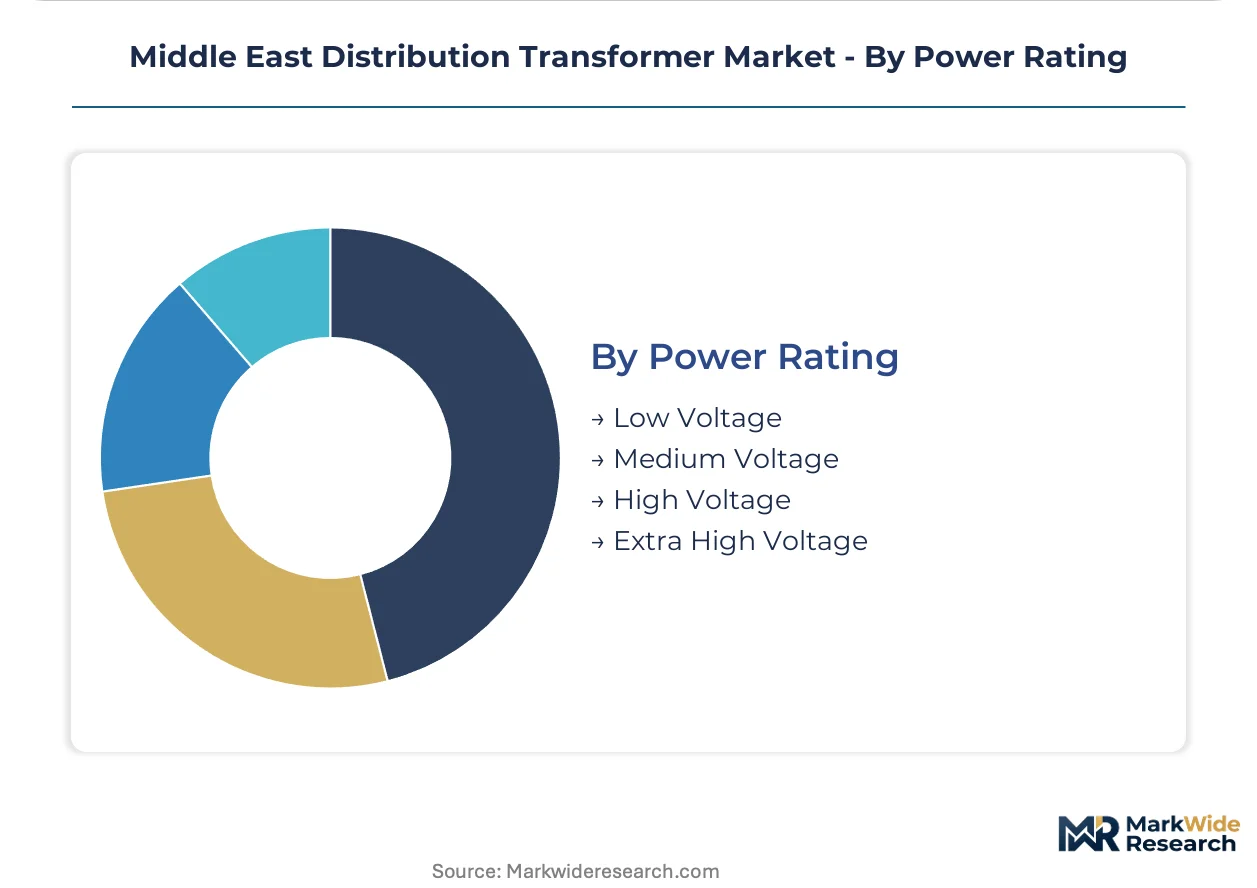
Power Rating:
Voltage tier segmentation correlates directly with grid hierarchy position and regulatory jurisdiction across national transmission operators.
- Medium Voltage:11kV and 33kV ratings bridge distribution substations to final utilization points across Saudi Arabia's 110kV sub-transmission backbone. Procurement volumes concentrate in ratings compatible with SASO efficiency mandate thresholds.
- Low Voltage:415V three-phase and 230V single-phase units serve final delivery to industrial motors and residential clusters with standardized kVA ranges.
- High Voltage:66kV and 132kV ratings support interconnection between transmission and distribution networks in UAE and Qatar grid expansions.
- Extra High Voltage:220kV and above ratings remain specialized for transmission-distribution interface points in Saudi Arabia's national grid backbone.
Medium Voltage ratings dominate procurement volumes while Low Voltage segments show the steepest expansion trajectory in distributed solar integration zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO efficiency mandates and sovereign wealth infrastructure programs are redirecting procurement toward localized manufacturing capacity across Gulf Cooperation Council member states. Grid operators now bundle long-term service contracts with equipment awards, compressing supplier qualification timelines.
Saudi Arabia
NEOM and Red Sea Project developments are generating concentrated demand for pad-mounted distribution transformers with aesthetic integration requirements. SASO regulations are phasing out lower-efficiency transformer tiers and accelerating replacement cycles. Riyadh and the Eastern Province host the densest clusters of coil winding and core assembly facilities serving domestic giga-projects.
United Arab Emirates
Dubai Electricity & Water Authority and Abu Dhabi distribution companies specify digitally monitored transformer assets with integrated condition monitoring. ESMA registration requirements are reshaping import eligibility and local testing obligations. Dubai-based technical service infrastructure dominates aftermarket retrofit demand across commercial high-rise developments.
Qatar
Utility-scale renewable integration is widening procurement specifications for bidirectional power flow management. The country's national standardization body aligns with Gulf Standardization Organization harmonization drafts ahead of formal implementation. Doha and surrounding industrial zones concentrate demand for heavy-duty ratings in petrochemical and aluminum smelting applications.
Oman
Rural electrification programs deploy single-phase units for isolated residential clusters with modest load profiles. Underpenetrated utility sectors present first-mover advantages for suppliers with established GCC manufacturing footprints. Muscat and northern coastal regions anchor grid modernization investments targeting secondary network infrastructure.
Kuwait
Legacy distribution networks with available land buffers maintain conventional outdoor substation-grade installations. The Ministry of Electricity & Water procurement patterns favor bundled awards combining equipment supply with multi-year maintenance obligations. Al-Jahra and southern industrial areas concentrate replacement demand for aging oil-immersed assets.
Middle East Distribution Transformer Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturers with regional coil winding and core assembly capabilities that satisfy domestic content regulations. Tiered competitive positioning separates integrated energy conglomerates with full-service portfolios from specialized transformer fabricators focused on medium-voltage ratings. Strategic archetypes include sovereign-backed local champions, European engineering majors with GCC manufacturing footprints, and Indian exporters leveraging cost-advantaged production. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for giga-project procurement cycles.
Among regional specialists, Emirates Transformers & Switchgears Factory LLC and Saudi Transformers Company Ltd. exemplify the sovereign-backed local champion archetype, anchoring aftermarket service revenue through technical infrastructure proximity to major grid operators. Siemens Energy occupies a position representing European engineering majors with established regional manufacturing presence. Alfanar Group sits within the diversified industrial conglomerate tier, leveraging backward integration into electrical steel sourcing and localized assembly capacity.
| Leading Market Players |
|---|
| Saudi Transformers Company Ltd. |
| ABB Ltd. |
| Siemens Energy |
| CG Power and Industrial Solutions Limited |
| Emirates Transformers & Switchgears Factory LLC |
| GE Vernova |
| Alfanar Group |
| Voltamp Transformers Limited |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Riyadh's coil winding and core assembly cluster concentrates regional manufacturing capacity, granting suppliers with localized facilities pricing leverage over import-dependent competitors bidding on Saudi giga-projects. This geographic concentration compresses margins for European and Indian exporters while rewarding joint-venture structures that satisfy SASO domestic content thresholds.
Pricing Analysis
Certification level creates the primary spread across the Middle East distribution transformer market. IEC 60076 efficiency tier compliance separates premium-rated units from standard-grade alternatives, while GSO harmonization drafts fragment certification costs across multiple national testing protocols. Pricing pressure stems from grain-oriented electrical steel cost volatility transmitted through Asian metallurgical supply contracts. Industrial buyers in Jubail petrochemical complexes exhibit lowest price sensitivity due to thermal performance priorities, while rural electrification programs in Oman prioritize unit economics over efficiency premiums.
Supply Chain Analysis
Extended payment terms from Saudi Electricity Company and Dubai Electricity & Water Authority are reshaping supplier working capital requirements across the transformer value chain. Core material supply draws from Japanese and South Korean grain-oriented electrical steel producers, with copper winding conductors sourced through UAE trading hubs. Single-source vulnerability concentrates in specialized amorphous metal core feedstock for NEOM renewable integration specifications. Distribution runs through EPC contractors bundling transformer procurement within giga-project construction packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Gulf Standardization Organization implementation timelines creates niche opportunities for suppliers with multi-country certification capabilities. Sovereign wealth program bundling of equipment and long-term service contracts is splintering procurement into specialized availability-based segments.
For Market Incumbents: Pre-empt emerging competition from Indian cost-advantaged exporters by deepening Dubai-based technical service infrastructure for aftermarket retrofit contracts. Secure coil winding technician pipelines through vocational partnerships with Saudi technical institutes before SASO precision tolerance requirements tighten further. Anchor long-term service agreements with Abu Dhabi distribution companies before performance-based contracting becomes mandatory.
For New Entrants and Emerging Players: Build out GSO certification pathways ahead of formal harmonization implementation to capture first-mover positioning in Kuwait and Oman grid modernization cycles. Target rural electrification segments in northern Oman where procurement sophistication lags Saudi utility-scale deployments. Enter through joint-venture structures with established UAE assembly facilities to satisfy In-Country Value program scoring thresholds.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure services play because sovereign wealth program bundling is transforming hardware margins into recurring availability revenue streams. Acquisition targets should prioritize regional technical service infrastructure over pure manufacturing capacity. Monitor Gulf Standardization Organization formal implementation announcements as the signal for certification cost rationalization and margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Manufacturing Footprint Expansion | Local coil winding capacity satisfies SASO domestic content mandates for NEOM procurement. |
| Long-Term Service Contracting | Integrated availability agreements with DEWA transform equipment sales into recurring revenue. |
| Amorphous Metal Core Technology Licensing | Reduced no-load losses align with Saudi renewable integration zone specifications. |
| GSO Harmonization Pre-Certification | Multi-country testing protocols eliminate redundant qualification costs across GCC markets. |
| Technical Service Infrastructure Buildout | Dubai-based spare parts and field engineering capabilities capture aftermarket retrofit demand. |
Methodological Framework
A standing panel of utility planning officers, EPC procurement managers, transformer manufacturing executives, and grid operators provided ongoing calibration across the primary research phase. This practitioner input combined with customs and trade data, IEC certification registries, SASO and ESMA filing documentation, and sovereign wealth program procurement disclosures. Bottom-up project pipeline aggregation triangulated against top-down grid investment forecasts derived from national transmission operator capex disclosures.
Scenario bracketing around GSO harmonization implementation timelines and grain-oriented electrical steel price volatility bands bounded the projection range across the analysis window. Segmentation modeling incorporated product type, installation configuration, end-use application, power rating tier, and national regulatory framework dimensions. CAGRs were derived from unit shipment trajectories weighted by efficiency tier premium coefficients and service contract bundling penetration assumptions.
Stress conditions across metallurgical input cost spikes, GSO implementation delays, and technician training pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sovereign wealth program execution schedules and efficiency mandate enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
United States Transformer Market
Transformers
Uninhibited Transformer Oil Market
Transformers
Europe Distribution Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Step Up/Down Transformers Market
Transformers
North America Oil Filled Transformer Market
Transformers
High Frequency Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
Canada Transformer Market
Transformers
India Power Transformer Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Middle East and Africa Transformer Market
Transformers
China Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Rectifier Transformers Market