
 Saudi Arabia Diesel Generator Market | 2026-2036
Saudi Arabia Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Diesel Generator Market Analytics
SASO energy efficiency certification is bifurcating the competitive landscape into qualified and non-qualified supplier tiers. Caterpillar Inc. leverages its Riyadh service infrastructure to sustain long-term maintenance contracts across Aramco-linked sites. Cummins Arabia anchors its position through localized assembly capacity at Dammam facilities, reducing import lead times for above-500 kVA units. Saudi Diesel Equipment Co. Ltd. differentiates via deep channel control across municipal and defense procurement verticals.
A diesel generator converts mechanical energy from compression-ignition engines into electrical power through rotating alternators, typically operating at 50 Hz with voltage outputs of 220-480V for Saudi grid synchronization. Canopy-set configurations dominate commercial installations where noise attenuation below 75 dBA at 1 meter satisfies urban building codes, while trailer-mounted units capture fastest growth in construction mobility applications. Above-500 kVA power rating segments concentrate margin pools due to engineering complexity and aftermarket service attachment rates.
SFDA and SASO jointly enforce emission thresholds and fuel efficiency benchmarks that determine market access eligibility for imported generator sets. MOF procurement guidelines now mandate local content minimums for public infrastructure power backup, redirecting supply chain configurations toward domestic assembly partners. Stakeholders must monitor how renewable-integration mandates for new industrial zones reshape standby power specifications and diesel generator run-hour limitations.
Market Dynamics
SASO efficiency mandates and SFDA emission protocols are compressing product certification timelines while megaproject construction in Riyadh and Jeddah accelerates procurement cycles for above-500 kVA units.
Growth Catalysts
- NEOM and Red Sea Project Timelines:Compressed construction schedules across giga-projects are pulling forward diesel generator orders for site electrification and concrete batching operations.
- SASO Energy Efficiency Certification:Mandatory efficiency benchmarks for imported generator sets are filtering out low-tier suppliers and concentrating procurement among qualified vendors with established Saudi service networks.
- Aramco Expansion Clusters:Upstream and downstream capacity additions in the Eastern Province are driving continuous demand for industrial-grade standby power systems.
Market Restraints
- Diesel Price Volatility:Fluctuations in domestic fuel subsidy structures directly impact total cost of ownership calculations for fleet operators and construction contractors.
- Import Dependency for Above-500 kVA Engines:Core engine blocks for high-capacity units concentrate sourcing from limited overseas foundries, exposing lead time risks.
- Solar-Battery Hybrid Substitution:Falling lithium-ion storage costs and renewable-integration mandates for new industrial zones are eroding addressable market for pure diesel standby systems.
Strategic Opportunities
- MOF Local Content Mandates:Public infrastructure procurement guidelines now require domestic assembly minimums, creating partnership openings for foreign OEMs with Dammam-based facilities.
- Trailer-Mounted Mobility Segment:Construction mobility applications remain underpenetrated relative to canopy-set commercial installations, offering volume expansion potential.
- Remote Monitoring Convergence:Integration of IoT telemetry with predictive maintenance platforms enables outcome-based service contracts for Aramco-linked sites.
Industry Challenges
- Certification Timeline Compression:SFDA and SASO parallel review processes for emission and efficiency compliance are extending product launch cycles for new generator models.
- Skilled Technician Scarcity:Above-500 kVA alternator winding repair and electronic governor calibration require specialized training that outpaces local vocational pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Diesel Generator Market |
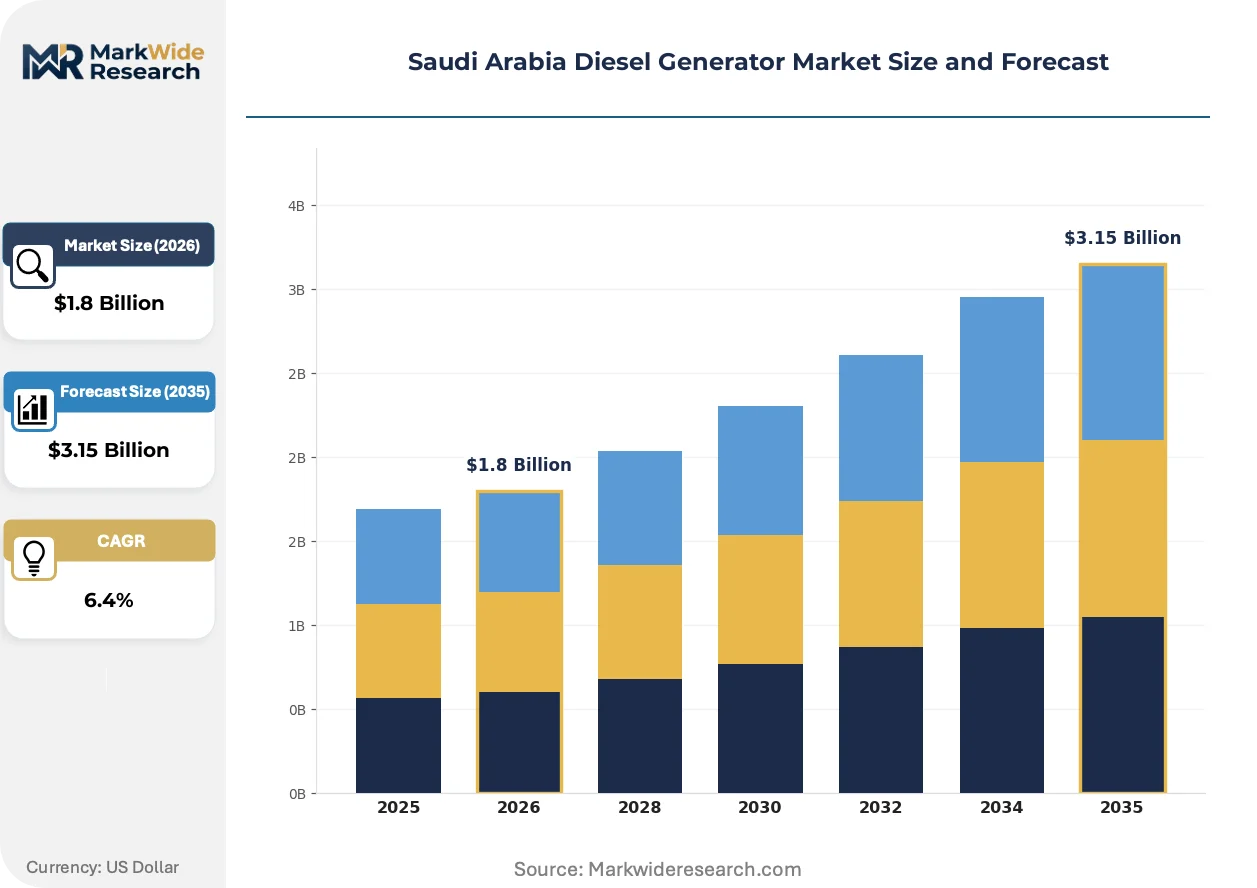
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open-Set, Canopy-Set, Trailer-Mounted, Rental End User: Construction, Oil & Gas, Manufacturing, Residential Power Rating: 1-100 kVA, 101-300 kVA, 301-500 kVA, Above 500 kVA Fuel Type: Diesel, Bio-Diesel, Synthetic Diesel, Others |
| Companies Covered | Kohler SDMO, Caterpillar Inc., Cummins Arabia, Generac Holdings Inc., Saudi Diesel Equipment Co. Ltd., Atlas Copco Industrial Equipment Co., Aksa Power Generation, Kirloskar DMCC, FG Wilson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Diesel Generator Market Evolving Landscape
Digital load management and hybrid architecture are reconfiguring how Saudi buyers evaluate standby power investments, shifting specification criteria from raw kVA output toward integrated system efficiency and remote operability.
Advanced electronic governors with precision frequency control are displacing mechanical speed regulation in above-500 kVA installations across Aramco expansion sites and municipal data centers. These digital systems enable tighter grid synchronization tolerances and faster transient response under variable load conditions. Procurement specifications from Eastern Province industrial clusters now mandate electronic governor inclusion, effectively filtering mechanical-governor suppliers from qualified bidding pools.
SFDA emission protocols are tightening particulate matter and NOx thresholds for diesel generator import eligibility, forcing OEMs to reconfigure exhaust after-treatment systems for Saudi-bound units. Engine manufacturers must now submit test-cell data from accredited laboratories demonstrating compliance across the Saudi ambient temperature range. The Eastern Province concentration of heavy industrial users faces the steepest adaptation curve as existing fleet replacement cycles compress to meet new certification deadlines.
Buyers across Riyadh commercial construction and Jeddah municipal infrastructure are unbundling generator procurement from long-term maintenance contracts, treating service agreements as separately negotiated performance instruments. This disintermediation pressures OEMs to demonstrate standalone service capabilities rather than relying on equipment margin cross-subsidies. Dammam-based assemblers with captive parts warehousing and technician deployment networks capture disproportionate share of this unbundled service spend.
Saudi Arabia Diesel Generator Market Segmentation
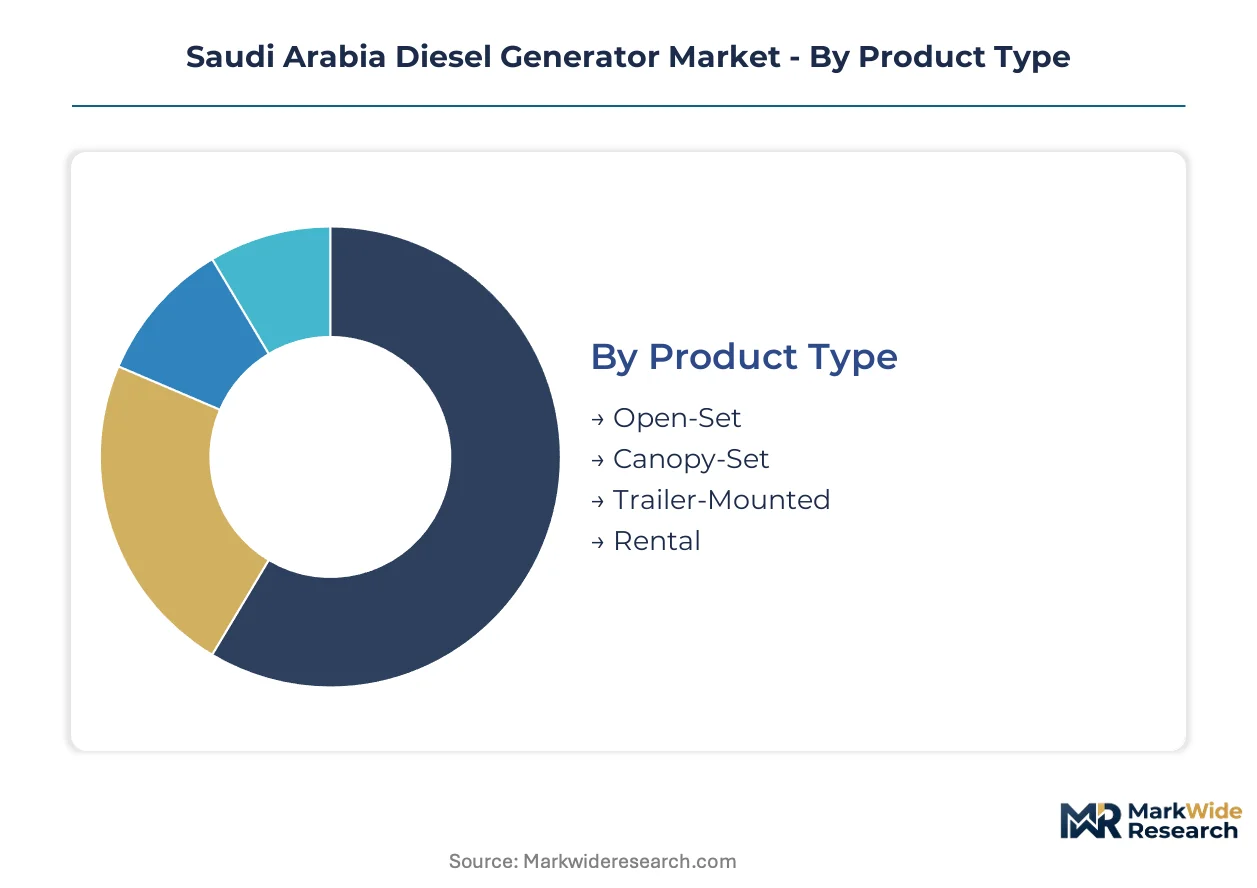
Diesel generator procurement patterns across Saudi Arabia diverge sharply by installation environment and mobility requirements. Channel economics favor different configurations for permanent industrial backup versus temporary construction electrification.
Product Type:
Channel distribution varies by mobility requirement and noise regulation exposure, with permanent installations flowing through engineering contractors and mobile units through rental fleets.
- Canopy-Set:Enclosed steel housings with integrated fuel tanks and acoustic insulation reduce noise emissions below 75 dBA at one meter. Demand concentrates across Riyadh commercial towers and Jeddah municipal facilities where urban building codes mandate sound attenuation. SASO certification timelines for canopy assemblies run longer due to combined engine and enclosure testing protocols.
- Trailer-Mounted:Highway-towable skid configurations with stabilizing outriggers enable rapid redeployment across NEOM and Red Sea Project sites. These units bypass permanent permitting requirements while satisfying temporary construction electrification needs. Eastern Province contractors prioritize trailer-mounted fleets for Aramco-linked maintenance turnaround schedules.
- Open-Set:Bare engine-alternator assemblies without enclosure suit controlled industrial environments with dedicated generator rooms. Oil & Gas facilities in the Eastern Province specify open-sets for indoor installation where external noise constraints do not apply.
- Rental:Short-term lease arrangements with bundled fuel and maintenance services address construction peak-load spikes. Rental penetration runs highest among tier-two contractors lacking capital allocation for fleet ownership.
By volume, Canopy-Set leads. By growth pace, Trailer-Mounted is expanding most quickly.
End User:
Customer procurement sophistication spans from specification-driven engineering departments to price-sensitive project managers.
- Oil & Gas:Upstream and downstream operators demand continuous-duty ratings with N+1 redundancy for process safety. Aramco expansion clusters in the Eastern Province specify electronic governors and remote telemetry as standard requirements. SFDA emission protocols force accelerated fleet replacement cycles at existing production facilities.
- Construction:General contractors prioritize capital efficiency and mobility over fuel optimization for temporary site power. Compressed timelines across giga-projects pull forward procurement of above-500 kVA units for concrete batching and tower crane operations.
- Manufacturing:Industrial city tenants in Jubail and Yanbu require seamless grid synchronization for sensitive production lines. These buyers unbundle equipment procurement from long-term service contracts, treating maintenance as separately negotiated performance instruments.
- Residential:Villa and compound developers specify compact canopy-sets for backup power during grid instability. Demand clusters in Riyadh and Jeddah high-end residential districts where power reliability expectations exceed national grid performance.
By revenue contribution, Oil & Gas dominates. By contract velocity, Construction is climbing the fastest.
Power Rating:
Engineering complexity and margin structure escalate non-linearly above 500 kVA threshold.
- Above 500 kVA:Heavy-duty industrial units with electronic fuel injection and precision alternator windings serve continuous-duty applications. Eastern Province petrochemical complexes and data centers concentrate demand for this segment. Import dependency for core engine blocks exposes lead time risks from limited overseas foundries.
- 301-500 kVA:Mid-range commercial units bridge small business backup and light industrial requirements. SASO efficiency certification mandates filter supplier qualification tiers most aggressively in this band.
- 101-300 kVA:Standard commercial backup configurations for retail and hospitality sectors. Municipal procurement guidelines in Riyadh and Jeddah favor this range for public building standby power.
- 1-100 kVA:Compact residential and small commercial units with air-cooled or small liquid-cooled engines. Price competition intensifies as local assembly capacity expands for this segment.
By margin pool concentration, Above 500 kVA leads. By unit volume, 101-300 kVA is gaining share fastest.
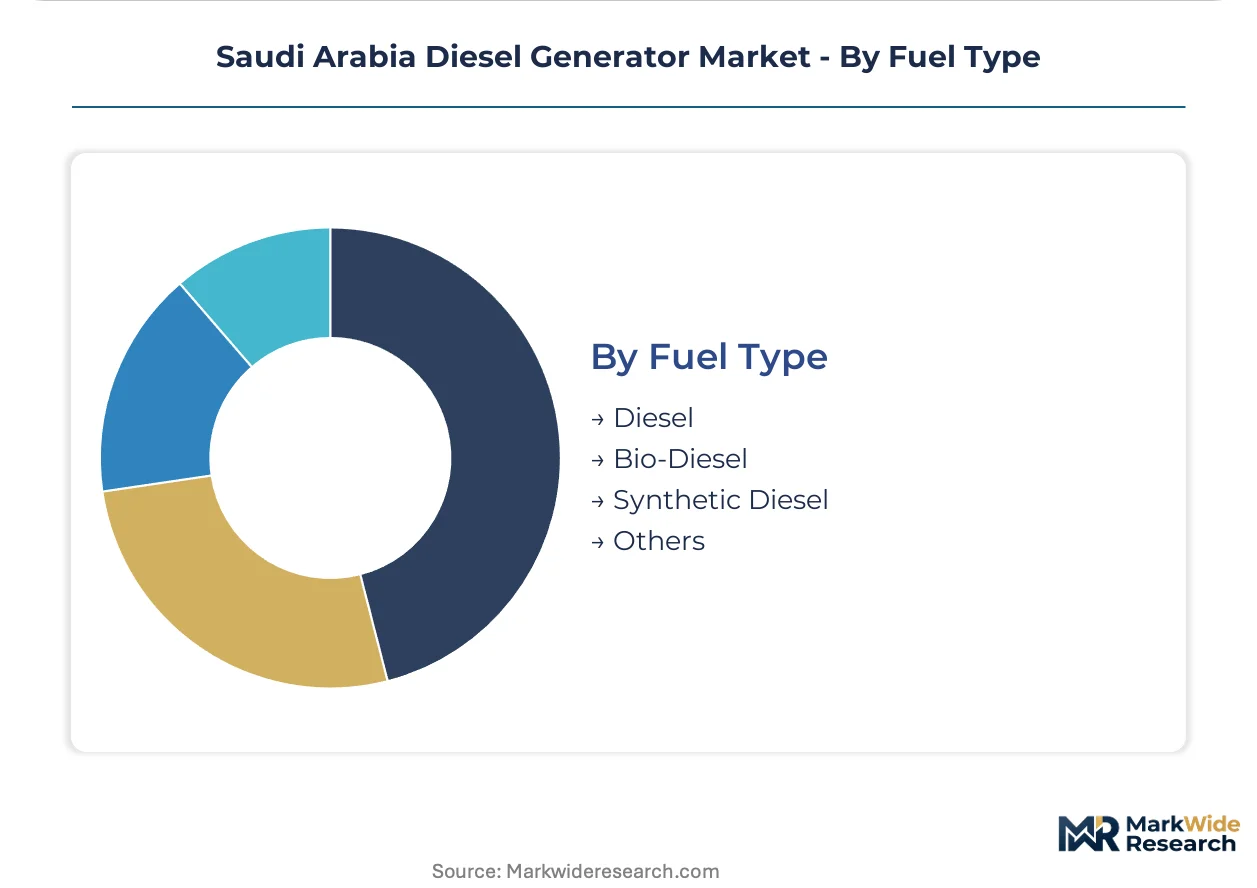
Fuel Type:
Regulatory pressure and total cost of ownership calculations reshape fuel specification trajectories.
- Diesel:Conventional petroleum-derived fuel dominates installed base and procurement volumes. Domestic subsidy structures and distribution infrastructure maturity sustain this position despite emission compliance costs.
- Bio-Diesel:B20 and B100 blends from waste oil feedstocks gain trial deployment at Aramco facilities pursuing sustainability metrics. Cold flow properties limit year-round reliability in northern Saudi climates.
- Synthetic Diesel:Gas-to-liquid and biomass-to-liquid fuels from regional production trials address carbon intensity targets. Cost premiums currently restrict adoption to demonstration projects and government fleet mandates.
- Others:Emerging dual-fuel and hydrogen-blended pilot programs at research institutions. Commercial scalability remains unproven for standby power applications.
By installed base, Diesel leads. By regulatory momentum, Bio-Diesel shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA emission protocols and SASO efficiency mandates are redirecting procurement flows toward qualified suppliers with established service networks across Saudi Arabia's industrial corridors.
Eastern Province
Aramco expansion clusters and petrochemical complex upgrades drive continuous demand for above-500 kVA standby systems. SFDA enforcement of NOx thresholds accelerates fleet replacement cycles at existing upstream facilities. Jubail and Ras Al-Khair industrial cities concentrate procurement for process-critical power redundancy.
Riyadh
NEOM giga-project support offices and commercial tower construction compress generator procurement timelines. SASO certification requirements filter supplier qualification tiers for municipal building backup systems. The Riyadh Metro expansion and Qiddiya entertainment district anchor mid-range power rating demand.
Western Region
Red Sea Project coastal development and Jeddah Islamic Port expansion pull mobile generator orders for temporary site electrification. Urban building codes mandate canopy-set configurations with sub-75 dBA noise attenuation. Makkah hospitality infrastructure upgrades sustain residential-scale backup demand.
NEOM Northwest
THE LINE and Oxagon construction schedules prioritize trailer-mounted fleets for rapid redeployment across linear site configurations. Renewable-integration mandates for the zone reshape standby power specifications and diesel run-hour limitations. Trojena and Sindalah island developments concentrate seasonal procurement spikes.
Saudi Arabia Diesel Generator Market Competitive Landscape
Listed leaders compete with private specialists across certification qualification tiers, creating a bifurcated structure where SASO-compliant vendors capture disproportionate share of public infrastructure contracts. The vendor base stratifies into three archetypes: multinational OEMs with captive Saudi service networks, regional assemblers with Dammam-based facilities, and local distributors controlling municipal procurement channels. Dominant competitive moves include partnerships with domestic assembly partners to satisfy MOF local content mandates and unbundling of equipment sales from long-term maintenance contracts.
Within the multinational OEM tier, Caterpillar Inc. and Cummins Arabia exemplify players leveraging established Riyadh and Dammam infrastructure to secure Aramco-linked site contracts. Saudi Diesel Equipment Co. Ltd. occupies a distinct position anchoring the local specialist segment through channel control across defense and municipal verticals.
| Leading Market Players |
|---|
| Kohler SDMO |
| Caterpillar Inc. |
| Cummins Arabia |
| Generac Holdings Inc. |
| Saudi Diesel Equipment Co. Ltd. |
| Atlas Copco Industrial Equipment Co. |
| Aksa Power Generation |
| Kirloskar DMCC |
| FG Wilson |
| Others |
Value Network & Pricing Analysis
Long-term maintenance contracts with Aramco-linked sites lock in both supply access and price visibility for qualified vendors, compressing spot-market exposure while embedding multi-year service revenue streams. SASO certification requirements filter bidding eligibility, concentrating procurement among tier-one suppliers with captive Dammam assembly capacity and established SFDA compliance track records.
Pricing Analysis
Certification level creates the primary spread between qualified and non-qualified supplier tiers in the Saudi market. Three-tier pricing structure across premium, standard, and economy levels reflects SASO efficiency grade, electronic governor inclusion, and bundled after-sales coverage. Price differentiation intensifies as buyers unbundle equipment from service contracts, forcing OEMs to demonstrate standalone maintenance capabilities. Cost compression in the 101-300 kVA segment runs deepest among municipal contractors facing capital constraints, while Oil & Gas operators show lowest price sensitivity due to process-critical redundancy requirements.
Supply Chain Analysis
Strategic stockpiling of core engine blocks above 500 kVA dominates inventory strategy given limited foundry sourcing from the United States, Germany, and Japan. Domestic assembly in Dammam draws from imported alternator windings, electronic governor modules, and exhaust after-treatment systems. Single-source vulnerability concentrates in precision fuel injection components tethered to European Tier 1 suppliers. Distribution runs through engineering contractors for permanent installations and rental fleet operators for mobile construction deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance contracts and remote telemetry subscriptions expand faster than hardware shipments, reconfiguring vendor economics toward recurring revenue.
For Market Incumbents: Compound channel control across Eastern Province industrial cities by deepening technician deployment networks and captive parts warehousing. Solar-battery hybrid substitution threatens pure diesel standby margins, necessitating backward integration into hybrid control systems. Prioritize SASO pre-certification of next-generation electronic governor platforms to compress product launch cycles ahead of SFDA emission deadline convergence. For New Entrants and Emerging Players: Remote monitoring platform gaps among tier-two construction contractors present the most penetrable service-layer entry point. Trailer-mounted fleet operators in NEOM and Red Sea Project corridors remain under-served by incumbent telemetry providers. Pursue white-label partnerships with Dammam-based assemblers to satisfy MOF local content minimums without capital-intensive facility investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Dammam-based assemblers with captive maintenance contract books and Aramco site relationships. Long-term viability hinges on hybrid-architecture adaptation capability rather than diesel-only positioning. Acquisition targets should demonstrate electronic governor integration expertise and established SFDA testing laboratory relationships. Monitor renewable-integration mandate enforcement velocity across new industrial zones as the primary inflection signal for diesel run-hour limitation severity.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Partnership | MOF procurement guidelines redirect supply chain configurations toward Dammam-based domestic assembly partners. |
| Electronic Governor Integration | Aramco expansion clusters now mandate precision frequency control, filtering mechanical-governor suppliers from bidding pools. |
| Predictive Maintenance Platform | IoT telemetry convergence enables outcome-based service contracts for process-critical standby power systems. |
| Hybrid Architecture Development | Renewable-integration mandates for new industrial zones reshape specifications toward diesel-battery hybrid configurations. |
| SASO Pre-Certification Investment | Parallel SFDA and SASO review processes compress product launch cycles for emission-compliant generator models. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs import records, SASO certification databases, and Aramco procurement disclosures. Interviews with maintenance directors at Eastern Province petrochemical complexes, aftermarket service heads at Dammam assembly facilities, and procurement officers for NEOM giga-project contractors anchor demand-side validation. Bottom-up unit shipment estimates triangulate against top-down energy consumption projections for standby power applications.
Segmentation dimensions modeled include product mobility configuration, end-user industry vertical, power rating tier, and fuel specification trajectory across the analysis window. CAGRs derive from regression analysis of historical procurement cycles against megaproject timeline acceleration and regulatory compliance deadline clustering. Forecast inputs incorporate SFDA emission protocol enforcement schedules and MOF local content mandate expansion patterns.
Underlying assumptions cover sustained Aramco expansion capital allocation and stable domestic diesel subsidy structures, with deviation risk concentrated in renewable-integration mandate acceleration and lithium-ion storage cost decline velocity. Revision becomes warranted when hybrid system payback periods cross threshold parity against pure diesel standby configurations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Africa Portable Generator Market
Generators
Gasoline Generator Market
Generators
Southeast Asia Portable Generator Market
Generators
South Africa Diesel Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Portugal Gas Generator Market
Generators
Generator (Up to 20 Kva) Market
Generators
Halogenerator Market
Generators
Onboard Marine Gensets Market
Generators
Asia-Pacific Gas Generator Market
Generators
Containerized Solar Generators Market
Generators
East Africa Diesel Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
Telecom Generator Market
Generators
South America Portable Generator Market
Generators
Multi Fuel Generators Market