
 Electric Generators Market | 2026-2036
Electric Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Generators Market Analytics
ISO 8528-5 load acceptance certification is rotating as the decisive gate for prime-power generator suppliers bidding into data center and healthcare contracts. Caterpillar Inc. leverages its integrated engine-alternator manufacturing footprint to control lead times on large diesel sets above 2 MW. Cummins Inc. sustains R&D intensity in dual-fuel natural gas platforms that bridge EPA Tier 4 Final compliance with carbon reduction targets. Generac Power Systems anchors the North American residential standby segment through installer channel density and 24-hour service network coverage.
Electric generators are electromechanical devices that convert mechanical energy into electrical output, typically rated by prime power in kVA, frequency stability, and transient response under block loading. They serve as on-demand or backup power sources for facilities where grid failure risks operational continuity or safety. The standby product category commands the dominant revenue share due to mandatory backup requirements in hospitals, financial institutions, and cloud computing facilities. Diesel fuel type installations retain the largest installed base, though natural gas and hybrid configurations are gaining fastest in regions with pipeline infrastructure and tightening particulate regulations. Industrial end users represent the deepest margin pool, as procurement emphasizes total cost of ownership and long-term maintenance contracts over unit price.
The EPA enforces Tier 4 Final emission limits on non-road diesel engines above 560 kW, compelling manufacturers to integrate selective catalytic reduction or exhaust gas recirculation into generator packages. ISO 8528 classification standards, alongside national electrical codes such as NFPA 110 in the United States, define acceptable performance bands for life-safety applications and determine market access for certified suppliers. Stakeholders must monitor how state-level clean energy mandates and carbon border adjustments reshape fuel choice and retrofit economics across installed generator fleets.
Market Dynamics
The EPA's Tier 4 Final emission mandates are compressing diesel generator margins while accelerating natural gas and hybrid platform R&D across prime-power suppliers bidding into data center and healthcare infrastructure contracts.
Growth Catalysts
- Data center load expansion:AI compute cluster deployment across Virginia, Texas, and Arizona is forcing hyperscale operators to double backup power redundancy ratios, pulling megawatt-class generator sets through extended tender cycles.
- ISO 8528-5 certification gate:Prime-power contracts for life-safety facilities now mandate documented transient response under block loading, filtering supplier pools to certified manufacturers with in-house test cells.
- India's manufacturing corridor electrification:Grid instability across Gujarat, Maharashtra, and Tamil Nadu industrial zones is accelerating captive power plant procurement for continuous process industries.
Market Restraints
- Platinum group metal cost volatility:Selective catalytic reduction systems for Tier 4 Final compliance concentrate palladium and rhodium exposure in exhaust after-treatment modules, squeezing gross margins on sub-1 MW diesel packages.
- Engine block casting concentration:Foundry capacity for large diesel crankcases clusters in China and India, creating 18-24 month order backlogs for non-integrated generator OEMs during demand spikes.
- Natural gas pipeline infrastructure gaps:Prime-power sites in rural Texas, North Dakota, and parts of Rajasthan lack pipeline connectivity, blocking gas generator deployment despite regulatory preference for cleaner combustion.
Strategic Opportunities
- Brazilian agro-industrial captive power:Sugarcane processing and poultry integration facilities in São Paulo and Minas Gerais states operate off-grid for months during harvest, creating demand for biogas-compatible generator sets with local fuel sourcing.
- Electrolyzer-hybrid convergence:Green hydrogen production sites in Denmark, Australia, and Saudi Arabia require spinning reserve generators synchronized with intermittent renewable input, opening specification windows for fast-ramp gas engines.
- EPA Renewable Fuel Standard pathways:Biodiesel and renewable diesel blending mandates for stationary engines create retrofit eligibility for existing Tier 2 and Tier 3 generator fleets, extending service contract revenue for maintenance providers.
Industry Challenges
- Combustion calibration engineering scarcity:Dual-fuel natural gas-diesel optimization requires rare expertise in cylinder pressure indication and knock-limited combustion phasing, constraining product development velocity at mid-tier suppliers.
- NFPA 110 Type 10 start-time certification:Life-safety applications demand full load acceptance within ten seconds of utility failure, forcing redundant starting systems and compressed commissioning protocols that extend field validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Generators Market |
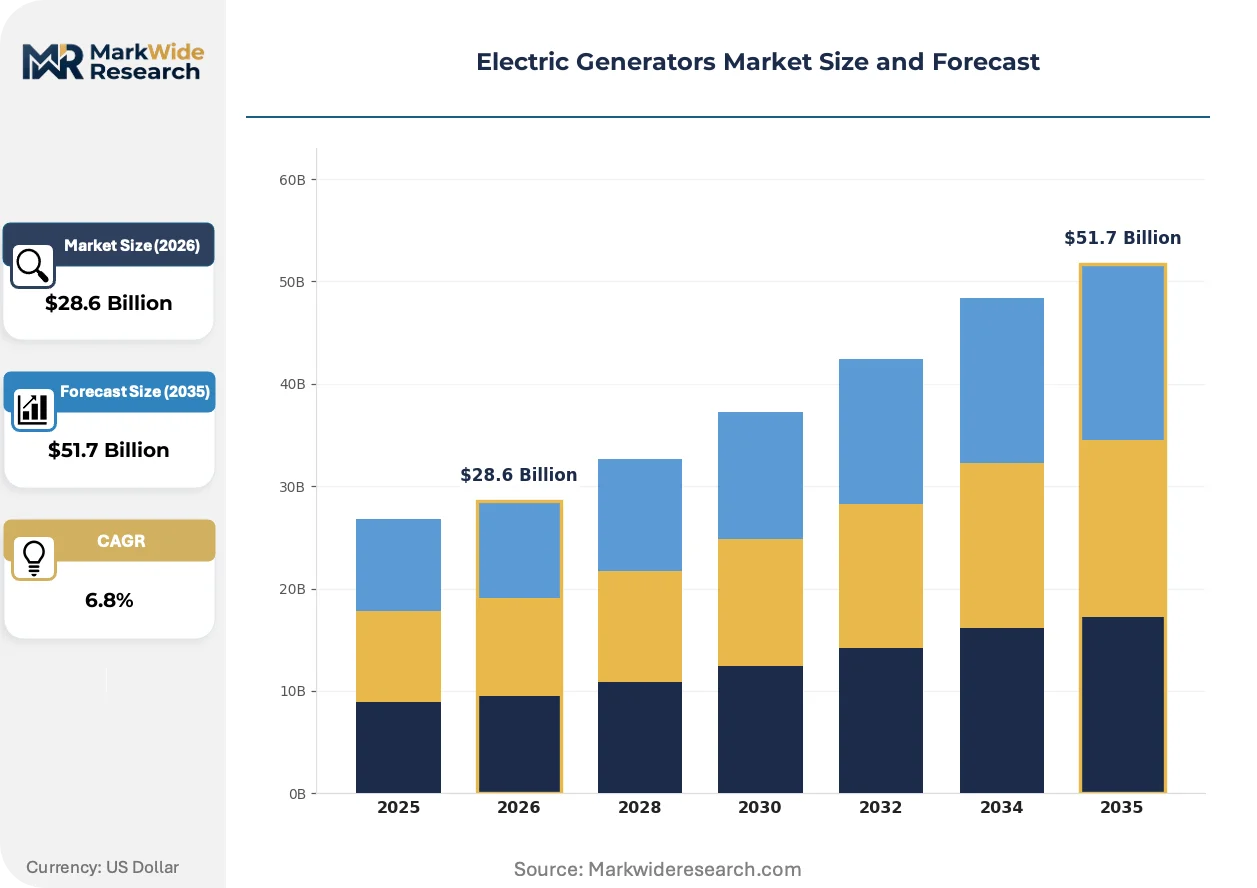
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Inverter, Diesel Fuel Type: Gasoline, Natural Gas, Propane, Hybrid End User: Residential, Commercial, Industrial, Infrastructure Installation Type: On-Grid, Off-Grid, Mobile, Permanent |
| Companies Covered | Caterpillar Inc., Cummins Inc., Generac Power Systems, Rolls-Royce Holdings plc, Mitsubishi Heavy Industries, Kohler Co., Honda Motor Co. Ltd., Atlas Copco, Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Generators Market Evolving Landscape
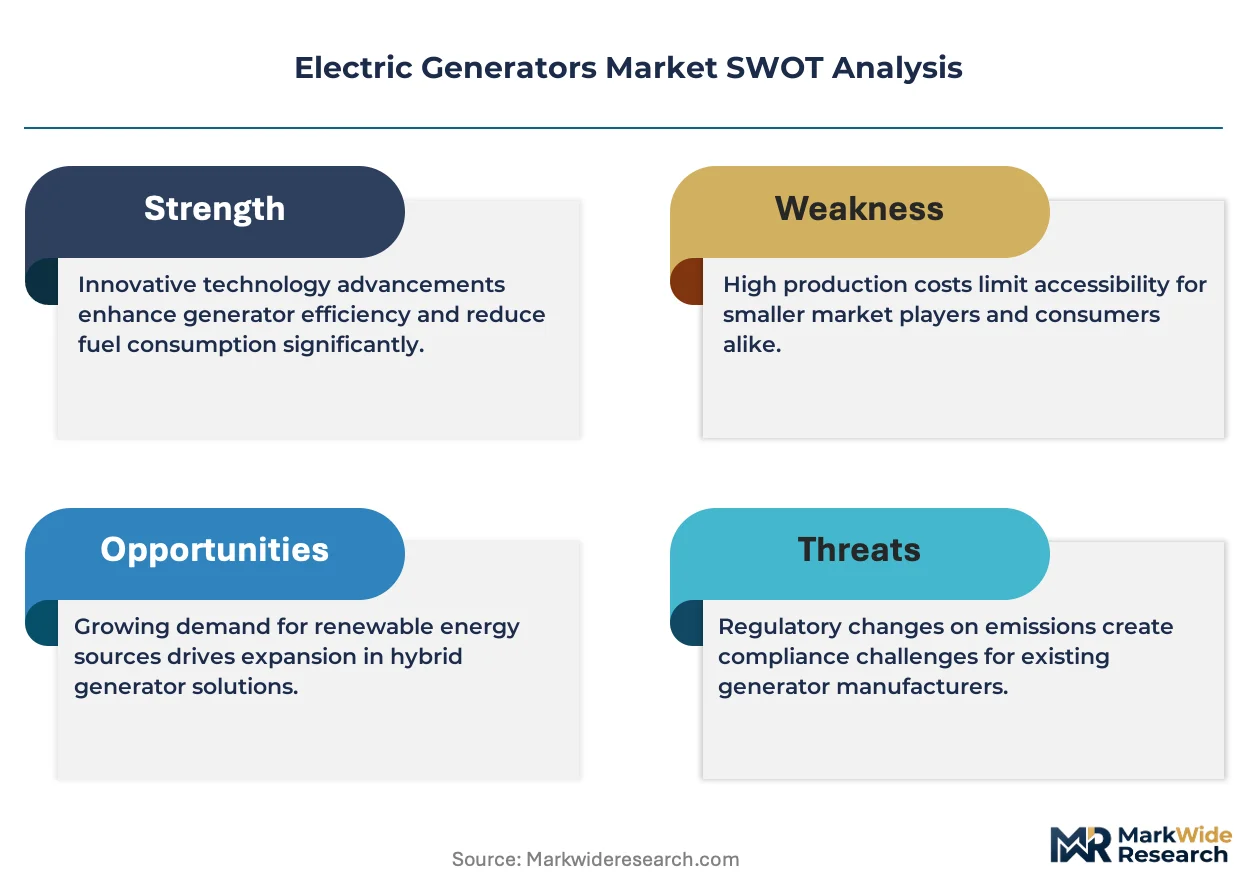
Generator set architecture is pivoting from standalone diesel blocks toward integrated hybrid systems that synchronize with battery energy storage and renewable input, rewiring supplier competitive advantage around power electronics and control software capabilities.
Permanent magnet alternator technology is supplanting conventional wound-field synchronous generators in sub-500 kVA mobile and rental applications. Telecom tower operators and construction fleet managers in Germany, Japan, and Australia are specifying PMG-equipped sets for fuel efficiency gains under variable load profiles. This shift is compressing aftermarket revenue from brush and slip-ring replacement while transferring value capture to rare-earth magnet supply chains and inverter-integrated voltage regulation.
REACH restrictions on chromium VI compounds in corrosion protection are forcing coating system reformulation for generator enclosures and fuel tanks across EU member states. Manufacturers serving data center and healthcare contracts must now qualify zinc-flake and aluminum-rich primer alternatives through salt-spray validation cycles. The industrial end-use segment bears the steepest compliance cost, as long maintenance contracts require guaranteed enclosure integrity over 15-20 year service lives.
Specification authority is migrating from facility engineering departments to procurement functions with total-cost-of-ownership mandates. Large manufacturing groups in India, Mexico, and Poland now bundle generator acquisition with 10-year service agreements, displacing spot-buy equipment tenders. This pattern is most visible in automotive supplier parks and pharmaceutical manufacturing clusters where uptime guarantees override capital expenditure minimization.
Electric Generators Market Segmentation
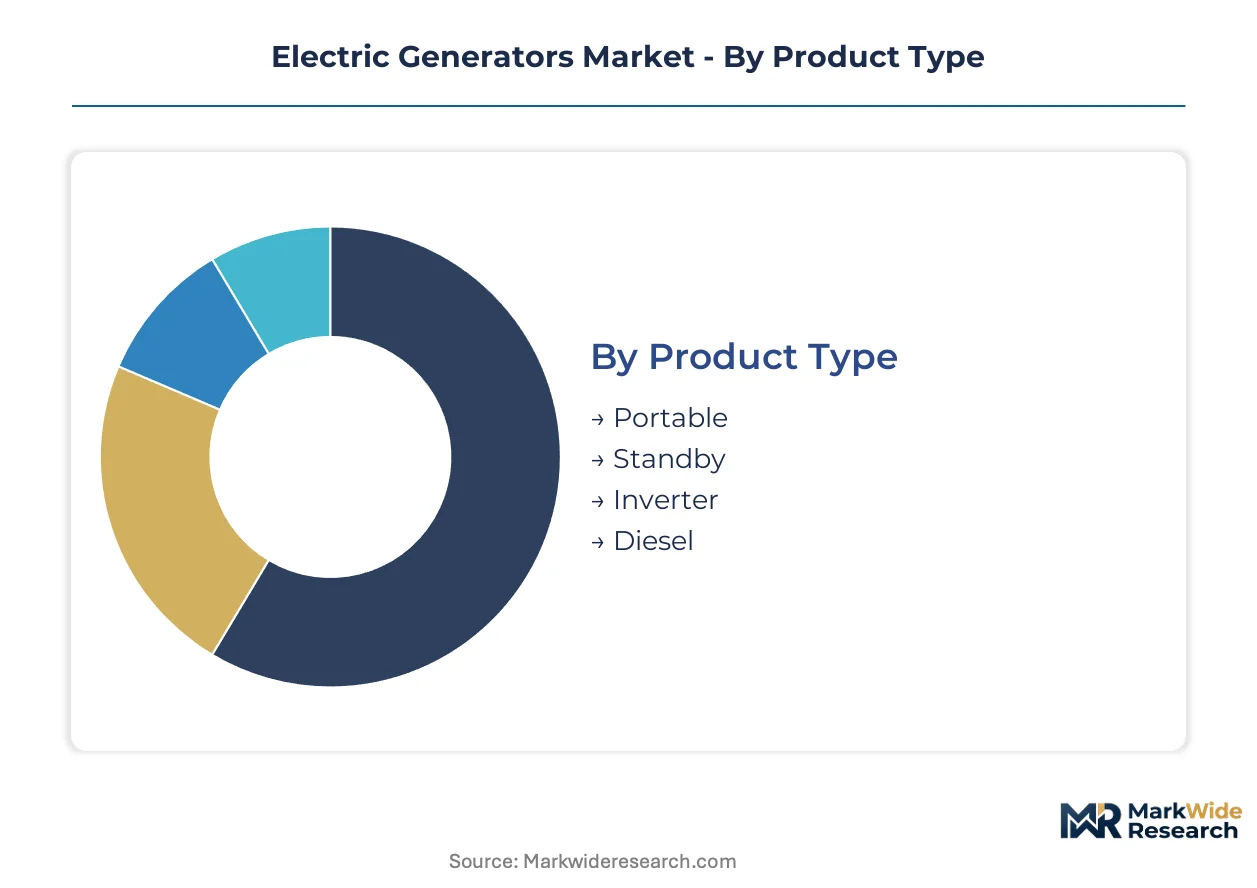
Generator procurement channels diverge sharply across product categories. Standby and industrial units flow through engineering-procurement-construction contractors with multi-year service agreements, while portable and residential segments concentrate in dealer networks and big-box retail.
Product Type:
Channel economics split this category into two distinct fulfillment models. Permanent-installation products move through certified distributor networks with factory-trained technicians, while mobile equipment routes through rental yards and consumer retail.
- Standby:Fixed automatic-start systems rated for emergency or prime power in hospitals, data centers, and manufacturing facilities. Demand clusters in Virginia, Texas, and Arizona hyperscale campuses where operators mandate NFPA 110 Type 10 compliance and 10-year maintenance contracts.
- Portable:Transportable units below 15 kVA deployed for construction, events, and residential backup. Procurement concentrates in Home Depot and United Rentals channels across the US Sun Belt, with hurricane seasonality driving Q3 inventory builds.
- Inverter:Microprocessor-controlled units with <3% total harmonic distortion for sensitive electronics. Compact form factors target RV owners and telecom field technicians in Germany and Japan where noise ordinances restrict conventional open-frame sets.
- Diesel:Traditional reciprocating-engine generators across all portability classes. EPA Tier 4 Final after-treatment requirements compress margins on sub-500 kVA units while sustaining demand in mining and remote construction where fuel logistics favor diesel over gas.
Standby dominates installed base. Inverter is where expansion concentrates.
Fuel Type:
Margin profiles stratify sharply by fuel chemistry and after-treatment burden. Natural gas and hybrid configurations capture premium pricing in pipeline-connected markets, while gasoline retains volume leadership in consumer and light commercial channels.
- Natural Gas:Pipeline-fed stationary engines with spark-ignited combustion and lower particulate output than diesel. Data center operators in Northern Virginia and Dallas-Fort Worth specify gas for EPA compliance, though rural Texas sites lack pipeline access.
- Hybrid:Integrated battery-generator systems with automatic load-leveling and silent-running modes. Telecom tower operators in Australia and Saudi Arabia deploy solar-diesel hybrids to cut fuel logistics costs at off-grid sites.
- Gasoline:Carbureted or fuel-injected spark-ignition engines in portable and residential standby classes. Lowest first-cost position sustains dominance in hurricane-belt consumer markets and emerging Asia construction rental.
- Propane:LPG-fueled systems with extended storage stability for rural residential standby. Midwest US counties without natural gas pipelines represent the deepest demand concentration.
Gasoline anchors unit volume. Hybrid is climbing the fastest.
End User:
Specification authority and procurement rhythm vary dramatically across end-use classes. Industrial buyers emphasize total cost of ownership and uptime guarantees, while residential decisions hinge on installer availability and financing terms.
- Industrial:Continuous or prime-power installations in process manufacturing, mining, and oil and gas extraction. Captive power plant procurement in Gujarat and Maharashtra industrial corridors accelerates as grid instability forces manufacturing self-sufficiency.
- Commercial:Retail, hospitality, and office backup systems with 10-500 kVA ratings. Grocery chains and regional banks in Poland and Mexico now bundle generator acquisition with decade-long service agreements.
- Infrastructure:Transportation, water treatment, and telecommunications critical facilities. Metro rail operators in São Paulo and cell tower companies in Rajasthan specify dual-fuel capability for fuel security.
- Residential:Single-family and multi-unit standby systems below 25 kVA. Generac's installer network density in Florida and Texas sustains market leadership through 24-hour response commitments.
Industrial commands the deepest margin pool. Infrastructure is gaining share fastest.
Installation Type:
Site preparation and interconnection requirements create distinct competitive barriers. Permanent installations demand electrical contractor relationships and permitting expertise, while mobile units compete on fleet utilization and logistics speed.
- Permanent:Fixed concrete-pad installations with automatic transfer switches and fuel storage tanks. Data center campuses in Loudoun County, Virginia require synchronized paralleling of multiple megawatt-class sets.
- Mobile:Skid-mounted or trailer-mounted rental fleet equipment. United Rentals and Sunbelt Rentals dominate US construction seasonality with telematics-tracked utilization optimization.
- On-Grid:Grid-connected backup systems with utility interconnection approval. California Title 20 compliance and New York City fire code restrictions constrain permissible fuel types and enclosure specifications.
- Off-Grid:Isolated installations without utility connection, common in mining and remote agro-processing. Brazilian sugarcane mills and Australian cattle stations operate biogas and solar-hybrid systems for months during harvest.
Permanent dominates revenue. Mobile is where fleet expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators and industrial captive power buyers concentrate procurement in five national markets where grid instability, emission mandates, and compute load expansion intersect.
United States
Virginia's Loudoun County and Texas's Dallas-Fort Worth metroplex host the densest hyperscale data center construction, pulling megawatt-class natural gas generator sets through extended tender cycles. EPA Tier 4 Final enforcement compresses diesel margins while accelerating hybrid platform R&D. Arizona's Phoenix-Tucson corridor demands synchronized paralleling capabilities for campus-scale redundancy.
India
Grid instability across Gujarat, Maharashtra, and Tamil Nadu industrial corridors forces continuous-process manufacturers toward captive power plant procurement. Central Electricity Authority regulations on islanding capability filter supplier pools to certified prime-power vendors. Automotive supplier parks in Pune and Chennai bundle decade-long service agreements with generator acquisition.
Germany
Telecom tower operators and construction fleet managers specify permanent magnet alternator-equipped sets under noise ordinances restricting conventional open-frame units. REACH restrictions on chromium VI compounds force coating system reformulation for generator enclosures. Industrial clusters in Bavaria and Baden-Württemberg prioritize total-cost-of-ownership procurement over unit price.
Brazil
Sugarcane processing and poultry integration facilities in São Paulo and Minas Gerais states operate off-grid for months during harvest, creating demand for biogas-compatible generator sets. ANVISA oversight of pharmaceutical manufacturing uptime guarantees drives NFPA 110 Type 10 compliance requirements. Metro rail operators in São Paulo specify dual-fuel capability for fuel security.
Australia
Solar-diesel hybrid deployments at off-grid mining sites and cattle stations cut fuel logistics costs through automatic load-leveling. TGA-equivalent state-level electrical safety regulations govern utility interconnection approval for grid-connected backup systems. Green hydrogen production sites in Western Australia require spinning reserve generators synchronized with intermittent renewable input.
Electric Generators Market Competitive Landscape
Player mix skews toward integrated engine-alternator manufacturers with in-house test cells and certified distributor networks. Market structure concentrates around three strategic archetypes: vertically integrated industrial power specialists controlling foundry-to-fuel-system supply chains; residential standby leaders anchoring market position through installer channel density; and dual-fuel technology developers bridging emission compliance with carbon reduction targets. Competitive moves center on capacity expansion in rare-earth magnet supply chains and strategic partnerships for power electronics integration.
Within the integrated industrial tier, Caterpillar Inc. and Cummins Inc. exemplify manufacturers with captive engine block casting and exhaust after-treatment capabilities. Generac Power Systems occupies a position representing residential standby market leadership through geographic coverage density. These three companies anchor the competitive landscape across distinct procurement channels.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Generac Power Systems |
| Rolls-Royce Holdings plc |
| Mitsubishi Heavy Industries |
| Kohler Co. |
| Honda Motor Co. Ltd. |
| Atlas Copco |
| Ingersoll Rand |
| Others |
Value Network & Pricing Analysis
Permanent magnet alternator substitution for wound-field synchronous generators is redrawing sourcing maps toward rare-earth processing clusters while compressing aftermarket service revenue into upfront equipment premiums. This materials transition simultaneously elevates magnet supply chain concentration and transfers pricing power from generator OEMs to magnet refiners and inverter-integrated control system suppliers.
Pricing Analysis
Cost-plus contracts with palladium and rhodium indexation dominate Tier 4 Final compliant diesel packages, passing platinum group metal volatility directly to data center and healthcare operators. Three-tier pricing structure across ISO 8528-5 certified prime-power, standard standby, and economy portable tiers reflects certification investment amortization and transient response guarantees. Cost compression in sub-500 kVA diesel runs through selective catalytic reduction module procurement, with industrial buyers least price-sensitive due to uptime guarantee requirements and residential standby segments most sensitive to first-cost positioning.
Supply Chain Analysis
China and India anchor foundry capacity for large diesel engine blocks, with 18-24 month order backlogs constraining non-integrated OEMs during demand spikes. Rare-earth magnet processing draws from Chinese separation facilities, while exhaust after-treatment catalysts rest on South African and Russian platinum group metal refining. Single-source vulnerability in permanent magnet supply creates tariff exposure under Section 301 and potential export restriction cascades. Distribution runs through certified distributor networks for permanent installations and rental yard fleets for mobile equipment, with engineering-procurement-construction contractors controlling specification authority on megawatt-class projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Generators Market is recovering from a cyclical trough driven by hyperscale data center construction resumption and industrial captive power investment in grid-unstable manufacturing corridors.
For Market Incumbents: Fortify backward integration into rare-earth magnet supply chains and captive engine block casting capacity to defend margin position against commodity volatility and foundry bottlenecks. Prioritize ISO 8528-5 test cell certification investments to filter competitor access to prime-power healthcare and data center contracts, while accelerating hybrid platform R&D to preempt regulatory preference shifts away from diesel architectures. For New Entrants and Emerging Players: Aftermarket service network density in Tier-2 Indian industrial corridors represents the most penetrable white-space, where incumbent coverage gaps force manufacturing operators toward uncertified suppliers. Target biogas-compatible generator specification for Brazilian agro-industrial captive power, where local fuel sourcing requirements and harvest-season off-grid operation create specification windows outside incumbent core competencies. Lead with power electronics and control software capabilities rather than engine manufacturing scale. For Investors and Strategic Acquirers: Capital is best deployed toward dual-fuel technology developers with proven cylinder pressure indication expertise and knock-limited combustion phasing capabilities, as combustion calibration engineering scarcity constrains product velocity at mid-tier suppliers. Long-term viability hinges on hydrogen-ready gas engine architectures and electrolyzer-hybrid convergence positioning. Watch EPA Renewable Fuel Standard pathway expansion as the inflection signal for retrofit service contract revenue extension.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Rare-Earth Magnet Processing | Secures upstream supply for permanent magnet alternator manufacturing against Chinese export restriction risk. |
| ISO 8528-5 Test Cell Certification Investment | Unlocks prime-power contract eligibility for data center and healthcare infrastructure tenders. |
| Dual-Fuel Natural Gas Platform Development | Bridges EPA Tier 4 Final compliance with carbon reduction targets for pipeline-connected sites. |
| Long-Term Service Agreement Bundling | Captures total-cost-of-ownership procurement shifts in Indian and Mexican manufacturing clusters. |
| Hybrid System Power Electronics Integration | Enables battery-generator synchronization for telecom tower and green hydrogen site specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center engineering directors, industrial plant managers in Gujarat and Maharashtra, EPA compliance officers, and aftermarket service network heads. Secondary validation drew from EPA Tier 4 Final enforcement documentation, Central Electricity Authority islanding regulations, FERC interconnection filings, and customs trade data on engine block and alternator imports. Bottom-up unit shipment estimates triangulated against top-down capex allocation disclosures from hyperscale operators.
Across the analysis window, the analytical framework modeled segmentation dimensions including fuel type chemistry, installation permanence, end-use criticality tier, and regional regulatory stringency cluster. CAGRs were derived from slope-matching historical procurement cycles to projected data center power density requirements and industrial electrification trajectories. Forecast inputs incorporated platinum group metal price band scenarios and rare-earth magnet supply constraint probabilities.
Forecasts assume regulatory continuity in EPA stationary engine standards and REACH coating restrictions; material policy shifts would require re-modeling. Specific risks that could revise projections include state-level clean energy mandates accelerating diesel retirement, carbon border adjustments altering fuel choice economics, and export controls on permanent magnet materials. Recalibration cycles align with material shifts in data center construction permitting and industrial captive power tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
North America Gasoline Gensets Market
Generators
Marine Gensets Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Global Portable Generator Market
Generators
Middle-East and Africa Diesel Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Mobile Generators Market
Generators
Home Standby Gensets Market
Generators
Telecom Generator Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
Residential Gas Generator Market
Generators
Southeast Asia Portable Generator Market
Generators
United States Portable Generator Market
Generators
South America Generator Sets Market
Generators
Nuclear Turbine Generators Market
Generators
Digital Inverter Generator Market