
 Plant-Based Chicken Market | 2026-2036
Plant-Based Chicken Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Chicken Market Outlook
Market Context
European extrusion capacity expansion is recalibrating supply availability for North American brands. Beyond Meat leverages integrated manufacturing facilities in the Netherlands to secure European shelf placement. Impossible Foods Inc. sustains its R&D intensity through proprietary heme fermentation technology. Maple Leaf Foods anchors Canadian distribution through its plant-based subsidiary and retail partnerships.
Technical Definition and Segment Structure
Plant-based chicken denotes textured protein products formulated from pea, soy, wheat gluten, or mycoprotein sources, manufactured through high-moisture extrusion to replicate the fibrous structure and bite profile of conventional poultry muscle tissue, serving foodservice and retail channels seeking animal-protein alternatives. Patties and nuggets occupy the dominant volume share within product type segmentation, driven by frozen retail and quick-service channel penetration. Pea protein leads ingredient source growth due to allergen positioning and supply chain scalability relative to soy. Foodservice distribution channels capture expanding margin pools as restaurant chains negotiate exclusive supply agreements.
Regulatory Frame and Outlook
The FDA enforces allergen labeling and GRAS notification requirements for novel plant proteins entering U.S. interstate commerce, while EFSA evaluates mycoprotein safety dossiers under novel food regulations, collectively elevating compliance costs for new entrants. The EU Green Deal and F-Gas Regulation indirectly shape ingredient sourcing by pressuring manufacturers to reduce processing emissions and eliminate synthetic refrigerants in cold chain logistics. Stakeholders must monitor evolving nomenclature standards that determine whether products qualify for "chicken" descriptor usage in retail labeling.
Market Dynamics
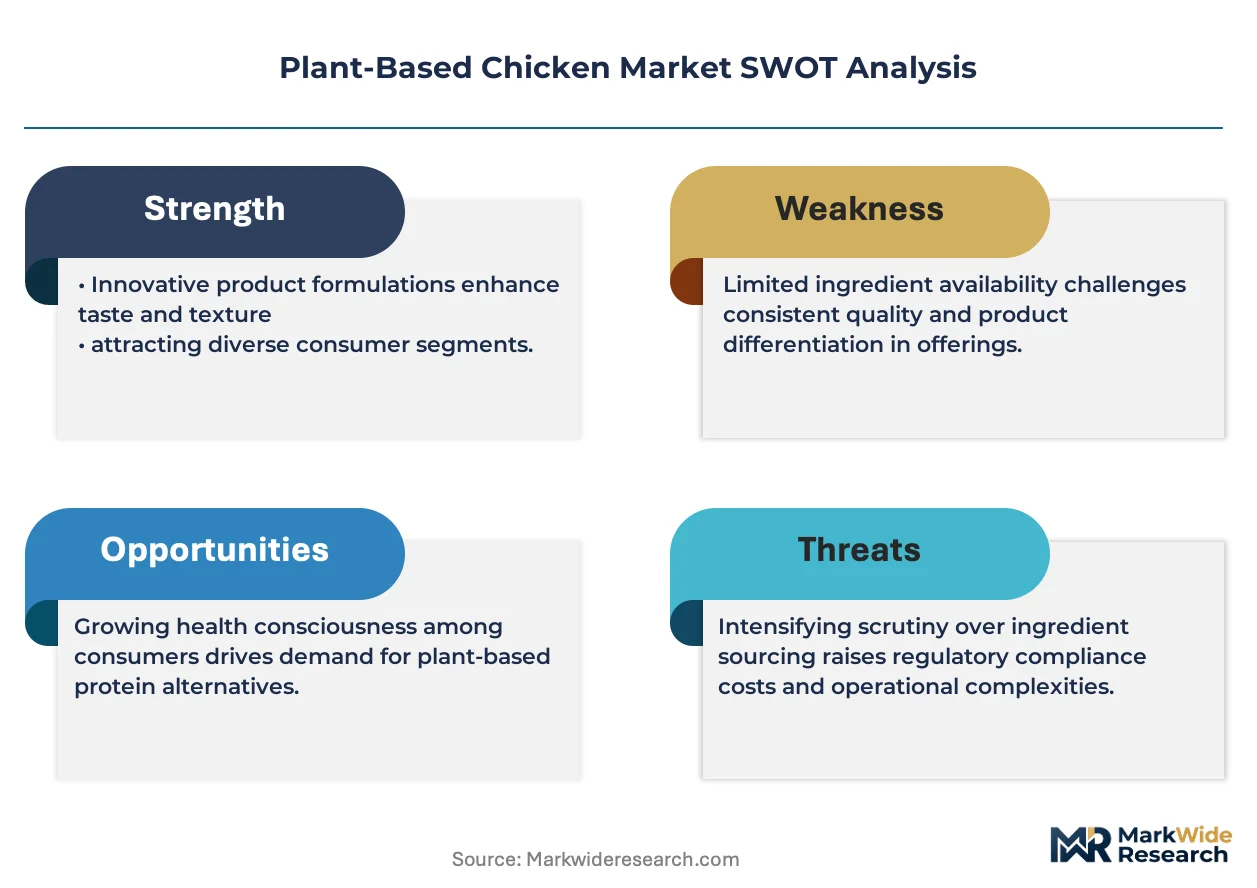
High-moisture extrusion technology maturation is compressing capital requirements for new plant-protein manufacturing facilities, while FDA and EFSA labeling convergence is forcing simultaneous compliance investments across Atlantic supply chains.
Growth Catalysts
- EU Green Deal procurement mandates:Public-sector foodservice contracts across Germany, France, and the Netherlands now require minimum plant-protein inclusion, creating institutional demand floors that stabilize volume planning for manufacturers.
- Quick-service restaurant chain menu expansion:Dedicated plant-based chicken lines at major North American and European fast-casual operators are normalizing trial among omnivore consumers previously resistant to meat alternatives.
- Pea protein supply chain scalability:Canadian and Ukrainian cultivation expansion has reduced input price volatility relative to soy, enabling cost-competitive positioning against conventional poultry in frozen retail channels.
Market Restraints
- Input cost concentration in pea protein isolate:Three suppliers control over sixty percent of food-grade isolate capacity, creating margin vulnerability when crop yields contract in the Canadian prairies.
- EFSA novel food authorization timelines:Mycoprotein and emerging fermentation-derived proteins face eighteen-to-twenty-four month safety dossier reviews that delay product launch windows and consume regulatory capital.
- Technical limitation in whole-muscle replication:Current extrusion systems cannot yet replicate the anisotropic fiber alignment of chicken breast tissue, constraining premium positioning against whole-cut poultry.
Strategic Opportunities
- Brazilian foodservice underpenetration:Quick-service chains in São Paulo and Rio de Janeiro lack dedicated plant-based chicken suppliers, presenting first-mover positioning for extrusion-capable manufacturers with tropical distribution partnerships.
- Cell-cultured hybrid products:Blending plant-based scaffolding with cultivated poultry cells offers a regulatory pathway through existing novel food frameworks while delivering sensory profiles beyond current extrusion limits.
- Direct-to-institutional channel development:University and corporate cafeteria networks in the United States are consolidating procurement through group purchasing organizations seeking sole-source plant-protein agreements.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning protein chemistry, extrusion engineering, and sensory science commands premium compensation that strains mid-cap manufacturer operating budgets.
- Dual certification complexity:Simultaneous USDA Organic and Non-GMO Project verification requires eighteen-month timeline commitments that delay revenue recognition for new product lines.
- Cold chain reconfiguration costs:Eliminating synthetic refrigerants under the EU F-Gas Regulation demands capital replacement of frozen distribution infrastructure without guaranteed pass-through pricing power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Chicken Market |
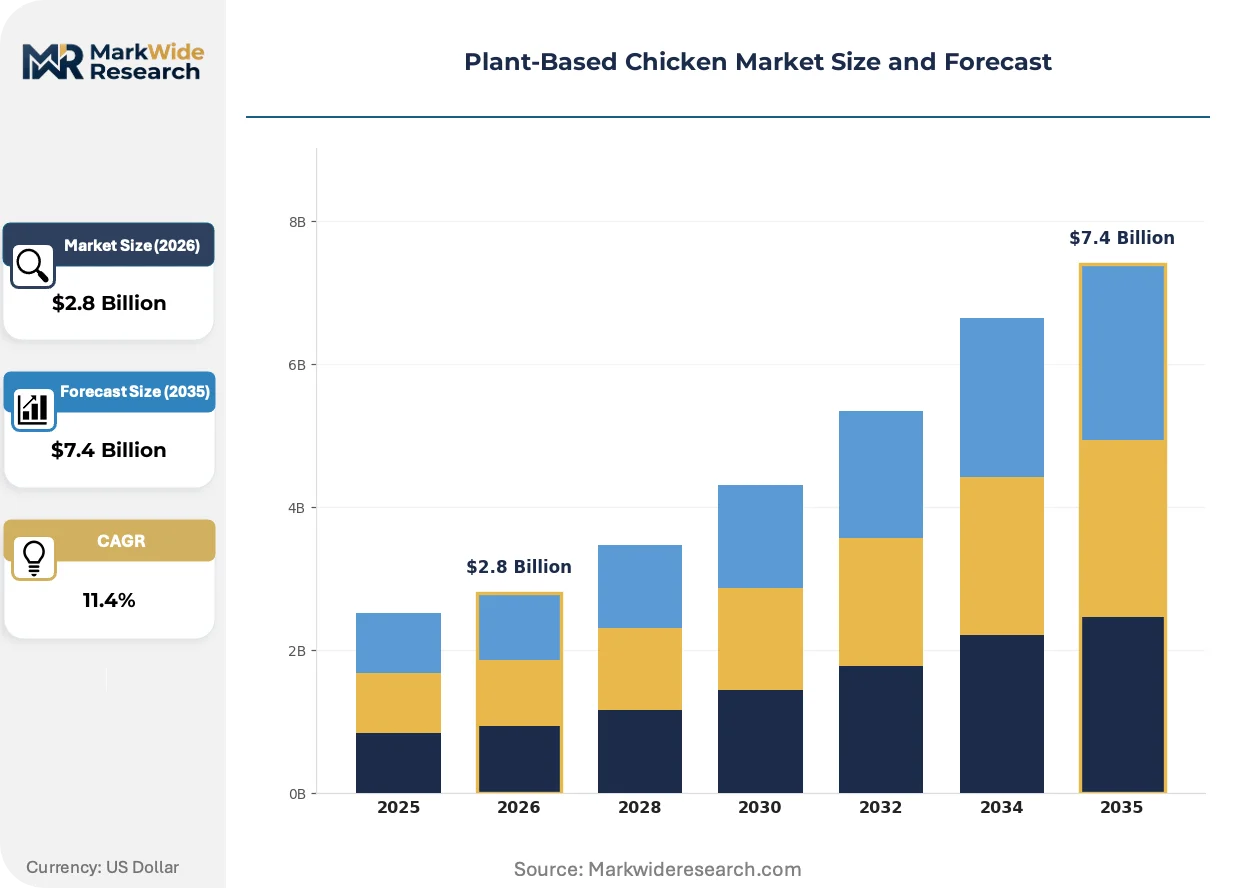
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunks, Patties, Nuggets, Tenders Ingredient Source: Pea Protein, Soy Protein, Wheat Gluten, Mycoprotein Distribution Channel: Online, Supermarkets, Health Food Stores, Foodservice End User: Vegetarians, Vegans, Flexitarians, Health Conscious Consumers |
| Companies Covered | Beyond Meat, Impossible Foods Inc., Conagra Brands, Maple Leaf Foods, Kellogg Company, The Vegetarian Butcher, Tofurky, Quorn, Amy's Kitchen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Chicken Market Strategic Shifts
Mycoprotein fermentation is advancing from niche positioning toward mainstream poultry substitution as capital flows into precision-fermentation infrastructure and regulatory dossiers mature across multiple jurisdictions.
Precision-fermentation-derived heme proteins are expanding into high-moisture extrusion formulations to replicate the Maillard reaction and umami depth of seared chicken. Foodservice operators in the United States and United Kingdom are adopting these enhanced formulations at accelerated pace for breaded cutlet and strip applications. This convergence is expanding into premium quick-service segments previously closed to plant-based alternatives due to sensory performance gaps.
The EU F-Gas Regulation and accompanying national implementation laws are prohibiting hydrofluorocarbon refrigerants in frozen food logistics from 2030, forcing cold-chain operators to invest in transcritical CO2 or ammonia systems. Manufacturers with pan-European distribution networks face stranded asset risk in legacy refrigerated transport fleets. Frozen plant-based chicken products with extended shelf stability are responding through reformulation for ambient distribution in select European markets.
Flexitarian households in the United States are consolidating weekly protein purchases around fewer, larger-format frozen products rather than daily fresh-meat acquisition. Retail channel buyers are displacing single-serve SKUs with family-sized nugget and patty formats in freezer case resets. This concentration is most visible in suburban grocery formats where basket-size economics favor bulk plant-protein purchasing alongside conventional protein staples.
Plant-Based Chicken Market Segmentation
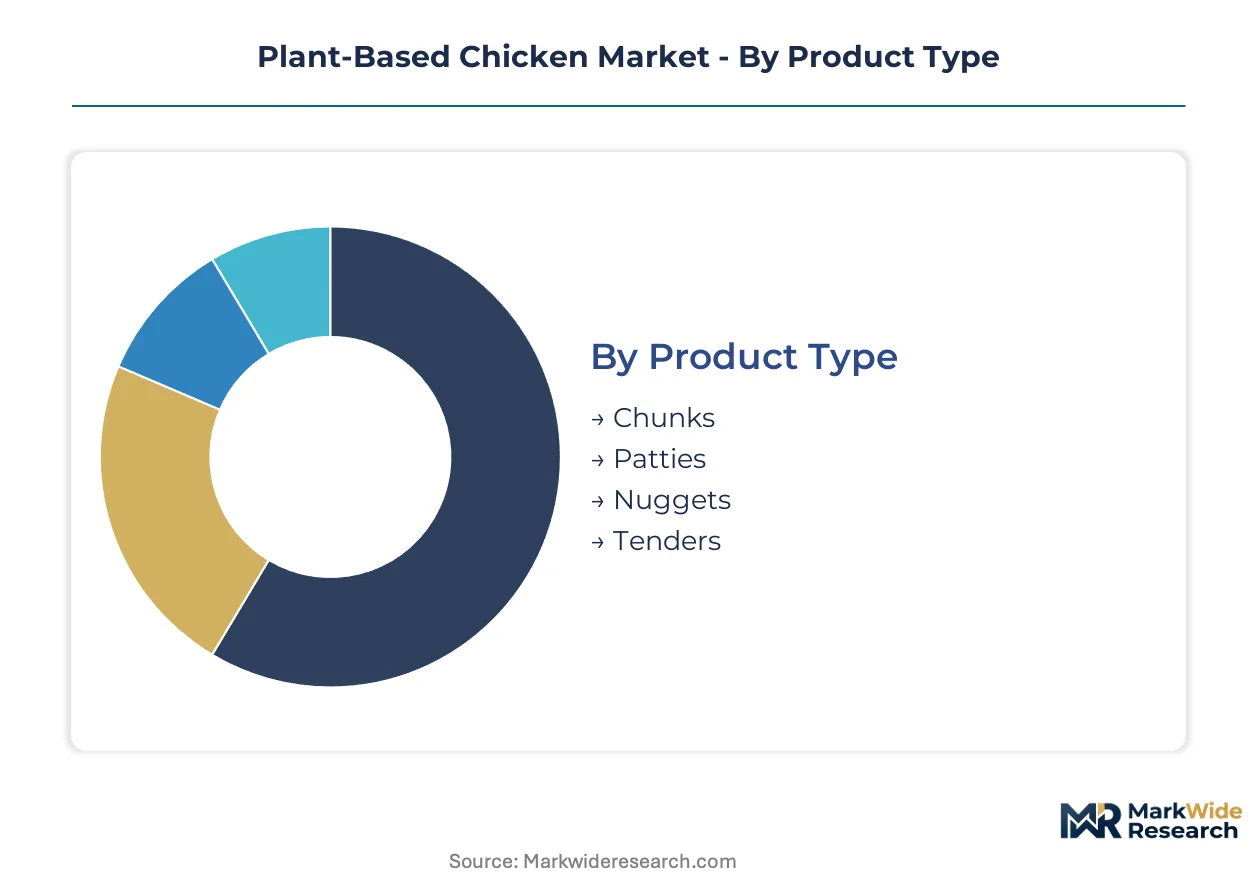
Plant-based chicken manufacturers configure production lines around specific extrusion parameters that vary sharply by product geometry. Segment-level demand patterns determine capital allocation across high-moisture extrusion capacity, with foodservice contracts and retail freezer placement driving divergent formulation priorities.
Product Type:
Supply concentration in high-moisture extrusion systems favors formats with standardized die configurations and predictable throughput economics.
- Patties:Uniform thickness profiles suit automated forming and controlled Maillard browning on griddle surfaces. Quick-service chains in the United States negotiate exclusive supply agreements for breaded patty formats, locking in multi-year volume commitments that stabilize manufacturer capacity planning.
- Nuggets:Breaded exterior-to-interior ratios mask textural limitations of current extrusion systems while enabling portion-controlled pricing. Frozen retail channels in suburban grocery formats favor family-sized nugget SKUs as flexitarian households consolidate weekly protein purchases.
- Chunks:Irregular geometries suited for stir-fry and bowl applications.
- Tenders:Elongated strips targeting premium quick-service breaded cutlet applications.
Patties absorb the bulk of installed capacity; nuggets are expanding most quickly.
Ingredient Source:
Cost tier differentiation separates commodity-positioned proteins from premium fermentation-derived alternatives commanding formulation premiums.
- Pea Protein:Isolate production concentrates among three suppliers controlling food-grade capacity, creating margin vulnerability during prairie crop yield contractions. Canadian and Ukrainian cultivation expansion has reduced input price volatility relative to soy, enabling cost-competitive frozen retail positioning.
- Mycoprotein:Fungal biomass fermentation delivers complete amino acid profiles and fibrous texture without extrusion. EFSA novel food authorization timelines of eighteen-to-twenty-four months delay product launch windows and consume regulatory capital for new entrants.
- Soy Protein:Established supply infrastructure with allergen labeling constraints in European markets.
- Wheat Gluten:Low-cost binder functionality with limited standalone texture replication.
Pea protein dominates current volume; mycoprotein is gaining share fastest.
Distribution Channel:
Application-specific margin pools separate institutional procurement from retail velocity requirements.
- Foodservice:Exclusive supply agreements with quick-service chains capture expanding margin pools as operators negotiate dedicated plant-based menu lines. Contract structures favor manufacturers with integrated manufacturing and cold-chain capabilities spanning multiple production facilities.
- Supermarkets:Freezer case resets displace single-serve SKUs with family-sized formats as suburban grocery buyers prioritize basket-size economics. Retail buyers demand eighteen-month timeline commitments for dual USDA Organic and Non-GMO Project verification.
- Online:Direct-to-consumer subscription models with ambient-stable shipping requirements.
- Health Food Stores:Premium positioning with certification-heavy product curation.
Foodservice channels concentrate margin extraction; supermarkets are climbing the fastest.
End User:
Customer type determines formulation trade-offs between sensory fidelity and clean-label positioning.
- Flexitarians:Omnivore households seeking partial protein substitution now represent the largest buyer cohort in the United States. These consumers prioritize sensory performance over ingredient purity, driving adoption of heme-enhanced formulations in quick-service applications.
- Health Conscious Consumers:Nutritional density and sodium reduction claims guide purchase decisions. FDA allergen labeling requirements and GRAS notification obligations for novel proteins elevate compliance costs for products targeting this segment.
- Vegetarians:Longstanding category participants with established brand loyalties.
- Vegans:Ethical positioning with zero-tolerance supply chain verification requirements.
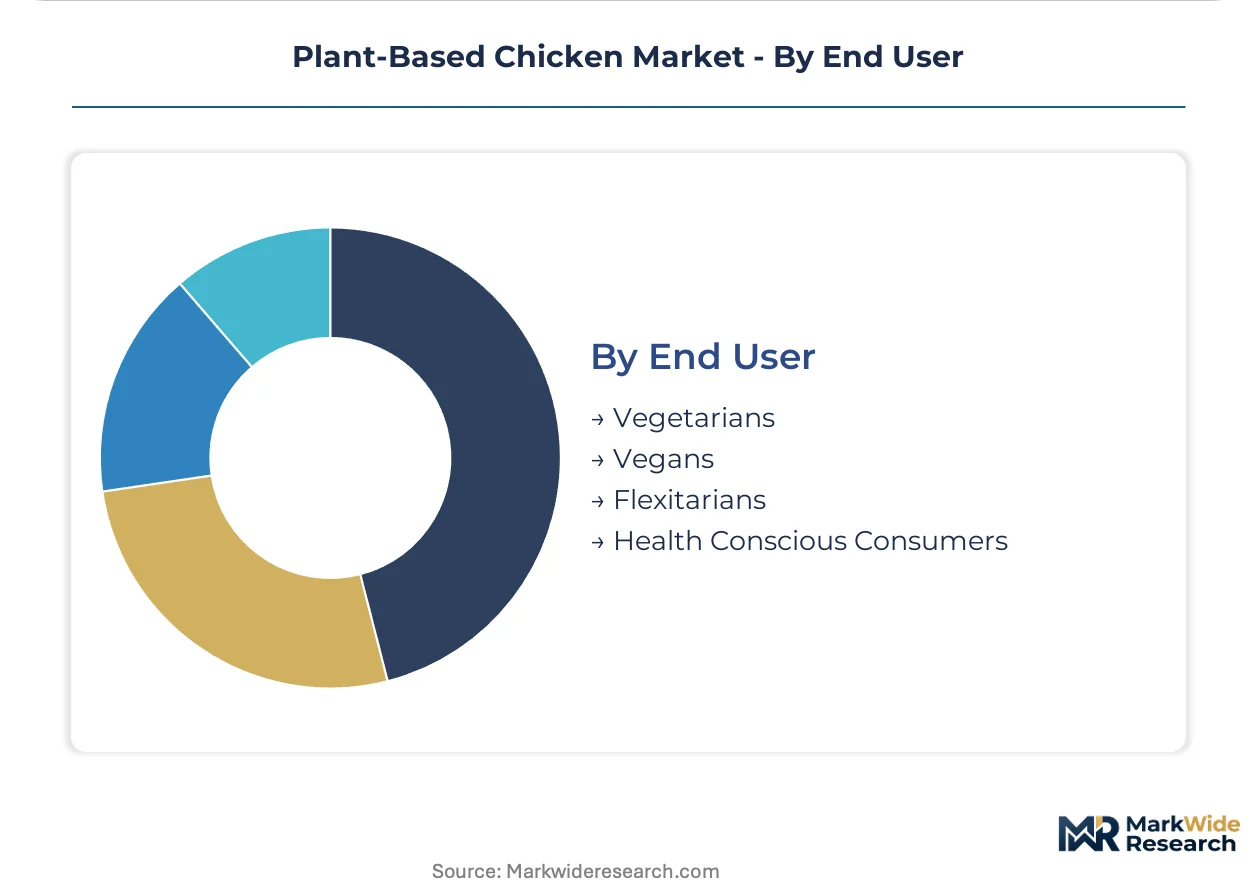
Flexitarians absorb the bulk of current volume; health conscious consumers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian prairie cultivation anchors pea protein supply chains that feed North American and European extrusion facilities. Ukraine's expanding isolate capacity is recalibrating input cost structures for manufacturers sourcing alternative proteins.
United States
Flexitarian households in suburban markets now drive the largest volume cohort for frozen nugget and patty formats. FDA GRAS notification requirements for novel proteins elevate compliance costs for entrants targeting interstate commerce. Chicago and Minneapolis-St. Paul host concentrated foodservice distribution networks negotiating exclusive supply agreements with quick-service chains.
Germany
Public-sector procurement mandates under the EU Green Deal require minimum plant-protein inclusion in institutional foodservice contracts. The F-Gas Regulation is forcing cold-chain operators to eliminate hydrofluorocarbon refrigerants by 2030. Berlin and Hamburg anchor manufacturing clusters where extrusion-capable facilities are retrofitting distribution infrastructure for transcritical CO2 systems.
Netherlands
Integrated manufacturing facilities serve as European launch platforms for North American brands seeking shelf placement across EU markets. EFSA novel food authorization timelines for mycoprotein delay product launch windows by eighteen-to-twenty-four months. Wageningen and Eindhoven concentrate R&D partnerships between ingredient suppliers and high-moisture extrusion equipment specialists.
United Kingdom
Precision-fermentation-derived heme formulations are penetrating premium quick-service breaded cutlet applications at accelerated pace. The country's national food standards regulator evaluates labeling nomenclature standards that determine "chicken" descriptor eligibility. London and Manchester host foodservice operator headquarters consolidating procurement through group purchasing organizations.
Brazil
Quick-service chains in São Paulo and Rio de Janeiro lack dedicated plant-based chicken suppliers, creating first-mover positioning opportunities. ANVISA, the national health regulatory agency, maintains novel food frameworks applicable to fermentation-derived proteins. São Paulo's foodservice distribution networks remain underpenetrated by extrusion-capable manufacturers with tropical logistics partnerships.
Plant-Based Chicken Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived alternatives and hybrid cell-cultured formulations. The market structures around three archetypes: integrated protein manufacturers with captive extrusion capacity, specialist brands leveraging proprietary heme or mycoprotein technologies, and diversified food conglomerates with retail distribution scale. Dominant competitive moves include backward integration into isolate production and exclusive supply agreements with quick-service restaurant chains.
Among North American specialists, Beyond Meat and Impossible Foods Inc. exemplify the technology-differentiated tier, while Maple Leaf Foods anchors the integrated manufacturing archetype with Canadian distribution control. These three occupy positions that illustrate the strategic divergence between proprietary fermentation platforms and captive supply chain infrastructure.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods Inc. |
| Conagra Brands |
| Maple Leaf Foods |
| Kellogg Company |
| The Vegetarian Butcher |
| Tofurky |
| Quorn |
| Amy's Kitchen Inc. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into pea protein isolate production anchors both supply security and pricing power for manufacturers seeking insulation from prairie crop volatility. Captive supply of food-grade isolate enables margin defense when three dominant suppliers constrain capacity during Canadian yield contractions.
Pricing Analysis
Certification bundling separates verified tiers from unbundled commodity positioning in frozen retail channels. Three-tier pricing structure across premium, standard, and economy levels tracks USDA Organic and Non-GMO Project verification status alongside heme-enhanced sensory performance. Price differentiation stems from eighteen-month dual certification timelines that delay revenue recognition for new entrants. Cost compression in economy tiers intensifies because Ukrainian isolate expansion feeds spot-market availability. Quick-service chains exhibit lowest price sensitivity due to exclusive contract structures; suburban flexitarian households in frozen retail show highest sensitivity to per-pound differentials.
Supply Chain Analysis
Pea protein isolate supply rests on Canadian prairie cultivation and Ukrainian processing expansion, with Dutch extrusion equipment completing the value chain. Raw material dependencies center on food-grade isolate, high-moisture extrusion systems, and precision-fermentation heme inputs. Single-source vulnerability concentrates in the three suppliers controlling sixty percent of food-grade isolate capacity. Distribution runs through integrated cold-chain networks serving quick-service chains and retail freezer placement, with EU F-Gas Regulation forcing transcritical CO2 system adoption by 2030.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over isolate production and downstream captive distribution determine competitive survival. Players are pursuing backward integration into prairie processing assets as the decisive lever.
For Market Incumbents: Lock in exclusive supply agreements with quick-service chains before fermentation-derived alternatives achieve EFSA authorization. Secure multi-year volume commitments that stabilize capacity planning against mycoprotein entrants. Invest in Canadian isolate processing partnerships to reduce dependency on the three dominant suppliers during prairie yield contractions.
For New Entrants and Emerging Players: Enter via Brazilian foodservice distribution partnerships in São Paulo and Rio de Janeiro, where quick-service chains lack dedicated plant-based chicken suppliers. Target university and corporate cafeteria networks consolidating procurement through group purchasing organizations. Pursue direct-to-institutional channel development with ambient-stable formulations bypassing cold-chain infrastructure requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified food conglomerates seeking extrusion capacity and quick-service contract books. Long-term viability favors manufacturers with integrated isolate supply and multi-facility distribution networks spanning regulatory jurisdictions. Watch EFSA novel food authorization timelines for mycoprotein as the inflection signal for fermentation-derived competitive threat.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isolate Production | Captive supply of pea protein reduces margin vulnerability to Canadian prairie yield volatility. |
| Exclusive Quick-Service Supply Agreements | Multi-year contracts with major chains stabilize volume planning and lock out fermentation entrants. |
| EFSA Novel Food Dossier Investment | Mycoprotein authorization opens premium positioning beyond current extrusion textural limits. |
| Cold-Chain Refrigerant Transition | Transcritical CO2 system adoption ahead of EU F-Gas Regulation deadlines prevents stranded asset risk. |
| Direct-to-Institutional Channel Development | Group purchasing organization contracts bypass retail slotting fees and certification timeline delays. |
Study Parameters
Document review covered FDA GRAS notifications, EFSA novel food safety dossiers, and EU Green Deal procurement mandates, complemented by interviews with plant-protein formulation scientists, quick-service chain procurement directors, and extrusion equipment specialists. Secondary validation drew from customs trade data, SEC filings of publicly traded food manufacturers, and cold-chain logistics operator disclosures. Bottom-up capacity modeling triangulated against top-down demand projections from institutional procurement databases and retail freezer placement audits.
Historical volume trajectories cross-referenced against expert panel input on extrusion technology maturation and regulatory timeline expectations. Segmentation dimensions modeled include product geometry, ingredient source tier, distribution channel margin structure, and end-user dietary archetype. CAGRs derived from weighted scenario analysis across the projection horizon, incorporating pea protein input price elasticity and quick-service contract renewal rates as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA authorization delays or prairie drought conditions. Forecasts reflect assumptions about extrusion capacity expansion timelines and flexitarian household penetration rates. A small set of named triggers—mycoprotein regulatory approvals, Ukrainian isolate supply disruptions, and F-Gas Regulation enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Middle East Plant Protein Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Soy Protein Market
Plant Based Food
Vegan Meals Market