
 Fiber Fortified Beverages Market | 2026-2036
Fiber Fortified Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Fortified Beverages Market Analytics
Beverage manufacturing capacity in North America is shifting toward in-house fiber infusion and aseptic processing lines to capture margin from value-added formulations. PepsiCo leverages its North American bottling network to anchor distribution density for functional hydration lines. Danone competes through specialized dairy-alternative platforms that integrate chicory root fiber. Nestlé sustains R&D intensity across clinical nutrition and everyday wellness beverage boundaries.
Fiber fortified beverages combine soluble or insoluble dietary fiber—typically inulin, psyllium husk, oat beta-glucan, or wheat dextrin at concentrations of 3–10 grams per serving—into ready-to-drink liquid matrices processed via high-shear homogenization and thermal stabilization to maintain suspension stability and mouthfeel. These products serve digestive health positioning, glycemic management claims, and satiety-focused weight control programs in consumer and medical nutrition contexts. Juice and smoothie formats occupy the deepest existing penetration as established taste profiles ease consumer transition, while inulin-sourced formulations represent the fastest-expanding ingredient category due to prebiotic labeling advantages and clean-label compatibility. Bottle packaging dominates shelf presence in conventional retail, though pouch formats gain traction in direct-to-athlete and subscription wellness channels where portability commands premium placement.
The FDA governs fiber content claims and serving-size declarations under Nutrition Facts modernization, while the USDA oversees school-channel eligibility where fortified beverages compete for placement. EFSA in Europe evaluates novel fiber health claims through centralized scientific assessment, creating divergent approval timelines that shape cross-border product rollouts. Stakeholders must monitor evolving regulator positions on isolated versus intact fiber sources and corresponding permitted health claim language.
Market Dynamics
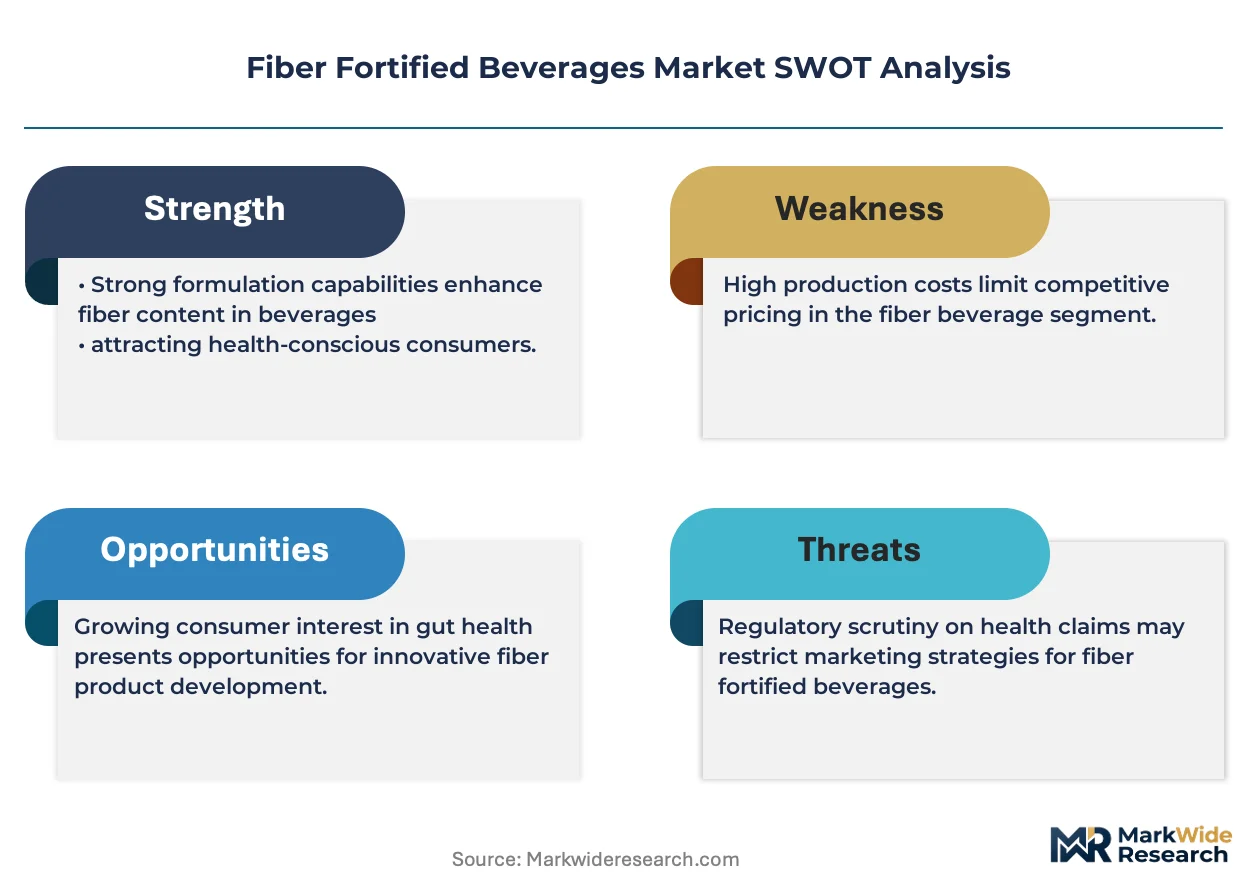
FDA's updated nutrition labeling rules for dietary fiber content are forcing beverage manufacturers to reformulate products and validate analytical methods for isolated fiber quantification, compressing time-to-market cycles and raising compliance costs across the functional beverage supply chain.
Growth Catalysts
- Prebiotic Health Claims:EFSA's evolving scientific assessment framework for gut microbiome benefits is opening regulatory pathways for inulin-sourced beverages in European retail channels.
- Aseptic Processing Investment:High-shear homogenization and thermal stabilization technologies are enabling extended shelf-life fiber suspensions without refrigeration infrastructure.
- Medical Nutrition Penetration:Hospital and clinical settings in the United States are expanding procurement of glycemic management beverages for diabetic patient protocols.
Market Restraints
- Chicory Root Supply Concentration:Inulin extraction depends heavily on Belgian and Dutch agricultural processing capacity, exposing formulations to weather-driven input volatility.
- FDA Claim Validation Burden:Isolated fiber sources require extensive analytical documentation to support dietary fiber declarations on Nutrition Facts panels, extending product development timelines.
- Texture Engineering Costs:Maintaining suspension stability and mouthfeel at fiber concentrations above 5 grams per serving demands specialized hydrocolloid systems that inflate unit economics.
Strategic Opportunities
- Direct-to-Athlete Subscription Channels:Pouch-format fiber beverages are capturing premium placement in performance nutrition subscriptions where portability commands price premiums over conventional retail.
- USDA School Channel Eligibility:Reformulated juice-based fiber beverages meeting reduced sugar thresholds are competing for placement in federal school meal programs.
- Clean-Label Convergence:Chicory root fiber paired with cold-pressed fruit matrices is absorbing demand from synthetic additive-dependent functional drinks in natural grocery channels.
Industry Challenges
- Sensory Panel Talent Scarcity:Beverage developers face acute shortages of food scientists trained in fiber-mouthfeel optimization and consumer hedonic testing for digestive health positioning.
- Legacy Equipment Retrofit Costs:Conventional bottling lines require substantial capital outlays for in-line fiber dispersion systems and enhanced clean-in-place protocols to prevent biofilm accumulation.
- Cross-Border Claim Harmonization:Divergent EFSA and FDA approval timelines for identical fiber health claims complicate unified product portfolio strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Fortified Beverages Market |
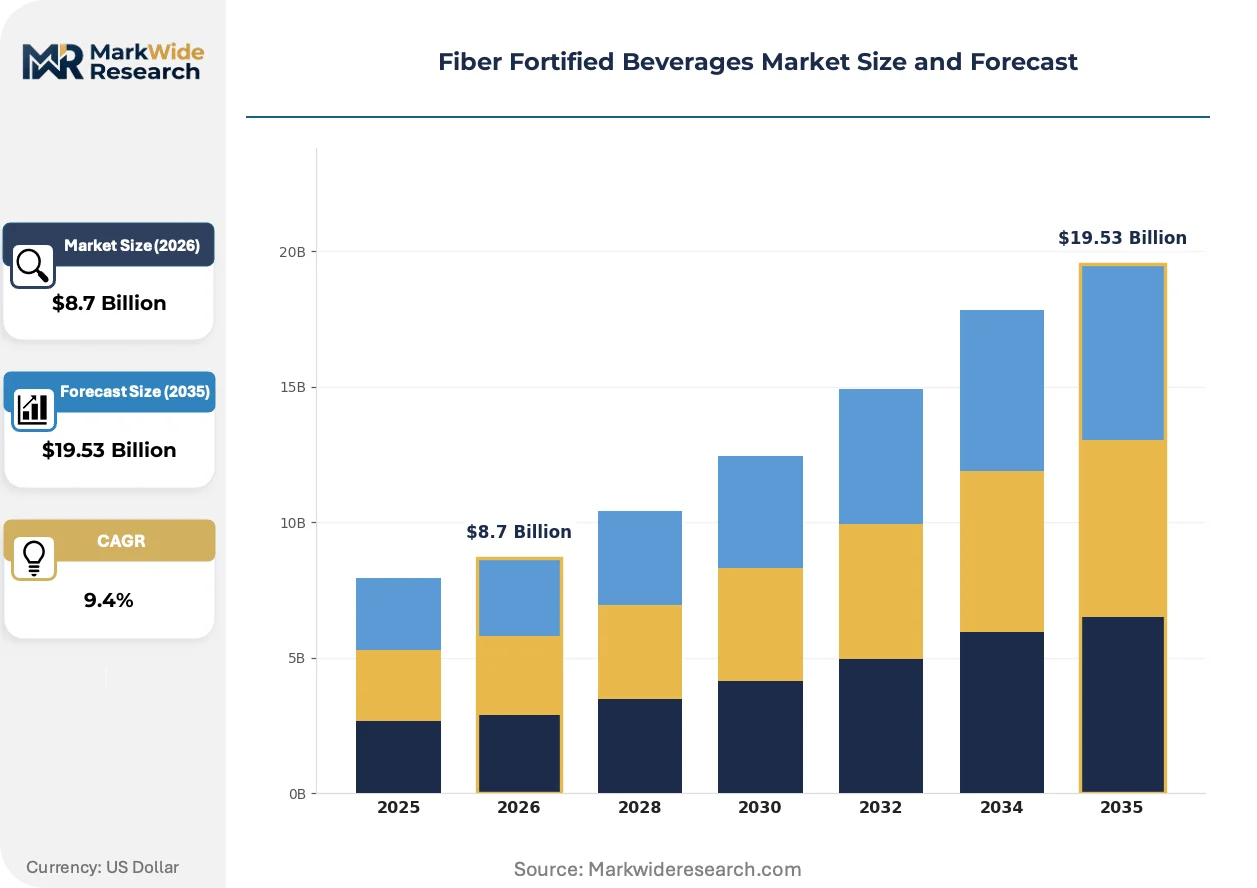
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juice, Shake, Smoothie, Tea Ingredient Source: Wheat, Oat, Psyllium, Inulin End User: Health-Conscious Consumers, Athletes, Weight Management Seekers, Seniors Packaging Type: Bottle, Carton, Pouch, Can |
| Companies Covered | The Coca-Cola Company, PepsiCo, Abbott Laboratories, Danone, Nestlé, Califia Farms, Sanitarium, Karma Water, Hello Water, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Fortified Beverages Market Evolving Landscape
Formulation science and channel economics are converging to redefine how fiber fortification delivers functional benefits, with processing technology and regulatory positioning now determining competitive advantage more than brand equity alone.
High-shear homogenization systems with integrated in-line viscosity monitoring are stabilizing fiber suspensions at higher loadings without phase separation. Beverage co-manufacturers serving natural and organic brands are adopting these platforms fastest to meet clean-label contract specifications. This equipment shift is absorbing margin from traditional stabilizer-dependent formulation approaches.
EFSA's centralized scientific assessment for novel fiber health claims is compressing approval timelines for prebiotic positioning in European markets. Manufacturers are front-loading clinical substantiation investments to secure Article 13.5 claims before competitors. Dairy-alternative platforms integrating chicory root fiber are most affected, reformulating to meet evolving substantiation thresholds.
Subscription wellness channels are displacing conventional retail as the primary growth vector for premium fiber beverage trials. Direct-to-consumer brands are unbundling after-sales education and personalized nutrition coaching from product shipments. This behavioral shift is most visible in United States metropolitan markets where convenience-driven consumption patterns dominate functional beverage adoption curves.
Fiber Fortified Beverages Market Segmentation
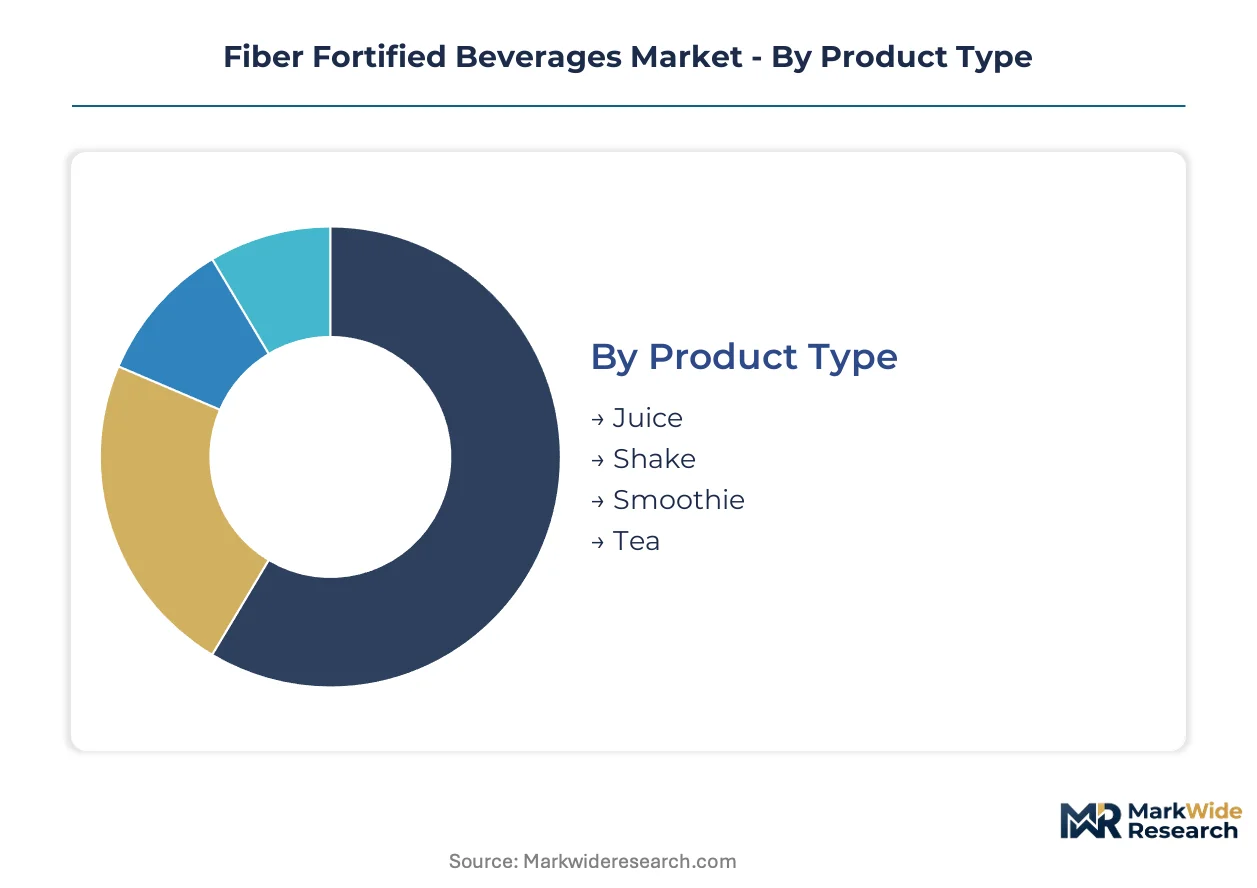
Fiber fortified beverage manufacturers face divergent capital requirements across product architectures, with formulation complexity and processing intensity varying substantially by segment. Understanding these structural cost differences enables targeted capacity planning and margin protection strategies.
Product Type:
Juice formats demand the lowest capital entry threshold, while aseptic smoothie lines require the most substantial upfront equipment investment for high-shear homogenization and extended shelf-life stabilization.
- Juice:Cold-pressed fruit matrices integrate soluble fiber at 3–5 gram loadings with minimal viscosity engineering. Demand concentrates in conventional grocery retail across the United States where taste familiarity reduces consumer education costs and accelerates trial conversion.
- Smoothie:High-fiber suspensions above 7 grams per serving require specialized hydrocolloid systems and thermal stabilization protocols. Athlete-focused subscription channels in metropolitan United States markets absorb premium pricing for these thicker, meal-replacement-positioned formats.
- Shake:Dairy-protein-fiber combinations serve medical nutrition protocols with glycemic management claims.
- Tea:Botanical extraction lines with in-line fiber dispersion accommodate lower throughput volumes.
Most installed capacity flows through Juice. Expansion is steepest in Smoothie.
Ingredient Source:
Supply security and extraction technology intensity create divergent investment profiles across fiber origins, with agricultural processing depth determining working capital requirements.
- Inulin:Chicory root extraction from Belgian and Dutch agricultural processors demands long-term supply contracts and quality validation infrastructure. European retail channels, particularly those seeking EFSA prebiotic claim approval, drive specification intensity for this fastest-expanding ingredient category.
- Psyllium:Husk processing requires specialized milling and contamination control systems given its medical-grade application history. Weight management seekers in United States clinical nutrition settings prioritize this source for its established laxative positioning and soluble fiber density.
- Wheat:Dextrin isolation leverages existing grain processing infrastructure with lower capital barriers.
- Oat:Beta-glucan extraction integrates with established oat milk supply chains.
Contracting activity concentrates on Inulin. Reformulation momentum favors Psyllium.
End User:
Customer acquisition economics vary dramatically across wellness motivation segments, with behavioral persistence and price sensitivity shaping lifetime value calculations.
- Health-Conscious Consumers:Broad demographic spanning preventive wellness motivations with moderate fiber dosage preferences at 3–5 grams per serving. Mainstream United States grocery and convenience retail channels capture this volume base through familiar juice and tea formats with clean-label positioning.
- Athletes:Performance nutrition demands concentrate in direct-to-consumer subscription models where portability-focused pouch formats command substantial price premiums over conventional retail packaging.
- Weight Management Seekers:Satiety-focused positioning drives higher fiber loadings and medical channel interest.
- Seniors:Digestive health and glycemic management claims resonate in clinical and assisted living procurement.
Health-Conscious Consumers anchor volume. Athletes deliver margin expansion.
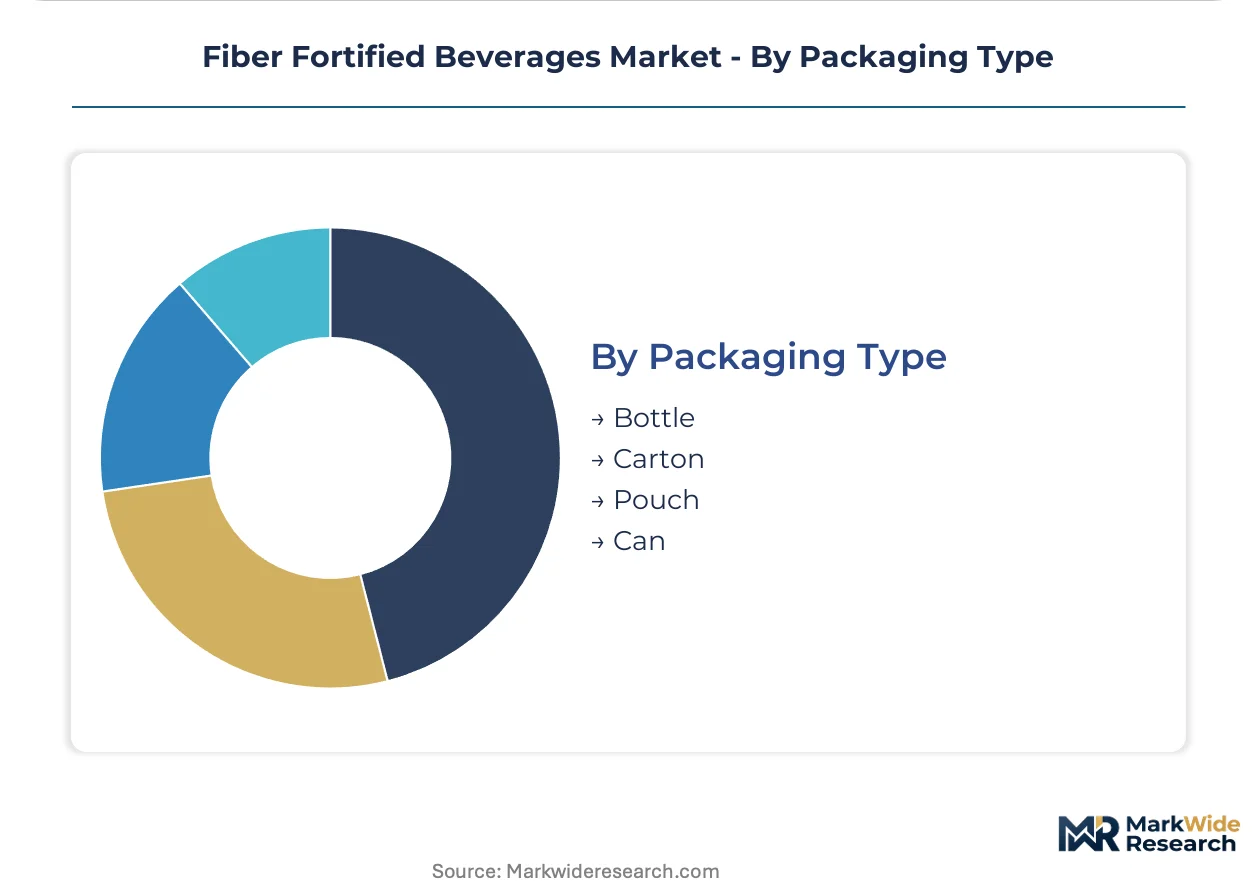
Packaging Type:
Line conversion costs and distribution infrastructure requirements create distinct capital allocation decisions across format choices.
- Bottle:PET and glass formats dominate conventional retail shelf presence with established filling line infrastructure. United States mainstream grocery channels favor this familiar format for fiber-fortified juices and ready-to-drink teas where visibility drives purchase decision.
- Pouch:Flexible format adoption accelerates in subscription wellness channels and direct-to-athlete distribution where portability and reduced shipping weight offset higher per-unit packaging costs.
- Carton:Aseptic carton lines serve ambient distribution for smoothie and shake formats.
- Can:Aluminum formats penetrate convenience retail for tea-based fiber beverages.
Bottle infrastructure represents the sunk cost base. Pouch capacity additions outpace all alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting fiber beverage production toward jurisdictions with streamlined novel food approvals and lower analytical validation burdens. Manufacturers are relocating pilot-scale operations to exploit these compliance-cost differentials while maintaining market access to premium retail channels.
United States
FDA's Nutrition Facts modernization drives reformulation urgency across functional beverage portfolios. The USDA school meal program creates procurement incentives for reduced-sugar fiber-fortified juices in federal feeding channels. California's Bay Area hosts the densest concentration of direct-to-consumer wellness brands deploying subscription-first distribution models.
Germany
EFSA's centralized health claim assessment accelerates prebiotic beverage approvals for chicory root fiber formulations. The country's beverage co-manufacturing sector specializes in aseptic processing lines for extended shelf-life smoothies. Bavaria's dairy-alternative innovation clusters integrate inulin sourcing with regional organic supply chains.
Belgium
Chicory root cultivation and inulin extraction infrastructure anchors European fiber ingredient supply security. National agricultural processing cooperatives enforce quality protocols that shape upstream specifications for beverage formulators. Flanders' port logistics facilitate bulk inulin distribution to contract manufacturers across the Low Countries.
Netherlands
Specialized hydrocolloid and fiber dispersion technology providers concentrate near Rotterdam's chemical processing corridor. Dutch food law harmonization with EU novel food regulations streamlines cross-border product registrations. Wageningen's agri-food research cluster supplies sensory science talent for mouthfeel optimization protocols.
Japan
METI's functional food labeling system enables specific health use claims for fiber beverages targeting metabolic syndrome management. Aging demographics sustain medical nutrition demand for glycemic control formulations in clinical and long-term care settings. Tokyo's metropolitan retail channels absorb premium-priced prebiotic beverages through convenience store networks.
Fiber Fortified Beverages Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and clean-label positioning. The market structure bifurcates between multinational beverage conglomerates with bottling network density and specialized wellness brands with formulation agility. Strategic archetypes include: diversified nutrition conglomerates leveraging clinical credibility, dairy-alternative specialists integrating chicory fiber, and athlete-focused direct brands optimizing pouch portability. Dominant competitive moves center on aseptic processing capacity expansion and EFSA prebiotic claim pre-submission investments.
Within the diversified nutrition tier, Abbott Laboratories and Nestlé exemplify clinical-channel anchoring through medical nutrition credibility. Danone occupies a position bridging everyday wellness and specialized dietary platforms. Among mainstream beverage conglomerates, PepsiCo represents distribution density advantages in North American retail. Califia Farms exemplifies the clean-label specialist archetype with dairy-alternative fiber integration. Karma Water and Hello Water sit within the functional water innovation segment targeting portability-premium positioning.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Abbott Laboratories |
| Danone |
| Nestlé |
| Califia Farms |
| Sanitarium |
| Karma Water |
| Hello Water |
| Others |
Value Network & Pricing Analysis
EFSA's prebiotic claim substantiation requirements gate qualified inulin supply and premium-tier pricing access for European market entry. Chicory root fiber certifications from Belgian and Dutch agricultural cooperatives command contract premiums that filter through to finished beverage shelf prices in retail channels.
Pricing Analysis
Retailer markup layers in conventional grocery channels absorb margin compression from aseptic processing investments while subscription direct-to-consumer models bypass intermediaries. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber loading and packaging format, with athlete-focused pouch products commanding the widest spreads. Pricing pressure stems from chicory root input volatility as weather-driven harvest variability transmits through long-term supply contracts. Health-conscious mainstream consumers exhibit highest price sensitivity, while medical nutrition procurement shows lowest elasticity due to protocol-driven purchasing.
Supply Chain Analysis
Food scientist talent shortages in Flanders and Wageningen constrain formulation capacity expansion for mouthfeel optimization protocols. Chicory root extraction centers on Belgium and the Netherlands, with psyllium husk milling concentrated in India and oat beta-glucan processing anchored in Nordic countries. Raw material dependencies include Belgian inulin, Indian psyllium, and North American wheat dextrin. Single-source vulnerability in chicory root supply exposes formulations to weather-driven disruption. Distribution runs through beverage co-manufacturer networks serving retail and subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as athlete and medical nutrition demand shifts toward premium specifications with validated prebiotic claims and extended shelf-life stability.
For Market Incumbents: Acquire aseptic processing capacity in North American bottling corridors to defend against direct-to-consumer subscription entrants. Secure long-term chicory root supply contracts with Belgian agricultural cooperatives before competitor lock-up. Prioritize EFSA prebiotic claim pre-submissions to accelerate European market access ahead of formulation followers. For New Entrants and Emerging Players: Enter via USDA school channel eligibility for reduced-sugar juice formats where incumbent presence remains thin. Target metropolitan United States subscription wellness channels with portability-optimized pouch products. Leverage clean-label positioning with cold-pressed fruit matrices to differentiate from synthetic-stabilizer-dependent competitors. For Investors and Strategic Acquirers: Roll-up economics work for specialized beverage co-manufacturers with aseptic line capacity because FDA compliance burdens favor scaled analytical validation infrastructure. Five-to-ten year viability hinges on clinical nutrition credentialing and EFSA claim portfolio depth. Watch for inflection in Belgian chicory root harvest yields as supply security signal.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Capacity Expansion | High-shear homogenization lines enable extended shelf-life fiber suspensions without refrigeration infrastructure. |
| EFSA Prebiotic Claim Investment | Article 13.5 substantiation accelerates European retail placement for chicory root fiber formulations. |
| Direct-to-Consumer Subscription Launch | Pouch-format portability commands price premiums in athlete-focused wellness channels. |
| Backward Integration into Fiber Sourcing | Long-term chicory root contracts with Belgian cooperatives reduce input volatility exposure. |
| USDA School Channel Certification | Federal meal program eligibility opens institutional procurement volume for reduced-sugar juice formats. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with beverage formulation scientists, retail category buyers, contract manufacturing executives, and clinical nutrition procurement managers combined with secondary validation from FDA filing databases, EFSA health claim registers, USDA school meal program specifications, and customs trade records. Triangulation across these sources ensures convergence between production capacity assessments and channel demand signals.
Historical trendline analysis of fiber fortification adoption curves informed projection frameworks across product type, ingredient source, end-user motivation, and packaging format dimensions. CAGRs derive from segment-level volume build-ups calibrated against macroeconomic consumption indicators and regulatory approval timelines. Forecast inputs include EFSA claim approval velocity, aseptic line capacity additions, and chicory root harvest yield variability.
The model holds under stable regulatory claim pathways and intact agricultural processing capacity; deviation in FDA fiber quantification rules or Belgian climate patterns would shift trajectory. Forecasts reflect documented assumptions about consumer willingness-to-pay for prebiotic positioning and medical nutrition protocol adoption. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Kombucha Market
Beverages
Bangladesh Energy Drinks Market
Beverages
Gluten Free Beverages Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Fermented Drinks Market
Beverages
Indonesia Bottled Water Market
Beverages
Asia-Pacific Juices Market
Beverages
Packaged Coconut Water Market
Beverages
Ready to Drink Premixes Market
Beverages
India Soy Beverages Market
Beverages
Fermented Foods and Beverages Market
Beverages
Smoothies Market
Beverages
Nitro-Infused Cola Market
Beverages
Europe Yerba Mate Market
Beverages
Sparkling Soda Market
Beverages
Asia Pacific Dairy Based Beverages Market